
 Preoperative Skin Preparation Market | 2026-2036
Preoperative Skin Preparation Market Size, Share, and Industry Trends Forecast 2026-2036
Preoperative Skin Preparation Market Analytics
Hospital procurement consolidation is decoupling purchasing power from individual surgical departments, forcing suppliers to negotiate with centralized health system contracting offices. Medline Industries leverages its private-label scale to compete on contract breadth across integrated delivery networks. 3M sustains technology leadership in persistent antimicrobial film-forming formulations. Johnson & Johnson anchors brand recognition through its heritage surgical preparation portfolio, though its channel control has narrowed as group purchasing organizations expand their influence.
Preoperative skin preparation encompasses antiseptic formulations and mechanical applicators designed to reduce microbial load on intact skin prior to invasive procedures, typically incorporating chlorhexidine gluconate, povidone-iodine, or alcohol-based chemistries with specified minimum contact times and log-reduction performance thresholds. Its primary commercial purpose centers on preventing surgical site infections, which carry substantial morbidity costs and reimbursement penalties for providers. Antiseptic solutions dominate current volume due to their established efficacy profiles and compatibility with diverse procedural protocols, while antimicrobial wipes represent the fastest-growing delivery format as ambulatory settings prioritize convenience and reduced cross-contamination risk. Skin prep gels concentrate margin pools in premium positioning where film-forming persistence commands price premiums over standard aqueous preparations.
FDA antiseptic drug monograph proceedings, EPA disinfectant registration requirements, and Joint Commission infection control standards collectively govern product formulation, labeling claims, and facility compliance obligations in the United States market. These frameworks elevate barriers for novel active ingredients while accelerating substitution toward compliant preoperative alternatives as older formulations face regulatory scrutiny. Stakeholders must monitor pending monograph finalizations and antimicrobial resistance surveillance data to align R&D portfolios with evolving clinical evidence requirements and payer reimbursement criteria.
Market Dynamics
FDA antiseptic drug monograph revisions are compressing formulation timelines and forcing manufacturers to revalidate active ingredient dossiers, fundamentally altering how suppliers allocate R&D capital and navigate compliance pathways.
Growth Catalysts
- Outpatient procedural migration:Ambulatory surgery centers in the United States are expanding antiseptic wipe procurement as same-day discharge protocols accelerate. This end-use segment commands differentiated packaging and contact-time specifications.
- Chlorhexidine gluconate persistence:Film-forming antiseptic technologies are displacing standard aqueous preparations in orthopedic and cardiac procedures where microbial suppression duration correlates with infection outcomes.
- Value-based care contracting:Medicare bundled payment models for surgical site infections are compelling hospitals to upgrade skin prep specifications regardless of incremental product cost.
Market Restraints
- Isopropyl alcohol supply concentration:Domestic production of pharmaceutical-grade alcohol concentrates in Texas and Louisiana chemical corridors, exposing formulators to hurricane-related disruption risk.
- Chlorhexidine resistance surveillance:CDC tracking of reduced susceptibility patterns in staphylococcal isolates threatens long-term efficacy claims for CHG-dominant portfolios.
- EPA-FDA jurisdictional overlap:Antiseptic wipes with residual claims face dual registration requirements that extend commercialization timelines by 18-24 months.
Strategic Opportunities
- Home-based preoperative preparation:Pre-surgical skin prep kits for patient self-application prior to ambulatory admission remain underdeveloped in United States outpatient markets.
- Electrolyte-stabilized formulations:Convergence of antiseptic chemistry with pH-buffering systems enables compatibility with chlorhexidine-sensitive patient populations.
- Direct-to-facility e-procurement:Specialized distributors are bypassing traditional group purchasing organization channels to serve independent ambulatory surgery centers.
Industry Challenges
- Formulation chemist scarcity:Antiseptic drug monograph expertise resides with a narrow cohort of regulatory affairs specialists, constraining product line expansion timelines.
- Legacy inventory reconciliation:Health systems must manage SKU transitions as FDA finalizes alcohol-based rub monograph specifications, complicating supply chain continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preoperative Skin Preparation Market |
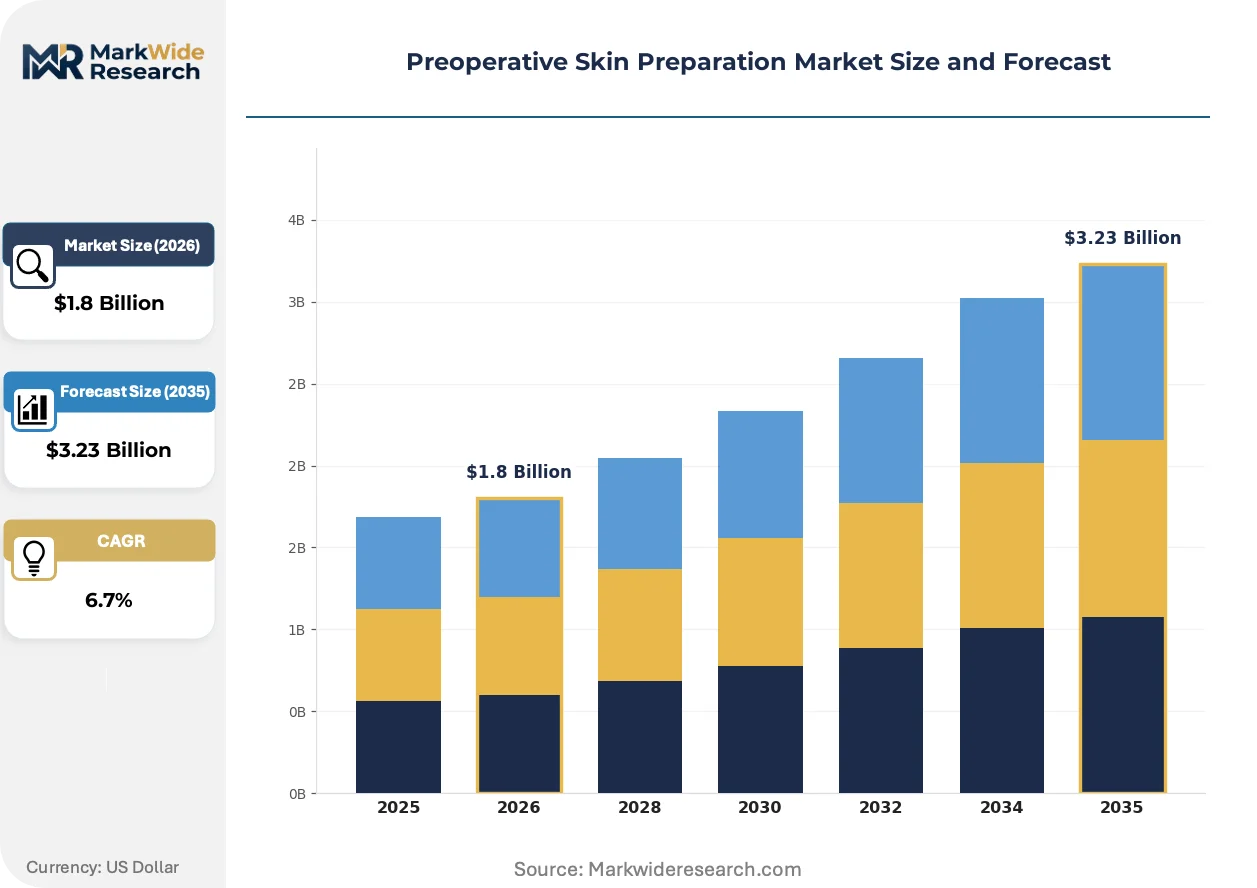
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiseptic Solutions, Antimicrobial Wipes, Scrub Brushes, Skin Prep Gels Application: Surgical Procedures, Diagnostic Imaging, Infection Control, Skin Grafting End User: Hospitals, Ambulatory Surgery Centers, Clinics, Research Labs Delivery Mode: Topical Application, Spray, Wipe, Lotion |
| Companies Covered | Johnson & Johnson, Medline Industries, 3M, Aplicare, Molnlycke Health, BD, Biomerieux SA, Clorox Healthcare, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preoperative Skin Preparation Market Evolving Landscape
Antimicrobial film persistence and applicator ergonomics are converging to redefine performance benchmarks, while regulatory clarity gaps around residual claims are forcing premature portfolio bets.
Film-forming polymer matrices incorporating chlorhexidine gluconate are absorbing market preference in prolonged-duration surgical procedures. Orthopedic and neurosurgical departments at academic medical centers are adopting these formulations at accelerated rates. This absorption is compressing margins on standard aqueous preparations and rewarding suppliers with polymer chemistry capabilities.
EPA's emerging guidance on antiseptic product residual efficacy claims is tightening data requirements for wipe formulations. Manufacturers must now submit expanded clinical endpoint studies to support 24-hour and 48-hour microbial suppression labeling. Ambulatory surgery center suppliers are responding by reformulating alcohol-based products toward immediate-kill positioning rather than persistence claims.
Centralized health system contracting offices are consolidating antiseptic procurement decisions away from individual surgical service lines. Integrated delivery networks in the United States are unbundling skin prep from broader infection control bundles to negotiate category-specific rebates. This concentration is most visible in multi-hospital systems across the Midwest and Southeast, where standardization mandates override surgeon-specific product preferences.
Preoperative Skin Preparation Market Segmentation
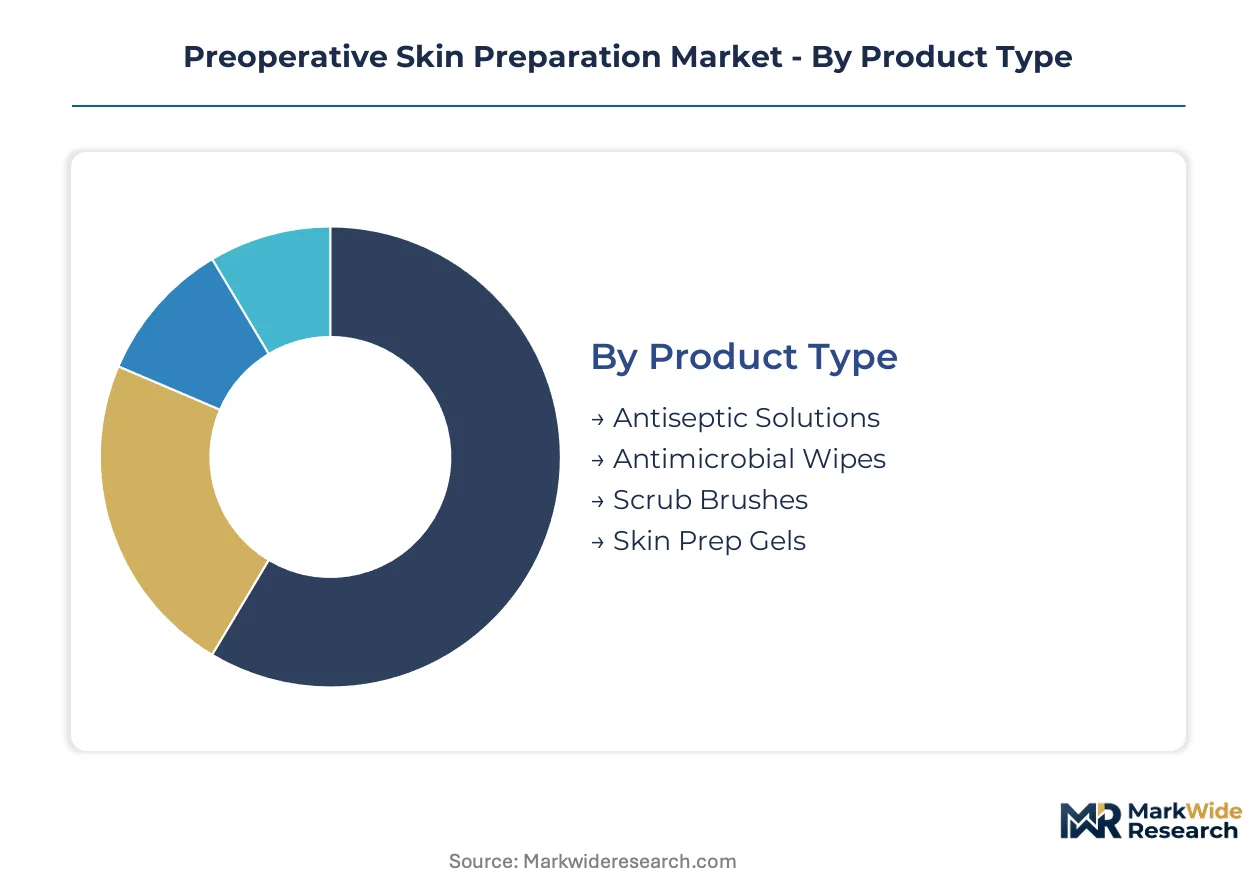
Preoperative skin preparation markets fragment across four distinct dimensions that shape capital allocation, regulatory pathways, and channel strategy. Product chemistry determines manufacturing infrastructure requirements. Application setting dictates contact-time specifications and reimbursement logic. End-user concentration drives contract negotiation leverage. Delivery mode influences packaging automation and sterilization validation costs.
Product Type:
Capital intensity peaks with antiseptic solutions requiring pharmaceutical-grade water systems and aseptic filling lines, while antimicrobial wipes demand nonwoven substrate integration and alcohol-handling infrastructure.
- Antiseptic Solutions:Aqueous and alcohol-based formulations incorporating chlorhexidine gluconate or povidone-iodine dominate hospital procurement volumes. Academic medical centers in the United States specify these for orthopedic and cardiac procedures where extended microbial suppression correlates with surgical site infection outcomes.
- Antimicrobial Wipes:Impregnated nonwoven substrates deliver pre-saturated convenience for ambulatory settings. Ambulatory surgery centers across the United States Southeast and Midwest prioritize these for same-day discharge protocols that compress preoperative preparation windows.
- Scrub Brushes:Mechanical applicators with integrated antiseptic reservoirs serve specific procedural protocols requiring friction-based debridement.
- Skin Prep Gels:Viscous film-forming preparations concentrate margin pools where persistence claims command price premiums over standard aqueous alternatives.
Most installed capacity flows through antiseptic solutions. Expansion is steepest in antimicrobial wipes.
Application:
Volume concentration aligns with procedural reimbursement intensity and infection penalty exposure, with surgical procedures absorbing the majority of premium formulation procurement.
- Surgical Procedures:Invasive interventions requiring intact skin antisepsis prior to incision, spanning general surgery through subspecialty orthopedics and neurosurgery. Medicare bundled payment models for surgical site infections compel United States hospitals to upgrade skin prep specifications regardless of incremental product cost.
- Infection Control:Broader institutional protocols extending beyond the operating room to catheter insertion sites and wound care. CDC surveillance requirements and Joint Commission standards drive compliance-oriented procurement in United States health systems.
- Diagnostic Imaging:Pre-procedural preparation for interventional radiology and biopsy procedures requiring percutaneous access.
- Skin Grafting:Donor site preparation protocols in burn centers and reconstructive surgery units.
Surgical procedures anchor procurement volumes. Infection control applications are climbing the fastest as surveillance standards tighten.
End User:
Customer scale and contracting sophistication determine pricing architecture, with hospital systems leveraging group purchasing organization consolidation against independent ambulatory facilities.
- Hospitals:Acute care institutions with centralized infection control committees and value-based care exposure. Integrated delivery networks in the United States unbundle skin prep from broader infection control bundles to negotiate category-specific rebates.
- Ambulatory Surgery Centers:Outpatient facilities with streamlined procurement and same-day discharge protocols. Independent centers across the United States bypass traditional group purchasing organization channels through specialized e-procurement distributors.
- Clinics:Office-based procedural settings with lower volume and less formalized antiseptic protocols.
- Research Labs:Preclinical and clinical trial sites with specialized documentation requirements.
Hospitals retain the dominant procurement position. Ambulatory surgery centers are gaining share fastest as procedural migration accelerates.
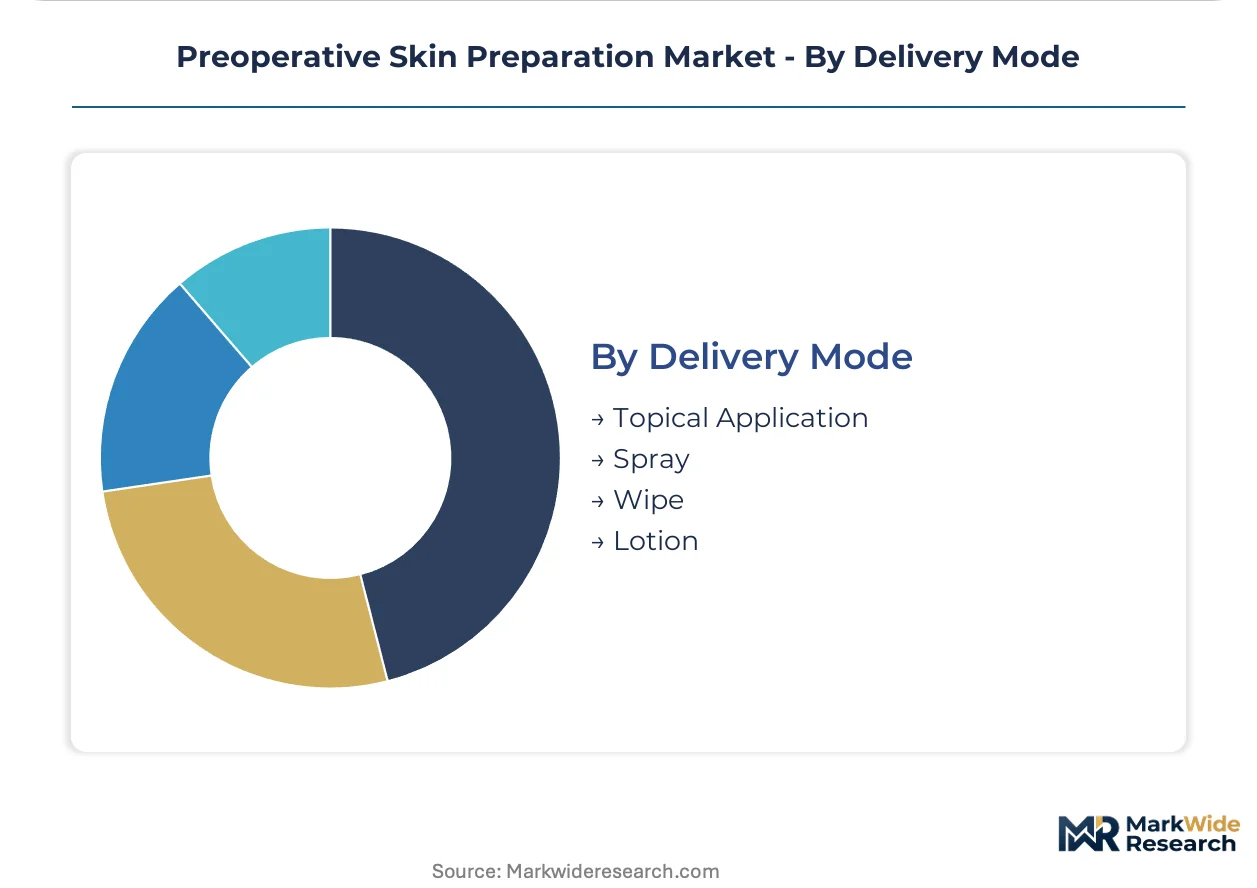
Delivery Mode:
Packaging and applicator engineering requirements vary sharply across modes, with spray systems demanding propellant handling infrastructure and wipe production integrating substrate conversion lines.
- Topical Application:Direct pour or swab-based delivery of liquid formulations, requiring precise volume control and contact time measurement.
- Spray:Aerosol or pump-dispensed fine mist application enabling rapid large-area coverage. Operating rooms in United States academic medical centers specify these for efficiency in high-volume surgical schedules.
- Wipe:Pre-saturated substrate delivery combining antiseptic application with mechanical action. FDA antiseptic drug monograph revisions and EPA residual claim requirements are compressing formulation timelines for manufacturers targeting this segment.
- Lotion:Viscous preparations with extended skin contact characteristics.
Topical application retains the largest installed base. Wipe delivery is expanding most quickly as ambulatory convenience priorities reshape procurement preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
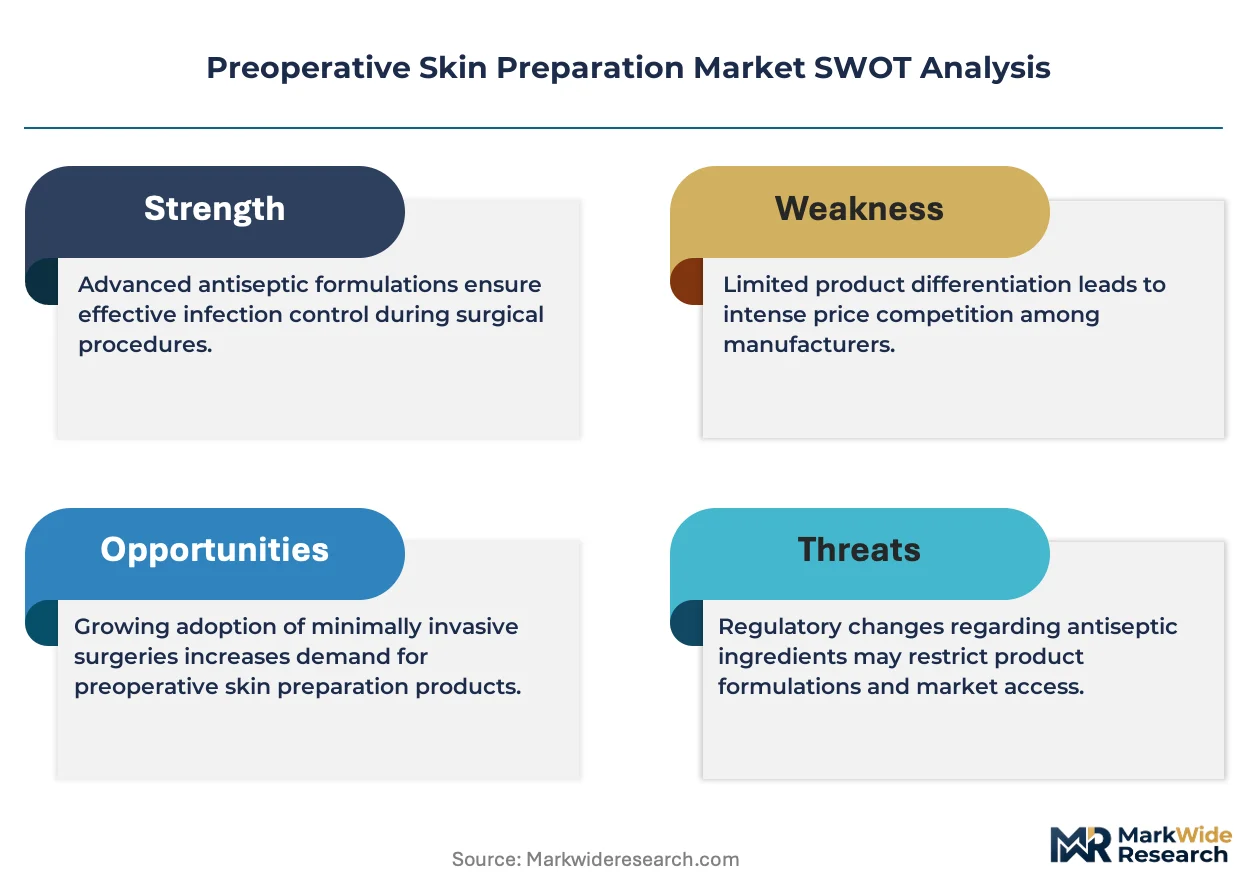
The United States commands premium formulation procurement through value-based care incentives, while Germany anchors European demand via MDR compliance rigor and surgical volume concentration.
United States
Hospital-acquired infection prevention protocols and Medicare bundled payment models drive specification upgrades for chlorhexidine gluconate formulations. FDA antiseptic drug monograph revisions compress manufacturer compliance timelines. The Texas-Louisiana chemical corridor concentrates pharmaceutical-grade isopropyl alcohol production, exposing formulators to hurricane-related supply disruption.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia specify film-forming antiseptic technologies for orthopedic and cardiac procedures. EU MDR and REACH frameworks elevate documentation burdens for active ingredient dossiers. The Rhine-Ruhr industrial basin hosts specialized chemical formulation infrastructure serving Central European hospital networks.
China
NMPA registration pathways for imported antiseptic formulations extend commercialization timelines for multinational suppliers. Domestic manufacturers in the Yangtze River Delta scale chlorhexidine production to serve hospital procurement consolidation. Shanghai and Suzhou medical device clusters integrate skin prep manufacturing with broader infection control product portfolios.
Japan
PMDA quality standards for preoperative antiseptics emphasize validated log-reduction performance thresholds. Metropolitan Tokyo and Osaka surgical centers adopt persistent antimicrobial film technologies for prolonged procedures. METI industrial policy supports domestic formulation chemistry capabilities against import dependency.
India
CDSCO regulatory harmonization with ICH guidelines accelerates approval pathways for novel antiseptic actives. Hospital procurement in Maharashtra and Karnataka shifts toward pre-saturated wipe formats as ambulatory surgical volumes expand. The Ahmedabad-Vadodara pharmaceutical corridor supplies active pharmaceutical ingredients to regional formulators.
Preoperative Skin Preparation Market Competitive Landscape
United States producers anchor one tier; European specialists hold formulation chemistry advantages through polymer matrix capabilities. The vendor base concentrates around diversified medical supply conglomerates and focused infection control specialists. Three strategic archetypes dominate: integrated delivery network contract aggregators, film-forming technology specialists, and private-label scale operators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as manufacturers navigate FDA monograph uncertainty.
Among United States-based suppliers, Johnson & Johnson and 3M exemplify heritage brand positioning anchored in surgical preparation portfolios, while Medline Industries occupies a position as a private-label scale competitor across integrated delivery networks. These three entities represent distinct strategic postures within a market where group purchasing organization consolidation narrows channel control for incumbent manufacturers.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medline Industries |
| 3M |
| Aplicare |
| Molnlycke Health |
| BD |
| Biomerieux SA |
| Clorox Healthcare |
| Cardinal Health |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade isopropyl alcohol costs cascade from Texas-Louisiana chemical corridor production through three distinct pricing tiers, with hurricane disruption risk embedding volatility premiums into contract structures for formulators serving ambulatory surgery centers.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for chlorhexidine gluconate active pharmaceutical ingredients, compressing margins on standard aqueous preparations while film-forming polymer formulations sustain premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates film-forming persistence claims from basic aqueous solutions and commodity alcohol-based rubs. Cost compression in the standard tier is intensifying because group purchasing organization consolidation concentrates buyer leverage. Independent ambulatory surgery centers exhibit highest price sensitivity, whereas academic medical centers prioritize performance specifications over unit cost.
Supply Chain Analysis
Chlorhexidine gluconate supply rests on Chinese and Indian active pharmaceutical ingredient manufacturers, with formulation chemistry capabilities concentrated among United States and European specialty chemical producers. Key inputs encompass pharmaceutical-grade alcohols, nonwoven substrates for wipe production, and film-forming polymer matrices. Single-source vulnerability runs through the Texas-Louisiana isopropyl alcohol corridor, where hurricane exposure threatens continuity. Distribution runs through group purchasing organization channels for hospital systems and specialized e-procurement platforms serving independent ambulatory facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procedural migration toward ambulatory settings concentrates procurement around premium wipe formats with validated contact-time performance.
For Market Incumbents: To counter FDA antiseptic drug monograph uncertainty, accelerate polymer chemistry R&D investments and secure backward integration into film-forming formulation capabilities. Channel control through direct-to-facility e-procurement partnerships with independent ambulatory surgery centers offsets group purchasing organization margin compression. For New Entrants and Emerging Players: Launch via specialized e-procurement distributors targeting independent ambulatory surgery centers in the United States Southeast and Midwest, where group purchasing organization penetration remains incomplete. Home-based preoperative preparation kits for patient self-application prior to admission represent the most penetrable white space, with reimbursement strategy development as the critical go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA compliance expertise resides with narrow regulatory affairs specialist cohorts. Long-term viability favors acquirees with validated polymer matrix capabilities and established hospital system relationships over commodity aqueous formulation players. Watch chlorhexidine resistance surveillance data from CDC as the inflection indicator for portfolio rebalancing toward alternative active chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Antiseptic Drug Monograph Compliance Investment | Accelerates dossier revalidation timelines and elevates barriers for non-compliant legacy formulations. |
| Film-Forming Polymer Chemistry Acquisition | Captures margin pools in orthopedic and cardiac procedural segments where persistence claims command premiums. |
| Ambulatory Surgery Center E-Procurement Partnership | Bypasses group purchasing organization channel control to access fastest-growing end-user segment. |
| Electrolyte-Stabilized Formulation Development | Expands addressable market into chlorhexidine-sensitive patient populations with pH-buffered alternatives. |
| Home-Based Preoperative Kit Launch | Addresses underdeveloped patient self-application segment prior to ambulatory admission. |
Research Methodology
Bottom-up ambulatory surgery center and hospital procurement modeling reconciled against top-down active pharmaceutical ingredient production tracking forms the analytical core of this study. Primary interviews with infection control committee directors, group purchasing organization contract managers, biomedical engineers, and regulatory affairs specialists at formulation manufacturers were cross-validated against secondary sources including FDA antiseptic drug monograph proceedings, EPA disinfectant registration databases, hospital procurement records, and CMS Medicare bundled payment program documentation.
Historical trendline analysis of procedural volume migration, formulation chemistry adoption curves, and contract pricing trajectories informed the projection framework across the analysis window. Segmentation dimensions encompass product chemistry, application setting, end-user concentration, and delivery mode, with CAGRs derived from regression analysis of volume and value outputs. Industry-specific forecast inputs incorporate FDA monograph finalization timelines and CDC antimicrobial resistance surveillance patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated chlorhexidine resistance emergence or hurricane-related isopropyl alcohol supply disruption. A small set of named triggers warrants ongoing watch: FDA monograph finalization language, CDC resistance surveillance updates, and Gulf Coast weather event frequency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Skin Care Emulsion Market
Skincare
Medicine Skin Care Market
Skincare
Cosmeceutical Ingredients Market
Skincare
Global Scar Removal Treatment Market
Skincare
Peel Off Face Mask Market
Skincare
Mineral Sunscreen Market
Skincare
Anti-Aging Services Market
Skincare
Global Eczema Skin-Care Products Market
Skincare
Anti-Acne Dermal Patch Market
Skincare
Fragrance-Free Skin Care Products Market
Skincare
Africa Cosmeceutical Market
Skincare
Personalized Skin Care Products Market
Skincare
Ultrasound Skin Cleaners Market
Skincare
Hyaluronic Acid Personal Care Products Market
Skincare
Encapsulated Retinol Market
Skincare
Bangladesh Skin Care Products Market