
 Self Balancing Scooter Market | 2026-2036
Self Balancing Scooter Market Size, Share, and Industry Trends Forecast 2026-2036
Self Balancing Scooter Market Outlook
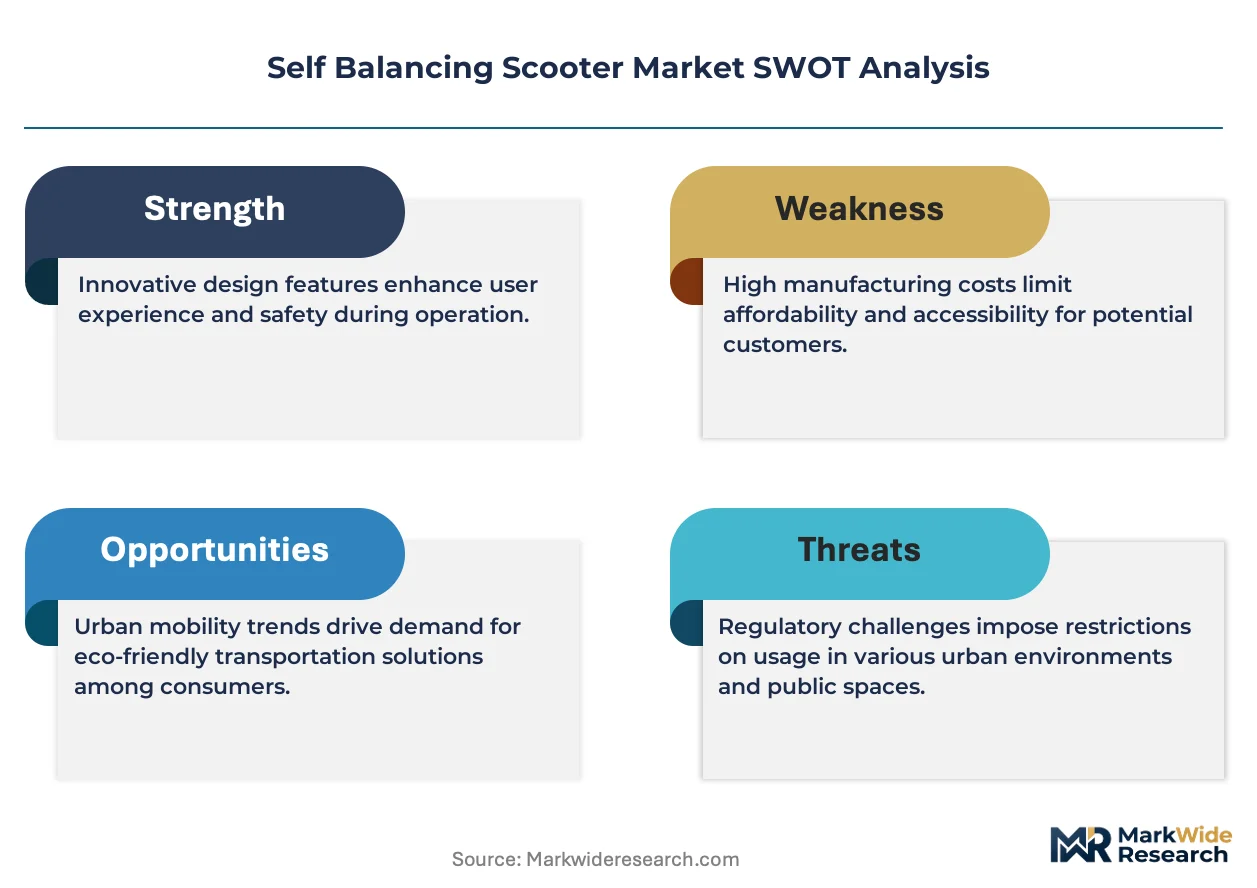
The gap between premium lithium-polymer models and entry-level lead-acid units is expanding across retail and commercial channels. Segway leverages its patent portfolio to anchor premium positioning in North American corporate fleets. Ninebot sustains manufacturing scale through backward integration into battery pack assembly. INMOTION specializes in all-terrain configurations for outdoor recreation buyers in European markets.
A self balancing scooter is a battery-powered personal transporter utilizing gyroscopic sensors and accelerometers to maintain equilibrium, typically operating at speeds up to 20 km/h with 10- to 21-inch wheel diameters depending on terrain rating. The device serves urban commuters, warehouse operators, and recreational users seeking motorized mobility without handlebar steering mechanisms. Two-wheel configurations dominate volume sales due to lower production complexity and broader consumer familiarity, while off-road variants command higher margins through reinforced frames and dual-motor layouts. App-controlled systems are displacing manual interfaces as fleet operators demand telemetry integration for asset tracking and geofencing compliance.
The US Consumer Product Safety Commission enforces electrical system standards that block uncertified imports at ports, while China's SAMR mandates GB-compliant battery management systems for domestic production and export clearance. The EU's CE marking framework requires electromagnetic compatibility testing that adds six to twelve weeks to product registration timelines. Stakeholders must monitor evolving micromobility ordinances in municipal jurisdictions that increasingly restrict sidewalk operation and mandate helmet compliance for rental deployments.
Market Dynamics
App-controlled telemetry systems are absorbing fleet procurement decisions as urban delivery operators mandate real-time asset tracking and geofencing compliance for rider accountability.
Growth Catalysts
- Micromobility infrastructure investment:Municipal dockless parking networks in Germany, South Korea, and the United States expand legal operating zones for rental and private units.
- CE marking alignment:EU electromagnetic compatibility directives compress certification timelines for compliant manufacturers, accelerating market entry against uncertified competitors.
- Lithium-ion energy density improvements:Cell chemistry advances extend single-charge range for warehouse operators running multi-shift fulfillment operations.
Market Restraints
- Cobalt and lithium price volatility:Raw material input swings compress margin stability for battery pack assemblers lacking long-term offtake agreements.
- Single-source sensor dependency:Gyroscopic MEMS production concentrates among Taiwanese and South Korean foundries, creating supply vulnerability.
- Sidewalk operation bans:Municipal ordinances in dense US and European urban cores restrict consumer recreational usage to bike lanes and mixed-traffic roads.
Strategic Opportunities
- Indian urban logistics:Last-mile delivery penetration remains underdeveloped relative to fleet density in East Asian markets, offering first-mover positioning.
- Battery-swapping station networks:Infrastructure operators in Chinese and Southeast Asian cities pilot subscription models decoupling vehicle from energy ownership.
- ISO 12100 machinery safety convergence:Harmonized international standards reduce multi-market certification burden for all-terrain and industrial variants.
Industry Challenges
- Firmware cybersecurity validation:Over-the-air update protocols require penetration testing cycles that extend product launch timelines.
- Cross-border customs classification:HS code ambiguity between personal mobility devices and motorized vehicles triggers port delays and duty disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self Balancing Scooter Market |
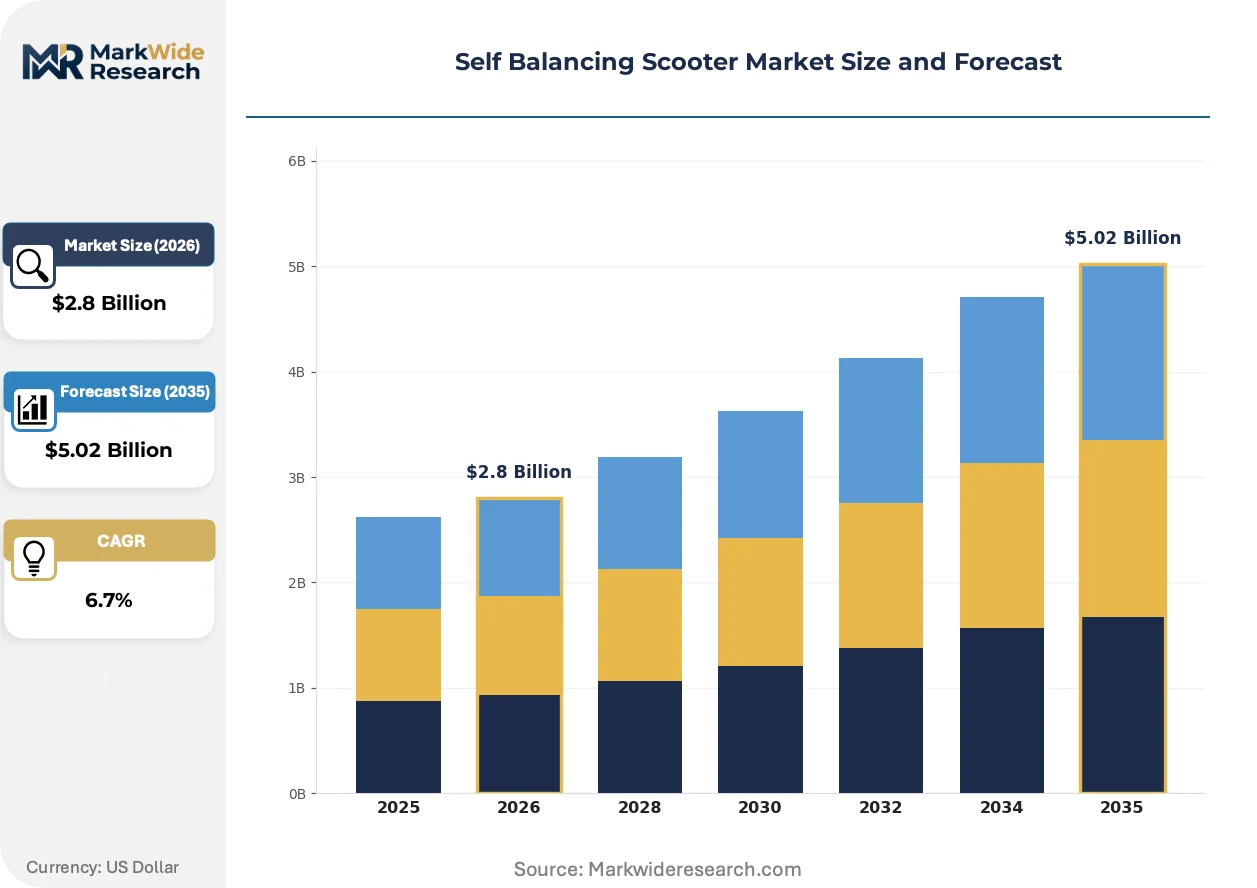
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Wheel, All-Terrain, Off-Road, Mini Weight Capacity: 100 kg, 120 kg, 150 kg, 200 kg Battery Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Lithium Polymer Control Type: App-Controlled, Remote-Controlled, Manual, Gesture-Controlled |
| Companies Covered | Airwheel, IPS, Ninebot, CHIC, Robstep, Segway, Inventist, ESWING, INMOTION, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self Balancing Scooter Market Strategic Shifts
Solid-state battery prototyping and AI-assisted balance algorithms are compressing competitive differentiation windows, forcing incumbents to accelerate R&D cadence or cede positioning to specialized entrants.
Solid-state electrolyte architectures are absorbing venture funding and pilot production capacity as manufacturers seek thermal runaway elimination. Warehouse fleet operators with indoor charging constraints are piloting early units despite premium pricing. The technology is absorbing liability risk premiums currently embedded in lithium-ion insurance and facility compliance costs.
The EU's Machinery Regulation (replacing the Machinery Directive) mandates functional safety documentation for autonomous balancing systems, effective 2027. Manufacturers must demonstrate failure-mode analysis for sensor redundancy and emergency shutdown protocols. Industrial-grade suppliers in Germany and the Netherlands are pre-certifying products eighteen months ahead of enforcement to secure fleet procurement contracts.
Rental operators are unbundling maintenance from vehicle procurement, contracting third-party service networks for battery health monitoring and field repair. This model displaces in-house technician staffing for urban micromobility platforms. The shift is most visible in US and French markets where asset-light balance sheet strategies dominate venture-backed deployment strategies.
Self Balancing Scooter Market Segmentation
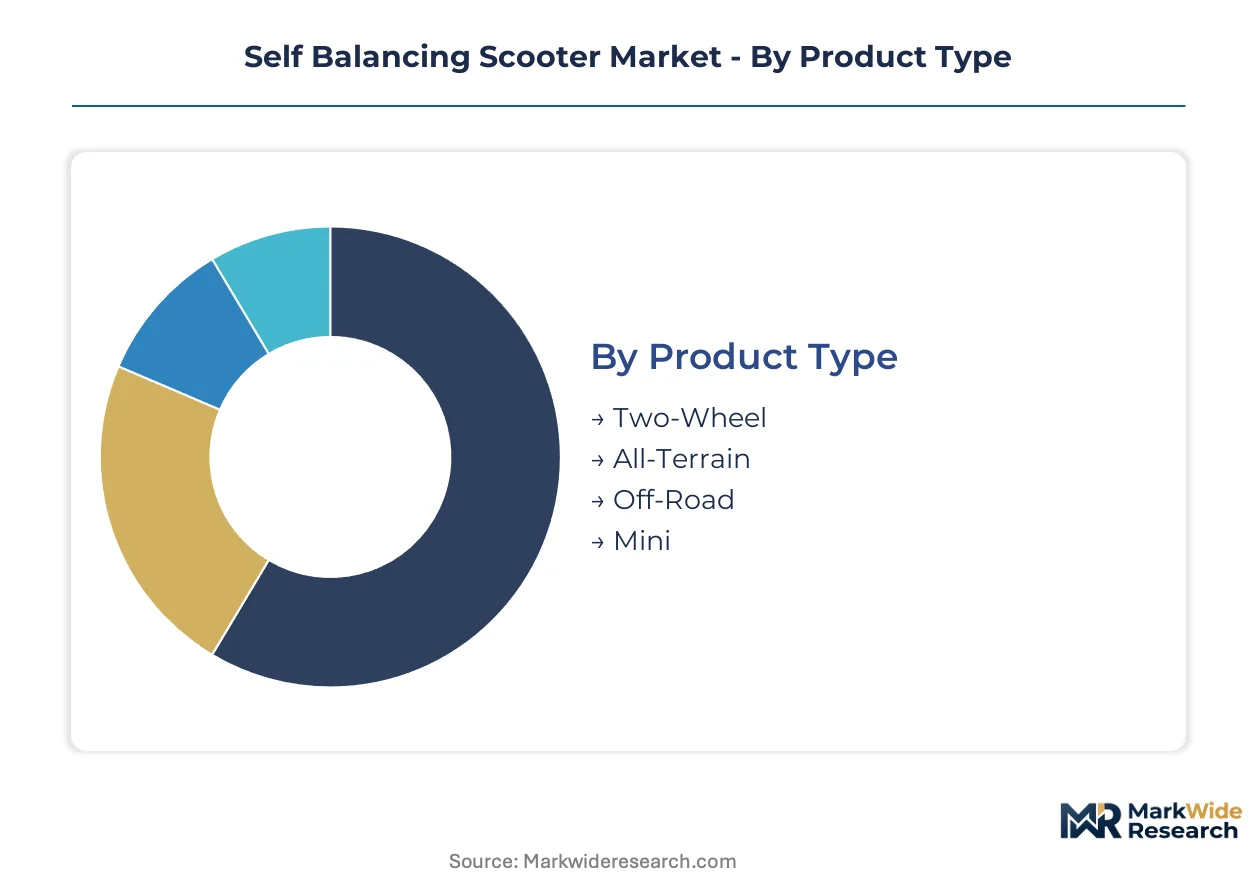
Self balancing scooter procurement splits sharply between mass-market commuter units and specialized configurations for commercial logistics and outdoor recreation. Battery chemistry and control interface choices increasingly determine fleet eligibility for corporate buyers and rental operators.
Product Type:
Volume concentrates in commuter-grade configurations while premium margins flow to reinforced chassis designed for uneven terrain.
- Two-Wheel:Standard dual-wheel layout with 10-inch pneumatic tires and single-hub motor configuration. Demand clusters in urban rental fleets across Germany and South Korea where sidewalk-width restrictions favor compact footprints.
- All-Terrain:Reinforced aluminum frames with 21-inch knobby tires and dual-motor 4WD layouts. European outdoor recreation buyers in Austria and Switzerland drive procurement as trail-access infrastructure expands.
- Off-Road:Suspension-equipped variants with IP65-rated enclosures for mud and water ingress protection. Week-end adventure users in US mountain states sustain niche volume.
- Mini:Reduced wheelbase units under 8 kg targeting adolescent learners and indoor warehouse navigation. Japanese corporate campuses pilot deployment for inter-building mail delivery.
Mature deployment sits with Two-Wheel configurations. Newer deployment is concentrated in All-Terrain variants.
Weight Capacity:
Commercial fleet specifications diverge from consumer-grade limits as delivery payload requirements harden.
- 100 kg:Entry-level commuter rating with polymer shell construction. Private ownership in dense Asian urban cores dominates offtake where rider BMI demographics skew lower.
- 120 kg:Mid-tier reinforced deck with steel subframe upgrade. US rental operators mandate this minimum for liability coverage across mixed rider populations.
- 150 kg:Industrial-grade welding and expanded battery bay for cargo attachment. Last-mile logistics fleets in Indian metropolitan corridors specify this threshold for parcel-plus-rider combined loads.
- 200 kg:Heavy-duty tubular steel chassis with dual shock absorption. Warehouse fulfillment centers in the Netherlands deploy for multi-tote horizontal transport.
Procurement volume clusters at 120 kg for consumer markets. Steepest expansion trajectory belongs to 150 kg ratings.
Battery Type:
Energy density and thermal safety profiles now gate fleet insurance eligibility and indoor charging permissions.
- Lithium-Ion:NMC cylindrical cell packs with 18650 or 21700 form factors and integrated battery management systems. China's SAMR GB standards and EU CE marking directives both mandate this chemistry for export clearance.
- Lead-Acid:Sealed AGM construction with lower energy density but price points under one-third of lithium alternatives. Southeast Asian price-sensitive consumer channels retain volume despite weight penalties.
- Nickel-Metal Hydride:Intermediate chemistry with reduced memory effect versus legacy NiCd. Niche deployment in Japanese municipal fleets with established recycling infrastructure.
- Lithium Polymer:Pouch cell architecture enabling non-rectangular pack geometries for frame integration. Premium positioning in North American corporate fleets leverages Segway's patent-protected configurations.
Established fleet deployment relies on Lithium-Ion. Lithium Polymer is gaining share fastest among premium repositioning strategies.
Control Type:
Interface sophistication separates rental-grade telemetry integration from basic consumer ownership models.
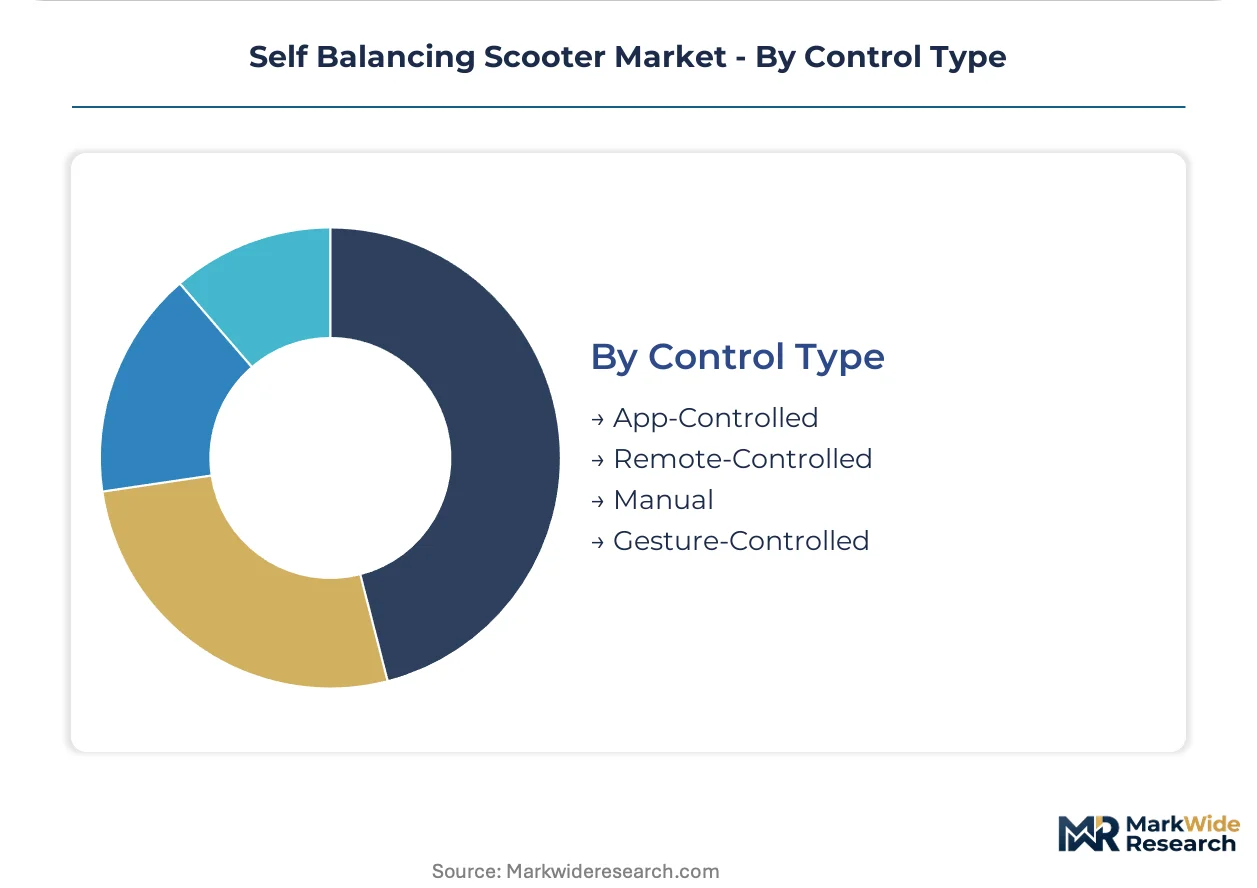
- App-Controlled:Bluetooth-linked smartphone interface with GPS tracking, speed limiting, and geofencing enforcement. Urban delivery operators in France and the United States mandate this capability for rider accountability and asset recovery.
- Remote-Controlled:Dedicated RF handset for parental supervision or training mode operation. Family recreational purchases in German suburban markets sustain demand.
- Manual:Physical foot-pad pressure sensors without wireless connectivity. Emerging market price tiers and legacy fleet maintenance stocks retain this specification.
- Gesture-Controlled:Accelerometer-based lean-angle interpretation with machine-learning calibration. Experimental deployment in South Korean tech-forward corporate campuses.
Manual interfaces anchor installed base maintenance. App-Controlled systems are expanding most quickly in new fleet procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors manufacturing density for self balancing scooter component supply, with Bao'an and Longgang districts hosting battery pack integrators and MEMS sensor distributors serving assembly plants across the Pearl River Delta.
United States
Urban delivery fleets in Los Angeles and Chicago mandate app-controlled telemetry for last-mile logistics contracts. The Consumer Product Safety Commission enforces electrical system standards that block uncertified imports at major ports. California's micromobility ordinances restrict sidewalk operation in San Francisco and Santa Monica, pushing rental deployments toward designated bike lanes.
Germany
Municipal dockless parking networks in Berlin and Munich expand legal operating zones for rental operators. The KBA administers type-approval frameworks that align with EU CE marking directives for electromagnetic compatibility. Industrial-grade suppliers in Baden-Württemberg pre-certify products ahead of 2027 Machinery Regulation enforcement to secure warehouse fleet contracts.
China
Domestic consumption concentrates in Shanghai and Beijing where shared mobility platforms deploy units for commuter feeder services. SAMR mandates GB-compliant battery management systems for export clearance and domestic production. Zhejiang and Jiangsu provinces concentrate final assembly capacity with backward integration into lithium-ion cell sourcing.
South Korea
Tech-forward corporate campuses in Seoul and Seongnam pilot gesture-controlled variants for inter-building mail delivery. The MFDS coordinates with industrial regulators on lithium-polymer safety standards for indoor charging permissions. Busan-Ulsan corridor hosts component distributors supplying gyroscopic MEMS modules to domestic assemblers.
India
Last-mile delivery penetration in Mumbai and Bangalore remains underdeveloped relative to East Asian fleet density, offering first-mover positioning for 150 kg-rated industrial units. The Bureau of Indian Standards develops certification pathways for lithium-ion imports amid expanding urban logistics demand. Tamil Nadu and Karnataka states attract assembly investment through electronics manufacturing zone incentives.
Self Balancing Scooter Market Competitive Environment
Premium-margin players sit above commodity-margin players across battery chemistry and control interface sophistication. The vendor base stratifies into patent-anchored incumbents, scale-driven manufacturers, and specialized terrain-focused suppliers. Three archetypes dominate: backward-integrated battery assemblers, IP-heavy positioning specialists, and all-terrain configuration experts. Competitive moves concentrate on certification pre-positioning for EU Machinery Regulation deadlines and telemetry integration for fleet procurement mandates.
Within the patent-anchored tier, Segway and Ninebot represent positioning extremes—one leveraging intellectual property portfolios for North American corporate fleet access, the other sustaining manufacturing scale through captive battery pack assembly. INMOTION occupies a specialization position among European outdoor recreation suppliers. These three exemplify how competitive separation now runs through certification timing and fleet telemetry compliance rather than unit economics alone.
| Leading Market Players |
|---|
| Airwheel |
| IPS |
| Ninebot |
| CHIC |
| Robstep |
| Segway |
| Inventist |
| ESWING |
| INMOTION |
| Others |
Value Chain & Pricing Dynamics
EU battery passport mandates and China's SAMR GB standards gate qualified supply access while compressing premium-tier pricing power for certified lithium-ion configurations against uncertified lead-acid alternatives. Fleet procurement contracts now embed compliance documentation as a price floor, with insurance underwriters demanding thermal runaway test data before binding coverage for indoor charging deployments.
Pricing Analysis
Telemetry-enabled uptime guarantees anchor value-based pricing for app-controlled fleet units, with rental operators paying subscription premiums for real-time asset tracking and geofencing enforcement. Three-tier pricing structure across premium lithium-polymer, standard lithium-ion, and economy lead-acid chemistries separates Segway's patent-protected corporate configurations from commodity Asian imports. Cost compression in entry-level tiers is intensifying because cobalt price volatility and lithium carbonate spot swings squeeze battery pack assemblers lacking long-term offtake agreements. Warehouse logistics buyers exhibit lowest price sensitivity due to indoor charging liability premiums, while Southeast Asian consumer channels remain most elastic to unit cost.
Supply Chain Analysis
CE marking and SAMR GB certification requirements filter component sourcing to qualified battery management system vendors and electromagnetic compatibility-tested MEMS foundries. Manufacturing gravity centers on China's Pearl River Delta, South Korea's Busan-Ulsan corridor, and Taiwan's gyroscopic sensor foundries, with Zhejiang and Jiangsu provinces hosting final assembly. Cell chemistry inputs draw from Chilean lithium brine, Congolese cobalt hydroxide, and Australian spodumene concentrate, exposing assemblers to commodity price volatility without hedging instruments. Distribution runs through Shenzhen export hubs to EU port clearance facilities, with Hamburg and Rotterdam warehousing for KBA type-approval staging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Machinery Regulation's 2027 functional safety documentation mandate erects a cost-of-compliance moat that advantages pre-certified German and Dutch industrial suppliers against late entrants scrambling for sensor redundancy test data.
For Market Incumbents: Cement fleet telemetry integration as the default procurement specification, locking rental operators into proprietary app ecosystems that block commodity substitution. Accelerate backward integration into battery pack assembly to capture margin currently flowing to Zhejiang integrators, while pre-positioning Machinery Regulation certification eighteen months ahead of enforcement to deny contract access to uncertified competitors. For New Entrants and Emerging Players: Solid-state battery prototyping offers a technology-first wedge against incumbents wedded to cylindrical cell formats, targeting warehouse operators with indoor charging constraints and liability-sensitive insurers. Indian last-mile logistics presents the most penetrable geography, with 150 kg-rated industrial units addressing underdeveloped fleet density relative to East Asian markets; pursue Bureau of Indian Standards certification pathways alongside Tamil Nadu electronics manufacturing zone incentives. For Investors and Strategic Acquirers: Early solid-state pilot deployments with Dutch warehouse operators are the leading indicator that thermal runaway elimination commands insurance premium arbitrage sufficient to offset cell cost multiples. Five-to-ten year viability hinges on certification timing rather than manufacturing scale alone; target acquisition profiles toward MEMS sensor specialists with redundant gyroscopic architectures and pre-certified battery management system IP.| Strategic Initiative | Industry Significance |
|---|---|
| Machinery Regulation Pre-Certification | Secures warehouse fleet contracts ahead of 2027 EU enforcement deadlines. |
| Telemetry Platform Integration | Locks rental operators into proprietary app ecosystems for recurring revenue. |
| Battery Pack Backward Integration | Captures margin from Zhejiang integrators while securing SAMR GB compliance. |
| Solid-State Pilot Deployment | Addresses indoor charging liability premiums for warehouse insurance arbitrage. |
| Indian Assembly Zone Investment | Leverages Tamil Nadu electronics incentives for 150 kg logistics unit production. |
Study Parameters
Document review covered SAMR GB standard filings, EU Machinery Directive transition guidance, and KBA type-approval frameworks, complemented by interviews with fleet procurement managers at French and US rental operators, battery pack engineering leads at Zhejiang assemblers, and electromagnetic compatibility testing directors at Dutch certification bodies. Secondary validation drew from customs trade databases, lithium carbonate spot price indices, and MEMS foundry capacity disclosures. Bottom-up unit shipment estimates triangulated against top-down battery chemistry demand models.
Historical shipment trajectories cross-referenced against panel input from procurement directors and certification consultants anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include battery chemistry tier, control interface sophistication, weight capacity rating, and regional regulatory cluster. CAGRs derived from slope consensus across triangulated demand drivers, with fleet telemetry adoption curves and solid-state pilot conversion rates serving as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including municipal sidewalk ban ordinances that could restrict consumer recreational usage, and unforeseen cobalt supply disruptions from Congolese mining jurisdictions. Forecasts reflect documented assumptions about certification timeline adherence and fleet operator insurance underwriting continuity. Stakeholders should weight assumptions against their own operating context and regional regulatory enforcement variability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
North America ATV and UTV Market
Recreational Vehicles
Saudi Arabia Yacht Charter Market
Recreational Vehicles
Jon Boat Market
Recreational Vehicles
United States Luxury Yacht Market
Recreational Vehicles
Fifth Wheel Trailer Market
Recreational Vehicles
Asia-Pacific Recreational Vehicle Market
Recreational Vehicles
RV Leisure Battery Market
Recreational Vehicles
Asia-Pacific Motor Home Market
Recreational Vehicles
Electric Golf Cart Market
Recreational Vehicles
Kick Scooter Market
Recreational Vehicles
Caravanning Market
Recreational Vehicles
Asia-Pacific Personal Watercraft Market
Recreational Vehicles
Recreational Boats Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
Online Powersports Market
Recreational Vehicles
Global Recreational Off-Highway Vehicles Market