
 Moveable Water Tap Market | 2026-2036
Moveable Water Tap Market Size, Share, and Industry Trends Forecast 2026-2036
Moveable Water Tap Market Foresight
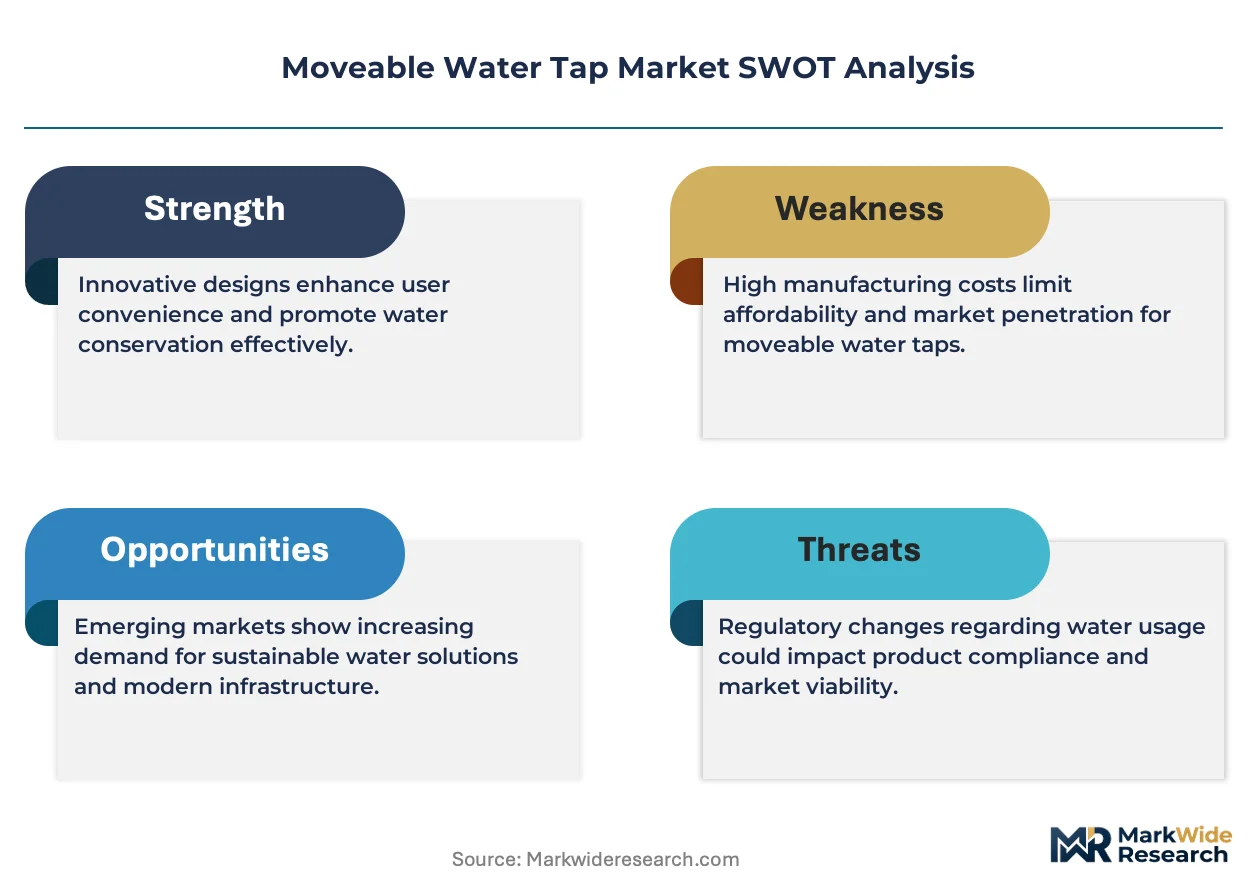
China is narrowing its cost advantage in die-cast brass components as Southeast Asian tooling clusters scale capacity. Kohler leverages captive zinc alloy foundries to sustain margin control across North American distribution. Grohe anchors European premium positioning through ceramic disc valve R&D intensity. Hansgrohe competes on EcoSmart flow-limiting technology leadership.
Moveable water taps are plumbing fixtures designed with articulated, retractable, or detachable delivery mechanisms, typically employing 35mm ceramic disc cartridges, braided stainless steel flex hoses, and low-lead brass or 304 stainless steel bodies to enable directed water flow across variable positions. Their primary commercial purpose centers on flexible washing, filling, and cleaning operations in kitchens, laboratories, and outdoor service environments where fixed spout reach proves inadequate. The brass material segment dominates installed value owing to machinability and perceived durability, though stainless steel occupies the fastest-growing tier among commercial foodservice specifiers prioritizing NSF 61 compliance. Residential deployment models generate the largest volume base, while agricultural and landscaping contractor channels represent concentrated margin pools for corrosion-resistant hose and sprayer configurations.
EPA Lead and Copper Rule revisions and NSF 372 low-lead certification requirements in the United States compel alloy substitutions that elevate unit costs and favor vertically integrated foundry operators. EMA and ECHA frameworks in Europe enforce nickel release thresholds under REACH that restrict certain brass surface finishes and redirect demand toward PVD-coated alternatives. Stakeholders must monitor evolving material compliance timelines and assess captive alloy development versus outsourced certified supply before committing to regional capacity expansion.
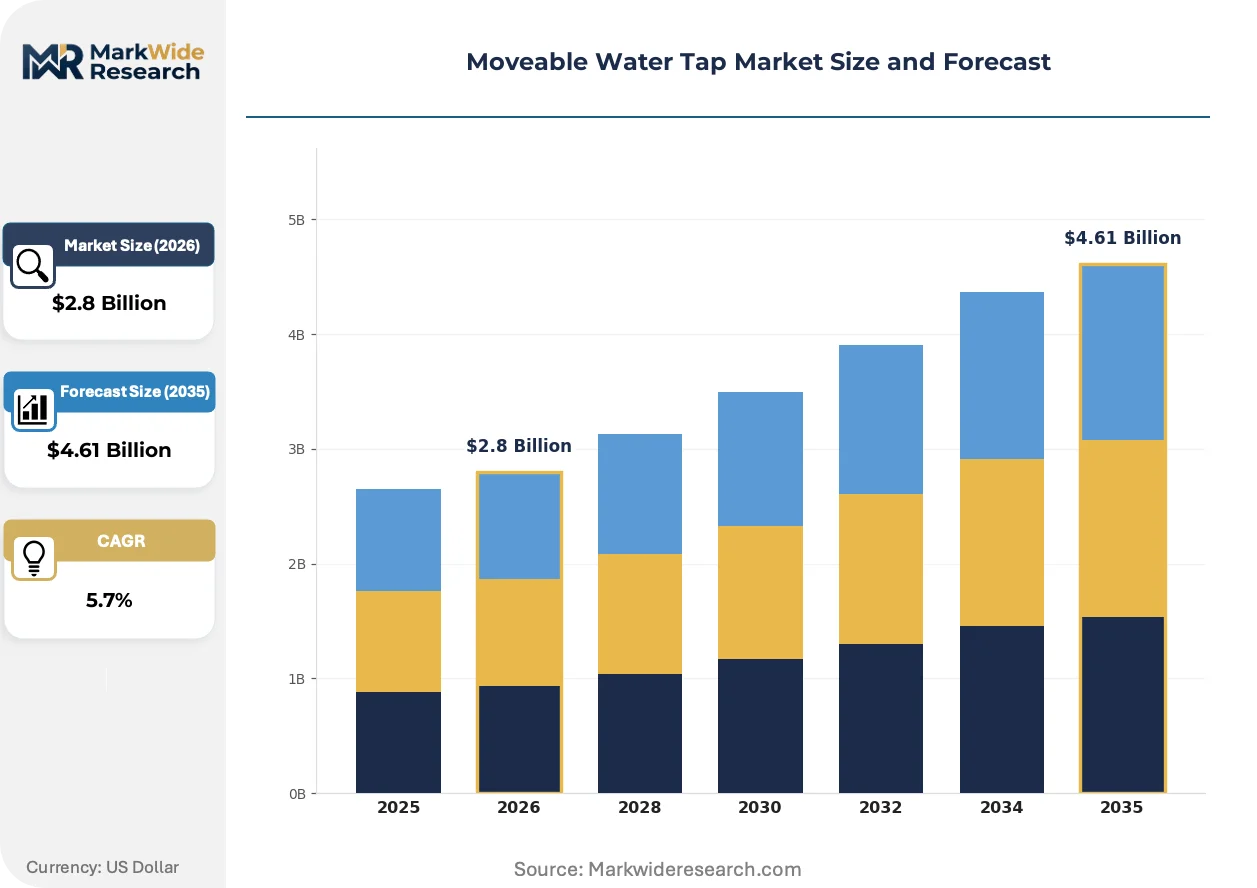
Market Dynamics
REACH nickel release thresholds and EPA Lead and Copper Rule revisions are forcing alloy substitutions across brass foundries, elevating unit costs and redistributing competitive advantage toward vertically integrated operators with captive low-lead formulation capabilities.
Growth Catalysts
- NSF 372 low-lead certification:US plumbing code adoption accelerates certified product replacement cycles in residential renovation channels.
- Outdoor kitchen installations:Pull-out tap systems capture specification share in residential hardscape projects across Germany and the United States.
- 35mm ceramic disc cartridge standardization:Interchangeable valve platforms reduce service part inventory burdens for commercial foodservice maintenance contractors.
Market Restraints
- Copper-zinc alloy volatility:Brass ingot price swings compress margin predictability for mid-tier OEMs without long-term foundry contracts.
- Die-cast tooling concentration:Southeast Asian mold-making clusters create single-source vulnerability for European precision component supply.
- Lead-free machinability trade-offs:Bismuth-substituted alloys reduce cutting tool life and elevate scrap rates in high-volume production runs.
Strategic Opportunities
- Mobile foodservice expansion:NSF 61-compliant stainless steel configurations address underpenetrated food truck and catering equipment channels.
- PVD surface coating adoption:REACH-compliant finishes bypass nickel release restrictions while enabling premium positioning in German and French specification markets.
- EcoSmart flow-limiting integration:Water efficiency mandates in drought-prone US states create specification pull for sub-1.5 gpm aerator systems.
Industry Challenges
- Metallurgical formulation expertise:Low-lead brass R&D capability scarcity constrains rapid product recertification timelines.
- Multi-jurisdictional compliance parallelism:Simultaneous EPA, NSF, and ECHA testing requirements extend new product introduction cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moveable Water Tap Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Faucet, Hose, Sprayer, Coupling Deployment Model: Residential, Commercial, Industrial, Agricultural Material: Plastic, Brass, Stainless Steel, Aluminum End User: Homeowners, Contractors, Landscaping Firms, Municipalities |
| Companies Covered | Kohler, Grohe, Delta, Moen, American Standard, TOTO, Quooker, Hansgrohe, Jaquar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moveable Water Tap Market Shifts & Advancements
Sensor-activated flow control and connected water monitoring are digitizing fixture specification criteria, compressing the traditional mechanical-valve supply base while opening interface partnerships with building automation platforms.
Touchless infrared activation modules are digitizing hygiene-sensitive installations in healthcare and commercial food preparation environments. Hospital facilities managers specify these systems at accelerating rates to reduce cross-contamination vectors. The technology is digitizing competitive positioning by shifting vendor evaluation criteria from mechanical durability to sensor reliability and IoT integration protocols.
REACH Annex XVII nickel restrictions are eliminating traditional chrome-plated brass finishes from European residential specifications. Manufacturers reformulate surface layers or migrate to PVD-coated alternatives at elevated processing cost. German sanitaryware distributors now stock predominantly nickel-free catalog lines to preempt compliance liability.
Specification authority migration from wholesalers to facilities management platforms is consolidating procurement leverage in multi-site foodservice and hospitality chains. Digital tendering platforms aggregate volume across property portfolios, compressing supplier margins while rewarding scale-capable manufacturers. This pattern concentrates most visibly in United States contract foodservice and UK hotel renovation channels.
Moveable Water Tap Market Segmentation
Segmentation in moveable water taps reveals divergent service requirements and margin structures across installation environments. After-sales intensity varies sharply between residential replacement cycles and commercial maintenance contracts, reshaping how manufacturers configure distribution and technical support networks.
Product Type:
Service part logistics and replacement frequency differ substantially across product types, with implications for inventory positioning and distributor relationships.
- Faucet:Articulated spout assemblies with ceramic disc cartridges dominate installed value in kitchen and laboratory environments. German sanitaryware distributors specify these systems for outdoor kitchen hardscape projects where pull-out reach flexibility commands premium positioning.
- Hose:Braided stainless steel flex lines with polymer sheathing enable variable-position water delivery across washing and filling operations. Landscaping contractors in drought-prone US states prioritize NSF 61-compliant configurations for mobile irrigation and equipment cleaning workflows.
- Sprayer:Detachable spray heads with flow-limiting aerators address targeted cleaning applications.
- Coupling:Quick-connect fittings facilitate tool-free attachment and repositioning across temporary installations.
By volume, Hose leads. By growth pace, Faucet is ahead.
Deployment Model:
Cost tier stratification separates specification-grade commercial systems from mass-market residential offerings, with distinct certification burdens and margin profiles.
- Residential:Pull-out and detachable tap systems for kitchen and outdoor environments generate the largest unit volumes. NSF 372 low-lead certification requirements in US plumbing codes accelerate replacement cycles in renovation channels.
- Commercial:NSF 61-compliant stainless steel configurations serve foodservice and healthcare facilities. Food truck and catering equipment channels remain underpenetrated, creating specification opportunities for corrosion-resistant mobile installations.
- Industrial:Heavy-duty brass or 304 stainless steel bodies withstand chemical exposure and high-frequency operation.
- Agricultural:Corrosion-resistant hose and sprayer configurations target contractor channels with concentrated margin pools for field irrigation and equipment washing.
Residential commands the volume base. Commercial offers the steepest expansion trajectory.
Material:
Volume concentration and supply chain geography determine competitive positioning, with foundry integration becoming a critical differentiator amid alloy reformulation pressures.
- Brass:Low-lead copper-zinc alloys dominate installed value through machinability and perceived durability. REACH restrictions on lead-containing alloys in Europe accelerate reformulation across manufacturers, elevating unit costs and favoring vertically integrated foundry operators.
- Stainless Steel:304-grade bodies with PVD surface coatings occupy the fastest-growing tier among commercial foodservice specifiers prioritizing NSF 61 compliance and REACH nickel release compliance.
- Plastic:Polymer housings reduce weight and cost in temporary and seasonal applications.
- Aluminum:Lightweight extrusions serve portable and mobile equipment configurations.
Brass retains value leadership. Stainless Steel is gaining share fastest.
End User:
Customer type determines procurement authority and specification complexity, with facilities management platforms consolidating leverage in multi-site accounts.
- Homeowners:Individual purchasers drive replacement demand through retail and wholesale channels. Digital tendering platforms are beginning to aggregate residential renovation volume in certain markets.
- Contractors:Professional installers specify systems based on service part availability and installation efficiency. German precision plumbing component exports anchor regional supply chains for this channel.
- Landscaping Firms:Mobile irrigation and equipment cleaning operations demand corrosion-resistant hose configurations with quick-connect functionality.
- Municipalities:Public procurement of outdoor service fixtures emphasizes durability and lead-free compliance for parks and recreational facilities.
Contractors lead by specification volume. Landscaping Firms show the most rapid demand expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision plumbing component exports anchor regional supply chains, while Southeast Asian tooling clusters scale capacity to narrow China's historical cost advantage in die-cast brass manufacturing.
United States
Residential outdoor kitchen installations drive pull-out tap specification in hardscape projects across Sun Belt states. EPA Lead and Copper Rule revisions compel NSF 372 low-lead certification adoption, accelerating replacement cycles in renovation channels. California and Texas housing markets concentrate demand for EcoSmart flow-limiting aerator systems.
Germany
REACH nickel release thresholds under ECHA frameworks eliminate traditional chrome-plated brass finishes from residential specifications. German sanitaryware distributors now stock predominantly PVD-coated catalog lines to preempt compliance liability. The Rhine-Ruhr and Bavarian industrial corridors host precision valve R&D clusters serving export markets.
China
Yangtze River Delta die-cast foundries face margin compression as Southeast Asian competitors capture tooling orders. The country's national environmental regulator enforces dual carbon goals that elevate energy costs for brass smelting operations. Zhejiang and Guangdong provinces concentrate stainless steel flex hose manufacturing for commercial foodservice export.
India
Maharashtra and Gujarat contractor channels generate concentrated demand for corrosion-resistant agricultural sprayer configurations. BIS standards for lead content in plumbing fixtures tighten compliance timelines for domestic manufacturers. Pune and Ahmedabad industrial zones scale CNC machining capacity for ceramic disc cartridge assembly.
United Kingdom
London and Southeast England facilities management platforms consolidate procurement leverage across multi-site hospitality renovation projects. UK building regulations align with REACH Annex XVII restrictions, redirecting specification toward nickel-free surface finishes. Midlands manufacturing clusters specialize in quick-connect coupling systems for mobile foodservice applications.
Moveable Water Tap Market Competitive Landscape
Vertically integrated brass foundry operators and precision ceramic valve specialists split the market between cost-controlled volume production and specification-grade premium positioning. The vendor base organizes around three strategic archetypes: captive alloy formulators, outsourced certified assemblers, and stainless steel compliance-focused fabricators. Consolidation pressures favor operators with in-house low-lead metallurgical R&D. Geographic expansion and strategic partnerships constitute the dominant competitive moves as manufacturers seek to bypass multi-jurisdictional certification bottlenecks.
Among German sanitaryware specialists, Grohe and Hansgrohe exemplify premium-tier positioning through ceramic disc valve technology leadership and EcoSmart water efficiency systems. Kohler anchors North American market presence through captive zinc alloy foundry operations that sustain margin control across distribution networks. These three entities represent distinct strategic pathways: European precision engineering, North American vertical integration, and flow-limiting regulatory anticipation.
| Leading Market Players |
|---|
| Kohler |
| Grohe |
| Delta |
| Moen |
| American Standard |
| TOTO |
| Quooker |
| Hansgrohe |
| Jaquar |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp freight corridors anchor European distribution economics, where container cost volatility propagates through German sanitaryware wholesale networks and compresses margin pools for mid-tier brass component assemblers lacking long-term foundry contracts.
Pricing Analysis
EPA Lead and Copper Rule revisions dictate the pricing tier structure across North American channels, separating NSF 372-certified premium systems from uncertified economy alternatives. Price differentiation hinges on low-lead alloy certification grade and captive foundry integration depth. Cost compression in standard-tier configurations is intensifying because bismuth-substituted alloys reduce cutting tool life and elevate scrap rates. Residential renovation contractors exhibit highest price sensitivity, while facilities management platforms at multi-site foodservice chains prioritize specification-grade durability over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic planning for die-cast brass component sourcing. Production gravity centers on Germany, China, and Vietnam, with Yangtze River Delta foundries facing margin pressure from Southeast Asian tooling clusters. Raw material dependencies rest on copper-zinc alloy ingots, ceramic disc cartridges, and braided stainless steel flex hoses. Single-source vulnerability concentrates in Vietnamese mold-making clusters serving European precision component demand. Distribution runs through German sanitaryware distributors and North American wholesale plumbing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facilities management platform consolidation across multi-site foodservice and hospitality chains is shifting procurement leverage toward volume-aggregated buyers, compressing supplier margins while rewarding scale-capable manufacturers.
For Market Incumbents: Build metallurgical formulation expertise as a defensive moat around low-lead brass R&D capabilities. Deepen backward integration into captive zinc alloy foundries to sustain margin control against copper-zinc price volatility. Secure long-term supply agreements with Southeast Asian tooling clusters to preempt single-source vulnerability in die-cast component supply. For New Entrants and Emerging Players: Mobile foodservice and food truck equipment channels in the United States represent the most penetrable entry point given NSF 61 compliance gaps among incumbent suppliers. Target corrosion-resistant stainless steel configurations for agricultural contractor channels in India where BIS lead-content standards are tightening. Pursue direct specification relationships with landscaping firms rather than wholesale distribution to bypass entrenched channel control. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming plumbing fixture divisions lacking REACH-compliant surface finishing capabilities. Five-to-ten year viability favors operators with in-house PVD coating infrastructure and ECHA certification pipelines. Monitor EPA enforcement intensity around Lead and Copper Rule implementation as the critical inflection signal for certified product replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Integration | In-house low-lead brass production secures margin control against alloy price volatility and EPA certification timelines. |
| PVD Surface Coating Scale-Up | REACH-compliant nickel-free finishes unlock German and French specification markets at premium positioning. |
| Ceramic Disc Cartridge R&D Partnership | Precision valve technology alliances with German R&D clusters defend premium-tier positioning against Asian cost competition. |
| Mobile Foodservice Channel Development | NSF 61-compliant stainless steel configurations address underpenetrated food truck and catering equipment segments. |
| EcoSmart Flow-Limiting Certification | Sub-1.5 gpm aerator systems capture specification pull in California and Texas drought-mandate environments. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plumbing fixture procurement managers, facilities management platform directors, brass foundry operations heads, and ceramic valve R&D specialists; and secondary validation against EPA enforcement records, ECHA REACH registration databases, NSF certification listings, and customs trade data for copper-zinc alloy imports. Bottom-up channel volume estimates triangulated against top-down manufacturer capacity assessments.
Forecast inputs incorporated deployment model segmentation across residential, commercial, industrial, and agricultural channels; material tier stratification between brass, stainless steel, plastic, and aluminum configurations; and end-user procurement authority patterns. CAGRs derived from replacement cycle analysis, regulatory compliance timeline modeling, and outdoor kitchen installation trend extrapolation across the projection horizon. Alloy substitution cost curves and PVD coating adoption rates informed price trajectory assumptions.
Stress conditions across brass ingot price volatility, REACH nickel release threshold enforcement intensity, and Southeast Asian tooling cluster expansion pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EPA Lead and Copper Rule implementation timing and ECHA framework evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Latin America Smart Home Market
Others
Mobile Retina Services Market
Others
Language Translation Device Market
Others
Underwater Lighting Market
Others
South America Halal Food and Beverages Market
Others
Latin America Contract Packaging Market
Others
Asia-Pacific Telecom Transformers Market
Others
Linseed Oil Market
Others
Silicone Molding Machinery Market
Others
Vegetable Carbon Market
Others
France 3D Printing Construction Market
Others
Badminton Apparel Market
Others
Smart Plug Market
Others
Global Cosmetovigilance Market
Others
Technical Films Market
Others
Europe Tablet PC Market