
 ASEAN Agricultural Logistics Market | 2026-2036
ASEAN Agricultural Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Agricultural Logistics Market Insights
Modular cold chain bundling is repositioning buyer choice across ASEAN agricultural corridors. DHL leverages its pharmaceutical-grade temperature infrastructure to extend services into durian and mangosteen exports from Thailand. Cargill Logistics anchors its regional presence through integrated grain handling and port terminal operations in Vietnam and Indonesia. Tiong Nam Logistics Holdings Bhd specializes in last-mile distribution networks connecting Malaysian palm oil estates to Port Klang container terminals.
Agricultural logistics encompasses the coordinated movement, storage, and preservation of crops, livestock products, and agrochemicals from farm gate to processing facility or export terminal, requiring controlled atmosphere systems maintaining specific humidity and temperature parameters to prevent post-harvest losses exceeding thirty percent in tropical climates. Transport Services dominates value generation across archipelagic markets where inter-island ferry and short-sea shipping bridge fragmented production zones, while Cold Chain Logistics represents the fastest-expanding segment as Thai and Vietnamese regulators tighten food safety protocols for seafood and fresh fruit shipments to China, Japan, and South Korea. IoT Solutions within the Technology dimension captures concentrated R&D investment as real-time cargo monitoring reduces insurance claims and customs clearance delays at ASEAN border checkpoints.
ASEAN member states coordinate phytosanitary certification through the ASEAN Economic Community framework, while national regulators including Thailand's Ministry of Agriculture and Cooperatives and Vietnam's Plant Protection Department enforce bilateral export protocols with China customs authorities. The EU Green Deal's deforestation regulation and emerging due diligence requirements are reshaping compliance costs for palm oil and rubber logistics originating from Indonesia and Malaysia. Stakeholders must monitor divergence between ASEAN harmonization timelines and unilateral EU and Chinese import standards that could fragment certification requirements across the region's major agricultural export corridors.
Market Dynamics
Cross-border trade corridor deepening under the ASEAN Economic Community framework is compressing compliance timelines and forcing logistics providers to harmonize phytosanitary certification systems across Thailand, Vietnam, and Indonesia simultaneously.
Growth Catalysts
- ASEAN Economic Community harmonization:Regulators are converging phytosanitary standards across member states, reducing border clearance friction for Thai durian and Vietnamese shrimp exporters serving Chinese import protocols.
- IoT-enabled cargo monitoring:Real-time temperature and humidity tracking systems are cutting insurance claims and customs delays at Mekong Delta export clusters serving Japan-bound aquaculture shipments.
- China-Japan demand concentration:Premium fresh produce and seafood export corridors from Vietnam and Thailand are pulling specialized cold chain investment into Ho Chi Minh City and Bangkok peripheral logistics zones.
Market Restraints
- Diesel price volatility:Archipelagic inter-island ferry and short-sea shipping operations across Indonesia and the Philippines face margin compression from fuel cost swings that operators cannot pass through contractually.
- Port terminal concentration:Grain handling capacity bottlenecks at Vietnamese deep-water terminals create queuing risks for Mekong Delta rice exporters during peak harvest windows.
- EU Green Deal due diligence:Emerging deforestation traceability requirements are layering compliance costs onto Malaysian palm oil and Indonesian rubber logistics chains without offsetting freight premiums.
Strategic Opportunities
- Myanmar corridor development:Underdeveloped cross-border road and cold storage infrastructure connecting Yangon to Thailand's Chanthaburi fruit belt offers first-mover positioning as bilateral trade normalization proceeds.
- Pharmaceutical-grade cold chain extension:Temperature-controlled infrastructure originally built for vaccine distribution is being repurposed for high-value tropical fruit exports, opening premium service tiers.
- Solar-powered reefers:Photovoltaic-assisted container cooling systems are converging with battery storage advances to cut generator dependency in remote Indonesian plantation pickup points lacking grid connectivity.
Industry Challenges
- Reefer technician scarcity:Specialized maintenance skills for controlled-atmosphere systems remain concentrated in Bangkok and Singapore, creating service response lags for Indonesian and Philippine agricultural clusters.
- Legacy warehouse retrofitting:Converting ambient storage facilities in Vietnam's Mekong Delta to full cold chain compliance requires capital outlays that mid-tier logistics operators cannot finance without foreign joint venture structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Agricultural Logistics Market |
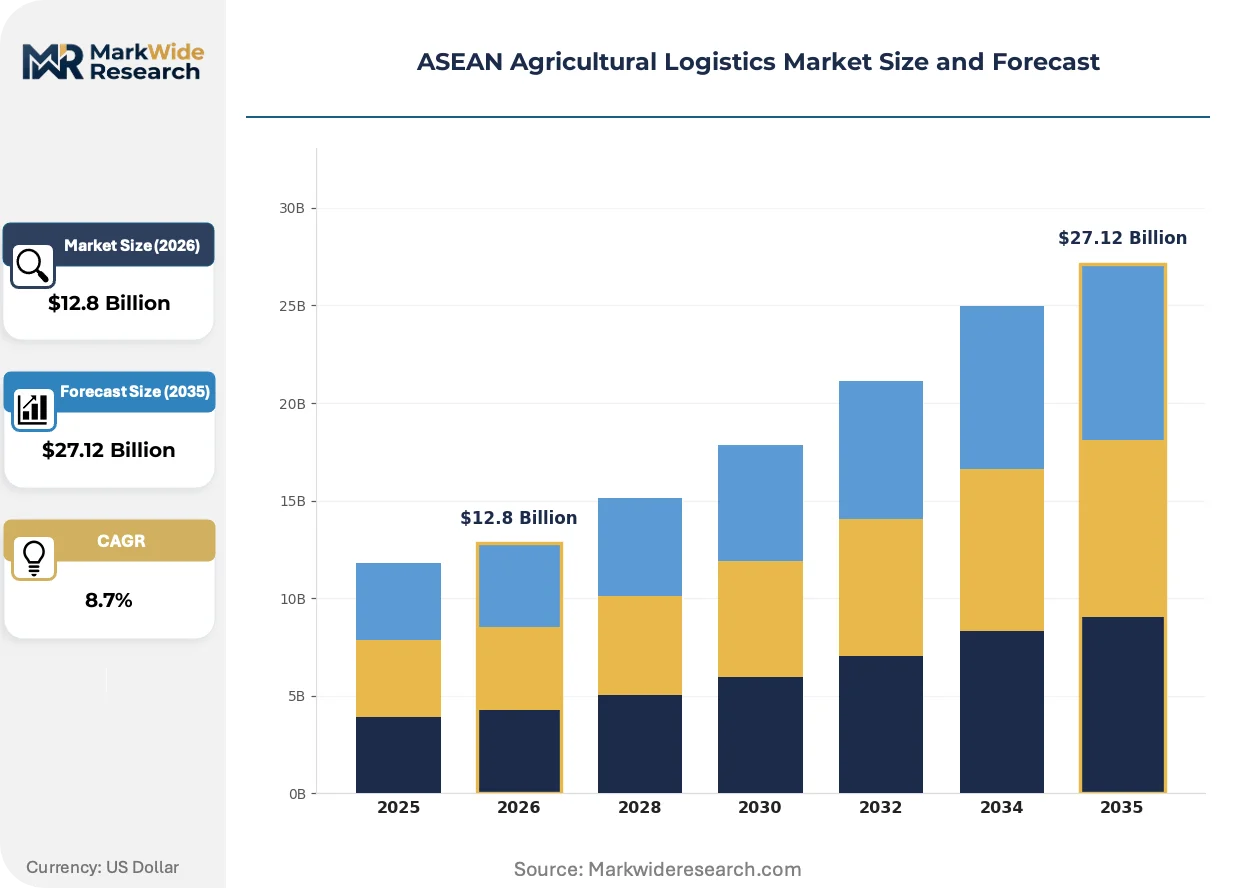
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transport Services, Warehousing, Cold Chain Logistics, Freight Forwarding End User: Farms, Distributors, Retail Chains, Exporters Technology: IoT Solutions, Automated Storage, Blockchain Systems, Tracking Software Packaging Type: Bags, Crates, Temperature-Controlled Containers, Bulk Packaging |
| Companies Covered | DHL, Kuehne + Nagel International AG, Bollore Logistics, Nippon Express Co., Ltd., Cargill Logistics, CEVA Logistics, The Maersk Group, C.H. Robinson, Tiong Nam Logistics Holdings Bhd, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Agricultural Logistics Market Trends and Innovations
Digital traceability systems and renewable-powered refrigeration are compressing operating cost structures while ASEAN regulators accelerate food safety protocol convergence. These shifts are redrawing competitive boundaries between asset-heavy integrated operators and technology-enabled platform models.
Blockchain-enabled provenance tracking is integrating shipment documentation with customs pre-clearance systems. Thai durian exporters serving Chinese supermarkets are adopting distributed ledger platforms to compress inspection times at border checkpoints. This technology convergence is integrating previously siloed logistics, insurance, and banking workflows into unified trade finance instruments.
Vietnam's Plant Protection Department and Thailand's Ministry of Agriculture are tightening bilateral export protocols with China customs authorities. These regulatory adjustments are forcing logistics providers to pre-certify cold chain integrity documentation before vessel loading. Seafood and fresh fruit segments are responding by embedding third-party auditors at farm-gate pickup points rather than terminal inspection.
Japanese supermarket procurement teams are consolidating supplier bases and demanding multi-origin consolidated containers from ASEAN hubs. This buyer concentration is displacing single-origin direct contracts that dominated pre-pandemic trade patterns. The shift is most visible in Bangkok's Lat Krabang logistics zone where Vietnamese, Thai, and Malaysian produce now share temperature-controlled consolidation facilities.
ASEAN Agricultural Logistics Market Segmentation
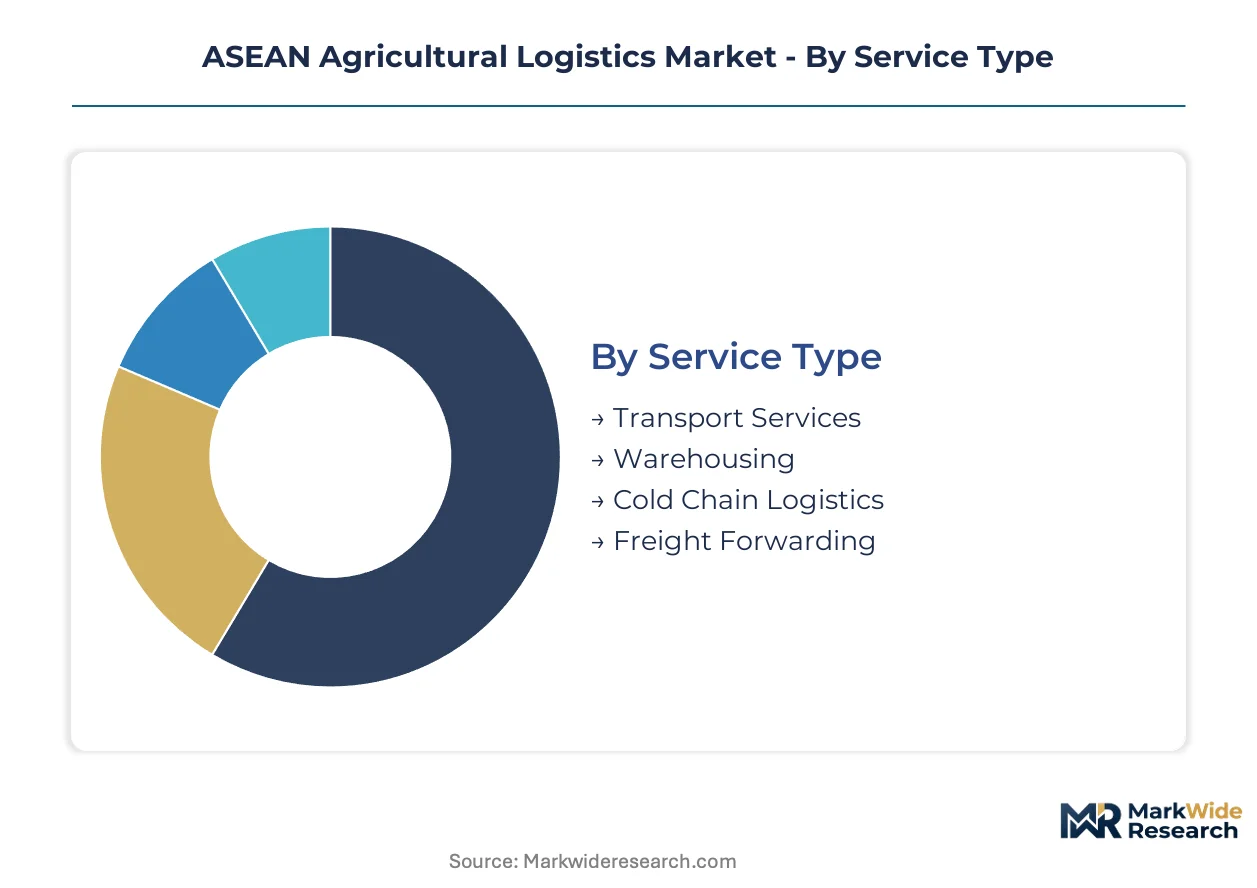
Segmentation across ASEAN agricultural logistics reveals how service bundling and technology embedding reshape procurement decisions. Buyers now select integrated solutions rather than discrete functions, compressing vendor shortlists to operators spanning multiple service layers.
Service Type:
Standalone transport contracts dominate low-value commodity flows, while integrated cold chain bundles capture premium perishable corridors requiring seamless custody transfer.
- Transport Services:Inter-island ferry networks and short-sea shipping bridge Indonesia's fragmented archipelago production zones. Diesel price volatility squeezes margins on Philippine coconut and Indonesian palm oil routes where fuel surcharges cannot pass through contractually.
- Cold Chain Logistics:Controlled-atmosphere systems maintain precise humidity and temperature parameters for Thai durian and Vietnamese shrimp exports to China. Regulatory tightening on food safety protocols is pulling specialized investment into Bangkok and Ho Chi Minh City peripheral zones.
- Warehousing:Ambient storage facilities in Vietnam's Mekong Delta face retrofitting pressure to meet full cold chain compliance.
- Freight Forwarding:Customs brokerage and documentation services compress clearance timelines at ASEAN border checkpoints.
Volume placements concentrate in Transport Services; the faster expansion belongs to Cold Chain Logistics.
End User:
Customer scale determines service tier access, with large exporters commanding dedicated infrastructure while smaller farms aggregate through cooperative structures.
- Exporters:Thai durian and Vietnamese aquaculture shippers to Japan and China demand pharmaceutical-grade temperature infrastructure with embedded IoT monitoring. Consolidated procurement teams at Japanese supermarket chains now require multi-origin container sharing across ASEAN hubs.
- Retail Chains:Modern trade networks in Malaysia and Thailand impose strict traceability requirements on upstream logistics providers. Blockchain-enabled provenance tracking integrates shipment documentation with customs pre-clearance systems.
- Distributors:Mid-tier aggregators connect Mekong Delta rice producers to Vietnamese deep-water terminals.
- Farms:Smallholder operations in Indonesia and the Philippines lack direct cold chain access, relying on plantation-level collection points.
Revenue gravity sits with Exporters; Retail Chains are climbing the fastest.
Technology:
Technology deployment splits between retrofit add-ons for legacy fleets and native integration in new infrastructure builds.
- IoT Solutions:Real-time temperature and humidity tracking systems cut insurance claims and customs delays at Mekong Delta export clusters. Sensor networks now extend from farm-gate pickup through vessel loading, replacing terminal-only inspection points.
- Blockchain Systems:Distributed ledger platforms compress inspection times at Thai-Chinese border checkpoints for durian shipments. Smart contracts integrate logistics, insurance, and banking workflows into unified trade finance instruments.
- Automated Storage:Robotic handling systems penetrate Malaysian palm oil consolidation facilities at Port Klang.
- Tracking Software:GPS and RFID systems provide shipment visibility without full blockchain infrastructure.
Adoption depth is greatest in IoT Solutions; Blockchain Systems show the steepest expansion trajectory.
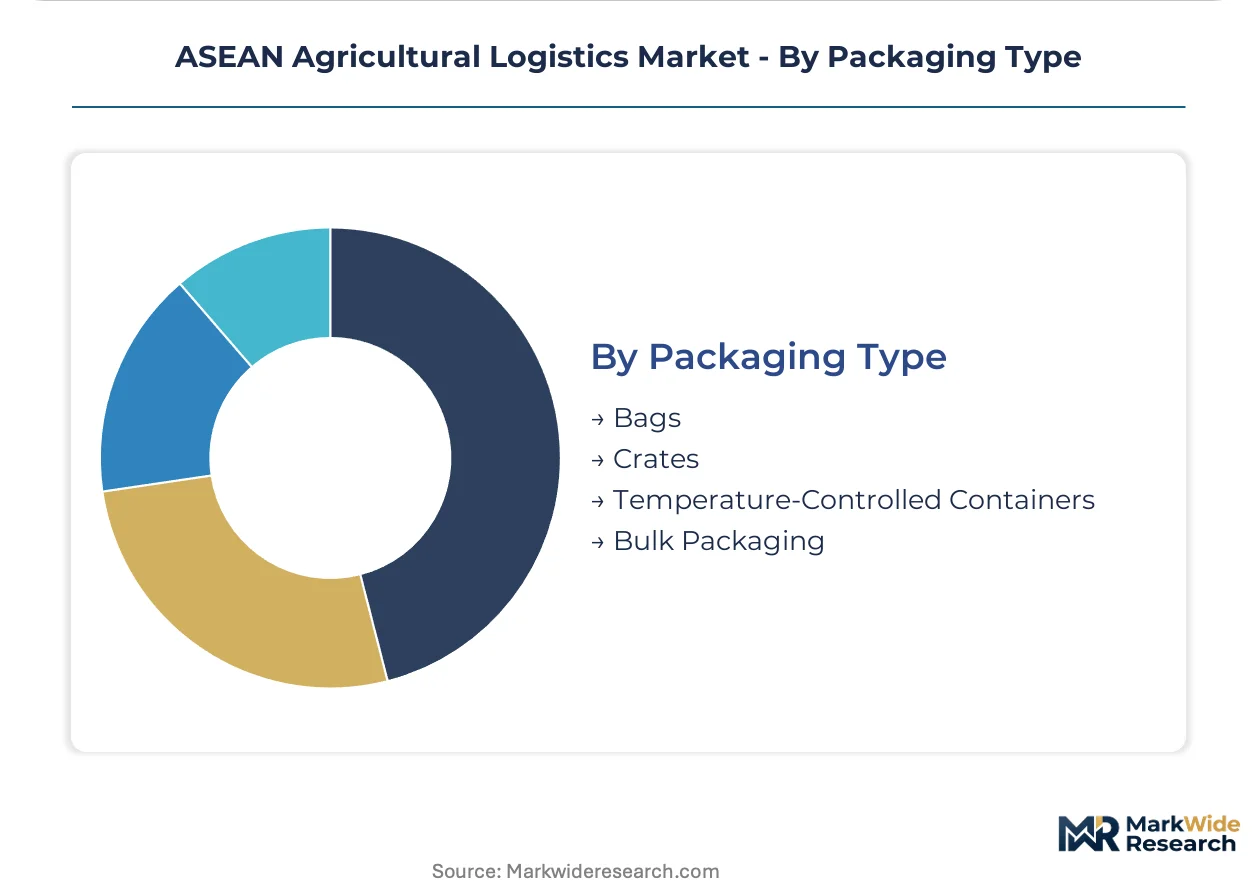
Packaging Type:
Packaging selection tracks product perishability and destination market regulatory requirements, with premium exports demanding certified controlled-atmosphere solutions.
- Temperature-Controlled Containers:Refrigerated units with photovoltaic-assisted cooling cut generator dependency at remote Indonesian plantation pickup points lacking grid connectivity. Solar-battery convergence enables autonomous operation beyond established power infrastructure.
- Crates:Standardized plastic and wooden crate systems dominate short-haul domestic distribution of fresh vegetables across Thailand and Vietnam.
- Bulk Packaging:Grain handling at Vietnamese deep-water terminals relies on bulk systems facing queuing risks during peak harvest windows.
- Bags:Woven polypropylene sacks persist in lowest-cost rice and commodity flows where temperature control remains unnecessary.
Deployment scale favors Crates; Temperature-Controlled Containers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand and Vietnam generate the bulk of ASEAN agricultural export volume, yet Indonesia and the Philippines dominate internal consumption logistics across sprawling archipelagic territories. This production-consumption split shapes divergent infrastructure investment priorities across member states.
Thailand
Chanthaburi's durian belt and Bangkok's Lat Krabang logistics zone anchor cold chain expansion for China-bound fruit shipments. Thailand's Ministry of Agriculture and Cooperatives enforces bilateral phytosanitary protocols with Chinese customs authorities, tightening pre-export certification requirements. DHL leverages pharmaceutical-grade temperature infrastructure to extend services into durian and mangosteen corridors from eastern provinces.
Vietnam
Mekong Delta rice and aquaculture exports to Japan and China concentrate demand in Ho Chi Minh City peripheral logistics clusters. Vietnam's Plant Protection Department coordinates with ASEAN Economic Community frameworks while maintaining separate bilateral agreements with Chinese import regulators. Deep-water terminal queuing risks at Vietnamese ports create harvest-window bottlenecks for grain exporters.
Indonesia
Palm oil estates across Sumatra and Kalimantan rely on inter-island ferry networks bridging fragmented production zones. EU Green Deal deforestation due diligence requirements are layering compliance costs onto rubber and palm oil logistics chains without offsetting freight premiums. Solar-powered reefers with photovoltaic-assisted cooling cut generator dependency at remote plantation pickup points lacking grid connectivity.
Malaysia
Port Klang container terminals serve as consolidation hubs connecting palm oil estates to international shipping lanes. Tiong Nam Logistics Holdings Bhd specializes in last-mile distribution networks linking Malaysian plantations to these export gateways. Modern trade networks in peninsular Malaysia impose strict traceability requirements on upstream logistics providers through blockchain-enabled provenance systems.
Philippines
Coconut and tropical fruit production across Luzon and Visayas islands depends on short-sea shipping and archipelagic ferry operations. Diesel price volatility squeezes margins on domestic routes where fuel surcharges cannot pass through contractually. Specialized reefer technician skills remain concentrated in Manila and Cebu, creating service response lags for southern agricultural clusters.
ASEAN Agricultural Logistics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across ASEAN agricultural corridors, creating a tiered market structure where scale advantages clash with localized agility. Asset-heavy integrated operators anchor grain handling and port terminal operations, while technology-enabled platform models capture digital traceability and IoT monitoring segments. Three archetypes dominate: global freight forwarders with cold chain extensions, regional plantation-linked logistics providers, and pharmaceutical-grade temperature infrastructure repurposers. Competitive moves concentrate on strategic partnerships for cross-border certification harmonization and capacity expansion at Mekong Delta and Bangkok peripheral zones.
Among global freight forwarding conglomerates, DHL, Kuehne + Nagel International AG, and Cargill Logistics occupy positions spanning multiple service layers. DHL exemplifies the pharmaceutical-grade cold chain extension archetype, repurposing vaccine-distribution infrastructure for high-value tropical fruit exports. Kuehne + Nagel International AG represents the integrated documentation and customs brokerage tier, compressing clearance timelines at ASEAN border checkpoints. Cargill Logistics anchors the plantation-linked grain handling segment through integrated operations in Vietnamese and Indonesian port terminals.
| Leading Market Players |
|---|
| DHL |
| Kuehne + Nagel International AG |
| Bollore Logistics |
| Nippon Express Co., Ltd. |
| Cargill Logistics |
| CEVA Logistics |
| The Maersk Group |
| C.H. Robinson |
| Tiong Nam Logistics Holdings Bhd |
| Others |
Pricing and Supply Chain Analysis
Japanese supermarket procurement consolidation into multi-origin consolidated containers is forcing ASEAN logistics providers to absorb consolidation costs while competing for shrinking vendor shortlists, compressing margins across Bangkok and Ho Chi Minh City peripheral zones.
Pricing Analysis
Margin tightening in mid-tier cold chain services reflects diesel price volatility that archipelagic ferry operators cannot pass through contractually. Three-tier pricing structure across pharmaceutical-grade, standard cold chain, and ambient transport levels separates exporters by certification grade and IoT embedding. Cost compression accelerates in Indonesian palm oil corridors as EU Green Deal due diligence layers compliance costs without freight premiums. Smallholder farms in the Philippines exhibit highest price sensitivity, while Japanese supermarket procurement teams command dedicated infrastructure with least sensitivity.
Supply Chain Analysis
Direct-to-exporter channels handle hyperscale demand from Thai durian and Vietnamese aquaculture shippers, while cooperative aggregation serves Mekong Delta rice producers. Supply concentrates in Thailand, Vietnam, and Indonesia, with raw material flows drawing from Sumatran palm oil estates, Mekong Delta harvests, and Chanthaburi fruit belts. Distribution runs through Port Klang, Bangkok's Lat Krabang zone, and Ho Chi Minh City peripheral clusters. Single-source vulnerability at Vietnamese deep-water terminals creates queuing risks during peak harvest windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN agricultural logistics is becoming a vertical-integration race as operators pursue upstream cold storage control to capture margin from farm-gate certification and bypass terminal bottlenecks.
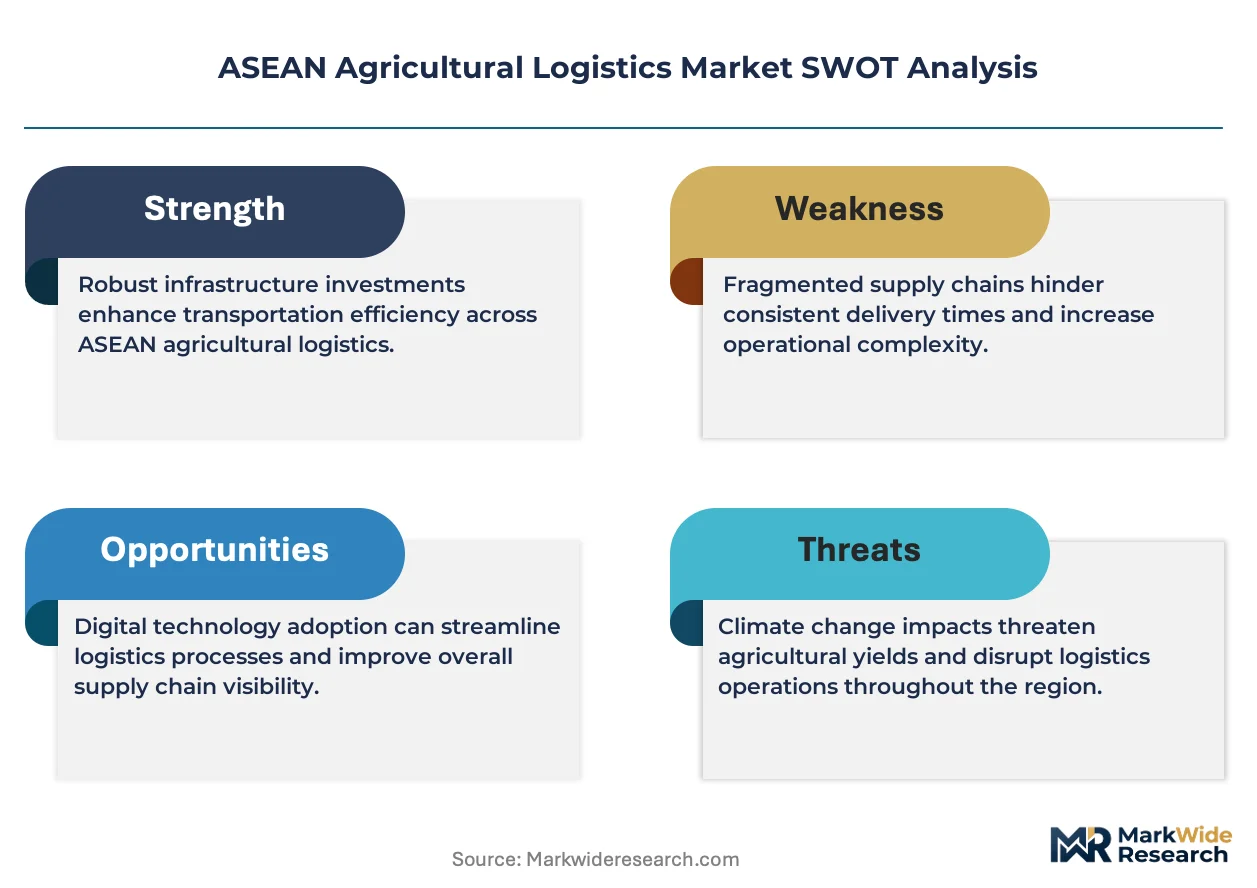
For Market Incumbents: Anticipate margin compression from pharmaceutical-grade cold chain repurposers by embedding third-party auditors at farm-gate pickup points rather than terminal inspection. Secure backward integration into solar-powered reefer fleets to cut generator dependency at remote Indonesian plantation points. Defend against platform-based traceability entrants by controlling consolidation facility access at Bangkok and Ho Chi Minh City peripheral zones. For New Entrants and Emerging Players: Launch via Myanmar corridor development as bilateral trade normalization proceeds, targeting underdeveloped cross-border road and cold storage infrastructure connecting Yangon to Thailand's Chanthaburi fruit belt. White-space exists in pharmaceutical-grade temperature infrastructure extension for high-value tropical fruit exports. Prioritize cooperative aggregation models for Mekong Delta smallholders lacking direct cold chain access. For Investors and Strategic Acquirers: The window for entry favors asset-light platform models with native IoT and blockchain integration over legacy warehouse retrofitting plays. Long-term viability hinges on certification harmonization capabilities across ASEAN Economic Community frameworks and bilateral Chinese protocols. Watch for divergence between ASEAN phytosanitary timelines and unilateral EU due diligence requirements as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Infrastructure Extension | Pharmaceutical-grade temperature systems capture premium durian and mangosteen export corridors from Thailand's eastern provinces. |
| Blockchain Traceability Integration | Distributed ledger platforms compress inspection times at Thai-Chinese border checkpoints for supermarket-bound shipments. |
| Solar-Powered Reefer Deployment | Photovoltaic-assisted cooling cuts generator dependency at remote Indonesian plantation pickup points lacking grid connectivity. |
| Myanmar Corridor Development | First-mover positioning in cross-border road and cold storage infrastructure as bilateral trade normalization proceeds. |
| Third-Party Auditor Embedding | Farm-gate inspection replaces terminal-only checkpoints under tightening Vietnam Plant Protection Department protocols. |
Research Methodology
Document review covered customs and trade databases, ASEAN Economic Community regulatory filings, and EU Green Deal implementation guidance, complemented by interviews with cold chain operations directors, plantation logistics managers, and Japanese supermarket procurement leads. Secondary sources included Vietnam's Plant Protection Department announcements, Thailand's Ministry of Agriculture bilateral protocol documents, and Indonesian port authority capacity disclosures. Bottom-up service provider revenue estimates were triangulated against top-down export flow analysis.
Market size outputs trace to modeled service type splits across transport, cold chain, warehousing, and freight forwarding, with technology adoption curves for IoT and blockchain systems calibrated against insurance claim reduction data. Segmentation dimensions spanned service tier, end-user scale, technology deployment depth, and packaging format. CAGRs derive from export volume projections against infrastructure investment pipelines, with phytosanitary harmonization timelines and Chinese import protocol adjustments as key forecast inputs.
Diesel price volatility, EU deforestation regulation enforcement timing, and reefer technician skill concentration in Bangkok and Singapore are the dominant revision risks to infrastructure deployment assumptions. Forecasts reflect documented base-case phytosanitary convergence and bilateral trade normalization trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Liquid-Cooled Heat Sink Market
Others
Vegetable Carbon Market
Others
United States Smart Homes Market
Others
Belt Press Filter Market
Others
Global Personal Care Packaging Market
Others
Global Aircraft Lighting Systems Market
Others
LED Packaging Market
Others
Global Thermally Conductive Grease Market
Others
Convenience Stores Market
Others
Australia Content Services Platform Market
Others
Subtilisin Market
Others
Fresh Pears Market
Others
5G Tester Market
Others
Industrial Wearable Devices Market
Others
Traditional PC Market
Others
Agitation System Market