
 Latin America Automotive HVAC Market | 2026-2036
Latin America Automotive HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Automotive HVAC Market Foresight
Aftermarket service revenue is reshaping margin distribution across the Latin America Automotive HVAC value chain as thermal system complexity extends component lifecycles. DENSO Corp. leverages its compressor manufacturing scale to anchor supply relationships with major vehicle assemblers in Mexico. Valeo SA competes through technology leadership in electronic control modules for electric vehicle climate systems. Hanon Systems specializes in integrated heating and cooling modules that reduce assembly complexity for OEM platforms.
Automotive HVAC encompasses the thermal regulation systems responsible for cabin temperature control, air quality management, and defrosting operations, typically integrating refrigerant loops, heat exchangers, blower motors, and electronic control units operating between 12V and 48V architectures depending on vehicle electrification level. These systems serve the essential commercial purpose of occupant comfort, battery thermal protection, and regulatory compliance with cabin air quality mandates. Compressors and electronic control technologies command premium positioning as electrification raises performance requirements, while mechanical control systems face structural decline across passenger vehicle platforms. Smart technology integration represents the fastest-growing technology dimension as OEMs demand predictive climate algorithms and over-the-air calibration capabilities.
Brazil's PROCONVE program and Mexico's NOM environmental standards shape refrigerant specifications and energy efficiency thresholds for HVAC systems sold across the region. ANVISA in Brazil and COFEPRIS in Mexico additionally regulate cabin air filtration and antimicrobial surface requirements for consumer health protection. Stakeholders must monitor regulatory divergence between Mercosur and USMCA-aligned technical standards as electrification timelines accelerate thermal system redesign cycles.
Market Dynamics
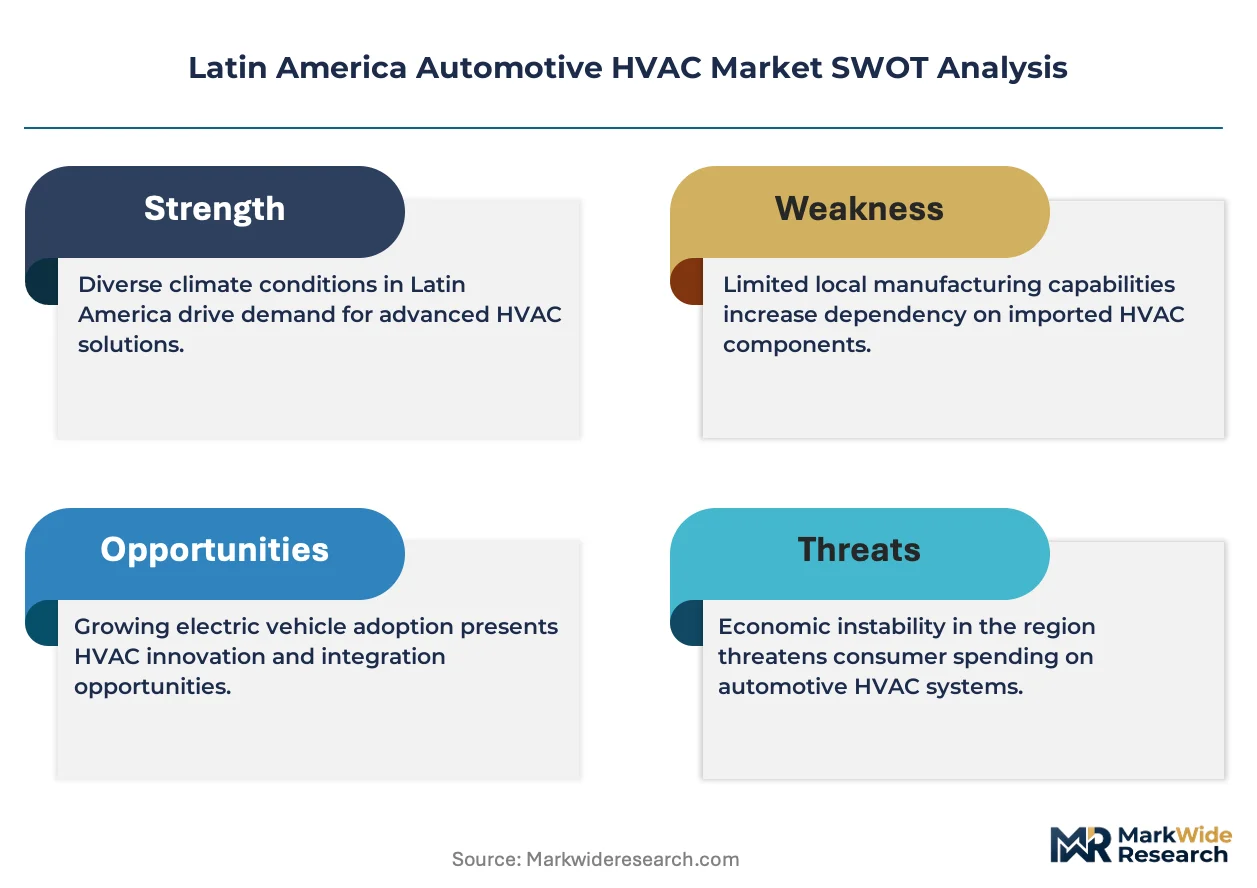
PROCONVE standards in Brazil and NOM environmental regulations in Mexico are forcing synchronous redesigns of refrigerant architectures and compressor efficiency curves across the Latin America Automotive HVAC supply base. Tier-1 suppliers must now certify systems for dual compliance regimes while scaling thermal management platforms for battery-electric vehicle programs.
Growth Catalysts
- PROCONVE L7 Phase-In:Brazil's emission control program mandates R-1234yf refrigerant adoption, compelling OEMs to procure next-generation climate systems with lower global warming potential. Compressor manufacturers are retooling São Paulo facilities to meet the specification.
- Electric Vehicle Assembly Concentration:Battery-electric platforms from Querétaro to São Paulo require integrated thermal management combining cabin HVAC with battery cooling loops. This convergence doubles component value per vehicle.
- USMCA Rules of Origin:Regional content requirements for automotive trade are pulling HVAC system sourcing into Mexico and away from Asian suppliers. Assembly plants in Guanajuato and Puebla are qualifying local compressor production.
Market Restraints
- Copper and Aluminum Price Volatility:Heat exchanger materials face commodity swings that compress margin visibility for Mexican radiator manufacturers. Input cost hedging remains underdeveloped across regional tier-2 suppliers.
- Single-Source Compressor Dependence:High-efficiency electric compressor supply concentrates among three global manufacturers with limited Latin American captive production. OEMs face allocation risk during demand surges.
- Legacy 12V Architecture Persistence:Entry-level vehicle segments in Argentina and Colombia continue specifying mechanical HVAC controls. Electrified climate platforms face delayed penetration in price-sensitive configurations.
Strategic Opportunities
- Colombian Andean Corridor:Bogotá's altitude-driven thermal load requirements create specialized demand for high-capacity HVAC systems. No regional supplier currently dominates this specification niche.
- Refrigerant Recovery Infrastructure:PROCONVE and NOM compliance creates service revenue pools in refrigerant reclamation and compressor retrofit. Independent service networks in Monterrey and Curitiba are consolidating this capability.
- 48V Mild-Hybrid Convergence:Belt-driven electric compressors paired with 48V electrical architectures enable thermal management without full battery-electric redesign. Brazilian flex-fuel platforms are piloting this intermediate specification.
Industry Challenges
- Thermal System Integration Engineering:Battery-electric platforms demand HVAC engineers fluent in both refrigerant thermodynamics and power electronics cooling. Talent scarcity in Guadalajara and Campinas engineering clusters extends development timelines.
- Dual Certification Parallel Tracks:Suppliers must validate identical hardware against PROCONVE protocols in Brazil and NOM test sequences in Mexico. Testing redundancy adds six to nine months to platform launches.
- Aftermarket Diagnostic Complexity:Electronic control modules with encrypted calibration data restrict independent service access. Repair channel conflicts between OEM-authorized and independent shops intensify in São Paulo metropolitan service areas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Automotive HVAC Market |
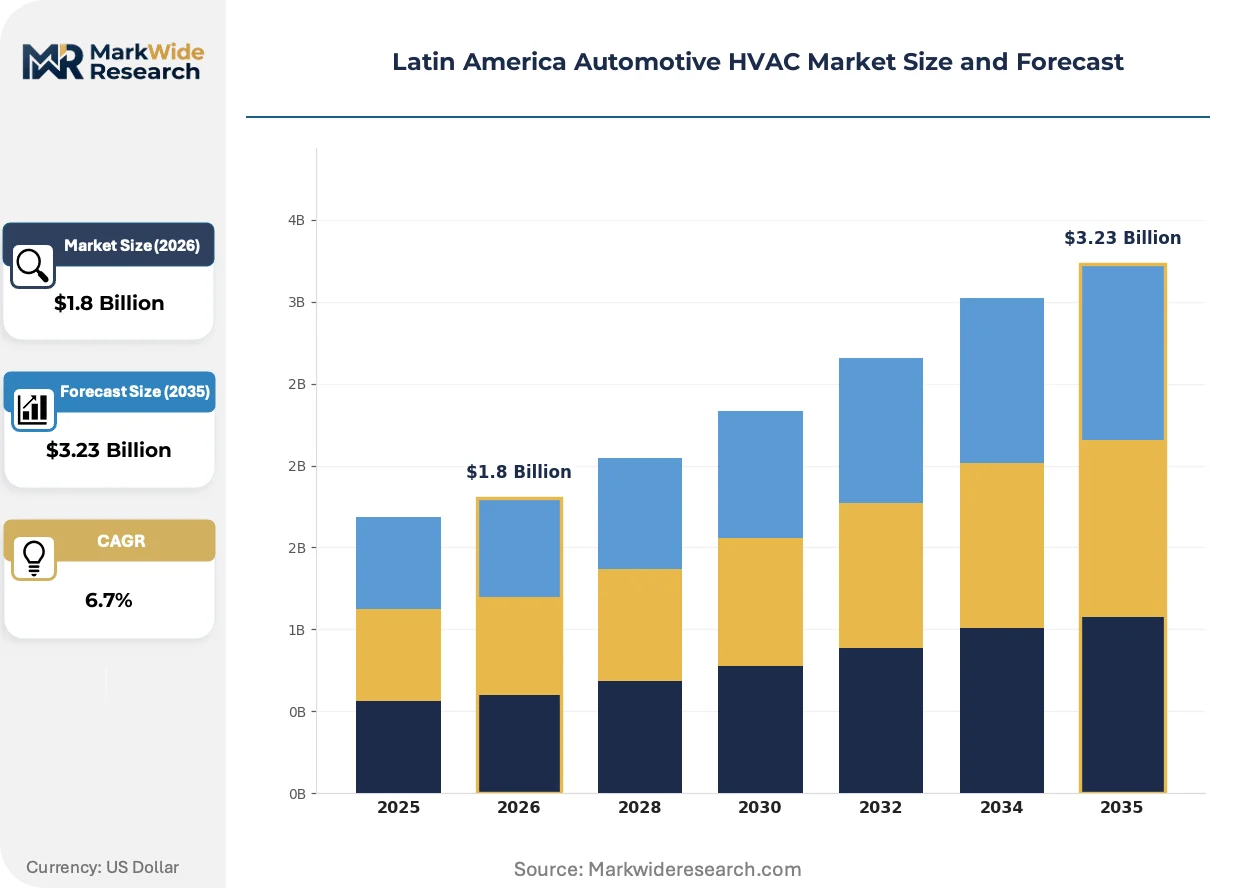
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heating Units, Air Conditioning Units, Ventilation Fans, Compressors Technology: Electronic Control, Mechanical Control, Hybrid Systems, Smart Technology End User: OEMs, Aftermarket Providers, Dealerships, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles |
| Companies Covered | DENSO Corp., Continental AG, Hanon Systems, Valeo SA, MAHLE GmbH, Sanden Corp., Marelli Holdings Co. Ltd., BorgWarner Inc., ZF Friedrichshafen AG, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Automotive HVAC Market Shifts & Advancements
Thermal management architectures are converging cabin comfort and battery conditioning into unified control systems. This integration is compressing supplier tiers and redrawing competitive boundaries across Latin American automotive manufacturing clusters.
Heat pump technology is migrating from premium European platforms to mass-market electric vehicles assembled in Mexico. The system captures ambient thermal energy for cabin heating, reducing battery drain by forty to sixty percent versus resistive heating. Brazilian OEMs are qualifying heat pump variants for tropical humidity conditions, adapting European designs for PROCONVE energy efficiency testing protocols.
NOM-052-SEMARNAT in Mexico and PROCONVE's refrigerant specifications are synchronizing around Kigali Amendment phase-down schedules for hydrofluorocarbons. Equipment manufacturers must now certify service tools and recovery systems for R-1234yf handling. The regulatory alignment is forcing distributor consolidation in border regions serving both regulatory jurisdictions.
Fleet operators in São Paulo and Mexico City are unbundling HVAC maintenance from comprehensive service contracts. Large ride-hail and logistics fleets now contract directly with compressor remanufacturers for component-level exchange programs. This procurement disintermediation bypasses traditional dealer service networks and compresses aftermarket margin pools for incumbent distributors.
Latin America Automotive HVAC Market Segmentation
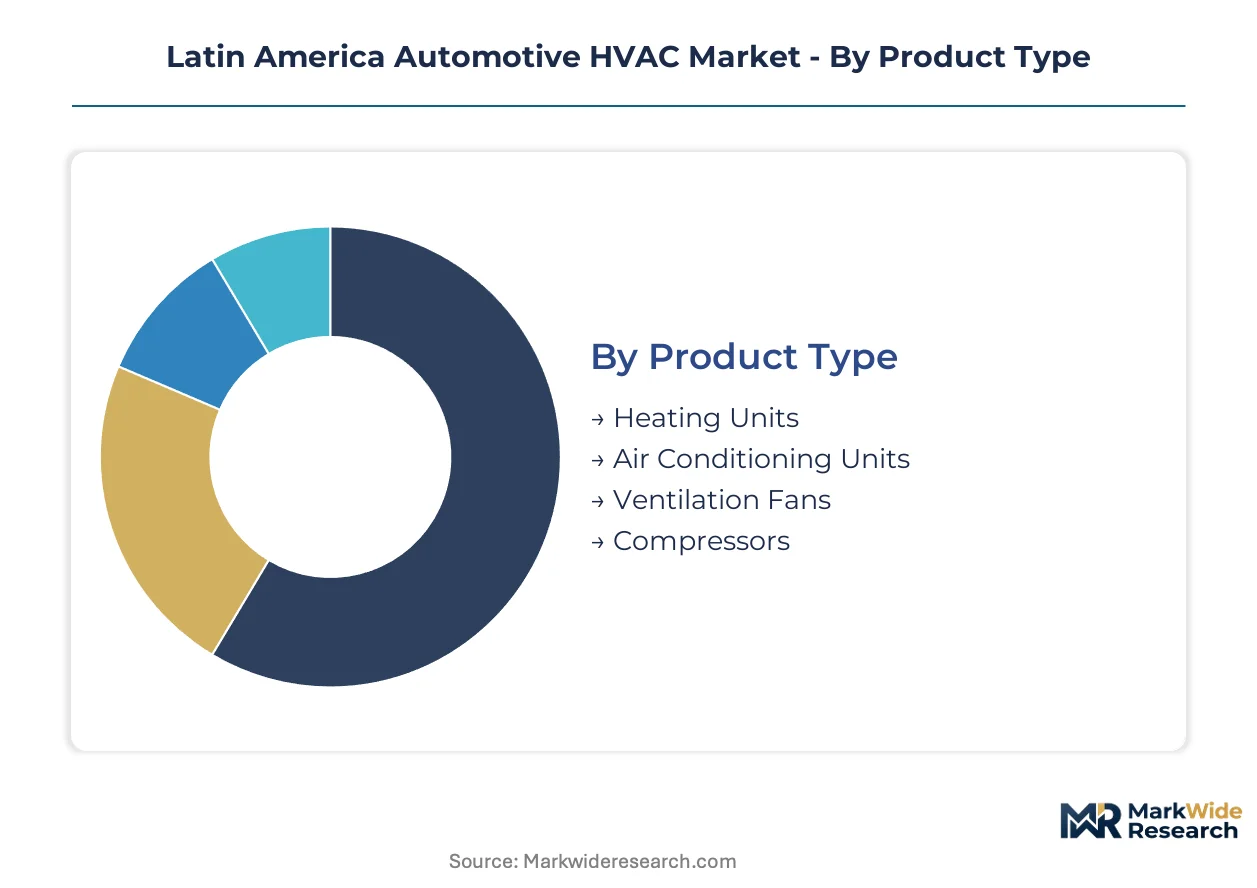
Segmentation in the Latin America Automotive HVAC market reveals how thermal system procurement diverges between electrified platforms and legacy internal combustion architectures. Understanding these splits enables suppliers to align R&D spending with the technology trajectories that PROCONVE and NOM regulations are accelerating.
Product Type:
Replacement cycles vary dramatically across product categories, with consumable components turning over fastest and capital-intensive systems anchoring long-term supplier relationships.
- Compressors:High-efficiency electric compressors integrate refrigerant compression with variable-speed motor control for battery-electric thermal management. Demand concentrates in Querétaro and São Paulo assembly corridors where OEMs source integrated compressor-inverter modules for new electric vehicle platforms.
- Air Conditioning Units:Complete packaged systems combine evaporator, condenser, and expansion valve assemblies into platform-specific modules. Brazilian OEMs specify these for flex-fuel vehicles under PROCONVE L7 efficiency testing, driving specification changes in Campinas supplier parks.
- Heating Units:Resistive and heat pump-based cabin heating modules for electric vehicle architectures.
- Ventilation Fans:Blower motors and ducting assemblies for cabin air distribution and filtration.
Compressors dominate installed base value. Air conditioning units are where expansion concentrates as platform electrification accelerates.
Technology:
Cost tiers separate legacy mechanical architectures from premium electronic and smart systems, with hybrid configurations bridging the gap in price-sensitive segments.
- Smart Technology:Predictive climate algorithms, occupant detection sensors, and over-the-air calibration capabilities integrated into vehicle domain controllers. Mexican OEMs pilot these systems in luxury electric vehicles assembled in Puebla, though tropical humidity adaptation remains an engineering priority.
- Electronic Control:Microprocessor-driven thermal management with CAN bus integration for precision temperature and energy optimization. Brazilian assemblers specify these for mid-range passenger vehicles in São Paulo state to meet PROCONVE energy consumption targets.
- Hybrid Systems:Combined mechanical-electronic architectures for transitional vehicle platforms.
- Mechanical Control:Cable-actuated temperature and mode doors for entry-level vehicle segments.
Electronic control dominates installed base. Smart technology is climbing the fastest as OEMs differentiate electric vehicle cabins.
End User:
Customer type determines contract structure, with vehicle assemblers driving volume and aftermarket providers capturing service lifecycle revenue.
- Vehicle Assemblers:Direct procurement of complete thermal systems for new vehicle production, typically through platform-specific supply agreements. Mexican electric vehicle manufacturers in Guanajuato qualify local compressor production to satisfy USMCA regional content thresholds.
- OEMs:Brand-holding manufacturers specifying thermal system performance targets and certification requirements.
- Aftermarket Providers:Independent distributors and service networks for replacement components and retrofit.
- Dealerships:Authorized service channels for warranty repairs and OEM-branded maintenance.
Vehicle assemblers dominate installed base. Aftermarket providers are gaining share fastest as fleet operators unbundle service contracts.
Application:
Application segments split by thermal load intensity and regulatory scrutiny, with electric vehicles demanding the most complex integrated solutions.
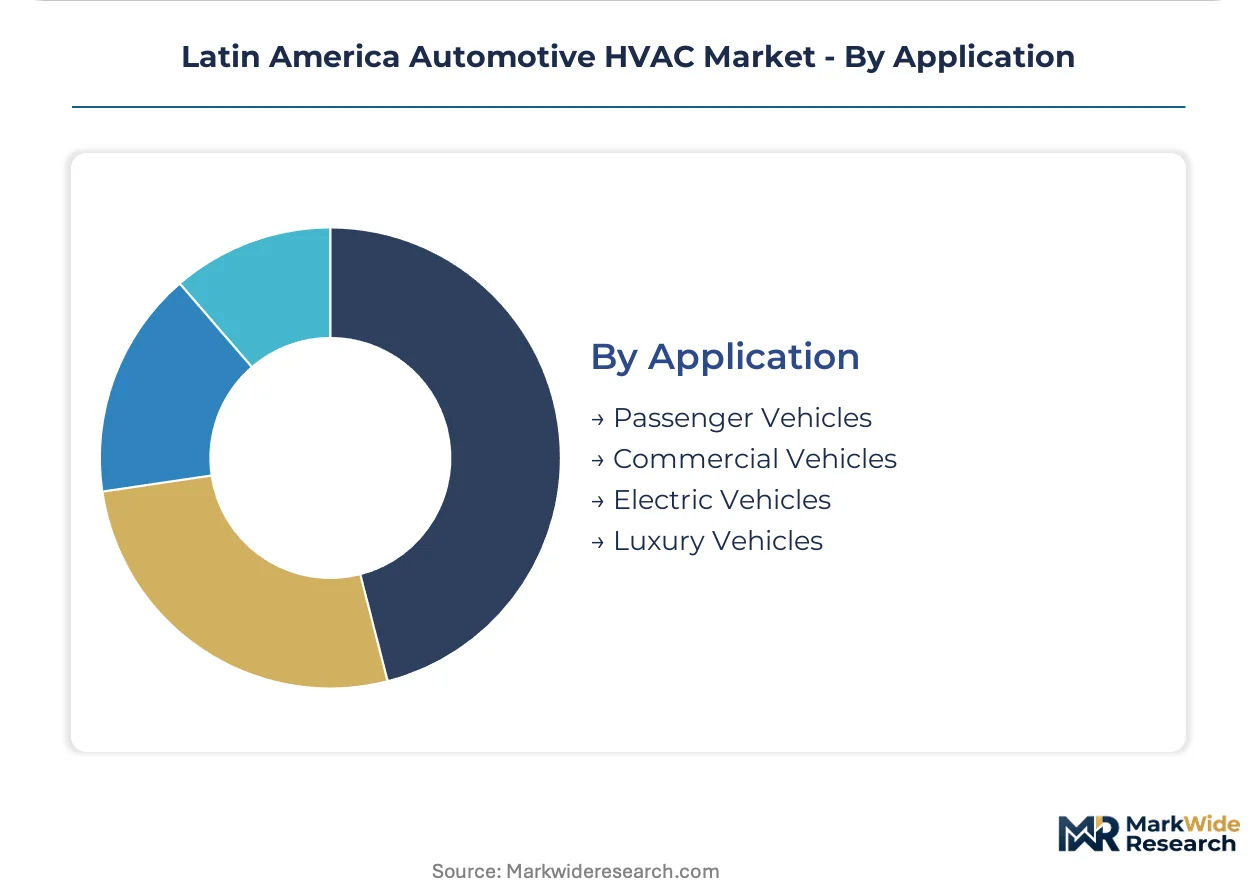
- Electric Vehicles:Unified cabin and battery thermal management systems with heat pump capability and refrigerant-based cooling loops. Mexican assembly plants in Querétaro engineer these for export to USMCA markets, doubling component count per vehicle versus conventional HVAC.
- Passenger Vehicles:Mass-market climate systems for internal combustion and hybrid platforms across Brazilian and Mexican production. PROCONVE L7 refrigerant specifications are forcing synchronous redesigns of compressor architectures for São Paulo-based assemblers.
- Commercial Vehicles:Heavy-duty HVAC for trucks and buses with extended duty cycles.
- Luxury Vehicles:Multi-zone climate control with advanced air quality and comfort features.
Passenger vehicles dominate installed base. Electric vehicles are where expansion concentrates as battery platform assembly scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compressor manufacturing and thermal system assembly concentrate in industrial corridors spanning Brazil and Mexico, with tier-1 suppliers qualifying regional production to satisfy USMCA content rules and PROCONVE certification requirements. Argentina and Colombia represent secondary demand centers where altitude and climate conditions create specialized specification niches.
Brazil
Electric vehicle assembly in São Paulo state drives integrated thermal management procurement as OEMs retool Campinas supplier parks for battery-electric platforms. ANVISA cabin air quality mandates and PROCONVE L7 refrigerant specifications force synchronous redesigns of compressor architectures. Curitiba engineering clusters specialize in heat exchanger manufacturing for tropical humidity conditions.
Mexico
Querétaro and Guanajuato assembly corridors anchor battery-electric vehicle production for USMCA export markets, doubling HVAC component value per vehicle versus conventional platforms. NOM environmental standards align with PROCONVE phase-down schedules for hydrofluorocarbon refrigerants. Puebla supplier parks qualify heat pump variants for regional climate adaptation.
Argentina
Legacy 12V mechanical HVAC architectures persist in entry-level vehicle segments across Córdoba and Buenos Aires production centers, delaying electrified climate platform penetration. The country's national environmental regulator enforces refrigerant handling protocols for service networks. Rosario aftermarket distributors consolidate compressor remanufacturing capabilities for regional fleet operators.
Colombia
Bogotá's altitude-driven thermal load requirements create specialized demand for high-capacity HVAC systems that no regional supplier currently dominates. The national environmental authority oversees refrigerant recovery infrastructure development in Andean corridor service networks. Medellín independent workshops expand component-level exchange programs bypassing traditional dealer channels.
Chile
Santiago metropolitan fleet operators unbundle HVAC maintenance from comprehensive service contracts, creating direct procurement relationships with thermal system specialists. The country's national automotive regulator monitors compliance with international refrigerant phase-down commitments. Valparaíso port logistics support import distribution for replacement components serving Andean markets.
Latin America Automotive HVAC Market Competitive Landscape
Integrated system architects and component specialists split the market between platform-level thermal management contracts and discrete compressor or control module supply. The vendor base concentrates among Japanese and European multinationals with captive Latin American production, while Korean specialists occupy intermediate positions in heating and cooling module integration. Three strategic archetypes dominate: full-system integrators delivering complete HVAC platforms, compressor manufacturers leveraging scale economies, and control technology providers embedding software capabilities. Capacity expansion in São Paulo and Querétaro supplier parks represents the dominant competitive move, followed by strategic partnerships between tier-1 suppliers and battery-electric vehicle assemblers for co-development of unified thermal architectures.
Within the full-system integrator tier, DENSO Corp. and Valeo SA exemplify archetypes spanning compressor manufacturing scale and electronic control leadership respectively. Hanon Systems occupies a position specializing in integrated heating and cooling modules that reduce assembly complexity for OEM platforms. These three anchors represent distinct strategic postures: scale-driven component supply, technology-forward control systems, and module-level integration expertise. Continental AG, MAHLE GmbH, and BorgWarner Inc. sit within adjacent competitive spaces, with Marelli Holdings Co. Ltd. and ZF Friedrichshafen AG representing diversified automotive suppliers extending thermal management capabilities through portfolio breadth rather than dedicated HVAC focus.
| Leading Market Players |
|---|
| DENSO Corp. |
| Continental AG |
| Hanon Systems |
| Valeo SA |
| MAHLE GmbH |
| Sanden Corp. |
| Marelli Holdings Co. Ltd. |
| BorgWarner Inc. |
| ZF Friedrichshafen AG |
| Others |
Supply & Pricing Matrix
Undercapacity in São Paulo compressor manufacturing facilities is forcing tier-1 suppliers to prioritize OEM platform contracts over aftermarket allocation, tightening availability for independent service networks and compressing margin visibility across the Latin America Automotive HVAC value chain. This utilization squeeze concentrates pricing power with DENSO Corp. and Valeo SA while Mexican assembly plants absorb premium positioning for USMCA-compliant thermal systems.
Pricing Analysis
Aftermarket service revenue tiers—spanning component exchange programs, refrigerant recovery contracts, and extended thermal system warranties—drive lifetime value capture across the Latin America Automotive HVAC market. Three-tier pricing structure across premium, standard, and economy levels separates heat pump-integrated electric vehicle modules from flex-fuel air conditioning units and legacy mechanical controls. Cost compression in standard-tier compressor assemblies is intensifying because Brazilian OEMs negotiate volume consolidation for PROCONVE L7 platforms. Fleet operators exhibit highest price sensitivity, while luxury electric vehicle assemblers in Querétaro absorb premium positioning for unified cabin-battery thermal management.
Supply Chain Analysis
Tariff exposure between Asian component sources and Latin American assembly plants dominates supply chain risk calculus for heat exchanger and electronic control module procurement. Manufacturing concentrates in Mexico, Brazil, and South Korea, with Mexican facilities qualifying regional content for USMCA markets and Brazilian plants serving Mercosur demand. Raw material dependencies center on copper tubing for condensers, aluminum fin stock for evaporators, and rare-earth magnets for electric compressor motors. Single-source vulnerability for high-efficiency compressor inverter modules persists because three global manufacturers control Latin American allocation. Distribution runs through tier-1 supplier direct contracts with OEM assembly plants, bypassing traditional wholesale channels for original equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America Automotive HVAC market sits at a platform-economics inflection where battery-electric vehicle thermal architectures are converging cabin comfort and battery conditioning into unified control systems, forcing supplier consolidation around software-defined climate capabilities and over-the-air calibration interoperability.
For Market Incumbents: Entrench platform-level supply relationships by qualifying São Paulo and Querétaro production for PROCONVE-NOM dual certification, eliminating six-to-nine-month testing redundancy that threatens contract renewals. Deepen upstream control over heat exchanger copper-aluminum supply through captive tolling arrangements with Mexican smelters, defending margin position against commodity volatility that compresses tier-2 radiator manufacturers. Prioritize R&D investment in tropical humidity-adapted heat pump variants to maintain specification leadership as Brazilian OEMs pilot European-derived designs. For New Entrants and Emerging Players: Build out refrigerant recovery and compressor remanufacturing capabilities in Bogotá and Medellín, capturing unmet demand from altitude-driven thermal load specifications that no regional supplier currently dominates. Target Colombian Andean corridor fleet operators with component-level exchange programs that bypass traditional dealer service networks, exploiting procurement disintermediation trends among ride-hail and logistics operators. Deploy direct contracting models with Santiago metropolitan fleet managers to unbundle HVAC maintenance from comprehensive service agreements. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because PROCONVE L7 and NOM environmental standards are synchronizing refrigerant phase-down schedules, forcing distributor consolidation in border regions and creating acquisition targets among independent service networks lacking R-1234yf certification infrastructure. Focus on tier-2 thermal management engineering boutiques in Guadalajara and Campinas with battery-electric platform fluency, where talent scarcity extends development timelines and inflates valuation multiples. Monitor heat pump adoption rates in Puebla-assembled mass-market electric vehicles as the inflection signal for technology migration from premium European platforms.| Strategic Initiative | Industry Significance |
|---|---|
| PROCONVE-NOM Dual Certification | Eliminates testing redundancy for suppliers serving Brazil-Mexico assembly corridors under divergent regulatory protocols. |
| Heat Pump Tropical Adaptation | Enables specification capture as Brazilian OEMs qualify European-derived designs for humidity-intensive PROCONVE energy efficiency testing. |
| Refrigerant Recovery Infrastructure | Creates service revenue pools in Monterrey and Curitiba as compliance mandates consolidate independent network capabilities. |
| 48V Mild-Hybrid Compressor Piloting | Positions belt-driven electric architectures as intermediate specification for Brazilian flex-fuel platforms delaying full electrification. |
| Direct Fleet Contracting | Bypasses dealer service networks as São Paulo and Mexico City operators unbundle HVAC maintenance from comprehensive agreements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, PROCONVE certification filings, and NOM environmental compliance records. Primary interviews engaged OEM platform engineers, tier-1 supplier procurement directors, aftermarket distributor operations heads, and thermal management R&D leads across São Paulo, Querétaro, and Guadalajara engineering clusters. Bottom-up triangulation against top-down trade flow analysis validates component-level demand estimates across compressor, heat exchanger, and electronic control module categories.
Forecast inputs incorporate vehicle electrification adoption curves, PROCONVE L7 phase-in schedules, and USMCA regional content threshold evolution across the projection horizon. Segmentation dimensions span propulsion architecture, vehicle class, content per vehicle, and regional production cluster. CAGRs derive from modeled unit shipments against average selling price trajectories, with thermal management complexity coefficients applied to battery-electric platform forecasts. Industry-specific inputs include heat pump penetration assumptions and refrigerant transition timelines aligned with Kigali Amendment commitments.
Sensitivities concentrate around copper-aluminum commodity volatility, single-source compressor allocation constraints, and regulatory divergence between Mercosur and USMCA technical standards. Forecasts embed assumptions regarding OEM platform consolidation and tier-1 supplier captive production expansion that operating reality may revise. Continuous validation against vehicle assembly data and thermal system procurement announcements is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Animal Feed Alternative Protein Market
Others
Hypermarket Market
Others
Military Wearable Market
Others
Security Bottles Market
Others
APAC Machine Vision Systems Market
Others
Latin America 3D Printing Construction Market
Others
Smart Home Service Market
Others
Global Digital Market
Others
High-End Servers Market
Others
Internet of Things Testing Market
Others
DIY Smart Home Market
Others
Pollen Allergy Market
Others
Bio-Based Leather Market
Others
HPHT Diamond Cubic Press Market
Others
Global Multi-Access Edge Computing Market
Others
Aboveground Storage Tanks Market