
 5G Edge Computing Market | 2026-2036
5G Edge Computing Market Size, Share, and Industry Trends Forecast 2026-2036
5G Edge Computing Market Analytics
Edge infrastructure engineering talent is bifurcating between hyperscale cloud operators and telecom-native integrators, creating two distinct labor pools with incompatible skill profiles. Amazon Web Services leverages its cloud-native developer ecosystem to extend container orchestration tools into cellular edge environments. Nokia Corporation anchors its position through deep radio access network integration and carrier-grade reliability standards. Ericsson competes by specializing in network slicing APIs that bridge 5G core functions with distributed compute nodes.
5G Edge Computing denotes distributed data processing architectures that position compute, storage, and analytics resources within one to ten milliseconds of end devices via 5G radio interfaces, typically operating at sub-6 GHz and millimeter-wave spectrum bands with latency budgets under ten milliseconds for industrial control applications. These systems serve autonomous robotics, immersive media, and critical infrastructure monitoring where centralized cloud latency violates operational constraints. Smart Manufacturing applications command the deepest deployment commitments as automotive and semiconductor fabs install on-premises edge clusters for real-time defect detection. IoT Services represent the fastest-expanding segment as utility and logistics operators deploy massive sensor grids requiring localized inference rather than backhaul to regional clouds.
The Federal Communications Commission in the United States governs spectrum allocation and edge facility siting rules that determine where micro data centers may attach to cell towers. The European Telecommunications Standards Institute and national regulators under the EU AI Act mandate algorithmic transparency for edge-deployed inference engines in healthcare and transport applications. China's Ministry of Industry and Information Technology enforces GB standards for edge node interoperability within domestic 5G standalone networks. Stakeholders must monitor evolving spectrum auction designs and data residency requirements that will determine which deployment models—public cloud, private cloud, or hybrid—gain regulatory preference in each major jurisdiction.
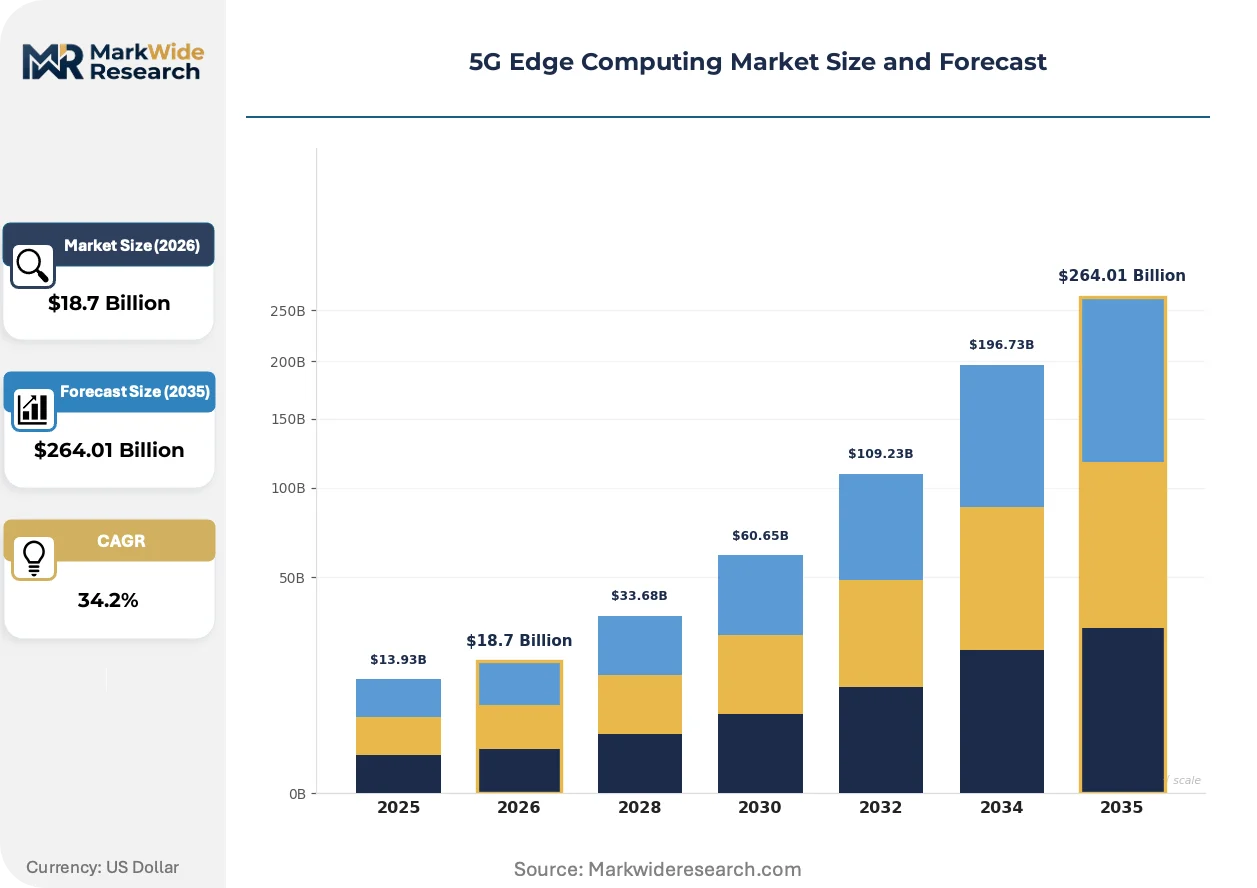
Market Dynamics
Edge infrastructure deployment is fragmenting between hyperscale cloud extensions and telecom-native architectures, creating competing technical standards that force buyers into premature technology commitments.
Growth Catalysts
- EU AI Act compliance mandates:Healthcare and transport operators in Germany and France must deploy localized inference engines, accelerating private edge node procurement for algorithmic transparency.
- Millimeter-wave spectrum availability:The FCC's recent mid-band auctions enable sub-ten-millisecond latency for industrial robotics in Michigan and Texas automotive corridors.
- Predictive maintenance adoption:Semiconductor fabs in South Korea and Japan are installing on-premises edge clusters for real-time defect detection, bypassing cloud backhaul entirely.
Market Restraints
- Radio unit supply concentration:Baseband processor and massive MIMO antenna sourcing depends on a narrow supplier base concentrated in East Asian manufacturing zones.
- Site acquisition costs:Cell tower attachment fees and utility interconnection charges for micro data centers consume disproportionate capex in dense urban deployments.
- Interoperability friction:GB standards enforced by China's MIIT create protocol incompatibilities with ETSI frameworks, complicating multi-vendor edge orchestration.
Strategic Opportunities
- India manufacturing corridors:PLI scheme incentives for electronics and automotive production are creating first-mover advantage for edge infrastructure providers establishing localized compute nodes.
- Immersive media convergence:5G edge nodes combined with low-latency video encoding are enabling stadium-scale augmented reality experiences previously impossible on centralized clouds.
- Private network API monetization:Network slicing interfaces that bridge 5G core functions with distributed compute represent untapped revenue streams for systems integrators.
Industry Challenges
- Container orchestration skill scarcity:Kubernetes specialization for cellular edge environments remains concentrated among hyperscale cloud operators, leaving telecom integrators with incompatible talent pipelines.
- Carrier-grade certification timelines:NEBS and ETSI reliability standards require eighteen-to-twenty-four-month validation cycles that delay commercial deployment of new edge hardware platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Edge Computing Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $264.01 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud Application: IoT Services, Smart Manufacturing, Augmented Reality, Real-Time Analytics End User: Telecommunications, Automotive, Healthcare, Retail Service Type: Infrastructure Management, Network Security, Data Storage, Monitoring Services |
| Companies Covered | Amazon Web Services, Huawei Technologies, Cisco Systems, Microsoft Corporation, Hewlett Packard Enterprise, Nokia Corporation, Ericsson, IBM Corporation, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Edge Computing Market Evolving Landscape
Containerized edge orchestration is fragmenting legacy network management paradigms, forcing infrastructure buyers to choose between cloud-native developer ecosystems and telecom-operational reliability cultures.
Software-defined radio access networks are fragmenting proprietary hardware dependencies, allowing automotive and semiconductor manufacturers to deploy vendor-neutral edge nodes that decouple baseband processing from radio units. German automotive clusters and Japanese electronics fabs are adopting open RAN interfaces fastest, compressing incumbent equipment margins while accelerating feature deployment cycles.
The EU AI Act's algorithmic transparency requirements are mandating explainable inference engines for healthcare and transport edge deployments, compelling operators to abandon black-box machine learning models. ETSI standards bodies are drafting technical specifications for auditable edge AI, with French and German regulators already enforcing documentation requirements that add six-to-nine-month compliance overhead.
Buyers are consolidating vendor relationships around integrated edge-to-cloud management platforms, displacing point-solution procurement that previously separated connectivity from compute sourcing. Utility and logistics operators in South Korea and Texas are demanding unified SLA frameworks spanning radio access through container orchestration, compressing supplier margins while raising switching costs for established relationships.
5G Edge Computing Market Segmentation
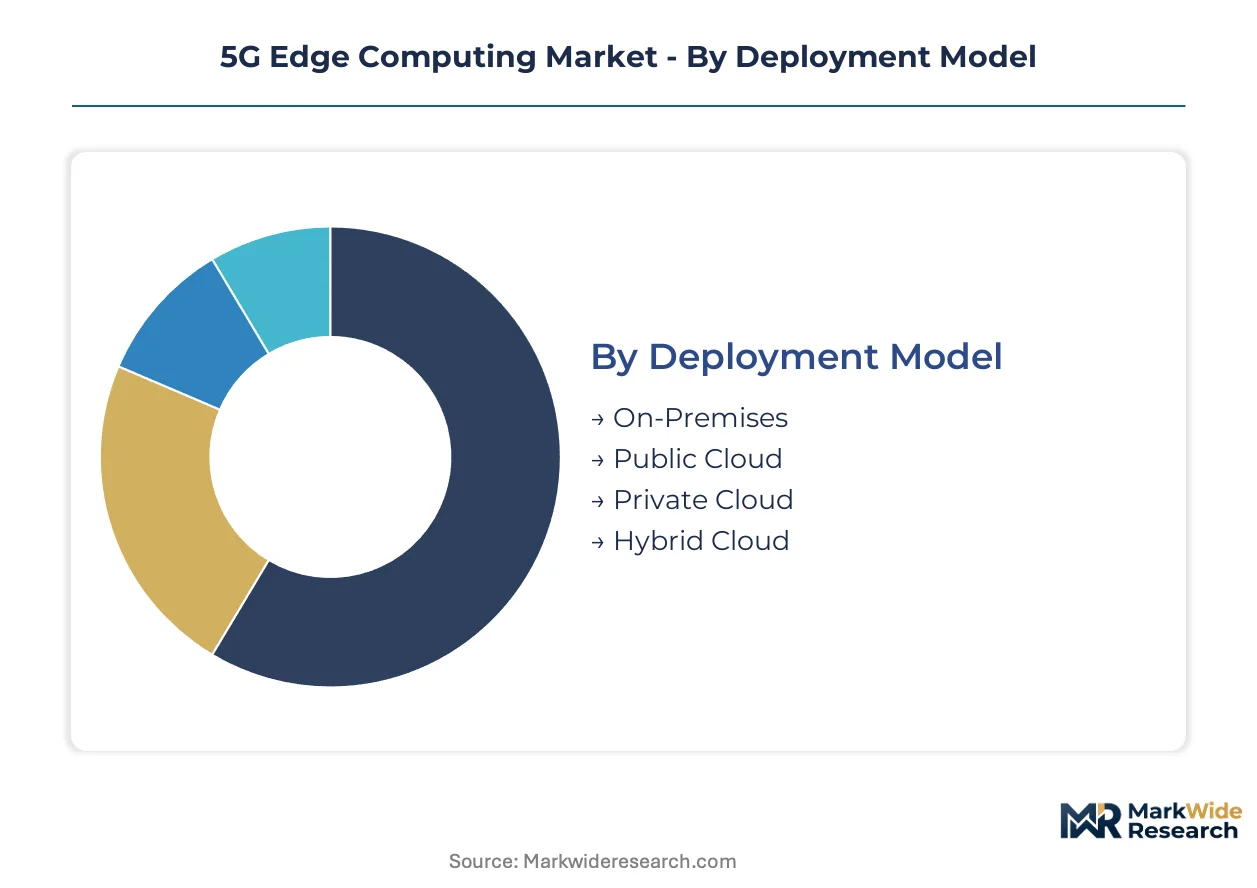
Segmentation in 5G edge computing determines procurement pathways and vendor selection criteria across incompatible technical standards. Buyers face irreversible commitments between hyperscale cloud extensions and telecom-native architectures that reshape long-term operational capabilities.
Deployment Model:
Public cloud edge extensions face substitution pressure from private cloud alternatives as data sovereignty mandates harden in Germany, France, and South Korea.
- On-Premises:Fully captive infrastructure deployed within semiconductor fabs and automotive assembly plants where sub-ten-millisecond latency is non-negotiable. South Korean electronics manufacturers and German automotive clusters are bypassing cloud backhaul entirely for real-time defect detection systems.
- Public Cloud:Hyperscale operators extend container orchestration into cellular edge environments via AWS Wavelength and comparable platforms. Michigan and Texas automotive corridors leverage these deployments for industrial robotics where spectrum auctions enabled mid-band availability.
- Private Cloud:Carrier-grade edge nodes operating under single-tenant contracts satisfy EU AI Act algorithmic transparency requirements. French healthcare operators and German transport authorities procure these for localized inference engines.
- Hybrid Cloud:Workload portability across on-premises and cloud-native edge nodes demands unified orchestration layers. Japanese electronics fabs and Texas utility operators are consolidating vendor relationships around integrated management platforms.
On-Premises retains volume leadership; Hybrid Cloud holds the steepest expansion curve.
Application:
Cost tier differentiation separates capital-intensive manufacturing deployments from sensor-grid utilities with lower per-node investment thresholds.
- Smart Manufacturing:Real-time defect detection and predictive maintenance systems command the deepest deployment commitments. Automotive and semiconductor fabs in South Korea and Japan install dedicated edge clusters that compress quality control cycles.
- IoT Services:Massive sensor grids for utility and logistics operators require localized inference rather than regional cloud backhaul. South Korean smart city deployments and Texas grid operators are expanding these networks fastest.
- Augmented Reality:Stadium-scale immersive media experiences depend on low-latency video encoding at 5G edge nodes. German sports venues and Japanese entertainment complexes are piloting these applications.
- Real-Time Analytics:Financial trading and critical infrastructure monitoring demand deterministic latency budgets. Frankfurt trading floors and Singapore port authorities deploy these for algorithmic decision-making at the edge.
Smart Manufacturing dominates capital deployment; IoT Services is climbing the fastest.
End User:
Customer type fragmentation creates incompatible procurement cultures between carrier-integrated telecom buyers and vertically integrated industrial operators.
- Telecommunications:Mobile network operators deploy multi-tenant edge nodes to monetize network slicing APIs. German carriers and South Korean operators lead private network provisioning for enterprise clients.
- Automotive:Autonomous robotics and connected vehicle platforms require sub-ten-millisecond control loops. Michigan and Texas manufacturing corridors anchor North American demand for cellular edge infrastructure.
- Healthcare:EU AI Act compliance mandates explainable inference engines for diagnostic imaging and patient monitoring. French and German hospital networks are procuring auditable edge AI systems.
- Retail:Inventory robotics and personalized in-store experiences drive edge node deployment. Japanese convenience chains and South Korean department stores are piloting computer vision at the edge.
Telecommunications captures the largest installed base; Automotive is gaining share fastest.
Service Type:
Maturity gradients separate established infrastructure management offerings from emerging security and monitoring capabilities with shorter track records.
- Infrastructure Management:Container orchestration and hardware lifecycle services constitute the foundational layer. Kubernetes specialization for cellular edge environments remains concentrated among hyperscale cloud operators.
- Network Security:Zero-trust architectures and edge-native threat detection address expanded attack surfaces. ETSI standards bodies are drafting security specifications for distributed compute nodes.
- Data Storage:Tiered persistence from hot NVMe caches to cold object stores supports variable latency requirements. German industrial operators demand data residency guarantees under GDPR and national sovereignty laws.
- Monitoring Services:Observability platforms for distributed edge fleets are displacing point-solution telemetry. South Korean smart city operators and Texas utility providers require unified SLA frameworks spanning radio through compute.
Infrastructure Management maintains revenue concentration; Monitoring Services shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial corridors where EU AI Act compliance premiums apply, while South Korean electronics clusters command volume leverage through captive semiconductor supply. Buyers in Texas and Michigan automotive zones face intermediate cost structures shaped by FCC spectrum auction dynamics.
United States
Michigan and Texas automotive corridors anchor North American demand for sub-ten-millisecond industrial robotics control. The FCC's mid-band spectrum auctions enable private edge deployments that bypass carrier infrastructure entirely. Detroit assembly plants and Austin semiconductor facilities are installing captive edge clusters for real-time quality assurance.
Germany
Automotive clusters in Bavaria and Baden-Württemberg drive private 5G network procurement for predictive maintenance systems. The EU AI Act mandates algorithmic transparency for edge-deployed inference engines in healthcare and transport applications. Stuttgart and Munich manufacturing zones are consolidating vendor relationships around integrated edge-to-cloud management platforms.
Japan
Electronics fabs in the Chubu region and Kansai industrial belt command the deepest on-premises edge commitments for defect detection. METI industrial standards enforce interoperability requirements for edge node deployment within domestic 5G standalone networks. Osaka semiconductor facilities and Nagoya automotive plants are bypassing cloud backhaul for millisecond-critical process control.
South Korea
Smart city deployments in Seoul and Busan-Ulsan corridors expand massive sensor grids requiring localized inference rather than regional cloud backhaul. The MFDS and national data sovereignty frameworks compel healthcare edge localization for diagnostic imaging systems. Samsung Electronics and SK Hynix fabs in Gyeonggi Province anchor private edge infrastructure procurement.
China
MIIT-enforced GB standards for edge node interoperability shape procurement within domestic 5G standalone networks. Yangtze River Delta manufacturing zones and Pearl River Delta electronics clusters deploy localized compute for industrial internet platforms. Shanghai and Shenzhen smart city operators are consolidating around state-directed edge infrastructure specifications.
5G Edge Computing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure where hyperscale cloud operators and telecom-native integrators compete for industrial buyer relationships. The vendor base separates into cloud-native developer ecosystems, carrier-grade reliability specialists, and open RAN hardware neutralists. Strategic moves concentrate on spectrum access partnerships and container orchestration talent acquisition rather than direct product competition.
Within the hyperscale tier, Amazon Web Services and Microsoft Corporation represent cloud-native archetypes extending container orchestration into cellular edge environments. Nokia Corporation and Ericsson exemplify telecom-native positioning through radio access network integration and network slicing API development. Huawei Technologies occupies a distinct geography-tied position serving domestic and aligned-market deployments under MIIT regulatory frameworks.
| Leading Market Players |
|---|
| Amazon Web Services |
| Huawei Technologies |
| Cisco Systems |
| Microsoft Corporation |
| Hewlett Packard Enterprise |
| Nokia Corporation |
| Ericsson |
| IBM Corporation |
| Intel Corporation |
| Others |
Value Network & Pricing Analysis
Hyperscale cloud capex cycles and telecom infrastructure refresh waves create divergent scale economies that compress price floors for standardized edge hardware while inflating premiums for carrier-certified configurations. German automotive buyers and South Korean semiconductor fabs absorb customization premiums for sub-ten-millisecond latency guarantees, whereas Texas utility operators exploit volume leverage through standardized procurement frameworks.
Pricing Analysis
The customization-premium spread separates configured-to-order private edge nodes from standardized public cloud extensions by a factor reflecting certification overhead and radio integration depth. Project-based pricing dominates smart manufacturing deployments where automotive and semiconductor fabs procure captive infrastructure with bespoke latency SLAs, while subscription-tiered models govern hyperscale edge extensions serving industrial robotics in Michigan and Texas corridors. Price differentiation rests on carrier-grade certification status and EU AI Act compliance documentation, with German healthcare operators least price-sensitive due to regulatory mandate premiums and IoT utility grids most sensitive due to sensor-volume scaling economics. Cost compression in standardized hardware tiers is intensifying because open RAN interfaces decouple baseband processors from proprietary radio units.
Supply Chain Analysis
Taiwan Strait transit vulnerability concentrates baseband processor and massive MIMO antenna sourcing within East Asian manufacturing zones that feed global edge infrastructure deployment. Taiwan, South Korea, and Japan anchor semiconductor fabrication for edge compute accelerators, while China dominates printed circuit board assembly and power management component production. Raw material dependencies span gallium nitride substrates for millimeter-wave amplifiers, high-purity silicon for edge AI inference chips, and rare earth elements for radio frequency filtering. Single-source vulnerability in advanced node semiconductor manufacturing threatens delivery timelines for sub-seven-nanometer edge AI processors. Distribution runs through carrier-authorized integrators for telecom-native deployments and hyperscale cloud marketplaces for developer-centric edge extensions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among automotive OEMs and semiconductor fabs that consolidate vendor relationships around unified edge-to-cloud management platforms, compressing supplier margins while raising switching costs for established relationships.
For Market Incumbents: Consolidate around integrated orchestration platforms that span radio access through container management to defend against hyperscale cloud encroachment into telecom-native accounts. Deepen open RAN certification investments to maintain hardware attach rates as Japanese electronics fabs and German automotive clusters adopt vendor-neutral interfaces. Vertical integration into edge AI inference silicon offers margin protection against commoditization of standardized compute nodes. For New Entrants and Emerging Players: Differentiate on network slicing API specialization that bridges 5G core functions with distributed compute for private network monetization. Target India manufacturing corridors where PLI scheme incentives for electronics and automotive production create first-mover advantage for localized edge node deployment. Pursue stadium-scale immersive media pilots in German sports venues and Japanese entertainment complexes as reference architecture for low-latency video encoding at the edge. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among private cloud edge operators serving EU AI Act compliance mandates in French healthcare and German transport applications. Long-term viability favors acquisition targets with carrier-grade certification pipelines and established relationships with South Korean smart city operators or Texas utility providers. Monitor FCC spectrum auction designs and EU data residency enforcement as inflection indicators for deployment model preference shifts between public cloud, private cloud, and hybrid architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Hardware Certification | ETSI interoperability standards enable vendor-neutral procurement by German automotive clusters. |
| Edge AI Inference Silicon Development | Explainable model architectures satisfy EU AI Act algorithmic transparency mandates for healthcare deployment. |
| Network Slicing API Commercialization | Private network monetization creates recurring revenue streams for South Korean mobile operators. |
| Hyperscale-Telecom Partnership Structuring | AWS Wavelength integrations with Verizon anchor industrial robotics control in Michigan automotive corridors. |
| India Manufacturing Corridor Localization | PLI scheme incentives accelerate captive edge infrastructure for electronics and automotive production. |
Research Methodology
The analysis maps public cloud edge extensions, private carrier-grade nodes, on-premises industrial clusters, and hybrid orchestration platforms, each validated through infrastructure procurement officers at automotive OEMs, network planning executives at mobile operators, platform engineers at hyperscale cloud providers, and regulatory affairs leads at edge AI vendors. Primary interview findings triangulate against secondary sources including FCC spectrum auction records, ETSI technical specifications, MIIT GB standards filings, hyperscaler capex disclosures, and industrial automation trade association deployment surveys. Bottom-up unit economics for edge node deployment combine with top-down market sizing across application segments.
Consistency checks validate volume and value outputs against external benchmarks including telecom infrastructure capital expenditure tracking, industrial IoT sensor deployment databases, and cloud edge revenue disclosures by major operators. The analytical framework models deployment model, application vertical, end-user industry, and service type dimensions across the projection horizon. CAGRs derive from segment-level growth rate reconciliation with macroeconomic indicators and technology adoption curves. Forecast inputs incorporate millimeter-wave spectrum availability timelines, EU AI Act compliance cost assumptions, and open RAN interface maturity assessments.
The analysis sits within stated boundaries; outcomes outside sustained mid-band spectrum allocation, stable East Asian semiconductor supply, or continued EU regulatory enforcement would require recalibration. Forecasts reflect documented assumptions regarding latency requirement evolution, container orchestration skill market expansion, and carrier certification timeline compression. Practitioners should keep alternative scenarios live as spectrum auction designs, data sovereignty mandates, and open RAN standardization velocity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Advanced Fiber-Based Gasket Market
Others
Cashew Kernel Market
Others
Space Cables Market
Others
Air Separation Plant Market
Others
Mexico Retail Market
Others
Electric Chainsaw Market
Others
United States Air Furnaces Market
Others
India Home Automation Market
Others
Calendered Polyvinyl Chloride Flexible Films Market
Others
Global Molded Plastics Market
Others
One-Way Degassing Valve Market
Others
Global Computer Graphics Market
Others
Storage Dewar and Dry Shipper Market
Others
US Legal Services Market
Others
Coalescing Filter Market
Others
Surface Green Mining Market