
 Super Computer Market | 2026-2036
Super Computer Market Size, Share, and Industry Trends Forecast 2026-2036
Super Computer Market Analysis
The split between premium exascale contracts and commoditized high-performance clusters is shifting procurement patterns across the supercomputer landscape. Hewlett Packard Enterprise leverages its Cray heritage to dominate federally funded exascale installations in the United States. Lenovo sustains aggressive volume positioning through its Neptune liquid-cooling platform, which reduces power usage effectiveness for hyperscale and academic buyers. IBM competes in the quantum-classical hybrid niche, anchoring specialized contracts where quantum computing intersects with traditional supercomputing workloads.
Supercomputers are large-scale computing systems integrating thousands of processors, high-bandwidth interconnects, and advanced cooling infrastructure to execute quadrillions of calculations per second for simulation, modeling, and data-intensive discovery. These systems employ parallel computing architectures where workload distribution across processor nodes determines effective throughput for tasks such as molecular dynamics and weather forecasting. High-Performance Clusters represent the broadest volume tier, serving commercial and mid-tier academic buyers with standardized configurations, while Quantum Computers occupy the fastest-expanding frontier despite limited current commercial deployment. Hybrid Systems capture widening interest as organizations seek to bridge classical and quantum processing for optimization problems in drug discovery and materials science.
The U.S. Department of Energy enforces strict power efficiency and domestic content requirements through its National Nuclear Security Administration and Office of Science procurement frameworks, directly shaping vendor design priorities and supply chain qualification. In Europe, the EuroHPC Joint Undertaking channels public investment toward systems compliant with EU strategic autonomy goals and CSRD-aligned sustainability disclosures, while Japan's Fugaku successor program under METI direction prioritizes arm-architecture efficiency for domestic semiconductor ecosystem development. Buyers must weigh sovereign technology requirements against interoperability standards when selecting architectural partners for decade-long deployment horizons.
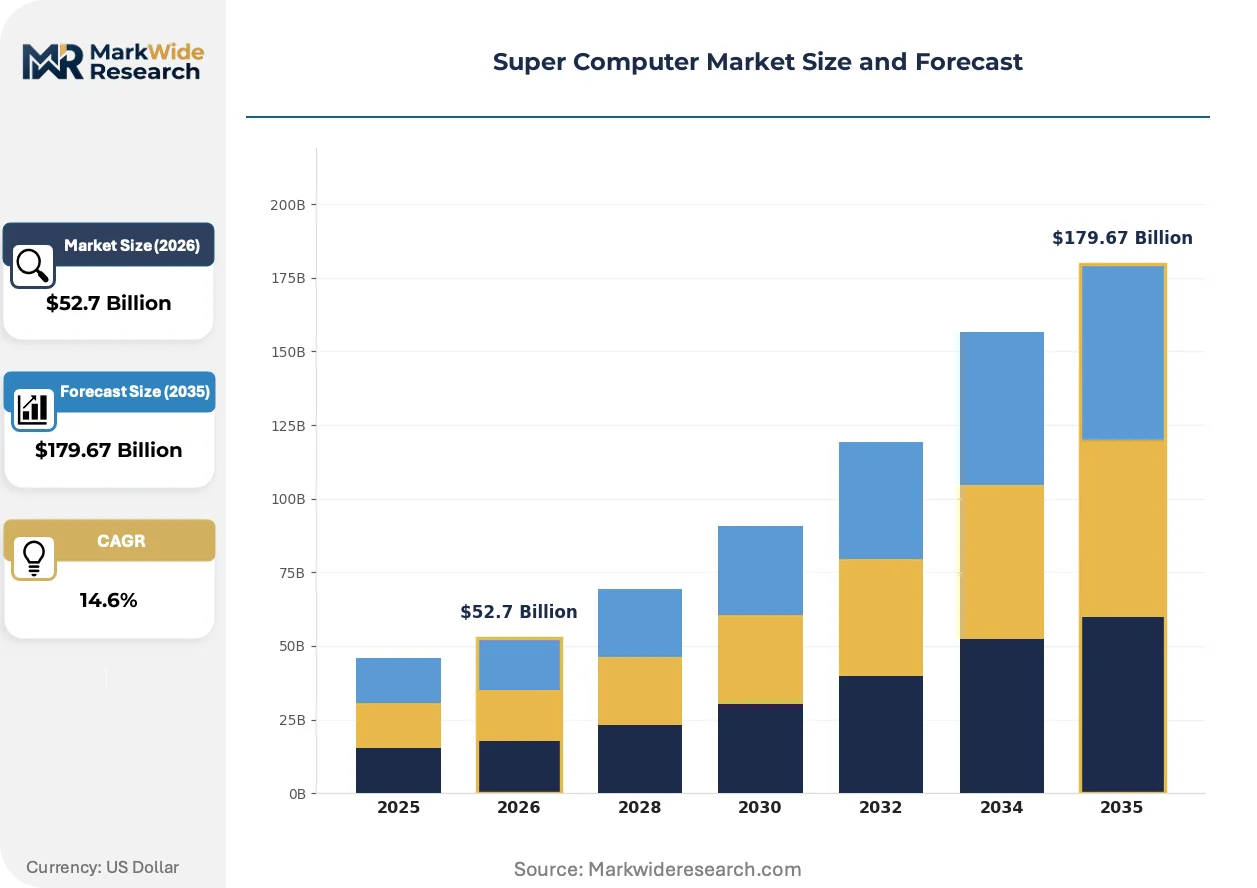
Market Dynamics
Exascale procurement mandates from the U.S. Department of Energy and the EU's EuroHPC Joint Undertaking are forcing architectural trade-offs between sovereign technology requirements and interoperability standards across decade-long deployment cycles.
Growth Catalysts
- Climate modeling mandates:Government research agencies in the United States, Germany, and Japan are expanding system procurement for atmospheric and oceanic simulation workloads under national environmental research frameworks.
- CSRD-aligned sustainability disclosures:The EU's Corporate Sustainability Reporting Directive tightens data center energy efficiency mandates, pushing liquid cooling adoption across European academic and commercial installations.
- Quantum-classical hybrid architectures:Optimization problems in drug discovery and materials science are pulling investment toward systems bridging traditional supercomputing with quantum processing nodes.
Market Restraints
- Domestic content requirements:The U.S. National Nuclear Security Administration enforces strict supply chain qualification that limits vendor sourcing flexibility and extends procurement timelines.
- Power density constraints:Air-cooled infrastructure hits thermal limits below 500 watts per processor socket, forcing costly facility retrofits for next-generation chip deployments.
- GPU accelerator dependence:Concentration in advanced semiconductor fabrication creates single-source vulnerability for AI-optimized supercomputing clusters.
Strategic Opportunities
- India's semiconductor mission:The country's PLI scheme for electronic manufacturing is creating localized assembly capacity for mid-tier high-performance clusters serving academic and defense buyers.
- Arm-architecture efficiency:Japan's Fugaku successor program under METI direction validates reduced-instruction-set designs for domestic semiconductor ecosystem development and export positioning.
- Hyperscale liquid cooling retrofit:Lenovo's Neptune platform and competing direct-to-chip systems open replacement cycles in existing air-cooled academic data centers.
Industry Challenges
- Interconnect software stack complexity:Programming models for heterogeneous processor-accelerator combinations require specialized HPC expertise scarce outside national laboratories and top-tier universities.
- Decade-long procurement cycles:Buyer commitment to specific architectural partners locks vendors into extended support obligations spanning multiple technology generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Super Computer Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $179.67 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Systems, Vector Processors, Quantum Computers, High-Performance Clusters Application: Weather Forecasting, Molecular Dynamics, Big Data Analytics, Computational Fluid Dynamics End User: Government Research, Aerospace, Academic Institutions, Healthcare Research Technology: Parallel Computing, Grid Computing, Cloud Computing, Quantum Computing |
| Companies Covered | Hewlett Packard Enterprise, Lenovo, IBM, NEC Corporation, Fujitsu, Nvidia, Dell Technologies, Atos, Intel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Super Computer Market Emerging Trajectories
Cooling technology and processor heterogeneity are converging to redefine system architecture, procurement evaluation criteria, and facility design standards across government, academic, and commercial deployments.
Liquid cooling infrastructure is absorbing thermal loads from processors exceeding 700 watts per socket, a threshold air-cooled facilities cannot sustain. National laboratories in the United States and Germany are specifying direct-to-chip and immersion systems as baseline requirements for new exascale awards. This technology compression is enabling higher rack densities that reduce facility footprints and construction costs for constrained urban sites.
The EU AI Act and accompanying CSRD disclosure rules are mandating algorithmic transparency and embodied carbon reporting for high-performance computing procurement. EuroHPC Joint Undertaking calls now require lifecycle environmental assessments and renewable energy sourcing documentation. Vendors are responding with supply chain traceability systems and power purchase agreement verification to maintain eligibility for public funding.
Service unbundling is fragmenting traditional turnkey contracts into separate hardware, software, and operational support components. Academic buyers in Germany and Japan are negotiating direct maintenance relationships with cooling subsystem specialists and interconnect providers, bypassing primary system integrators for post-warranty support. This pattern is most visible in university consortia operating shared national facilities with multi-institution governance structures.
Super Computer Market Segmentation
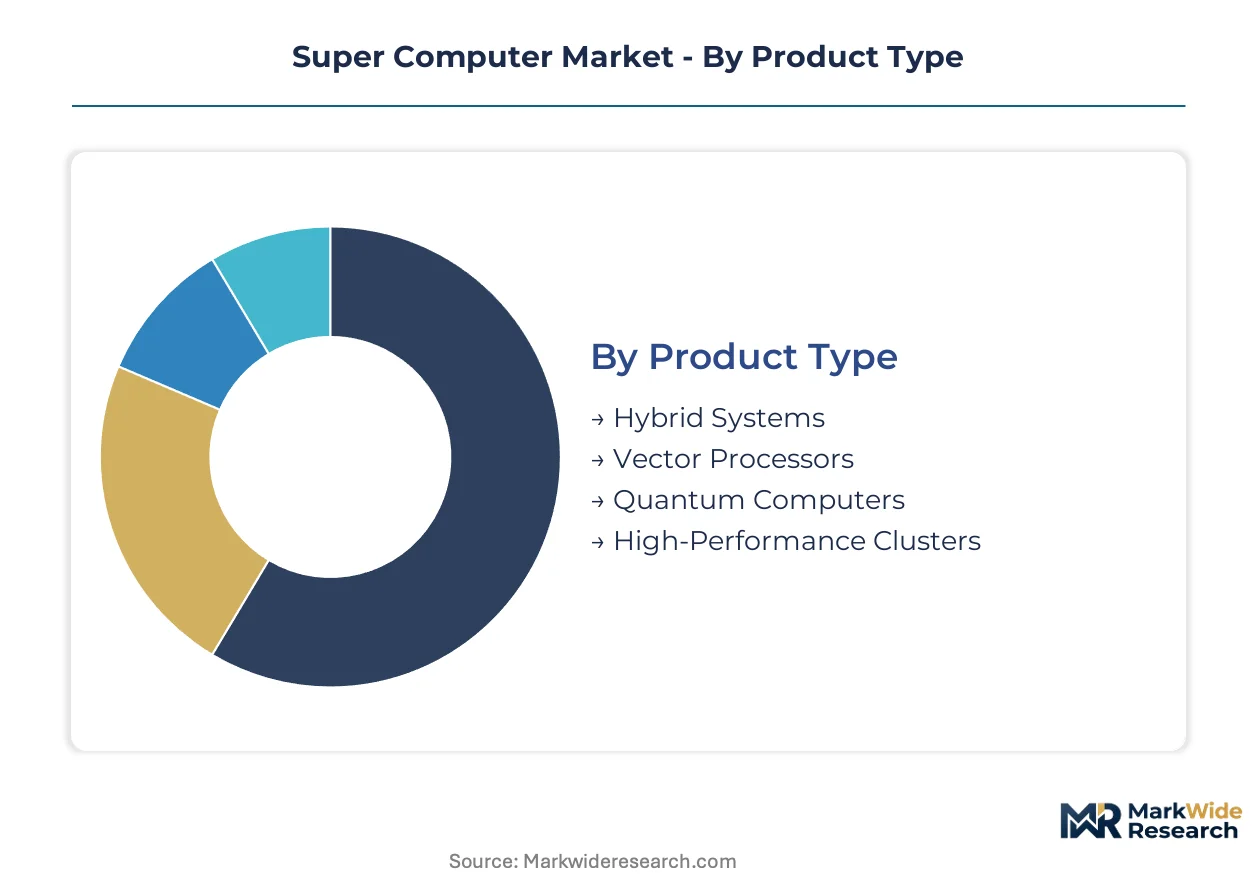
Procurement patterns in supercomputing diverge sharply between sovereign-funded exascale installations and commoditized commercial deployments. Segmentation by product architecture, workload application, and institutional end-use reveals where vendor specialization creates defensible positioning versus where standardization drives price competition.
Product Type:
Integration depth separates standalone systems requiring dedicated facilities from modular architectures deployable within existing data center footprints.
- High-Performance Clusters:Standardized configurations of commodity processors and interconnects serve commercial simulation and mid-tier academic workloads. Demand concentrates in Germany's university consortia and India's defense research establishments, constrained by procurement budgets that prioritize interoperability over peak performance.
- Hybrid Systems:Architectures bridging classical supercomputing nodes with quantum processing units target optimization problems in drug discovery and materials science. Japan's RIKEN and the U.S. Department of Energy are expanding pilot installations, drawn by algorithmic advantages for molecular simulation workloads.
- Quantum Computers:Specialized cryogenic systems for quantum annealing and gate-based processing occupy limited commercial deployment.
- Vector Processors:Reduced-instruction-set designs optimized for specific simulation kernels retain niche relevance in meteorological agencies.
High-Performance Clusters lead volumes today; Hybrid Systems are gaining share fastest.
Application:
Computational intensity and data throughput requirements stratify buyers across scientific domains with divergent facility investment timelines.
- Weather Forecasting:Atmospheric and oceanic simulation demands sustained floating-point throughput across thousands of cores. National meteorological services in Japan, Germany, and the United States maintain dedicated procurement pipelines, with METI and EuroHPC Joint Undertaking channeling public investment toward sovereign technology compliance.
- Molecular Dynamics:Atomic-scale simulation of protein folding and materials properties drives GPU-accelerated cluster adoption. Pharmaceutical researchers in Switzerland and academic consortia across France prioritize direct-to-chip liquid cooling to manage thermal loads from dense accelerator configurations.
- Big Data Analytics:Pattern recognition across petabyte-scale datasets employs distributed memory architectures.
- Computational Fluid Dynamics:Aerodynamic and combustion modeling retains specialized solver requirements.
Weather Forecasting commands the largest installed base; Molecular Dynamics shows steepest expansion trajectory.
End User:
Funding stability and procurement autonomy separate institutional buyers with decade-long deployment horizons from commercial users with shorter replacement cycles.
- Government Research:National laboratories and defense agencies operate under classified and unclassified procurement frameworks with stringent domestic content requirements. The U.S. National Nuclear Security Administration enforces supply chain qualification that limits vendor sourcing flexibility, while EuroHPC mandates CSRD-aligned sustainability disclosures.
- Academic Institutions:University consortia and shared national facilities negotiate unbundled service contracts, bypassing primary system integrators for post-warranty cooling and interconnect support. Germany's Gauss Centre for Supercomputing exemplifies multi-institution governance structures fragmenting traditional turnkey procurement.
- Aerospace:Commercial and defense aviation manufacturers maintain captive simulation capacity.
- Healthcare Research:Genomic sequencing and epidemiological modeling drive specialized cluster deployment.
Government Research absorbs the largest capital allocations; Academic Institutions are expanding procurement most aggressively.
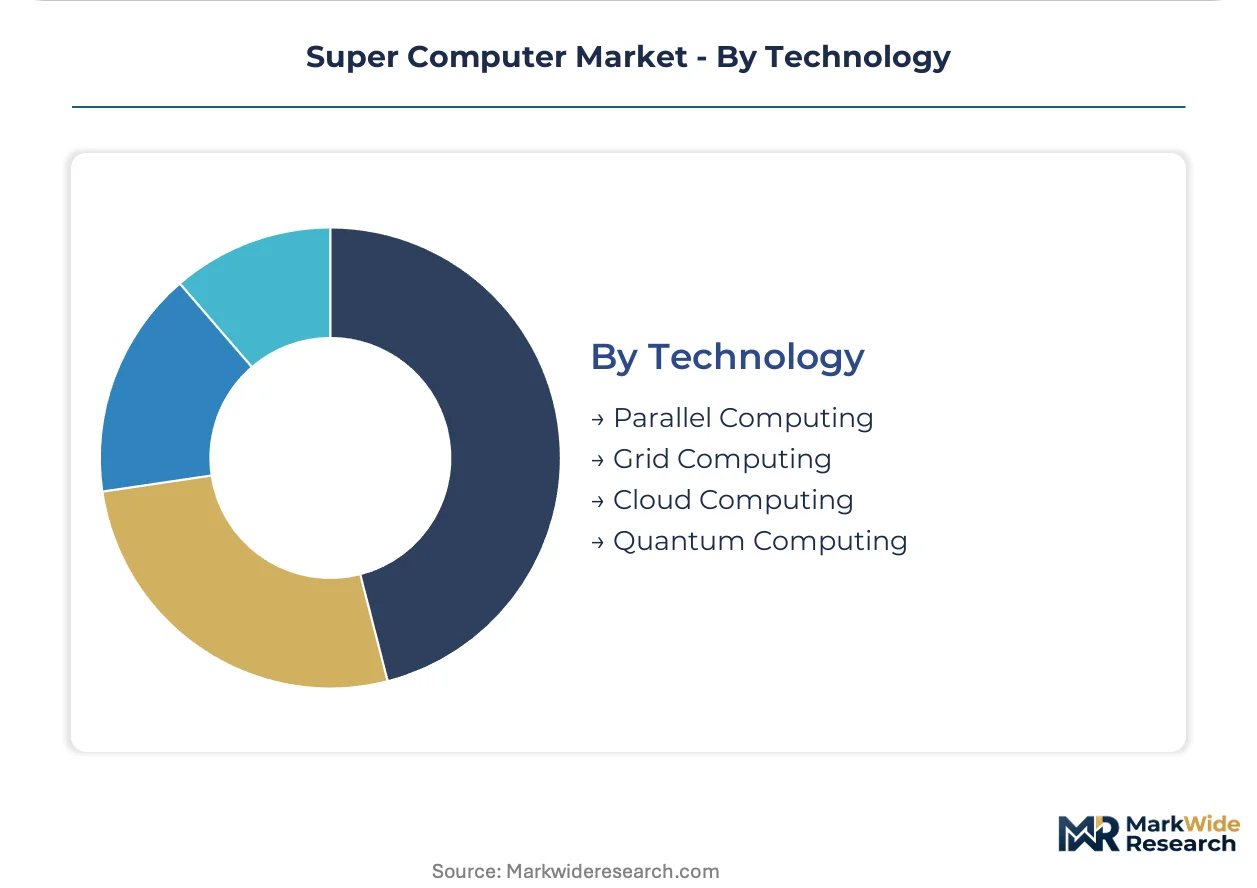
Technology:
Programming model complexity and hardware abstraction layers determine where specialized HPC expertise creates vendor lock-in versus where cloud portability enables buyer flexibility.
- Parallel Computing:Message-passing and shared-memory architectures dominate production supercomputing, with MPI and OpenMP standards enabling workload portability across vendor platforms. National laboratories in the United States and Japan anchor demand, constrained by interconnect software stack complexity that requires scarce specialized expertise.
- Cloud Computing:On-demand access to HPC resources through hyperscale providers allows commercial buyers to avoid facility capital expenditure. India's academic and startup researchers leverage this model, though data sovereignty requirements limit adoption for defense and healthcare workloads.
- Grid Computing:Federated resource sharing across institutional boundaries retains specialized scientific community relevance.
- Quantum Computing:Gate-based and annealing approaches occupy experimental deployment.
Parallel Computing underpins existing infrastructure; Cloud Computing is climbing the fastest among emerging technology categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized HPC engineering talent clusters around national laboratories in the United States, Germany, and Japan, anchoring procurement decisions and architectural roadmaps for exascale deployments.
United States
The Department of Energy's National Nuclear Security Administration and Office of Science sustain the largest installed base of top-tier systems through classified and unclassified procurement frameworks. Domestic content requirements under NHTSA-aligned supply chain rules limit vendor sourcing flexibility. Oak Ridge National Laboratory in Tennessee and Lawrence Livermore National Laboratory in California anchor exascale deployment timelines.
Germany
University consortia and the Gauss Centre for Supercomputing drive demand for mid-tier high-performance clusters with standardized configurations. The CSRD tightens data center energy efficiency mandates, pushing liquid cooling adoption across academic installations. Munich and Stuttgart host concentrated procurement activity for atmospheric simulation workloads.
Japan
METI direction prioritizes arm-architecture efficiency for domestic semiconductor ecosystem development through the Fugaku successor program. RIKEN expands pilot installations of hybrid systems bridging classical and quantum processing. Kobe and Tokyo anchor national meteorological service procurement for weather forecasting infrastructure.
China
Dual carbon goals and tightening data center energy efficiency mandates push vendors toward liquid cooling and renewable-powered architectures. National research programs concentrate procurement for climate modeling and materials science simulation. Beijing and Shanghai host the principal industrial clusters for system integration and deployment.
India
The PLI scheme for electronic manufacturing creates localized assembly capacity for mid-tier high-performance clusters serving academic and defense buyers. BIS standards govern equipment qualification for government research establishments. Bangalore and Hyderabad anchor defense research procurement with expanding university consortia participation.
Super Computer Market Vendor Landscape
Top-tier vendors anchor federally funded exascale installations, while mid-tier specialists compete on liquid-cooling efficiency and volume positioning for academic buyers. The market structures around three archetypes: heritage supercomputing integrators with Cray-derived architectures, volume-driven cluster assemblers with cooling platform differentiation, and quantum-classical hybrid specialists targeting optimization workloads. Capacity expansion and strategic partnerships dominate competitive moves, with vendors securing decade-long support obligations through primary system integrator relationships.
Within the heritage integrator tier, Hewlett Packard Enterprise and Fujitsu exemplify positioning anchored to national laboratory procurement frameworks. Lenovo occupies a position among volume-driven specialists with Neptune liquid-cooling platform differentiation for hyperscale and academic buyers. IBM sits within the quantum-classical hybrid niche, anchoring specialized contracts where quantum computing intersects with traditional supercomputing workloads.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| Lenovo |
| IBM |
| NEC Corporation |
| Fujitsu |
| Nvidia |
| Dell Technologies |
| Atos |
| Intel |
| Others |
Supply Flow & Price Mechanics
Liquid cooling infrastructure migration is compressing facility costs while concentrating procurement power among vendors with proven direct-to-chip deployment records. National laboratories in the United States and Germany now specify immersion and cold-plate systems as baseline requirements, forcing academic buyers toward unbundled service contracts that separate hardware from operational support.
Pricing Analysis
The bundled-versus-unbundled service split is fragmenting traditional turnkey contracts into discrete hardware, software, and cooling subsystem components. Pricing stratifies across exascale sovereign installations, mid-tier academic clusters, and commoditized commercial configurations, with differentiation driven by domestic content certification and liquid cooling integration depth. Cost compression in mid-tier segments is intensifying because university consortia negotiate direct maintenance relationships with subsystem specialists, bypassing primary integrators for post-warranty support. Academic buyers exhibit the highest price sensitivity due to fixed grant funding cycles, while defense agencies sustain premium tolerance for classified procurement frameworks.
Supply Chain Analysis
Dual-sourcing requirements mandated by the U.S. National Nuclear Security Administration and EuroHPC Joint Undertaking are forcing vendors to qualify secondary suppliers for advanced interconnects and accelerator modules. Manufacturing concentration rests on Taiwan and South Korea for GPU accelerators, the United States for high-bandwidth memory, and Japan for specialized interconnect silicon. Supply chain risk centers on single-source vulnerability for AI-optimized semiconductor fabrication, where advanced node capacity remains geographically concentrated. Distribution runs through primary system integrators with decade-long support obligations, though academic consortia increasingly fragment procurement across cooling specialists and interconnect providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in supercomputing hinges on liquid cooling platform differentiation and the shift toward premium exascale contracts with sovereign technology compliance requirements. Vendors capturing both efficiency gains and premium-tier positioning will outpace commodity cluster assemblers.
For Market Incumbents: To counter GPU accelerator dependence and single-source semiconductor vulnerability, heritage integrators should deepen backward integration into cooling subsystem design and secure captive supply agreements for high-bandwidth memory. Certification investment in CSRD-aligned sustainability disclosure systems will preserve eligibility for EuroHPC Joint Undertaking awards.
For New Entrants and Emerging Players: Begin with India's PLI-scheme electronic manufacturing corridors, where localized assembly capacity for mid-tier clusters serves defense research establishments with less stringent domestic content thresholds than U.S. or EU procurement. Academic consortia in Germany and Japan present the most penetrable buyer segment due to fragmented governance structures and unbundled service preferences.
For Investors and Strategic Acquirers: Valuations sit cheapest among liquid cooling platform specialists with Neptune-class direct-to-chip deployment records but limited exascale heritage. Long-term viability over a five-to-ten year window favors vendors with proven sovereign technology compliance and renewable energy sourcing verification. Watch for inflection in Arm-architecture efficiency validation through Japan's Fugaku successor program.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Platform Expansion | Neptune-class direct-to-chip systems reduce power usage effectiveness for hyperscale academic buyers. |
| Arm-Architecture Ecosystem Development | RIKEN's Fugaku successor program validates reduced-instruction-set designs for domestic semiconductor positioning. |
| Quantum-Classical Hybrid Pilot Installation | U.S. Department of Energy contracts bridge traditional supercomputing nodes with quantum processing units. |
| CSRD-Aligned Sustainability Certification | EuroHPC Joint Undertaking mandates lifecycle environmental assessments for public funding eligibility. |
| Localized Assembly Capacity Under PLI Scheme | India's electronic manufacturing incentives create mid-tier cluster supply for defense and academic buyers. |
Methodological Framework
Coverage spans the United States, Germany, Japan, China, and India, with primary inputs from each market anchoring demand-side validation. The study combines structured interviews with supercomputing procurement officers at national laboratories, facility engineers managing liquid cooling retrofits, and academic consortium directors overseeing shared national infrastructure. Secondary validation draws from U.S. Department of Energy procurement disclosures, EuroHPC Joint Undertaking award documentation, METI program announcements, and SEC filings from publicly traded system integrators. Bottom-up demand modeling triangulates against top-down market sizing across hardware, software, and operational support revenue streams.
Granularity-level modeling disaggregates volume and value outputs by product architecture, workload application, institutional end-use, and technology deployment model across the projection horizon. Segmentation dimensions include integration depth for standalone versus modular systems, computational intensity for weather forecasting versus molecular dynamics, funding stability for government research versus academic consortia, and programming model complexity for parallel versus cloud computing. CAGRs derive from fitted growth curves calibrated to exascale deployment timelines and sovereign procurement pipeline visibility. Industry-specific forecast inputs encompass thermal design power trajectories for next-generation processors and domestic content requirement phase-in schedules.
Several conditions sit outside the modeled scope, including specific contract award dates, classified program budgets, and quantum computing hardware commercialization timelines. Forecasts reflect assumptions about sustained public research funding, continued semiconductor fabrication concentration, and regulatory stability for energy efficiency mandates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Insoluble Sulfur Market
Others
Asia-Pacific Telecom Transformers Market
Others
Turkey Health and Medical Insurance Market
Others
Asia-Pacific Intercom Devices Market
Others
Buchner Funnels Market
Others
Gem Faceting Machine Market
Others
Global Car Wax Market
Others
Latin America Domestic CEP Market
Others
Spain Feed Additives Market
Others
Profiling Floats Market
Others
Africa 3D Printing Construction Market
Others
Solar Panel Testers Market
Others
Spain Smart Home Market
Others
Global Hydraulics Market
Others
Coloring Apps Market
Others
ASEAN Agricultural Logistics Market