
 Smart Wardrobe Market | 2026-2036
Smart Wardrobe Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Wardrobe Market Insights
Premium-grade sensor integration is bifurcating the competitive landscape between full-stack system architects and component specialists. Poliform leverages its Italian manufacturing heritage to command the ultra-luxury segment with bespoke millwork housing embedded IoT infrastructure. California Closets anchors the North American market through its franchise network, sustaining regional installation capacity that software-first entrants cannot replicate. Oppeinhome dominates China's mass-premium tier by controlling cabinet production at factory scale and extending captive distribution through 5,000-plus showrooms.
A smart wardrobe denotes an electronically augmented clothing storage system incorporating RFID garment tracking, environmental sensors, and motorized racking to automate inventory visibility and outfit curation. These systems typically integrate humidity control between 45% and 55% relative humidity to preserve textile integrity while feeding consumption data back to retail supply chains. Smart mirrors within the product type category capture disproportionate margin pools because they require minimal carpentry retrofit and command software-subscription attach rates. AI personal assistant technology leads feature differentiation, though RFID tracking sustains volume penetration due to lower per-unit sensor costs and simpler retrofit paths.
The EU Green Deal and Ecodesign for Sustainable Products Regulation compel manufacturers to disclose embodied carbon in wardrobe hardware and electronics, reshaping supplier qualification criteria across European markets. The US FCC governs wireless transmission protocols for IoT-enabled closet systems, while China's MIIT certifies GB-standard compliance for domestic smart home device interoperability. Stakeholders must weigh modular upgrade architectures against integrated sealed-unit designs as regulatory repairability mandates proliferate across jurisdictions.
Market Dynamics
The smart wardrobe sector confronts a fundamental tension between sealed-unit integrated architectures favored by luxury millwork houses and modular repairable designs mandated by emerging circular-economy regulations. This structural conflict is reshaping R&D allocation, supplier qualification, and warranty liability across all price tiers.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Mandatory disclosure of embodied carbon in electronics and hardware is accelerating supplier consolidation toward certified component vendors with traceable supply chains.
- RFID sensor cost compression:Declining per-unit tag prices are enabling mass-market wardrobe retrofits in China's tier-one cities without full carpentry replacement.
- Luxury residential development pipelines:Specified smart closet installations in Dubai and Riyadh are creating anchor demand that validates technology for broader consumer adoption.
Market Restraints
- Semiconductor supply concentration:RF transceiver and motor controller chip sourcing remains concentrated among Taiwan-based foundries, exposing lead time volatility.
- Technical interoperability limitations:Proprietary communication protocols between wardrobe hardware and third-party smart home platforms create integration friction for consumers.
- Substitution by standalone devices:Portable garment steamers with basic humidity sensing and smartphone-connected inventory apps capture budget-conscious demand without installation costs.
Strategic Opportunities
- India's nascent smart home channel:Underpenetrated wardrobe automation in Mumbai and Delhi NCR offers first-mover positioning before mass-market saturation.
- AI-mirror subscription services:Software attach rates for virtual styling and retail recommendation engines generate recurring revenue streams from installed hardware bases.
- Modular upgrade architectures:Design-for-disassembly approaches align with EU repairability mandates while creating aftermarket parts revenue and reducing warranty exposure.
Industry Challenges
- Embedded systems firmware talent scarcity:Shortage of engineers with combined IoT security and real-time motor control expertise constrains product development velocity.
- Multi-jurisdiction certification timelines:Simultaneous FCC Part 15, CE RED, and MIIT GB-standard compliance testing extends product launch cycles by 8-14 months.
- Legacy carpentry trade integration:Traditional closet installers lack electrical commissioning skills, forcing manufacturers to build parallel certified technician networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Wardrobe Market |
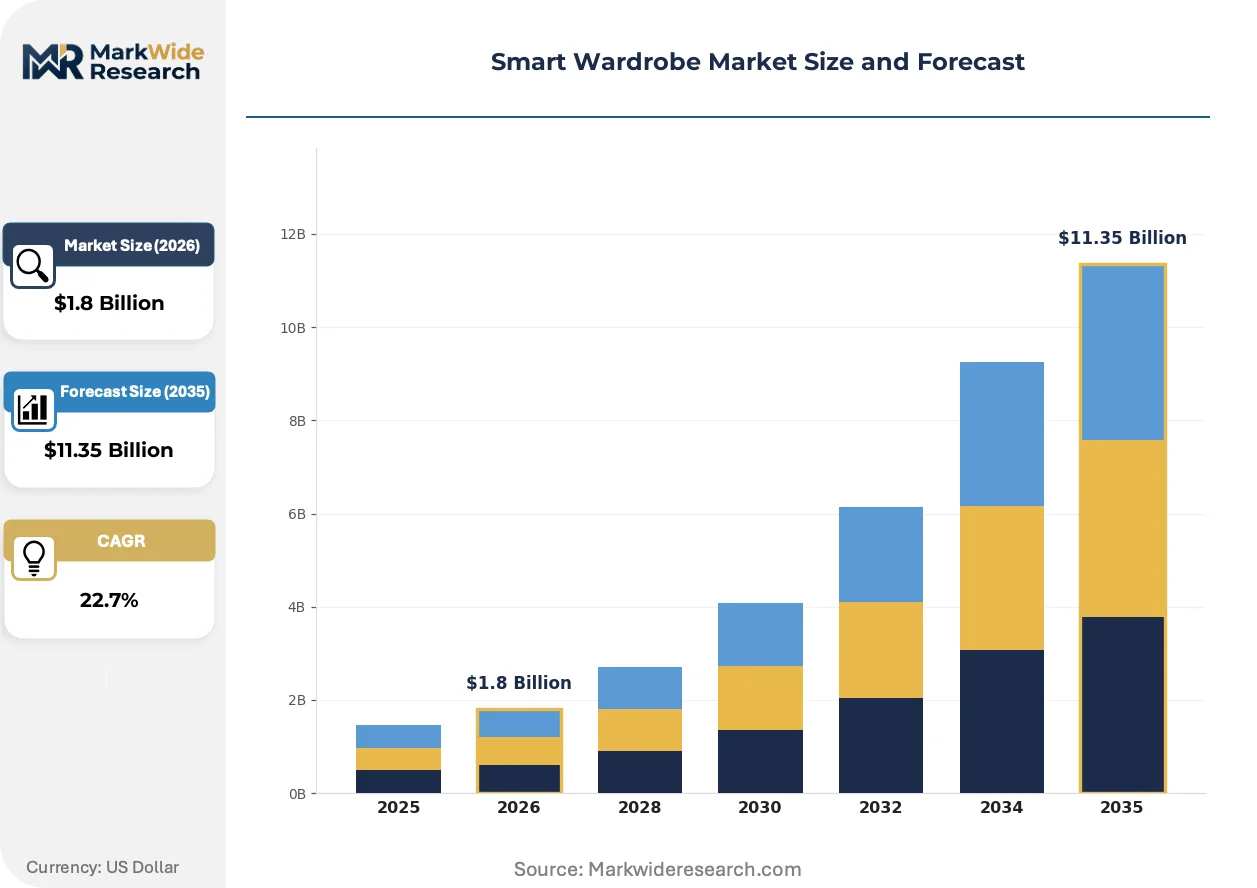
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Closets, Smart Hangers, Smart Mirrors, Clothing Management Systems Technology: IoT Integration, AI Personal Assistant, RFID Tracking, Mobile App Connectivity End User: Individual Consumers, Retail Stores, Fashion Designers, Hospitality Sector Feature: Automated Inventory, Virtual Outfit Planning, Climate Control, Cleaning Assistance |
| Companies Covered | Poliform, California Closets, Oppeinhome, Inspired Closets, Sliderobes, Sharps, ClosetMaid, Organized Living, Hammonds, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Wardrobe Market Trends and Innovations
Active innovation in smart wardrobes centers on three vectors: the unbundling of hardware from software value capture, regulatory pressure forcing design architecture pivots, and channel restructuring that separates physical installation from digital service delivery.
Computer vision-based garment recognition is decomposing the traditional RFID-tag dependency for inventory tracking. High-end residential developers in Saudi Arabia and the UAE are piloting camera-rack systems that eliminate per-garment tagging labor. This technology is compressing hardware bill-of-materials costs while shifting margin capture toward cloud-based styling algorithms.
The EU Green Deal's embodied carbon disclosure requirements are forcing manufacturers to redesign sealed electronic modules into field-replaceable units. Italian and German millwork houses are requalifying suppliers based on ISO 14040 lifecycle data availability. The premium bespoke segment faces the steepest compliance cost escalation as custom one-off production resists standardized component reuse.
Buyers in China's tier-one cities are fragmenting purchase decisions between hardware procurement and ongoing service subscriptions. Oppeinhome's showroom network and California Closets' franchise system are being bypassed by direct-to-consumer AI-mirror brands that partner with local electricians for physical mounting. This channel unbundling is most advanced in Shenzhen and Shanghai, where smart home penetration has normalized piecemeal technology adoption.
Smart Wardrobe Market Segmentation
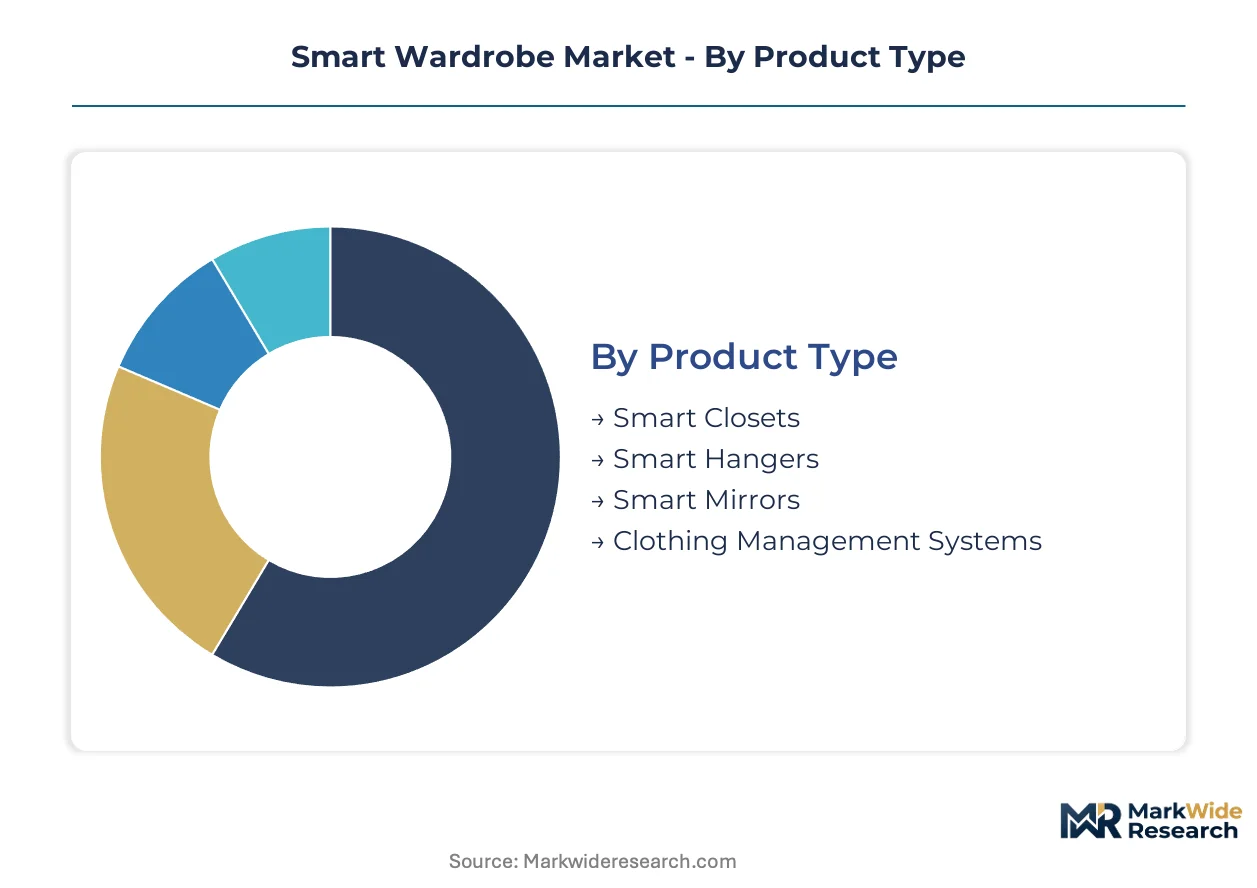
Smart wardrobe segmentation reveals divergent vulnerability to substitute technologies across hardware categories. Product architecture choices determine whether segments face displacement from standalone devices or retain defensible integration advantages.
Product Type:
Smart mirrors confront the most acute substitution pressure from tablet-based styling apps and standalone connected displays, while integrated closet systems maintain structural barriers against portable alternatives.
- Smart Mirrors:Wall-mounted or freestanding displays with embedded cameras and touchscreen interfaces deliver virtual try-on and styling recommendations. Demand concentrates in China's tier-one cities where apartment renovations favor minimal-carpentry retrofit solutions; the segment faces margin compression from smartphone-app alternatives that replicate core functionality without hardware purchase.
- Smart Closets:Full cabinetry systems incorporating motorized racking, environmental sensors, and embedded computing infrastructure. Luxury residential developers in Dubai and Riyadh specify these as standard amenities; high installation costs and space requirements insulate the segment from portable substitute threats.
- Smart Hangers:Individual garment carriers with integrated weight sensors and RFID readers for per-item tracking. Boutique hotel chains in Milan and Paris pilot these for guest wardrobe services.
- Clothing Management Systems:Modular software-hardware combinations focused on inventory digitization and outfit curation. Fashion rental platforms in London and New York deploy these for logistics optimization.
Smart closets retain volume leadership; smart mirrors hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium AI-driven experiences from mass-market sensor deployments, with middleware integration costs determining accessible price points.
- AI Personal Assistant:Natural language processing and computer vision systems enabling conversational outfit recommendations and predictive styling. High development costs restrict deployment to flagship installations in Saudi Arabia and the UAE; subscription revenue models partially offset hardware margin erosion.
- RFID Tracking:Passive or active radio-frequency identification tags enabling automated garment identification without line-of-sight requirements. China's factory-scale cabinet producers leverage tag cost compression to penetrate mass-market segments; per-unit sensor economics below one dollar enable retrofit penetration without full system replacement.
- IoT Integration:Networked connectivity enabling wardrobe hardware communication with broader smart home ecosystems. European manufacturers prioritize Matter protocol compatibility to satisfy interoperability mandates under EU AI Act and GDPR data governance requirements.
- Mobile App Connectivity:Smartphone-based control interfaces decoupled from dedicated wardrobe hardware. Indian smart home entrants exploit this technology to bypass physical distribution constraints in Mumbai and Delhi NCR.
RFID tracking dominates installed base scale; AI personal assistant technology captures the highest value-per-unit expansion trajectory.
End User:
Application maturity varies sharply between consumer installations driven by convenience and commercial deployments seeking operational efficiency gains.
- Retail Stores:Back-of-house inventory management and client-facing styling stations. Department stores in Tokyo and Seoul deploy these to reduce garment search time and enable endless-aisle fulfillment.
- Individual Consumers:Residential installations ranging from retrofit mirror additions to full custom millwork. Warranty liability and installation complexity constrain penetration in markets lacking certified technician networks.
- Fashion Designers:Sample archive management and rapid prototyping workflows. Milan-based luxury houses utilize climate-controlled storage to preserve delicate textile specimens.
- Hospitality Sector:Guest room wardrobe automation and staff garment processing. Five-star properties in Singapore and Bangkok differentiate through personalized outfit curation services.
Individual consumers represent the broadest addressable base; retail stores demonstrate the most concentrated procurement velocity.
Feature:
Customer type differentiation separates utility-driven purchasers prioritizing garment preservation from experience-seeking buyers valuing styling augmentation.
- Climate Control:Humidity regulation between 45% and 55% relative humidity with optional UV filtration for textile integrity preservation. Premium residential installations in humid subtropical markets including Miami and Shanghai specify these as standard; sensor calibration requirements create aftermarket service revenue.
- Virtual Outfit Planning:Digital wardrobe visualization combining owned garments with retail inventory for purchase recommendations. Software attach rates concentrate revenue in recurring streams rather than one-time hardware sales.
- Automated Inventory:Machine-readable garment cataloging with wear-frequency analytics and maintenance scheduling. Rental fashion platforms in Berlin and Amsterdam leverage this for depreciation tracking.
- Cleaning Assistance:Integrated steam treatment, odor neutralization, and care label interpretation. Japanese manufacturers embed these features to address space-constrained urban apartments lacking dedicated laundry facilities.
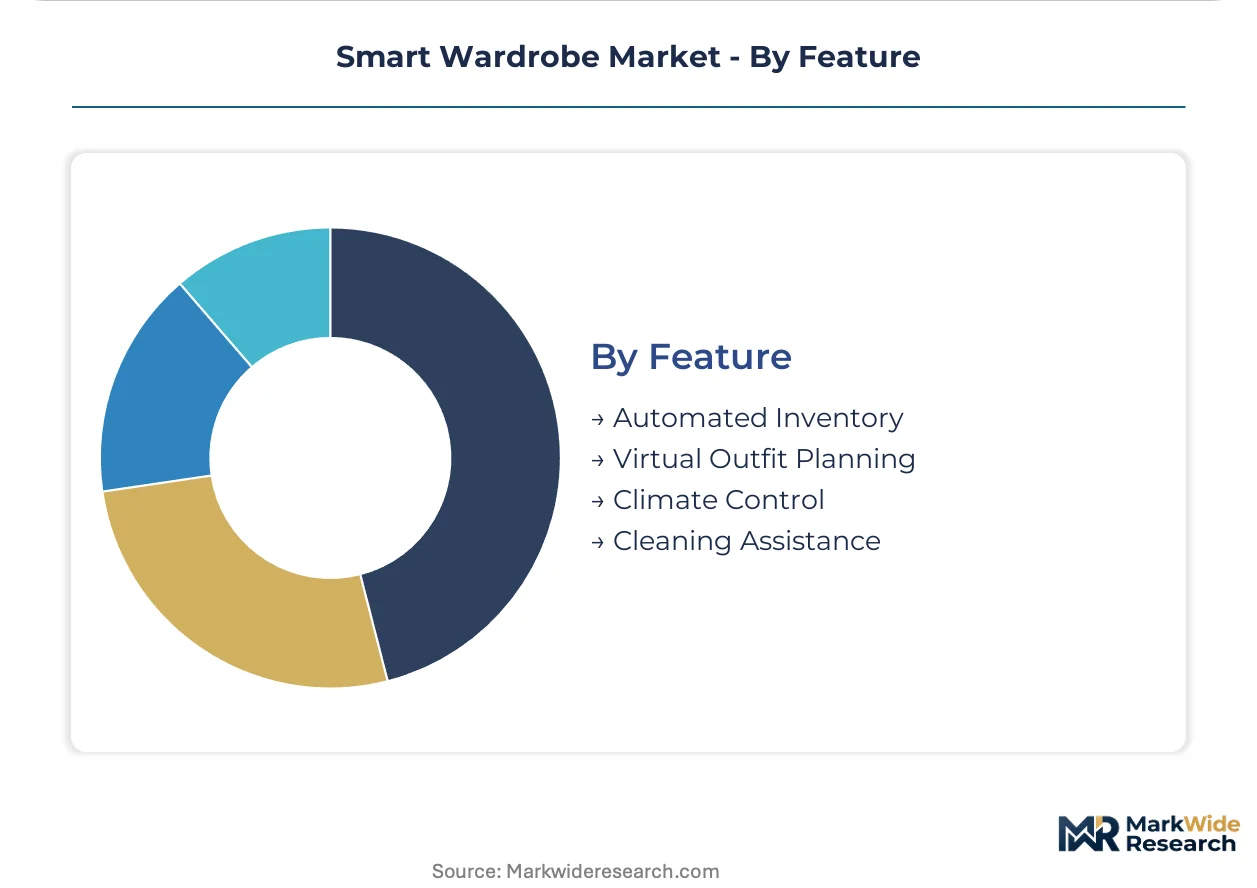
Climate control commands the highest installation attach rate; virtual outfit planning generates the most significant recurring revenue expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component sourcing for smart wardrobe systems concentrates in East Asian semiconductor foundries and Italian precision manufacturing clusters. Demand generation spreads across luxury residential developments in the Gulf, mass-market retrofits in Chinese megacities, and sustainability-driven replacements across the EU.
China
Oppeinhome's factory-scale cabinet production and 5,000-plus showroom network dominate mass-premium distribution in Shenzhen and Shanghai. MIIT certifies GB-standard compliance for domestic smart home device interoperability, accelerating adoption curves in tier-one cities. Pearl River Delta manufacturing clusters supply RFID sensors and motor controllers at compressed per-unit economics.
United States
California Closets sustains regional installation capacity through its franchise network that software-first entrants cannot replicate. FCC Part 15 governs wireless transmission protocols for IoT-enabled closet systems, extending product launch timelines. Miami's humid subtropical climate drives premium residential demand for climate-controlled wardrobe specifications.
United Arab Emirates
Luxury residential developers in Dubai specify connected closet systems as standard amenity upgrades, validating technology for broader consumer adoption. MOHAP regulates smart home device safety standards for hospitality sector deployments. Dubai's high-end property pipeline anchors Gulf demand for full cabinetry systems with embedded IoT infrastructure.
Germany
EU Ecodesign for Sustainable Products Regulation compels manufacturers to disclose embodied carbon in wardrobe hardware and electronics. German millwork houses requalify suppliers based on ISO 14040 lifecycle data availability. Bavaria's precision engineering clusters develop modular, repairable hardware architectures aligned with circular-economy mandates.
Saudi Arabia
High-end residential developers in Riyadh pilot camera-rack systems that eliminate per-garment tagging labor. SFDA oversees product safety certification for imported electronic components. NEOM's planned city developments specify smart home infrastructure including automated wardrobe systems as baseline residential amenities.
Smart Wardrobe Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. The market fragments between full-stack system architects commanding ultra-luxury segments and component specialists capturing mass-market volume through factory-scale production. Three archetypes dominate: Italian heritage millwork houses with bespoke IoT integration, North American franchise networks sustaining installation capacity, and Chinese factory-scale producers controlling captive distribution. Competitive moves concentrate on modular upgrade architectures versus integrated sealed-unit designs, and on building parallel certified technician networks to overcome legacy trade skill gaps.
Within the heritage millwork tier, Poliform exemplifies Italian manufacturing positioning through bespoke production. California Closets anchors North American regional coverage through franchise-based installation networks. Oppeinhome occupies the mass-premium position through factory-scale cabinet production and showroom density in Chinese tier-one cities.
| Leading Market Players |
|---|
| Poliform |
| California Closets |
| Oppeinhome |
| Inspired Closets |
| Sliderobes |
| Sharps |
| ClosetMaid |
| Organized Living |
| Hammonds |
| Others |
Pricing and Supply Chain Analysis
Camera-rack computer vision substitution for RFID garment tagging is redrawing component sourcing maps toward Shenzhen imaging sensor clusters while collapsing per-unit hardware economics that once sustained premium pricing tiers.
Pricing Analysis
The EU Ecodesign for Sustainable Products Regulation dictates the pricing tier structure through embodied carbon disclosure mandates that escalate compliance costs for bespoke millwork while sparing mass-market modular producers. Three-tier pricing structure across premium, standard, and economy levels separates Italian heritage houses with ISO 14040-certified supply chains from Chinese factory-scale producers and budget retrofit specialists. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in mass-market RFID-enabled wardrobes is intensifying because Pearl River Delta sensor manufacturers achieve sub-dollar per-unit tag economics. Budget-conscious residential retrofits in Chinese tier-one cities exhibit highest price sensitivity; ultra-luxury developers in Dubai and Riyadh demonstrate lowest.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for RF transceiver and motor controller chips that power smart wardrobe electronics. Component sourcing draws from Italian precision manufacturing clusters for bespoke millwork hardware and Pearl River Delta assembly lines for mass-market cabinet systems. Raw material dependencies include rare earth elements for permanent magnet motors, copper for RFID antenna traces, and engineered wood composites for cabinetry substrates. Single-source vulnerability concentrates in Taiwan-based foundry capacity for specialized IoT chipsets. Distribution runs through franchise installation networks in North America, captive showroom channels in China, and direct-to-consumer AI-mirror brands bypassing traditional carpentry trade in Shenzhen and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: EU repairability mandates and multi-jurisdiction certification timelines create switching costs that lock in incumbent positions while raising barriers for unqualified entrants.
For Market Incumbents: Fortify certified technician networks to overcome legacy carpentry trade skill gaps that constrain installation capacity expansion. Deepen backward integration into modular, field-replaceable electronic architectures that align with EU Ecodesign mandates while reducing warranty exposure. California Closets' franchise model and Oppeinhome's showroom density represent replicable channel control levers against software-first disintermediation threats.
For New Entrants and Emerging Players: CE RED fast-track certification for Matter protocol compatibility unlocks European market access before interoperability mandates harden competitive positions. India's nascent smart home channel in Mumbai and Delhi NCR offers penetrable white space before mass-market saturation. Direct-to-consumer AI-mirror partnerships with local electricians bypass physical distribution constraints that burden legacy millwork houses.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors component specialists with captive manufacturing scale over full-stack system architects facing margin erosion. Long-term viability across the projection horizon rests on software-subscription attach rates and aftermarket parts revenue rather than one-time hardware sales. Acquisition target archetype: modular hardware platforms with field-replaceable architectures and established certification pipelines. Signal to monitor: MIIT GB-standard harmonization with Matter protocol as inflection indicator for China-EU interoperability convergence.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Hardware Architecture Migration | Aligns with EU Ecodesign repairability mandates while creating recurring aftermarket parts revenue streams. |
| AI-Mirror Subscription Service Launch | Captures software value in Shenzhen and Shanghai where channel unbundling favors digital-first entrants. |
| Certified Technician Network Expansion | Addresses legacy carpentry trade skill gaps that constrain installation velocity in North American markets. |
| Matter Protocol Compatibility Investment | Satisfies GDPR and EU AI Act interoperability requirements under CE RED certification pathways. |
| India Market Entry Partnership | Positions before mass-market saturation in Mumbai and Delhi NCR through mobile-app-first distribution. |
Research Methodology
Initial hypotheses were tested against primary input from smart home platform engineers, luxury residential development procurement directors, franchise network operators, and RFID component manufacturing executives and refined through secondary validation. Primary fieldwork encompassed structured interviews with millwork house R&D leads, certified installation technicians, and smart mirror software product managers. Secondary sources included MIIT GB-standard filings, FCC Part 15 equipment authorization databases, EU Ecodesign preparatory study documents, and Pearl River Delta customs export records. Bottom-up unit economics modeling triangulated against top-down luxury residential pipeline assessments.
Variance decomposition across the projection horizon isolates volume drivers by product architecture type, technology tier, and end-user application maturity. Segmentation dimensions modeled encompass hardware category, sensor technology, customer type, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and replacement cycle assumptions. Industry-specific forecast inputs include RFID tag cost compression curves and luxury residential development pipeline data from Dubai and Riyadh.
Decision-makers should treat outputs as directional under sustained semiconductor supply concentration and EU repairability mandate enforcement; material deviation would warrant model refresh. Specific risks that could revise projections include Taiwan foundry capacity disruptions, Matter protocol adoption delays, and substitution acceleration by standalone garment management apps. Recalibration cycles align with material shifts in MIIT certification timelines and EU Green Deal implementation phases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Designer Sneaker Market
Apparel & Footwear
Bra Market
Apparel & Footwear
Streetwear Market
Apparel & Footwear
Women's Tights and Leggings Market
Apparel & Footwear
Gymnastic Leotards Market
Apparel & Footwear
Erotic Lingerie Market
Apparel & Footwear
South Africa Denim Jeans Market
Apparel & Footwear
Fast Fashion Apparel Market
Apparel & Footwear
Asia-Pacific Sports Apparel Market
Apparel & Footwear
North America E-Commerce Apparel Market
Apparel & Footwear
Hats Market
Apparel & Footwear
Global Swimwear (Swimsuit) Market
Apparel & Footwear
Womens Swimwear Market
Apparel & Footwear
Athletic and Sports Socks Market
Apparel & Footwear
US Thermal Underwear Market
Apparel & Footwear
Women's Coats and Jackets Market