
 Pesto Sauces Market | 2026-2036
Pesto Sauces Market Size, Share, and Industry Trends Forecast 2026-2036
Pesto Sauces Market Outlook
Asset-light co-manufacturing and private-label leasing arrangements is reconfiguring competitive entry barriers for mid-sized pesto producers. Barilla G. e R. Fratelli Spa leverages its vertically integrated milling and sauce operations to sustain cost advantages across Mediterranean supply chains. F.lli Sacla Spa anchors its position through specialized regional recipes that dominate UK and Italian retail shelves. Nestle SA competes through extensive cold-chain distribution controls spanning European supermarkets.
Pesto sauces comprise emulsified preparations of crushed basil, pine nuts or alternative tree nuts, hard cheese, garlic, and olive oil, traditionally produced through ambient-temperature stone grinding to preserve volatile aromatic compounds; these products serve as ready-to-use flavor bases for pasta dishes, sandwich spreads, and protein marinades in both retail and foodservice channels. Basil pesto occupies the mature volume core with established household penetration, while vegan pesto formulations represent the fastest-expanding margin pool as plant-based dietary frameworks gain traction. Glass jar packaging retains premium positioning in specialty retail channels, though plastic containers capture cost-sensitive supermarket volumes.
FDA food labeling requirements and EU Regulation 1169/2011 on food information to consumers shape ingredient disclosure standards and allergen warnings across transatlantic pesto trade. EFSA evaluations of pesticide residues in fresh basil directly influence raw material sourcing protocols for European manufacturers. Organic certification under USDA National Organic Program and EU organic regulations creates tiered market access thresholds that stakeholders must navigate as clean-label expectations intensify.
Market Dynamics
Clean-label ingredient regulations in the European Union are pressuring pesto manufacturers toward shorter ingredient decks and transparent sourcing, compressing formulation flexibility while opening premium positioning for compliant producers. This regulatory compression is reshaping competitive entry barriers and procurement protocols across Mediterranean supply chains.
Growth Catalysts
- EU Regulation 1169/2011:Mandatory allergen disclosure and ingredient transparency requirements are accelerating reformulation investments among European manufacturers seeking retail shelf access.
- Foodservice menu expansion:North American restaurant operators are integrating pesto-based dishes across pasta, sandwich, and protein categories, broadening volume outlets beyond traditional retail.
- Plant-based dietary frameworks:Vegan pesto formulations are capturing margin expansion as consumer protein diversification creates new premium product tiers.
Market Restraints
- Pine nut price volatility:Harvest fluctuations in Mediterranean growing regions create input cost instability that compresses gross margins for traditional recipes.
- EFSA pesticide residue limits:Stringent maximum residue levels for fresh basil restrict sourcing flexibility and elevate compliance screening costs across European production.
- Substitution threat from compound sauces:Lower-cost emulsified herb blends in foodservice channels displace authentic pesto in price-sensitive volume accounts.
Strategic Opportunities
- US organic certification gap:USDA National Organic Program compliance remains underdeveloped among imported pesto brands, creating first-mover positioning for certified entrants.
- Cold-chain distribution innovation:Refrigerated fresh pesto segments in European supermarkets offer higher per-unit economics than ambient shelf-stable alternatives.
- Technology convergence:High-pressure processing combined with modified atmosphere packaging is extending fresh pesto shelf life without thermal degradation of volatile aromatics.
Industry Challenges
- Basil agronomy expertise scarcity:Cultivation of Genovese DOP basil varieties requires specialized horticultural knowledge that concentrates among Italian growers.
- Co-manufacturing quality variance:Asset-light production arrangements introduce batch consistency risks that threaten brand equity in premium channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pesto Sauces Market |
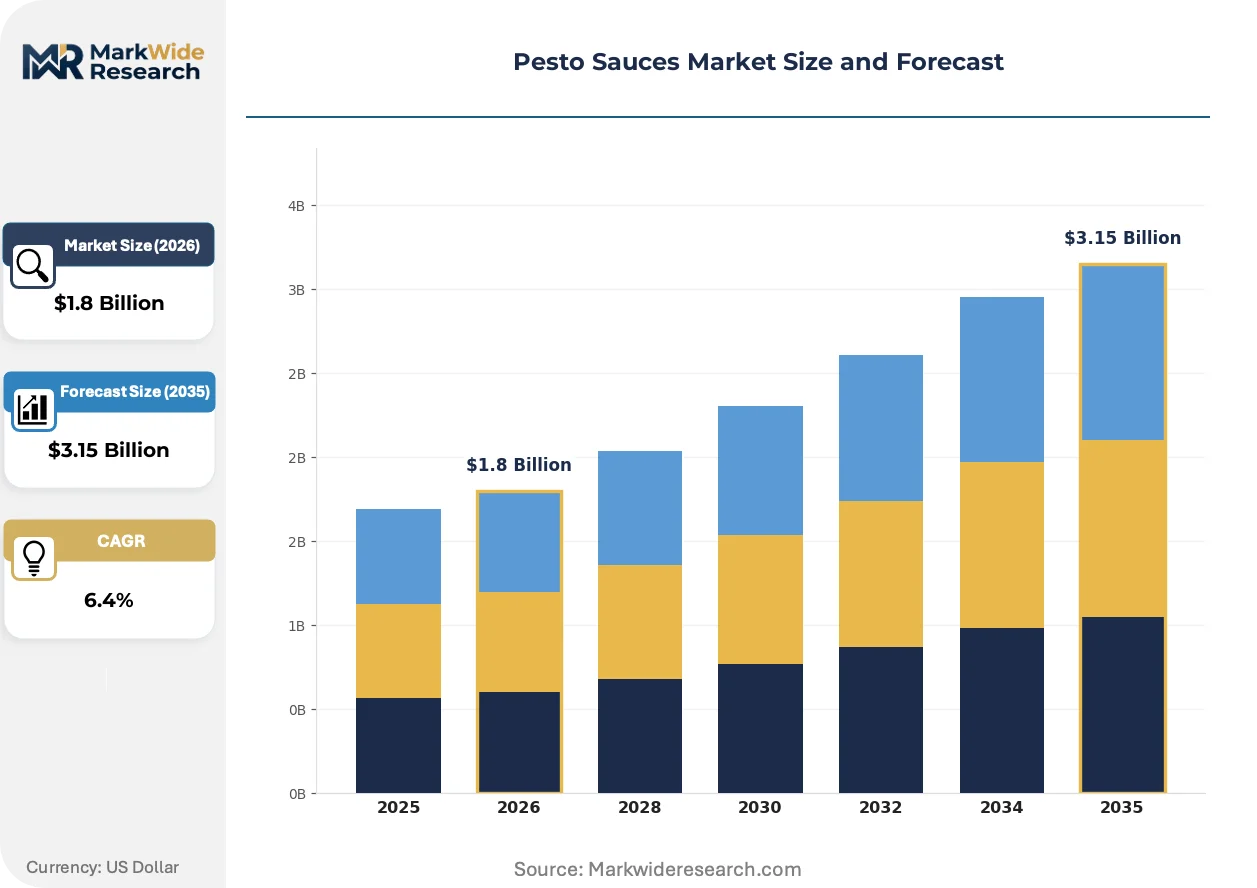
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basil Pesto, Sun-Dried Tomato Pesto, Vegan Pesto, Spicy Pesto Ingredient Type: Organic Ingredients, Non-GMO Ingredients, Gluten-Free Ingredients, Conventional Ingredients Packaging Type: Glass Jar, Plastic Container, Sachet, Tube Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Restaurants |
| Companies Covered | Nestle SA, Buitoni Food Co., Barilla G. e R. Fratelli Spa, F.lli De Cecco di Filippo SpA, Raos Specialty Foods Inc., Unilever PLC, F.lli Sacla Spa, Belazu Ingredient Co., Conagra Brands, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pesto Sauces Market Strategic Shifts
Digital traceability systems and sustainable packaging materials are reconfiguring how pesto manufacturers demonstrate provenance and reduce environmental footprint. These innovations intersect with regulatory compliance and consumer transparency demands.
Spectroscopic quality control systems is digitizing raw material authentication at receiving docks, enabling real-time detection of adulterated olive oils and mislabeled nut varieties. Mid-sized Italian producers are adopting these systems fastest to defend DOP certification integrity. The technology is digitizing supplier verification workflows that previously required weeks of laboratory analysis.
REACH chemical safety registrations for food-contact materials are tightening migration limits for plastic packaging components used in pesto containers. European manufacturers face reformulation deadlines for container resins and sealants. Fresh pesto segments in German and French retail channels are responding by accelerating glass jar transitions ahead of regulatory phase-in.
Direct-to-restaurant procurement platforms are bypassing traditional foodservice distributors for volume pesto contracts. Casual dining chains in the United States are negotiating annual supply agreements directly with Ligurian producers. This channel disintermediation is most visible among mid-scale Italian-American restaurant groups seeking authentic provenance claims.
Pesto Sauces Market Segmentation
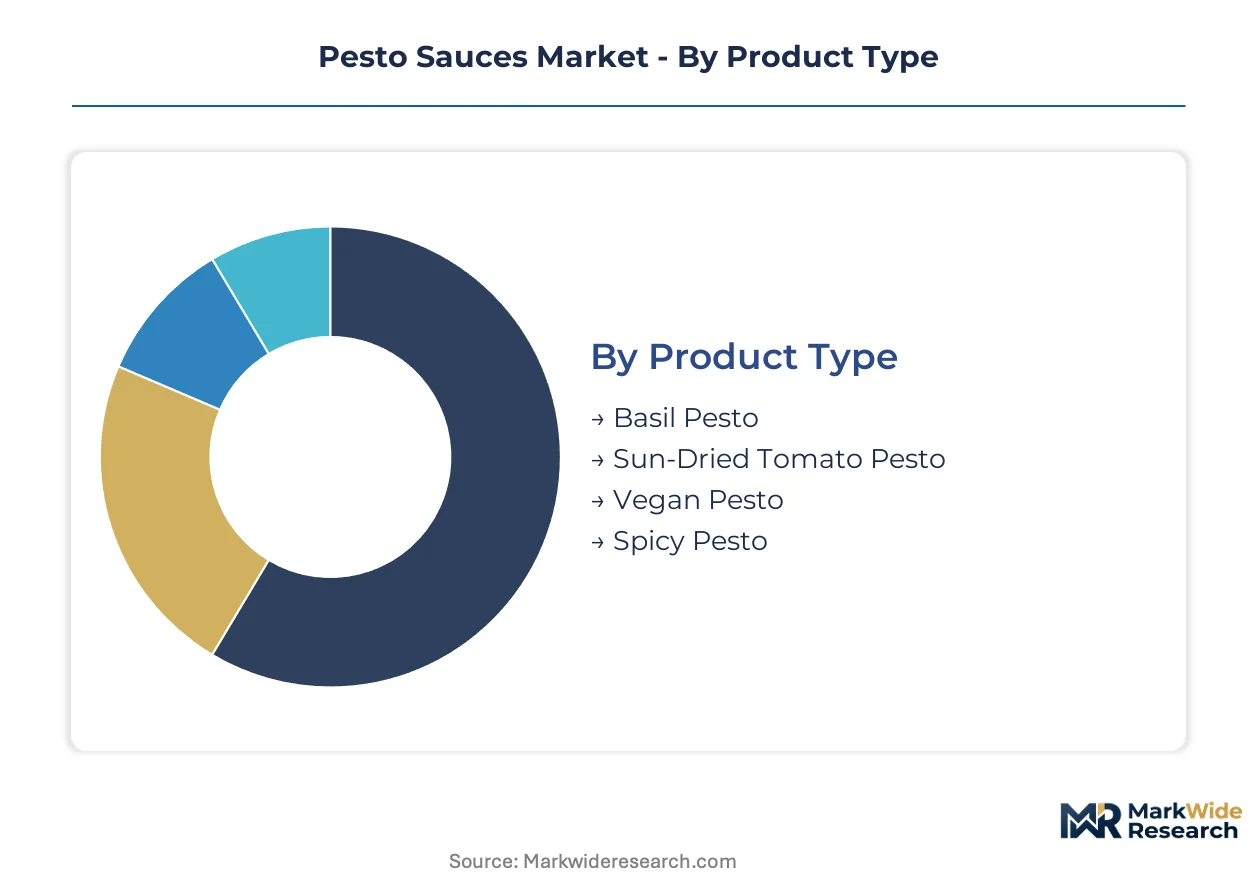
Pesto sauce manufacturers navigate distinct demand profiles across product formulations, ingredient sourcing standards, packaging formats, and channel strategies. Each segmentation axis reveals divergent margin structures and competitive intensity that shape portfolio allocation decisions.
Product Type:
The use-case spectrum spans traditional pasta applications to emerging sandwich spreads and protein marinades across retail and foodservice channels.
- Basil Pesto:Emulsified preparations of crushed Genovese basil, pine nuts, Parmigiano-Reggiano, garlic, and extra virgin olive oil maintain dominant household penetration in Italian and UK retail. Demand concentrates in Mediterranean foodservice accounts seeking authentic provenance credentials, though pine nut price volatility compresses margins for traditional recipes.
- Vegan Pesto:Plant-based formulations substitute nutritional yeast and cashew cream for hard cheese, capturing premium positioning in German and French supermarkets aligned with clean-label dietary frameworks. This segment is expanding most quickly as protein diversification trends reshape European and North American purchasing patterns.
- Sun-Dried Tomato Pesto:Tomato-base variants with reduced basil content offer extended shelf stability and lower input cost structures for price-sensitive volume accounts.
- Spicy Pesto:Calabrian chili-infused formulations target younger demographics in urban US markets seeking flavor intensity differentiation.
The dominant share belongs to Basil Pesto, while Vegan Pesto is closing the gap fastest.
Ingredient Type:
Cost tier stratification separates premium-positioned certified ingredients from conventional sourcing for mainstream supermarket placement.
- Organic Ingredients:USDA National Organic Program and EU organic regulations compliance enables shelf access in Whole Foods Market, Edeka, and Waitrose premium aisles. Sourcing concentrates among contracted Italian growers meeting EFSA pesticide residue limits, with compliance costs creating tiered entry barriers for imported brands.
- Non-GMO Ingredients:Third-party verified non-genetically modified formulations address disclosure requirements under FDA food labeling standards and EU Regulation 1169/2011. Demand clusters in California and Pacific Northwest retail channels with stringent consumer transparency expectations.
- Gluten-Free Ingredients:Certified gluten-free production protocols prevent cross-contamination for celiac-sensitive consumers in UK and Australian markets.
- Conventional Ingredients:Standard agricultural sourcing supports private-label and economy-tier pricing for discount supermarket chains.
Organic Ingredients command the steepest price premium, while Non-GMO Ingredients are gaining shelf space fastest among mid-market retailers.
Packaging Type:
Volume-maturity dynamics separate established ambient-stable formats from emerging fresh segments with distinct cold-chain requirements.
- Glass Jar:Premium positioning in specialty retail channels leverages visual transparency and perceived quality associations; REACH chemical safety registrations are accelerating transitions from plastic alternatives in German and French markets ahead of migration limit deadlines.
- Plastic Container:Polypropylene and PET formats capture cost-sensitive supermarket volumes with lighter logistics profiles; EFSA food-contact material evaluations shape resin selection protocols for European manufacturers.
- Sachet:Single-serve flexible packaging targets foodservice portion control and airline catering contracts.
- Tube:Aluminum-laminate tubes enable precise dispensing for sandwich spread applications in convenience-oriented urban retail.
Glass Jar retains the premium channel majority, though Plastic Container volumes dominate absolute unit sales.
Distribution Channel:
Customer-type concentration distinguishes direct procurement relationships from layered distributor networks across retail and foodservice.
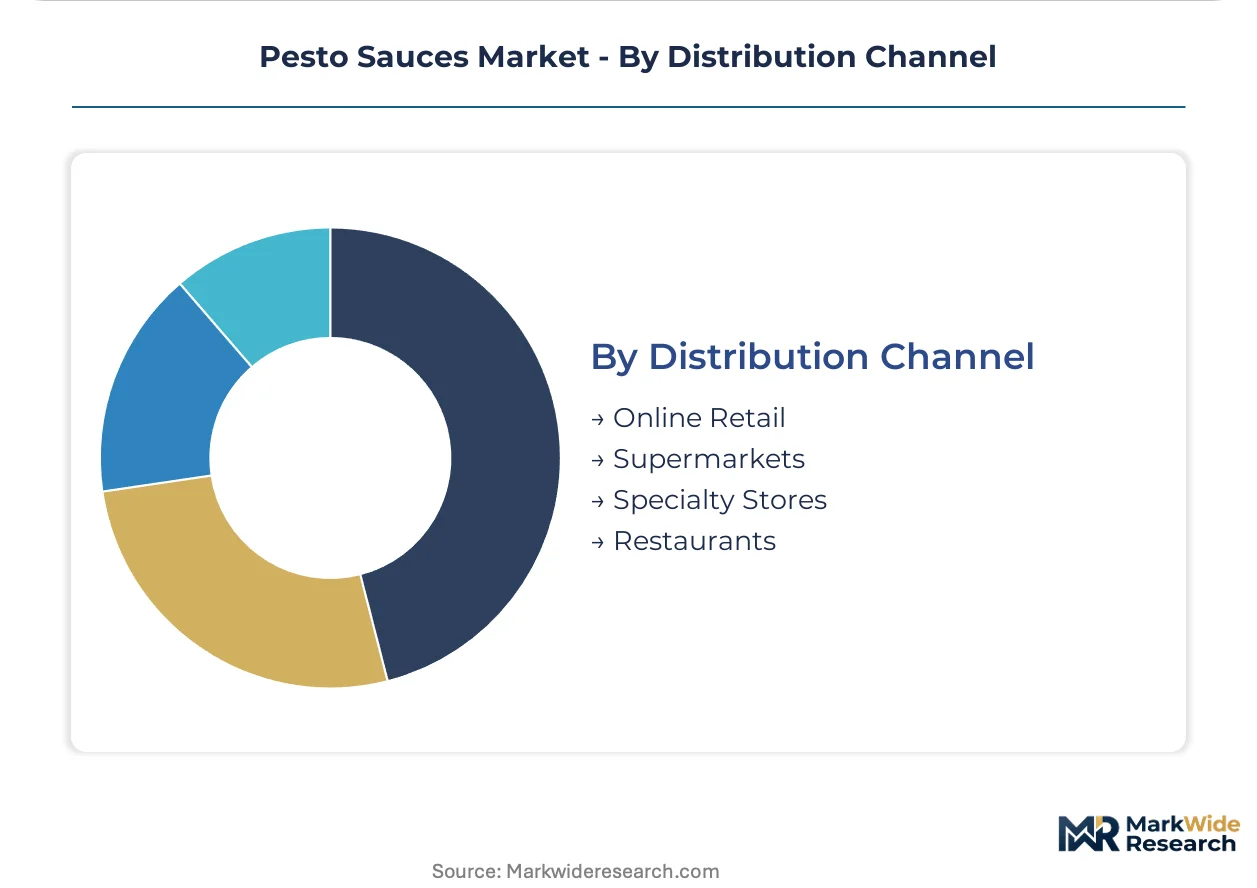
- Supermarkets:Tesco, Carrefour, and Kroger central procurement dictates slotting fee structures and promotional calendar alignment for branded and private-label pesto placement.
- Restaurants:Direct-to-operator procurement platforms are bypassing traditional foodservice distributors for volume contracts with Italian-American restaurant groups seeking Ligurian provenance claims.
- Online Retail:Amazon Fresh and Ocado fulfillment centers require modified atmosphere packaging compatibility for last-mile cold-chain integrity.
- Specialty Stores:Italian delicatessens and gourmet food halls emphasize DOP certification and small-batch production narratives.
Supermarkets anchor volume throughput, while Restaurants are shifting procurement patterns fastest through channel disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Regulation 1169/2011 on food information to consumers is reshaping formulation standards across Mediterranean supply chains, while FDA allergen disclosure rules govern transatlantic trade flows. National organic certification programs in Italy and the United States are creating tiered market access thresholds that concentrate premium production in specific growing regions.
Italy
Genovese DOP basil cultivation in Liguria anchors authentic provenance positioning for premium export channels. EFSA pesticide residue limits for fresh basil restrict sourcing flexibility, elevating compliance costs for non-certified growers. Production clusters concentrate around Genoa and Imperia provinces, where stone-grinding traditions preserve volatile aromatic compounds for specialty retail.
United States
USDA National Organic Program certification unlocks shelf access in Whole Foods Market and regional premium chains across California and the Pacific Northwest. FDA food labeling requirements mandate allergen warnings for tree nut content, compressing formulation flexibility for traditional pine nut recipes. Foodservice procurement platforms in New York and Chicago metro areas are negotiating direct supply agreements with Mediterranean producers.
Germany
REACH chemical safety registrations for food-contact materials are accelerating glass jar transitions ahead of plastic migration limit deadlines. Edeka and Aldi central procurement dictates promotional calendar alignment for both branded and private-label placement. Fresh pesto segments in Bavaria and Baden-Württemberg retail channels command higher per-unit economics than ambient alternatives.
United Kingdom
Tesco and Sainsbury's slotting fee structures shape competitive dynamics for both mainstream and specialty pesto placement. FSA allergen labeling guidance aligns with EU Regulation 1169/2011 implementation, maintaining disclosure consistency post-Brexit. London-based Italian delicatessens emphasize DOP certification narratives for affluent urban consumers seeking authentic provenance.
France
ANSM food safety evaluations intersect with EFSA basil residue protocols to elevate screening costs for imported raw materials. Carrefour and Intermarché procurement teams are expanding refrigerated fresh pesto sets in Île-de-France and Auvergne-Rhône-Alpes hypermarkets. Vegan pesto formulations capture premium positioning in Parisian bio-specialty channels aligned with plant-based dietary frameworks.
Pesto Sauces Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated milling operations and specialized regional recipe specialists. Three strategic archetypes dominate: multinational CPG conglomerates with cold-chain distribution scale, Italian family-owned producers with DOP certification heritage, and private-label specialists leveraging asset-light co-manufacturing. Competitive moves center on backward integration into basil cultivation and technology licensing for high-pressure processing shelf-life extension.
Among Italy-based heritage producers, Barilla G. e R. Fratelli Spa and F.lli Sacla Spa exemplify the DOP-certified archetype, occupying positions anchored in regional recipe authenticity. Nestle SA represents the multinational scale tier, sitting within cold-chain distribution networks spanning European supermarket channels. These three entities illustrate the competitive tension between provenance narrative and operational scale that defines category dynamics.
| Leading Market Players |
|---|
| Nestle SA |
| Buitoni Food Co. |
| Barilla G. e R. Fratelli Spa |
| F.lli De Cecco di Filippo SpA |
| Raos Specialty Foods Inc. |
| Unilever PLC |
| F.lli Sacla Spa |
| Belazu Ingredient Co. |
| Conagra Brands, Inc. |
| Others |
Value Chain & Pricing Dynamics
Pine nut price volatility in Mediterranean growing regions compresses gross margins for traditional basil pesto recipes while simultaneously determining tier spreads between premium DOP-certified and economy private-label offerings. This commodity exposure forces manufacturers to either absorb cost swings or reformulate toward alternative tree nuts, reshaping procurement networks toward more diversified sourcing geographies.
Pricing Analysis
Certification level creates the primary spread between organic EU-compliant formulations and conventional private-label alternatives. Three-tier pricing structure across premium DOP-certified, standard commercial-grade, and economy private-label levels separates shelf positioning in European supermarkets. Pricing pressure stems from EFSA pesticide residue compliance costs elevating organic input premiums. Foodservice operators exhibit highest price sensitivity, while specialty retail channels absorb premium markups for provenance narratives.
Supply Chain Analysis
EU Regulation 1169/2011 allergen disclosure requirements and REACH chemical safety registrations for food-contact materials restrict cross-border flow of non-compliant packaging and ingredient formulations. Raw material sourcing concentrates in Italy, Spain, and Greece for basil cultivation, with pine nut supply anchored in Turkey and Portugal. Stone-grinding equipment and Genovese DOP seed stock dependencies create single-source vulnerability for authentic production. Distribution runs through cold-chain networks for fresh segments and ambient logistics for shelf-stable glass jar formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compound sauce substitutes threaten authentic pesto displacement in price-sensitive foodservice accounts, forcing incumbents to defend provenance positioning while entrants identify certification gaps.
For Market Incumbents: Insulate market position through backward integration into contracted Genovese DOP basil cultivation in Liguria, eliminating third-party supply variance. Pursue high-pressure processing technology licensing to extend fresh pesto shelf life without thermal degradation, capturing refrigerated segment premiums. These moves counter private-label erosion and co-manufacturing quality risks. For New Entrants and Emerging Players: USDA National Organic Program certification gaps among imported brands present white-space opportunity in California and Pacific Northwest premium retail. Vegan pesto formulations in German bio-specialty channels offer fastest margin expansion with lower competitive density. Direct-to-restaurant procurement platforms bypass entrenched distributor relationships for Italian-American restaurant group contracts. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-sized Italian heritage producers with DOP certification and cold-chain distribution scale. Long-term viability hinges on clean-label regulatory compliance and plant-based portfolio expansion. Watch EFSA pesticide residue limit tightening as inflection indicator for organic input cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Basil Cultivation | Captive supply of Genovese DOP varieties secures provenance credentials against co-manufacturing variance risks. |
| High-Pressure Processing Technology Licensing | Extended fresh pesto shelf life enables refrigerated segment expansion in Edeka and Carrefour channels. |
| USDA Organic Certification Investment | First-mover positioning in Whole Foods Market and regional premium chains unlocks underpenetrated US retail. |
| Direct-to-Restaurant Procurement Platform | Bypassing traditional foodservice distributors captures volume contracts with Italian-American restaurant groups. |
| Vegan Formulation Portfolio Expansion | Plant-based recipes capture premium positioning in German and French bio-specialty retail aligned with protein diversification. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with pesto manufacturing executives, retail category buyers at Tesco and Carrefour, foodservice procurement directors, and Italian agricultural cooperative managers; and secondary validation through EU Regulation 1169/2011 compliance filings, EFSA pesticide residue evaluations, USDA National Organic Program certification records, and customs trade data for Mediterranean basil and pine nut flows. Bottom-up volume triangulation across product type, ingredient certification, packaging format, and distribution channel segments converged with top-down market sizing.
Forecast inputs span formulation type, certification tier, packaging technology, and regional regulatory cluster across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs include EFSA residue limit evolution, REACH chemical safety registration timelines, and cold-chain infrastructure penetration in European retail.
Macroeconomic conditions sit as an overlay; deviation in olive oil commodity prices, Mediterranean harvest yields, or transatlantic tariff structures would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory stability and consumer clean-label preference persistence. Material shifts in EU organic certification requirements or US FDA allergen disclosure rules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Sandwich Spread Market
Condiments & Sauces
Salad Dressings and Mayonnaise Market
Condiments & Sauces
Ketchup Market
Condiments & Sauces
Vegan Cheese Sauce Market
Condiments & Sauces
West Africa Mayonnaise Market
Condiments & Sauces
Ketchup Concentrates Market
Condiments & Sauces
Culinary Sauces Market
Condiments & Sauces
Vegan Pasta Sauce Market
Condiments & Sauces
Asia Pacific Fish Sauce Market
Condiments & Sauces
GCC Condiment Sauces (for Hospitality Sector) Market
Condiments & Sauces
Pasta Sauce Market
Condiments & Sauces
Low Fat Mayo Market
Condiments & Sauces
Hot Sauce Market
Condiments & Sauces
Europe Gluten-Free Soups and Sauces Market
Condiments & Sauces
Cheese Sauce Market
Condiments & Sauces
Prepared Mustard Market