
 Global Ceramic and Porcelain Tiles Market | 2026-2036
Global Ceramic and Porcelain Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ceramic and Porcelain Tiles Market Foresight
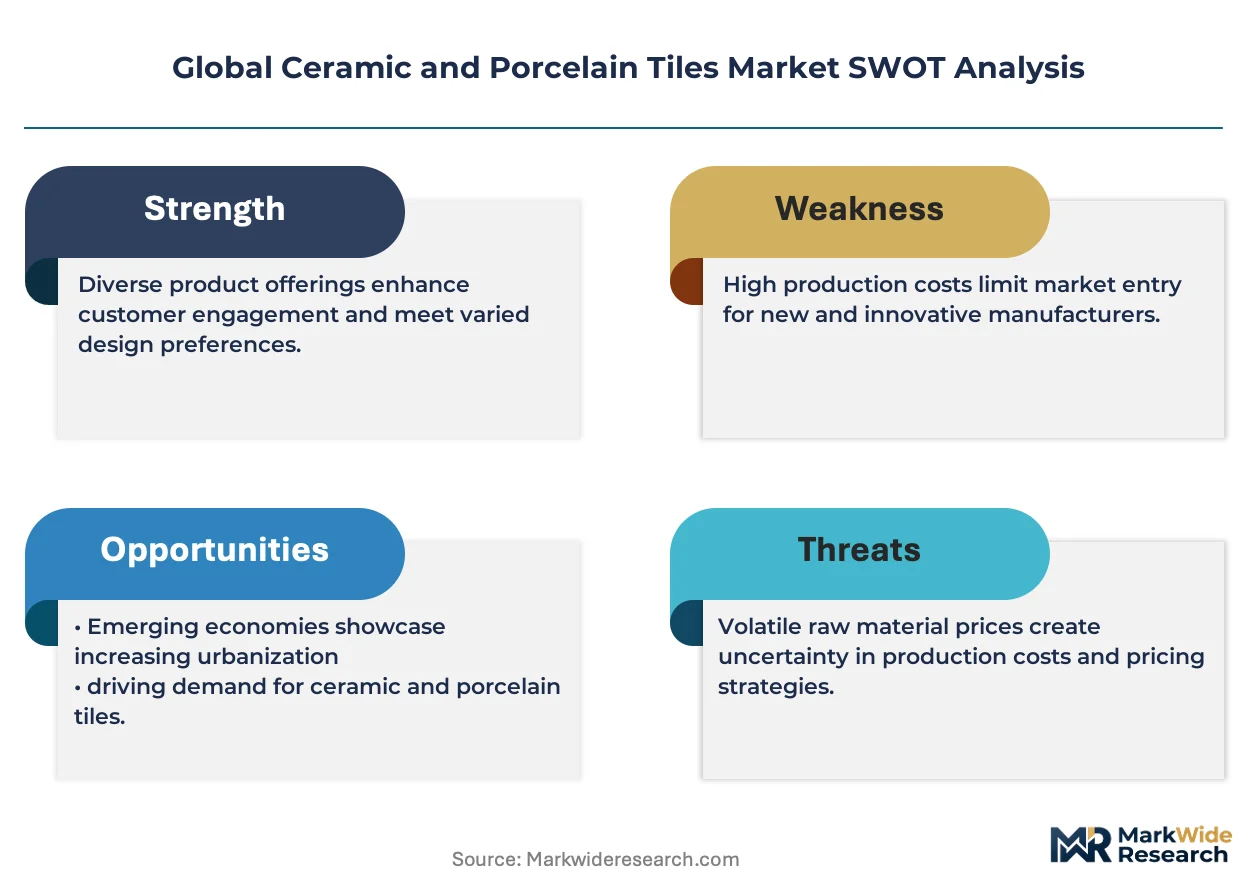
REACH compliance is restructuring the cost-of-entry calculus for European tile imports, forcing reformulation of glaze chemistries and third-party certification spend. Mohawk Industries leverages vertical integration across North American clay reserves to buffer raw material volatility. RAK Ceramics anchors production scale in the UAE, while Porcelanosa Grupo differentiates through design-forward glazed porcelain positioning in premium hospitality channels.
Ceramic and porcelain tiles are sintered clay-based surfacing materials fired at 1,100–1,400°C, with porcelain achieving <0.5% water absorption through denser vitrification; their primary purpose is to provide durable, chemically resistant finishes for interior and exterior built environments. Glazed porcelain commands margin pools in commercial flooring due to superior stain resistance and lower lifecycle replacement rates. Residential buildings remain the volume anchor, though hospitality venues represent the fastest-growing end-user category as hotel renovation cycles compress globally.
EMA chemical safety protocols, EPA air quality standards for kiln emissions, and India's BIS certification for ceramic product durability collectively shape manufacturing investment priorities and market access conditions across the three largest producing blocs. Stakeholders must monitor how carbon border adjustments and evolving slip-resistance grading standards reshape competitive positioning in export-dependent supply corridors.
Market Dynamics
The EU Green Deal's embodied carbon thresholds are forcing kiln fuel switching and clinker substitution across European manufacturing, while India's western ceramic clusters absorb displaced export volume through BIS-certified production scale.
Growth Catalysts
- Commercial floor coverage expansion:Southeast Asian hospitality and retail complexes are specifying large-format glazed porcelain for high-traffic zones, pulling volume from traditional ceramic alternatives.
- REACH glaze chemistry reformulation:ECHA compliance mandates are accelerating lead-free and low-cadmium frit development, creating certified product premiums in EU import channels.
- Compressed hotel renovation cycles:Global hospitality operators are shortening replacement intervals for guest room and lobby surfacing, concentrating demand in stain-resistant porcelain categories.
Market Restraints
- Natural gas price volatility:Kiln firing costs constitute 35-45% of tile production economics, exposing margins to European and Asian spot market swings.
- Western India supply concentration:Gujarat and Rajasthan clusters control over 60% of India's export-grade output, creating single-point vulnerability to monsoon logistics disruption.
- Thin-profile large-format technical limits:Sub-6mm porcelain slabs face breakage rates above 8% in standard handling, constraining adoption in renovation applications.
Strategic Opportunities
- Carbon border adjustment arbitrage:EU CBAM phase-in creates first-mover advantage for Turkish and Moroccan producers with verified low-carbon process documentation.
- Cool roof tile mandates:California Title 24 and similar building codes in Australia are specifying high solar reflectance index (SRI) surfaces for commercial structures.
- Digital inkjet-press hybrid systems:Convergence of single-pass decoration and in-line quality inspection enables batch-size-one production economics for architectural specification channels.
Industry Challenges
- Glaze chemist talent scarcity:Formulation expertise for lead-free, high-abrasion frits is concentrated among retiring European specialists, constraining R&D velocity.
- Continuous roller kiln capex intensity:Sub-3mm large-format production requires 80-meter-plus firing lines exceeding $15 million per installed unit.
- Slip-resistance certification fragmentation:Divergent DIN, ASTM, and pendulum test protocols force parallel testing regimes for multi-territory projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ceramic and Porcelain Tiles Market |
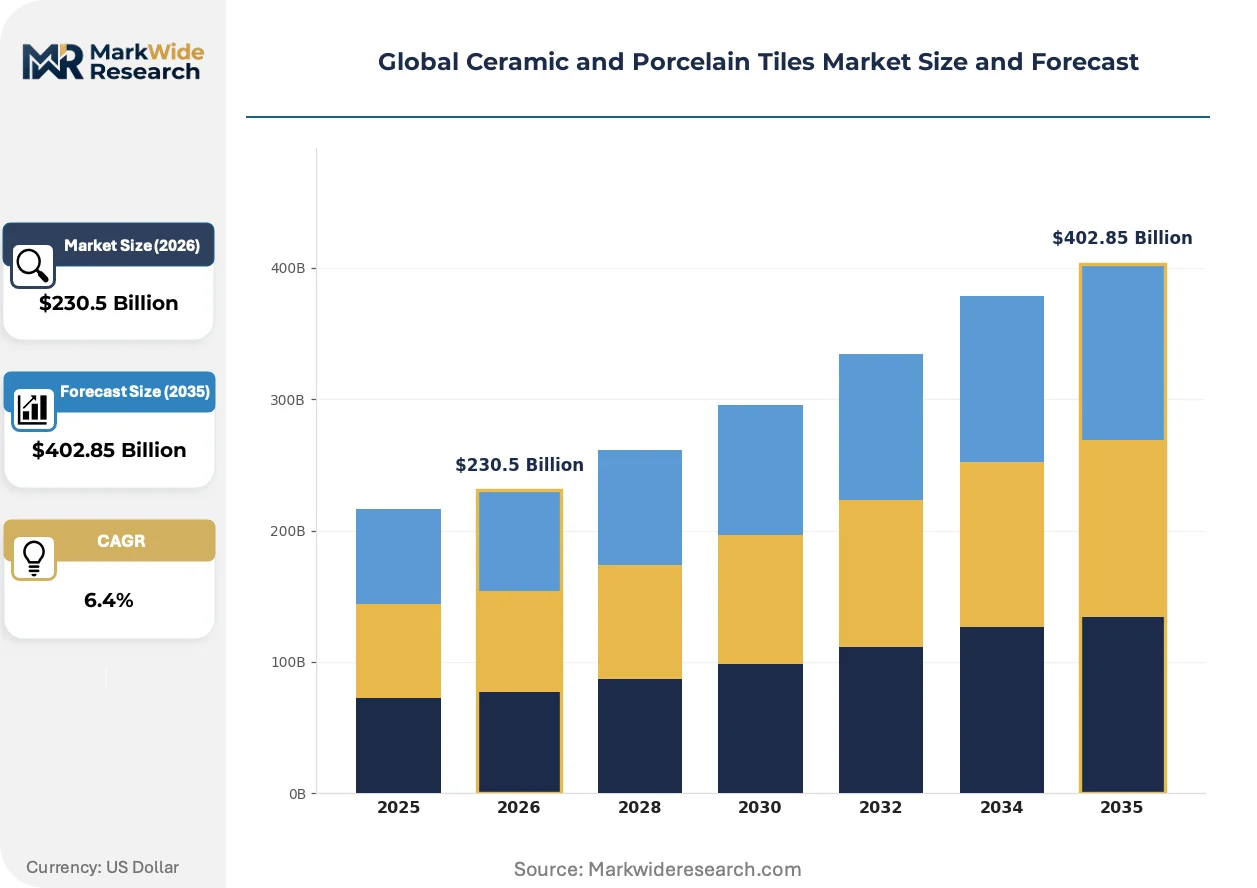
| Market Size in 2026 | $230.5 Billion |
| Market Size in 2035 | $402.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed Ceramic, Unglazed Ceramic, Full Body Porcelain, Glazed Porcelain, Polished Porcelain Application: Flooring, Wall Cladding, Countertops, Backsplash, Outdoor Paving Installation Method: Thin-set Mortar, Mud-set, Click-lock, Adhesive Tape, Interlocking System End User: Residential Buildings, Commercial Complexes, Institutional Facilities, Hospitality Venues, Government Projects |
| Companies Covered | RAK Ceramics, Florim Ceramiche, Mohawk Industries, Atlas Concorde, Lasselsberger Group, Grupo Lamosa, Kajaria Ceramics, Monalisa Tiles, Porcelanosa Grupo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ceramic and Porcelain Tiles Market Shifts & Advancements
Digital decoration and low-carbon process engineering are converging to compress batch economics and expand specification-grade output from non-traditional supply bases.
Single-pass inkjet decoration combined with in-line surface profiling is rewriting cost structures for custom architectural tile runs. Boutique hotel chains and high-end residential developers are adopting these digitally printed surfaces at triple-digit annual growth rates. The technology is compressing minimum order quantities from 500 square meters to under 50, enabling distributed manufacturing models.
REACH Annex XVII restrictions on heavy metals in consumer goods are tightening glaze composition standards for all EU-bound ceramic surfacing. Manufacturers must reformulate frit chemistries and absorb third-party certification costs averaging 3-5% of export invoice value. Italian and Spanish producers with in-house R&D facilities are capturing specification share from import-dependent distributors.
Architects and commercial contractors are consolidating procurement through direct mill relationships, bypassing traditional distributor markups. Large-format porcelain slabs for facade cladding are moving through specification channels where technical documentation and warranty terms outweigh price sensitivity. This consolidation is most visible in German and Dutch commercial construction markets where DGNB and BREEAM certification requirements demand traceable supply chain documentation.
Global Ceramic and Porcelain Tiles Market Segmentation
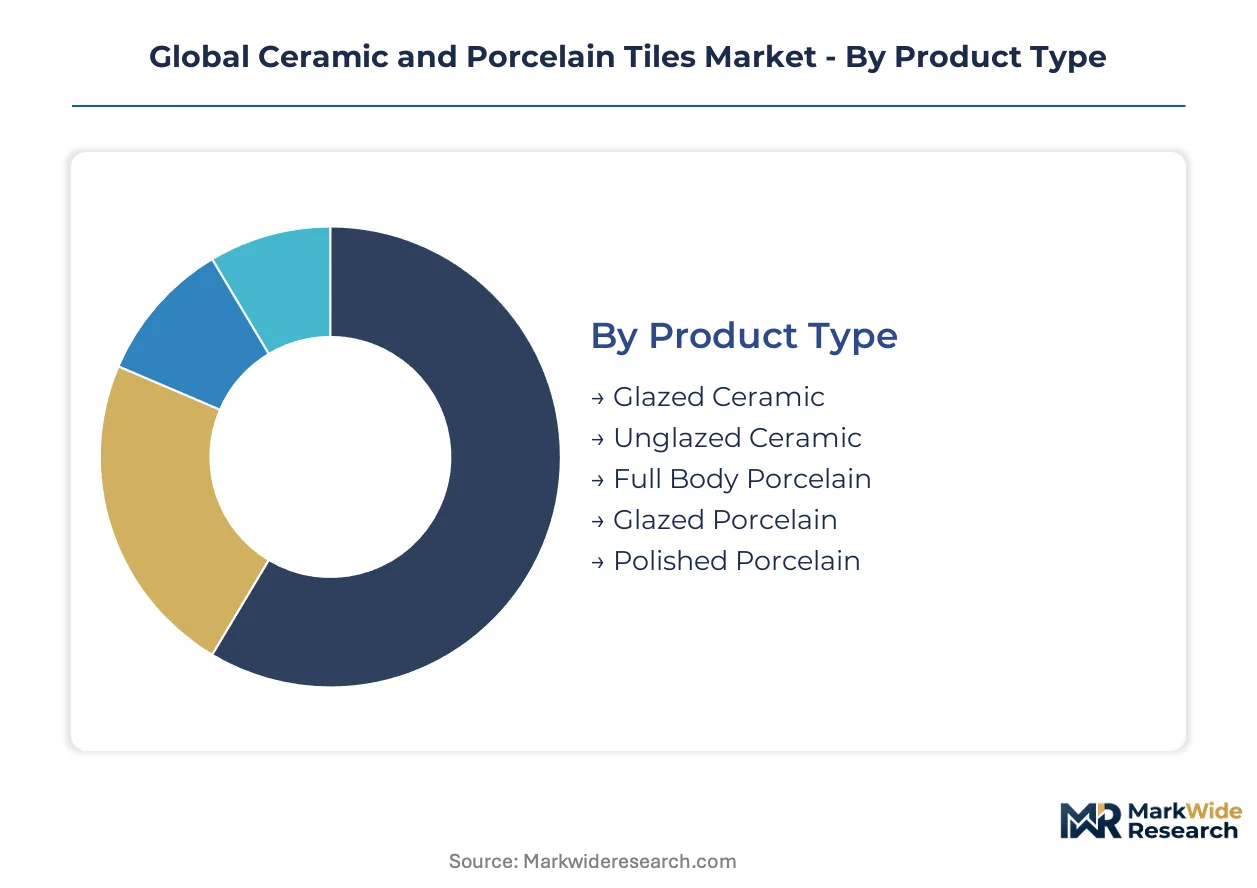
Segmentation in ceramic and porcelain tiles reveals how technical specifications, installation constraints, and end-use durability requirements split manufacturing investment and margin capture across fundamentally different demand pools. Understanding these divides exposes where specification-grade premiums concentrate versus where volume throughput dominates procurement economics.
Product Type:
Volume production clusters around ceramic grades fired at lower temperatures, while porcelain categories command specification premiums through denser vitrification and superior abrasion resistance.
- Glazed Ceramic:Clay bodies fired at 1,100–1,200°C with glass-forming surface coatings provide cost-efficient interior wall and light-traffic flooring solutions. Residential renovation demand in India's Gujarat cluster absorbs bulk output, though REACH glaze reformulation is compressing margins on EU-bound shipments.
- Full Body Porcelain:Homogeneous composition through the full tile thickness enables heavy-traffic performance without surface glaze dependency. Commercial flooring specifications in German hospital and airport projects favor this grade for lifecycle replacement cost minimization.
- Unglazed Ceramic:Absorptive clay bodies suit outdoor paving where freeze-thaw cycling demands permeability; quarry tile variants serve California Title 24 cool roof mandates.
- Glazed Porcelain:Vitrified substrates with decorative surfaces combine stain resistance with design flexibility; hospitality renovation cycles in Dubai and Singapore concentrate procurement here.
- Polished Porcelain:Surface grinding after firing yields mirror finishes for premium residential and lobby applications; breakage sensitivity in large-format formats constrains renovation adoption.
Today's leader: Glazed Porcelain. Tomorrow's challenger: Full Body Porcelain.
Application:
Installation environment dictates performance specifications, with exterior and wet-zone applications demanding water absorption thresholds below 0.5% that only porcelain achieves consistently.
- Flooring:The dominant volume application spanning residential, commercial, and institutional traffic levels. Slip-resistance certification fragmentation across DIN, ASTM, and pendulum protocols forces parallel testing for multi-territory hospitality projects.
- Wall Cladding:Large-format thin porcelain slabs for facade systems require specialized anchoring engineering; BREEAM and DGNB certification in Dutch and German markets demands traceable supply chain documentation.
- Countertops:Thickness requirements above 12mm and stain resistance specifications favor full-body porcelain; Italian producers with in-house R&D capture specification share from import-dependent distributors.
- Backsplash:Smaller format tiles with decorative glaze chemistry dominate residential kitchen and bathroom segments; digital inkjet decoration enables batch-size-one economics for custom architectural runs.
- Outdoor Paving:Frost resistance and anti-slip surface profiling are mandatory; cool roof tile mandates in California and Australia specify high solar reflectance index surfaces.
Flooring anchors current volume. Wall cladding is climbing the fastest as facade specification channels consolidate procurement through direct mill relationships.
Installation Method:
Substrate preparation requirements and skilled labor availability determine method selection, with thin-set dominating new construction and click-lock systems penetrating renovation markets.
- Thin-set Mortar:Cementitious bonding layers applied with notched trowels remain standard for porcelain tiles over concrete substrates; curing time requirements constrain fast-track commercial schedules.
- Mud-set:Thick mortar beds with wire reinforcement provide leveling tolerance for uneven substrates; institutional and heritage restoration projects in Italy and Spain specify this method for dimensional stability.
- Click-lock:Interlocking edge profiles enable floating floor installation without adhesive; residential renovation demand in North American markets favors speed-of-installation over maximum durability.
- Adhesive Tape:Pressure-sensitive systems for lightweight ceramic wall tiles; DIY retail channels in UK and Australian markets stock these for consumer bathroom refreshes.
- Interlocking System:Pedestal-mounted pavers for rooftop and terrace applications; commercial complexes across Southeast Asia specify these for drainage and accessibility compliance.
Thin-set Mortar retains specification authority. Click-lock is gaining share fastest as renovation cycles compress and labor scarcity intensifies.
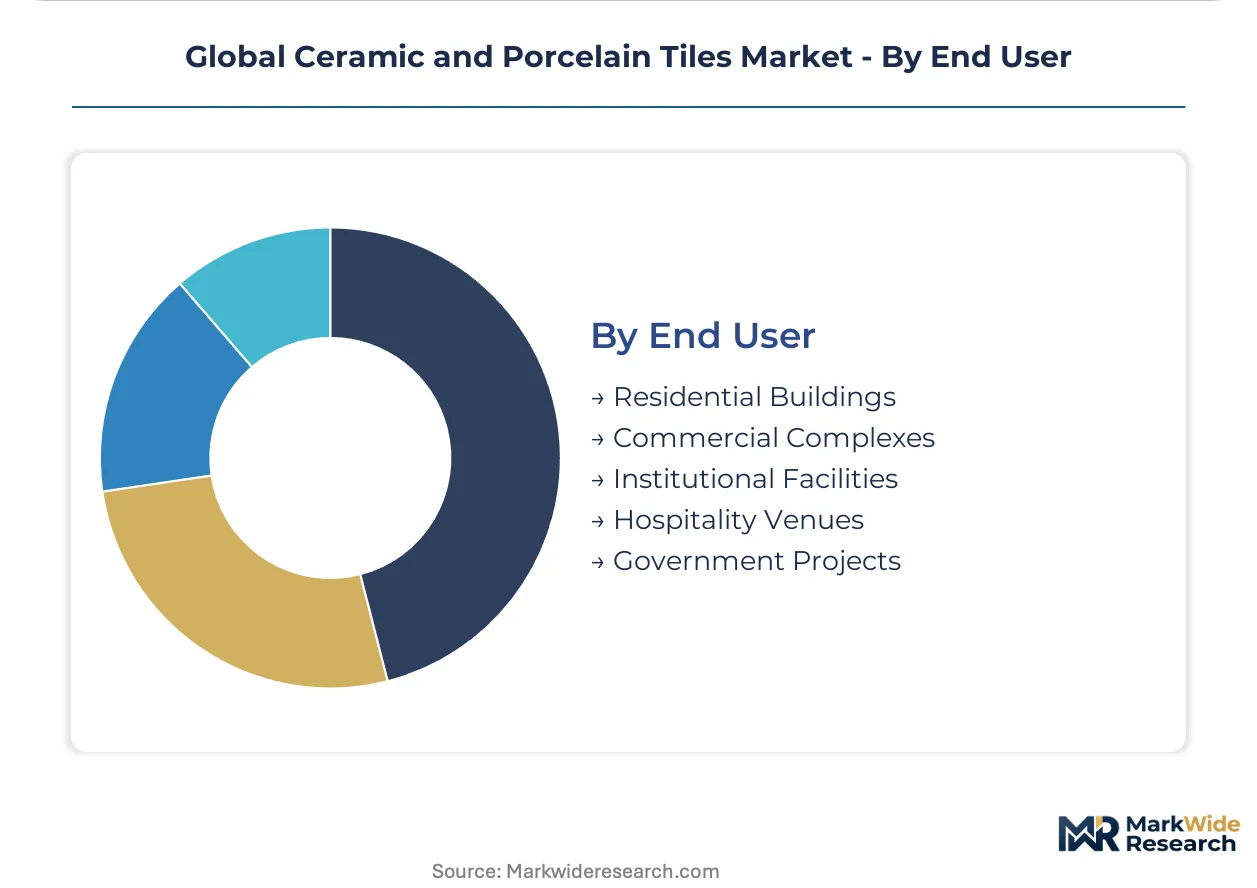
End User:
Procurement sophistication varies dramatically, with hospitality and government segments demanding certified documentation while residential buyers prioritize installed cost per square meter.
- Residential Buildings:Volume anchor segment where price sensitivity dominates and distributor markups structure final consumer pricing; India's western ceramic clusters supply export-grade output through BIS-certified production scale.
- Hospitality Venues:Compressed renovation cycles for guest rooms and lobbies concentrate demand in stain-resistant glazed porcelain; global hotel operators are shortening replacement intervals, expanding specification-grade procurement.
- Commercial Complexes:Southeast Asian retail and office developments are expanding floor coverage requirements, pulling volume toward large-format glazed porcelain for high-traffic zones.
- Institutional Facilities:Healthcare and education procurement demands lifecycle cost documentation and slip-resistance certification; EPA air quality standards for kiln emissions shape supplier qualification.
- Government Projects:Public procurement regulations in EU member states and India require local content verification and embodied carbon disclosure; EU Green Deal thresholds are forcing fuel switching documentation.
Residential Buildings anchor volume throughput. Hospitality Venues show the steepest expansion trajectory as hotel renovation cycles compress globally.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled glaze chemists and kiln engineers concentrate in European ceramic districts and India's western industrial corridors, anchoring production expertise in these geographies while Southeast Asian markets absorb expanding commercial floor coverage.
China
Foshan and Zibo ceramic clusters supply over half of global tile export volume, with digital inkjet decoration systems penetrating mid-tier factories. GB standards for building materials enforce water absorption and abrasion resistance thresholds. The Pearl River Delta concentrates glazed porcelain capacity serving hospitality renovation demand across Southeast Asia.
India
Gujarat and Rajasthan ceramic clusters control BIS-certified export-grade production, with Morbi township alone housing over 700 manufacturing units. The Bureau of Indian Standards mandates durability testing for ceramic product certification. Western Indian infrastructure supports containerized shipment scale to Middle Eastern and African markets.
Italy
Sassuolo district retains the densest concentration of ceramic R&D facilities and digital decoration technology suppliers. REACH Annex XVII compliance drives lead-free frit formulation investment. Emilia-Romagna's producer network captures specification share in German and Dutch BREEAM-certified commercial projects.
United States
Residential renovation demand concentrates in Sun Belt metros, with distributor consolidation reshaping procurement channels. EPA air quality standards for kiln emissions constrain greenfield manufacturing investment. Mohawk Industries leverages captive clay reserves across Georgia and Tennessee to buffer raw material cost volatility.
United Arab Emirates
Dubai and Sharjah logistics hubs position tile re-export operations for Saudi and Egyptian construction markets. MOHAP building material safety protocols govern product import documentation. RAK Ceramics anchors production scale in Ras Al Khaimah emirate, supplying large-format glazed porcelain to Gulf hospitality developments.
Global Ceramic and Porcelain Tiles Market Competitive Landscape
The competitive structure tilts toward vertically integrated conglomerates with captive raw material positions and design-forward specialists commanding specification premiums. Tiered concentration separates scale-driven volume producers from boutique architectural suppliers. Dominant archetypes include clay-reserve-integrated multinationals, digital decoration technology leaders, and regionally anchored export platforms. Capacity expansion and strategic technology licensing represent the primary competitive moves reshaping market positioning.
Within the design-forward specialist tier, Porcelanosa Grupo exemplifies premium hospitality channel positioning, while Florim Ceramiche and Atlas Concorde occupy comparable specification-grade territory. Among emerging market scale players, Kajaria Ceramics represents the Indian export platform archetype. Mohawk Industries anchors the North American integrated producer category. RAK Ceramics sits within the Middle East logistics-hub producer segment.
| Leading Market Players |
|---|
| RAK Ceramics |
| Florim Ceramiche |
| Mohawk Industries |
| Atlas Concorde |
| Lasselsberger Group |
| Grupo Lamosa |
| Kajaria Ceramics |
| Monalisa Tiles |
| Porcelanosa Grupo |
| Others |
Supply & Pricing Matrix
EU Green Deal embodied carbon thresholds gate qualified supply access and premium-tier pricing power, forcing kiln fuel documentation and clinker substitution investments that stratify producers into certified export-eligible tiers versus spot-market commodity suppliers. Buyers in German BREEAM-certified commercial projects pay specification premiums for traceable low-carbon process documentation, while price-sensitive residential renovation demand in India's western clusters absorbs undifferentiated volume through BIS-certified production scale.
Pricing Analysis
Project-based bundled contracts dominate hospitality and institutional procurement, unbundled spot transactions serve residential renovation channels. Three-tier pricing structure across premium, standard, and economy levels separates DGNB-certified facade porcelain from BIS-certified export ceramic and undifferentiated domestic wall tile. Cost compression in standard-grade ceramic is intensifying because Gujarat cluster overcapacity and European gas price volatility squeeze firing economics. Residential buyers in North American Sun Belt metros exhibit highest price sensitivity; German hospital procurement committees demonstrate lowest sensitivity due to lifecycle cost documentation requirements.
Supply Chain Analysis
Direct-to-specifier channels handle architectural-grade porcelain demand, distributor networks push volume ceramic through retail. Raw material sourcing concentrates in India, China, and Italy; Gujarat and Rajasthan clusters control over sixty percent of BIS-certified export-grade output, while Sassuolo district anchors European glaze chemistry R&D. Production draws from captive clay reserves, imported frit formulations, and natural gas feedstock. Single-source vulnerability to monsoon logistics disruption in western India creates supply chain risk. Distribution runs through containerized port infrastructure at Jebel Ali, Rotterdam, and Savannah.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU carbon border adjustment phase-in against India's BIS-certified low-cost export scale creates geographic-arbitrage conditions for Turkish and Moroccan producers with verified process documentation. Cost differentials between European kiln fuel switching investments and Gulf-subsidized natural gas feedstock anchor this spread.
For Market Incumbents: Deploy backward integration into captive clay reserves to buffer raw material volatility. Mohawk Industries exemplifies this lever through Georgia and Tennessee reserve control. Consolidate specification share in German and Dutch BREEAM-certified channels by investing in REACH Annex XVII-compliant frit R&D facilities. Threat from compressed hotel renovation cycles demands stain-resistant glazed porcelain capacity expansion in Ras Al Khaimah and Sharjah logistics corridors. For New Entrants and Emerging Players: Begin with digital inkjet-press hybrid systems for batch-size-one architectural specification runs. Boutique hotel chains and high-end residential developers represent most penetrable demand pool. Target cool roof tile mandates in California Title 24 and Australian commercial building codes as go-to-market angle, leveraging high solar reflectance index surface engineering. For Investors and Strategic Acquirers: Roll-up economics work for Italian and Spanish design-forward specialists because REACH compliance mandates and glaze chemist talent scarcity create acquisition currency for in-house R&D capabilities. Long-term viability hinges on carbon border adjustment arbitrage window duration. Monitor EU CBAM implementation pace and Turkish producer low-carbon process documentation penetration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Clay Reserves | Mohawk Industries leverages captive Georgia and Tennessee reserves to buffer raw material cost volatility. |
| REACH-Compliant Frit R&D Investment | Italian Sassuolo district producers capture specification share through lead-free glaze chemistry development. |
| Digital Inkjet-Press Hybrid Deployment | Single-pass decoration systems compress batch economics for architectural specification channels. |
| Low-Carbon Process Documentation | Turkish and Moroccan producers gain EU CBAM phase-in advantage with verified kiln fuel switching records. |
| Cool Roof Tile Certification | California Title 24 and Australian building codes mandate high SRI surfaces for commercial structures. |
Research Methodology
Coverage spans India, China, Italy, United Arab Emirates, and United States, with primary inputs from each ceramic-producing corridor. Plant managers at Gujarat cluster facilities, procurement leads at German hospital systems, distribution channel partners in Dubai logistics hubs, and technical R&D directors in Sassuolo district provided qualitative grounding. Secondary validation drew from BIS certification records, REACH Annex XVII filings, EPA air quality compliance disclosures, and customs trade data. Bottom-up production capacity tallies and top-down end-use demand estimates were triangulated against cluster-level output figures.
Rate-of-change decomposition across the analysis window separates volume growth from value mix shifts. Segmentation dimensions modeled include product type, application, installation method, and end-user procurement sophistication. CAGRs were derived from production capacity expansion schedules, renovation cycle compression rates in hospitality, and embodied carbon threshold implementation timelines. Forecast inputs incorporated natural gas price volatility scenarios and monsoon logistics disruption frequency in western India.
Several conditions sit outside the modeled scope, including sudden regulatory reversals on EU CBAM timing, breakthroughs in thin-profile large-format handling technology, and geopolitical trade route disruptions affecting Jebel Ali re-export volumes. Forecasts reflect assumptions about sustained hospitality renovation demand and REACH compliance cost pass-through rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramic Armor Materials Market
Ceramics
Europe Activated Alumina Market
Ceramics
Philippines Ceramic Tiles Market
Ceramics
Hot-Pressed Aluminum Titanate Ceramics Market
Ceramics
India Kaolin Market
Ceramics
Ceramic Sanitary Ware Market
Ceramics
Co-Fired Ceramic Market
Ceramics
Global Ceramic Tube Market
Ceramics
Methyl Silicate Market
Ceramics
Global High Performance Ceramic Coatings Market
Ceramics
USA and Canada Alumina Market
Ceramics
Calcined Kaolin Market
Ceramics
Fly Ash and Ceramic Microsphere Market
Ceramics
Lithium Zirconate Market
Ceramics
2N High Purity Alumina Market
Ceramics
South Korea Ceramic Sanitaryware Market