
 Global DIY Home Improvement Market | 2026-2036
Global DIY Home Improvement Market Size, Share, and Industry Trends Forecast 2026-2036
Global DIY Home Improvement Market Analysis
The EU Green Deal is recalibrating insulation and window replacement standards across member states, raising compliance costs for imported building materials and favoring domestic suppliers with certified supply chains. The Home Depot leverages its captive distribution network to absorb these sourcing premiums, while Kingfisher plc anchors its competitive stance through specialized sustainable product lines in European banners. Lowe's Companies sustains North American market presence via contractor-grade inventory depth that meets evolving efficiency codes.
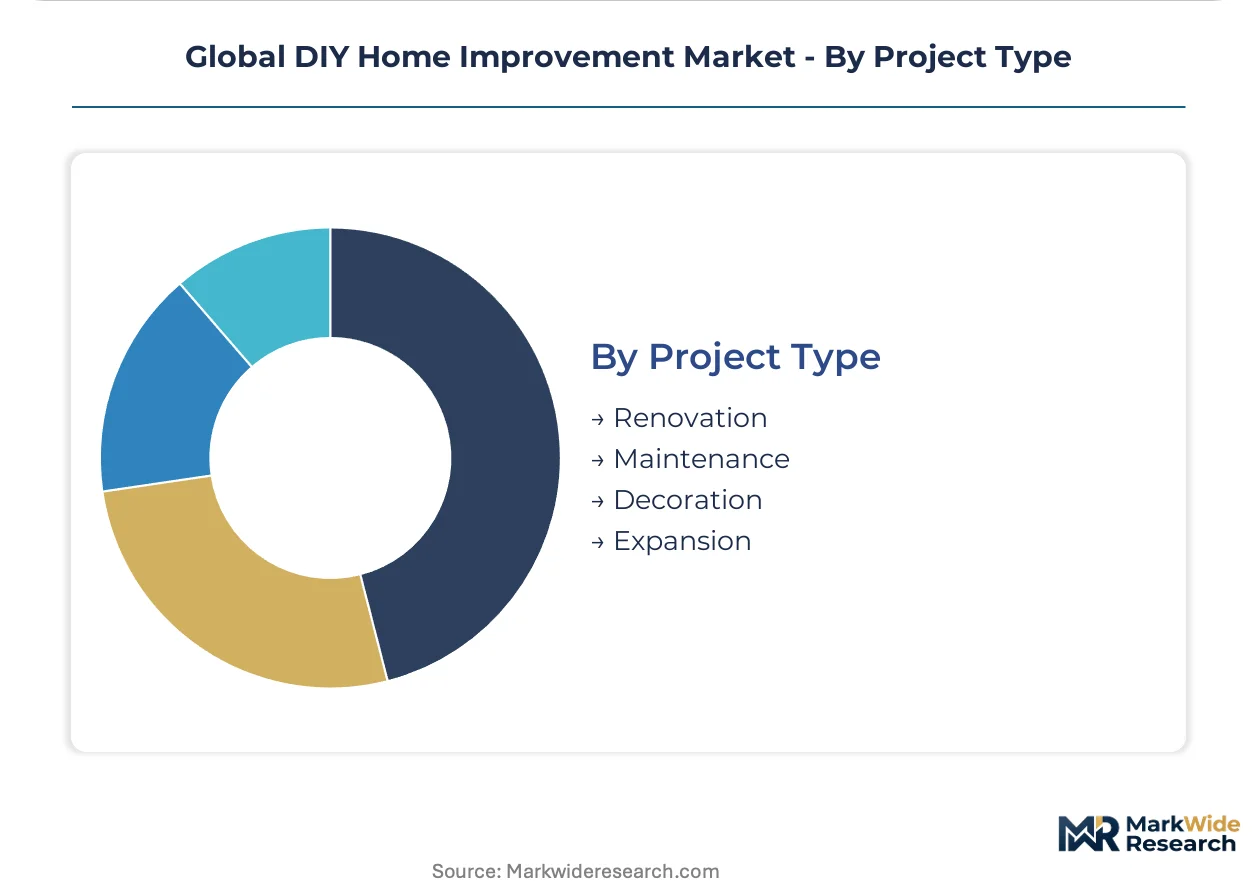
DIY home improvement encompasses self-directed residential modification, repair, and enhancement activities utilizing hand tools, power equipment, paints, flooring systems, and lighting fixtures with specifications typically rated for consumer rather than commercial-grade duty cycles; the category serves the fundamental purpose of enabling non-professionals to maintain property value, personalize living spaces, and reduce reliance on contracted labor. Flooring and tools occupy the most mature margin pools where brand loyalty and replacement cycles stabilize revenue, while online retail channels represent the fastest-growing distribution vector as digital fulfillment infrastructure narrows the convenience gap against physical home improvement chains. Project type segmentation reveals renovation and maintenance as the volume backbone, with decoration projects exhibiting higher frequency among the renter customer segment.
The US EPA governs volatile organic compound limits in architectural coatings, directly constraining paint formulation options available to DIY consumers, while REACH compliance in Europe mandates chemical substance registration that filters out smaller import competitors. China's GB standards and SAMR oversight on power tool safety certifications create parallel technical barriers for cross-border equipment manufacturers. Stakeholders must monitor divergence between regional efficiency mandates and harmonized international standards to determine whether localized production or modular product platforms offer superior cost control.
Market Dynamics
The EU Green Deal is compressing product lifecycles by mandating energy-efficient retrofits across residential building stock, forcing manufacturers to requalify materials faster than traditional replacement cycles allow. This regulatory pressure is redistributing margin toward certified domestic supply chains and away from import-dependent distributors.
Growth Catalysts
- First-time Millennial homebuyers:This demographic cohort is expanding project scope beyond basic repairs into full-room renovations and smart home integration, creating sustained pull for power tools and modular flooring systems.
- REACH compliance in Europe:Chemical substance registration mandates are filtering out smaller import competitors, consolidating shelf space for established suppliers with in-house toxicology testing capabilities.
- Germany's urban renovation corridors:Dense city-center building stock in Berlin, Hamburg, and Munich is generating concentrated demand for insulation and window replacement materials that meet tightened thermal performance standards.
Market Restraints
- Lumber and resin input volatility:Engineered wood and composite decking manufacturers face margin compression from construction-grade softwood price swings tied to North American mill capacity constraints.
- Power tool battery cell concentration:Cylindrical lithium-ion cell supply clusters in China's Jiangsu and Guangdong provinces create single-source vulnerability for cordless equipment OEMs.
- VOC formulation limits:US EPA architectural coating restrictions constrain paint chemistry options, blocking certain high-coverage formulations from consumer channels entirely.
Strategic Opportunities
- India's emerging homeowner class:Urban middle-income households in Mumbai and Bangalore are adopting Western-style DIY maintenance habits, opening whitespace for organized retail formats and branded hand tool sets.
- Digital fulfillment infrastructure:Same-day delivery networks and AR-enabled room visualization tools are narrowing the convenience gap against physical home improvement chains, enabling pure-play e-commerce entry.
- EU Green Deal retrofit mandates:Member state building renovation passports and subsidized efficiency loans are creating guaranteed demand pull for certified insulation, heat pumps, and high-performance glazing.
Industry Challenges
- Skilled installer scarcity:Plumbing and electrical rough-in competence gaps in aging trade workforces are pushing project complexity back onto manufacturers to design foolproof connector systems.
- Cross-border certification timelines:China's SAMR power tool safety approvals and GB standard testing queues add 8-14 months to product launch schedules for foreign entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global DIY Home Improvement Market |
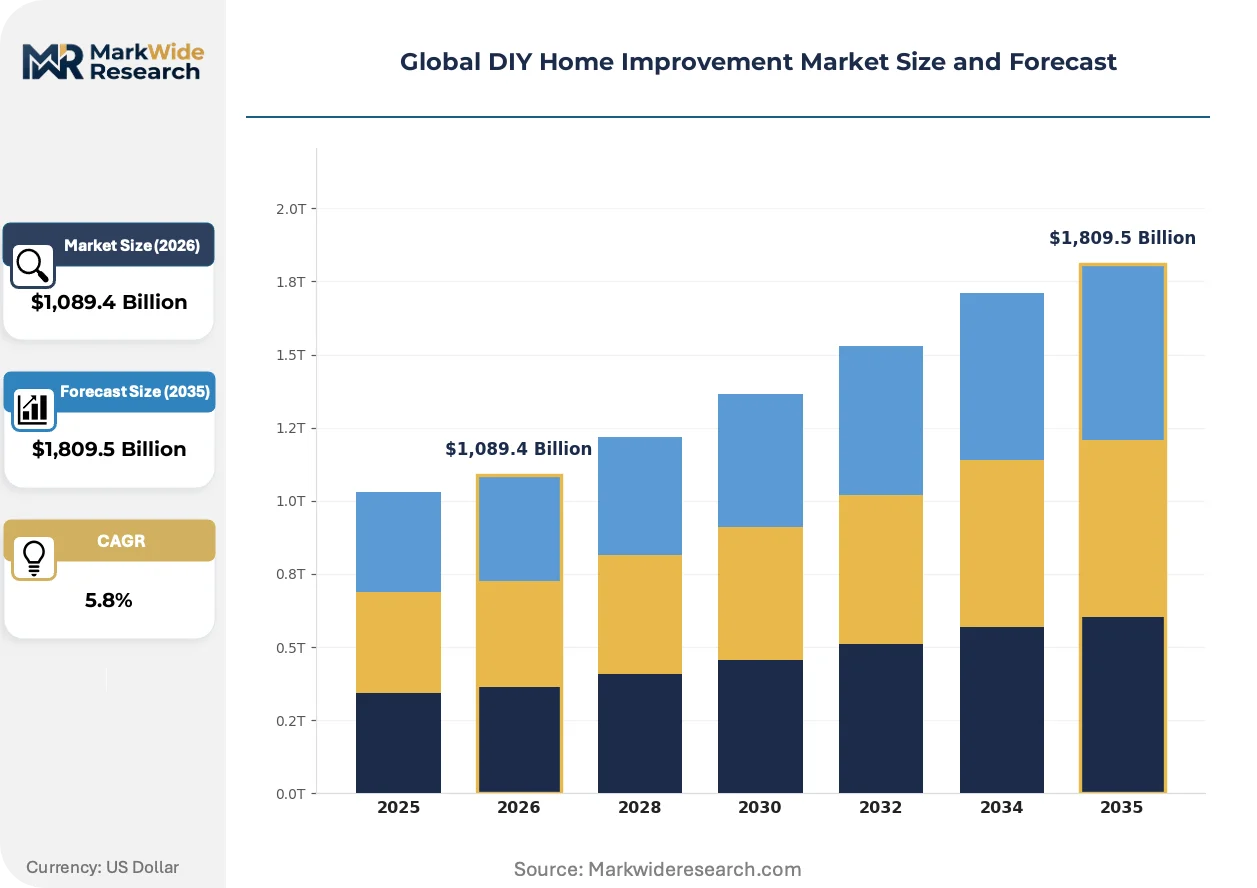
| Market Size in 2026 | $1,089.4 Billion |
| Market Size in 2035 | $1,809.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flooring, Paints, Tools, Lighting Customer Type: Homeowners, Renters, Contractors, Interior Designers Distribution Channel: Online Retail, Specialty Stores, Home Improvement Chains, Wholesale Project Type: Renovation, Maintenance, Decoration, Expansion |
| Companies Covered | The Home Depot, Lowe's Companies, Kingfisher plc, ADEO Group, Ace Hardware, Stanley Black & Decker, Bosch, Bunnings Warehouse, Hornbach Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global DIY Home Improvement Market Emerging Trajectories
Digital tools and connected equipment are restructuring how consumers plan, purchase, and execute home projects. Three converging developments are compressing the traditional research-to-purchase funnel while elevating performance expectations for entry-level products.
Brushless motor technology is absorbing the performance gap between consumer-grade and contractor-grade power tools. Weekend renovators in suburban US markets are adopting 20V cordless platforms for deck building and fence installation. This technology compression is forcing mid-tier manufacturers to abandon brushed motor architectures entirely or retreat to disposable price points.
REACH and RoHS directives in Europe are eliminating legacy solvents and heavy metal pigments from decorative coatings. Formulation houses are rebuilding product lines around bio-based binders and mineral-derived colorants. German and French paint producers are absorbing reformulation costs fastest, while Mediterranean import brands face shelf delisting.
Subscription-based tool access models are disrupting ownership patterns among urban renters. Milwaukee and DeWalt battery platforms anchor rental networks in London and New York, displacing single-purpose purchases. This behavioral shift is most visible in dense European capitals where storage constraints and project frequency favor pay-per-use economics over garage accumulation.
Global DIY Home Improvement Market Segmentation
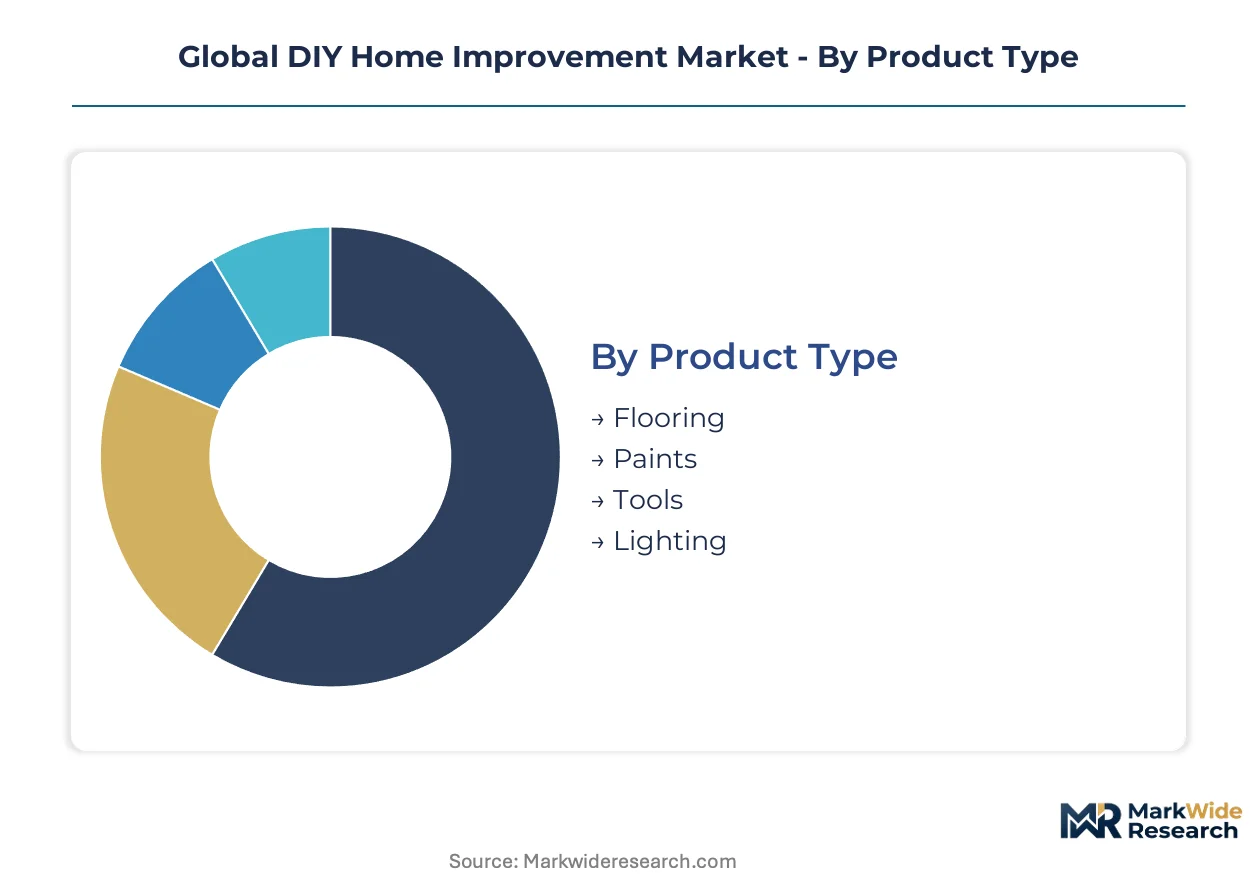
Segmentation in DIY home improvement reveals how product specifications, buyer economics, and channel infrastructure interact to determine margin capture. Understanding these divisions exposes where technology premiums concentrate and where commoditization pressures dominate.
Product Type:
Technical specifications separate consumer-grade from contractor-grade duty cycles, with motor architecture and coating chemistry driving replacement frequency and price positioning.
- Tools:Brushless motor platforms now dominate 20V cordless systems, compressing performance gaps between weekend renovators and professional installers. Demand clusters in suburban US markets for deck-building and fence-installation applications, with battery platform loyalty locking users into ecosystem purchases.
- Flooring:Engineered wood and luxury vinyl plank specifications emphasize click-lock installation systems that reduce skilled labor dependency. Germany's urban renovation corridors generate concentrated pull for moisture-resistant substrates that meet tightened thermal performance standards under EU Green Deal mandates.
- Paints:Low-VOC and zero-VOC formulations dominate architectural coating shelves as US EPA limits constrain legacy solvent chemistry. REACH compliance in Europe accelerates bio-based binder adoption.
- Lighting:LED retrofit kits and smart fixture platforms replace incandescent and halogen inventories, with integrated controls gaining share in whole-room renovation projects.
Mature deployment sits with Flooring. Newer deployment is concentrated in Lighting.
Customer Type:
Project scope and labor substitution economics determine which buyer segments absorb premium pricing versus seeking entry-level functionality.
- Homeowners:First-time Millennial buyers expand project scope beyond basic repairs into full-room renovations and smart home integration, creating sustained pull for power tool platforms and modular flooring systems with professional-grade specifications.
- Contractors:Small-scale remodelers purchasing through pro-desk channels prioritize inventory depth and same-day availability over price minimization, with loyalty programs capturing recurring material spend.
- Renters:Subscription-based tool access and temporary improvement solutions dominate, with pay-per-use economics favored in dense European capitals where storage constraints limit garage accumulation.
- Interior Designers:Curated specification sourcing for client projects drives demand for premium finishes and coordinated material palettes with certified sustainability credentials.
Volume concentration remains with Homeowners. Margin expansion is climbing the fastest among Interior Designers.
Distribution Channel:
Fulfillment speed and product touch requirements shape channel viability across bulky, fragile, and specification-intensive categories.
- Online Retail:Same-day delivery networks and AR-enabled room visualization tools narrow the convenience gap against physical chains, with digital pure-plays gaining share in lighting and decorative categories.
- Home Improvement Chains:Captive distribution networks absorb sourcing premiums from regulatory compliance, with pro-desk services and tool rental centers defending contractor relationships.
- Specialty Stores:Flooring and paint boutiques emphasize specification expertise and sample-based selling for complex material selection decisions.
- Wholesale:Volume aggregation for multi-unit property managers and commercial maintenance operations, with private-label programs capturing price-sensitive replacement demand.
Established infrastructure sits with Home Improvement Chains. Channel expansion is gaining share fastest through Online Retail.
Project Type:
Regulatory mandates and replacement cycles determine project frequency, with efficiency retrofits creating non-discretionary demand distinct from discretionary aesthetic upgrades.
- Renovation:Energy-efficient retrofits mandated under EU Green Deal building renovation passports generate guaranteed demand for certified insulation, heat pumps, and high-performance glazing in Germany, France, and Netherlands urban corridors.
- Maintenance:Seasonal replacement cycles for HVAC filters, caulking, and weatherstripping create predictable recurring revenue with limited brand switching.
- Decoration:Higher project frequency among renters and younger homeowners, with color trend cycles driving paint and lighting refresh purchases.
- Expansion:Structural additions and accessory dwelling units require permitting compliance and professional inspection, limiting pure DIY penetration.
Regulatory pull concentrates in Renovation. Discretionary refresh cycles dominate Decoration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in Germany's urban renovation corridors concentrate retrofit demand under EU Green Deal subsidies. Tax-advantaged development districts in Texas and Florida accelerate suburban housing turnover. India's special economic zones for manufacturing are seeding organized retail infrastructure in Mumbai and Bangalore.
United States
Millennial first-time homebuyers in suburban Texas and Florida markets are expanding project scope into full-room renovations. The EPA's VOC limits on architectural coatings constrain paint formulation options available through consumer channels. Atlanta's exurban corridors generate concentrated demand for power tool platforms and modular flooring systems.
Germany
Berlin, Hamburg, and Munich building stock generates dense demand for insulation and window replacement materials. EU Green Deal building renovation passports mandate thermal performance upgrades that favor certified domestic suppliers. The Rhine-Ruhr corridor anchors distribution networks absorbing compliance premiums for REACH-registered building materials.
China
GB standards and SAMR oversight on power tool safety certifications create technical barriers filtering smaller import competitors. The Yangtze River Delta clusters cylindrical lithium-ion cell production for cordless equipment OEMs. Shenzhen's electronics manufacturing base supplies smart fixture platforms for LED retrofit markets.
India
Urban middle-income households in Mumbai and Bangalore are adopting Western-style DIY maintenance habits. BIS certification requirements for electrical safety equipment filter unorganized sector imports. Maharashtra's organized retail expansion opens whitespace for branded hand tool sets and home improvement chains.
United Kingdom
London's rental-heavy housing stock drives subscription-based tool access and temporary improvement solutions. REACH compliance mandates accelerate bio-based binder adoption in decorative coatings. The Southeast's dense suburban corridors concentrate demand for click-lock flooring systems reducing skilled labor dependency.
Global DIY Home Improvement Market Vendor Landscape
US producers anchor one tier; European specialists hold certification-advantaged positions in retrofit materials. The vendor base stratifies across three layers: mass-market retailers with captive distribution networks, mid-tier manufacturers absorbing brushless motor transition costs, and premium-grade suppliers capturing specification-intensive renovation contracts. Two dominant competitive moves are reshaping positioning: backward integration into battery cell supply chains and portfolio diversification into subscription-based tool access models.
Within the mass-market retail tier, The Home Depot and Lowe's Companies exemplify North American scale-driven positioning, while Kingfisher plc occupies the European specialist archetype navigating EU regulatory complexity. These three anchors represent contrasting strategic responses to regional compliance pressures.
| Leading Market Players |
|---|
| The Home Depot |
| Lowe's Companies |
| Kingfisher plc |
| ADEO Group |
| Ace Hardware |
| Stanley Black & Decker |
| Bosch |
| Bunnings Warehouse |
| Hornbach Holding AG |
| Others |
Supply Flow & Price Mechanics
Brushless motor migration across cordless power tool platforms is compressing manufacturing cost curves while concentrating supplier leverage in China's Jiangsu and Guangdong provinces, where cylindrical lithium-ion cell production clusters anchor ecosystem economics for 20V battery platforms.
Pricing Analysis
Short lead-time premiums command pricing power in contractor-grade inventory channels, while spot inventory discounts clear seasonal overhang in decorative categories. Three-tier pricing structure across premium brushless, standard brushed motor, and economy disposable tiers separates professional duty-cycle specifications from weekend renovator segments. Price differentiation hinges on battery platform interoperability and REACH certification tier, with margins tightening in engineered wood substrates due to North American softwood volatility. Small-scale remodelers show lowest price sensitivity, prioritizing same-day availability, while urban renters exhibit highest elasticity favoring subscription access over ownership.
Supply Chain Analysis
Freight cost absorption in bulky flooring categories favors regional manufacturing footprints over Asian import dependence for EU market access. Supply concentrates in China for lithium-ion cells and power tool assembly, Germany for certified insulation and glazing systems, and Vietnam for engineered wood substrates facing US tariff exposure. Raw material dependencies span construction-grade softwood, bio-based coating binders, and rare-earth magnet powders for brushless motors. Single-source vulnerability in cylindrical cell supply creates chokepoint risk for cordless OEMs. Distribution runs through captive home improvement chain networks in North America and specialized sustainable product banners in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DIY home improvement sector sits in a technology-transition phase where brushless motor architectures displace brushed legacy platforms, compressing performance tiers and forcing mid-tier manufacturers toward ecosystem lock-in or commoditized retreat.
For Market Incumbents: Lock in battery platform loyalty through proprietary 20V ecosystem expansion and backward integration into cell supply partnerships, defending against pure-play e-commerce entrants narrowing the convenience gap with same-day delivery infrastructure. Prioritize REACH certification investment to filter import competition from European retrofit corridors. For New Entrants and Emerging Players: AR-enabled room visualization tools and digital pure-play channels offer the lowest barrier entry path into lighting and decorative categories where specification touch requirements are minimal. Target India's emerging homeowner class in Mumbai and Bangalore with organized retail formats and branded hand tool sets, exploiting whitespace left by unorganized sector fragmentation. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to mass-market retailers seeking captive distribution expansion, with long-term viability favoring suppliers with certified domestic supply chains under EU Green Deal mandates. Watch brushless motor patent expiration schedules as inflection indicators for commoditization timing in power tool tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Supply | Cylindrical lithium-ion concentration in Jiangsu creates single-source vulnerability for cordless OEMs requiring upstream control. |
| REACH Certification Investment | ECHA chemical registration mandates filter smaller import competitors, consolidating shelf space for compliant domestic suppliers. |
| Subscription-Based Tool Access Launch | Milwaukee and DeWalt battery platforms anchor rental networks displacing ownership in London and New York storage-constrained markets. |
| AR-Enabled Room Visualization Deployment | Digital fulfillment infrastructure narrows convenience gap against physical chains in lighting and decorative categories. |
| Certified Insulation Product Line Expansion | EU Green Deal building renovation passports generate guaranteed demand pull in Berlin, Hamburg, and Munich urban corridors. |
Methodological Framework
Document review covered regulatory filings from EPA and ECHA, trade databases tracking softwood and resin input flows, and SEC disclosures from listed home improvement retailers, complemented by interviews with power tool product managers, flooring procurement directors at multi-unit property managers, coating formulation chemists, and pro-desk operations heads at home improvement chains. Secondary validation drew from customs records, EU building renovation passport implementation timelines, and GB standard certification queues. Bottom-up segment sizing triangulated against top-down market consolidation estimates.
Cross-referencing historical replacement cycle patterns with panel input from distribution channel partners shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type duty-cycle tier, customer project scope, distribution channel fulfillment speed, and project type regulatory mandate intensity. CAGRs derived from trajectory alignment between input cost forecasting and demand elasticity assumptions in renovation versus decoration categories. Brushless motor adoption curves and EU subsidy program uptake rates served as industry-specific forecast inputs.
The model holds under stable regulatory implementation timelines for EU Green Deal mandates and continued lithium-ion cell supply concentration; deviation in tariff regimes or breakthrough solid-state battery commercialization would shift competitive positioning assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
Double-Hung Windows Market
Home Improvement and Renovation
China Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Italy Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Brazil Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
DIY Furnitures Market
Home Improvement and Renovation
Vietnam Home Improvement Market
Home Improvement and Renovation
DIY Home Decor Market
Home Improvement and Renovation
Home Improvement Services Market
Home Improvement and Renovation
Home Improvement Market
Home Improvement and Renovation
Vietnam DIY Home Improvement Market
Home Improvement and Renovation
US Home Remodeling Market
Home Improvement and Renovation
Melamine Door Market
Home Improvement and Renovation
United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Interior Doors Market
Home Improvement and Renovation
External Blinds Market
Home Improvement and Renovation
Automatic Curtain Market