
 Interior Doors Market | 2026-2036
Interior Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Interior Doors Market Intelligence
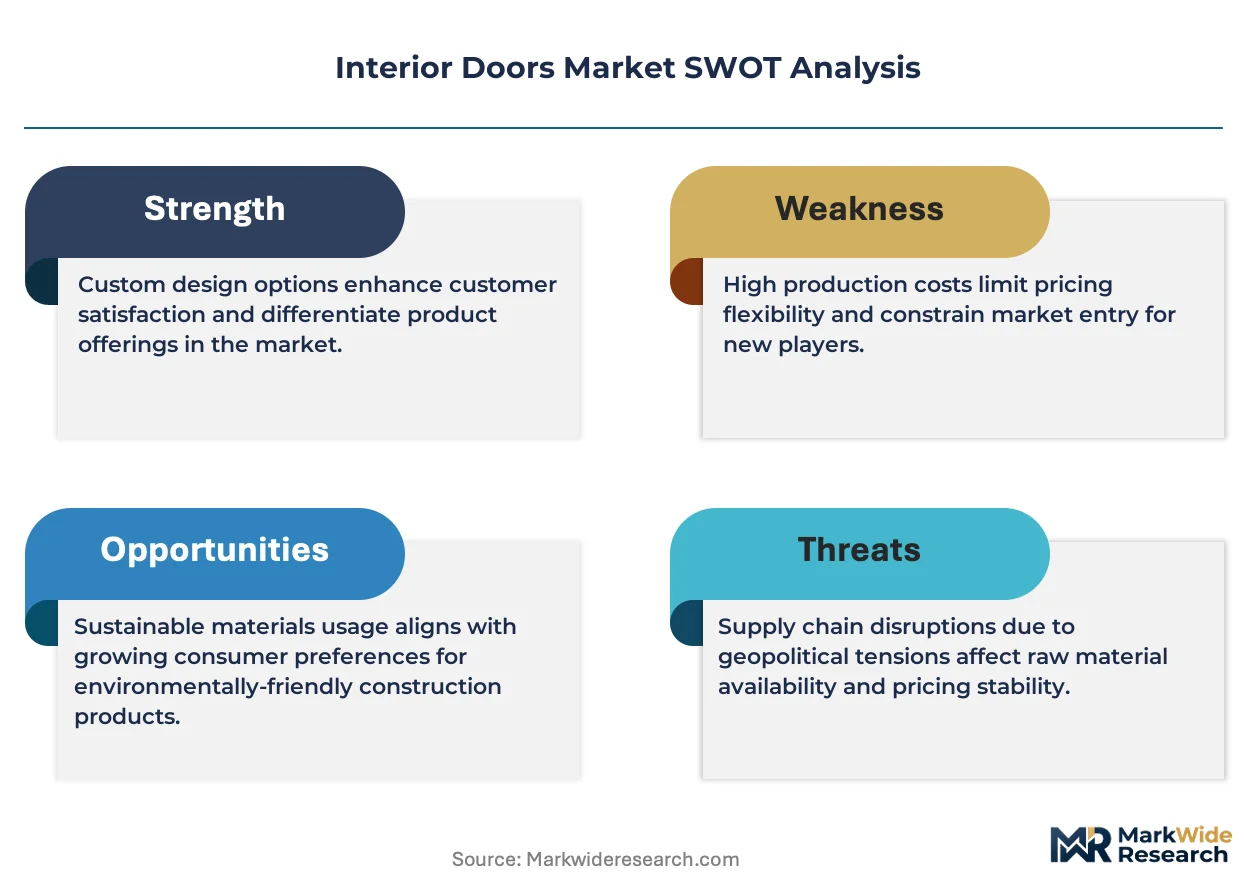
Aftermarket service revenue from refinishing and hardware retrofit kits is narrowing as manufacturers bundle lifecycle contracts into original sales. Masonite International Corporation leverages its composite manufacturing scale to control material costs across North American distribution. Jeld-Wen Holdings Inc. anchors its position through vertical millwork integration that spans door slabs to pre-hung frames. Simpson Door Company differentiates via species-specific wood sourcing programs that appeal to architect-led specification channels.
Interior doors are non-load-bearing movable barriers, typically 1-3/8 to 1-3/4 inches thick, engineered for privacy, acoustic separation, and thermal zoning within built environments. Flush doors dominate volume production due to standardized hollow-core construction and economical MDF skin lamination, while panel doors command specification premiums in heritage and executive residential applications. French doors represent the fastest-growing product type as open-plan commercial and hospitality layouts demand transparent visual connectivity without sacrificing HVAC zone control.
EPA formaldehyde emission standards under TSCA Title VI govern composite wood substrates used in domestic production, while CE marking and the EU Green Deal's embodied-carbon thresholds shape import eligibility and material substitution patterns across European specification channels. Builders, developers, and facility managers must monitor evolving lifecycle assessment requirements that increasingly privilege cradle-to-gate verified products over first-cost procurement metrics.
Market Dynamics
EU Green Deal embodied-carbon thresholds are redirecting specification decisions across residential and commercial construction, forcing material substitution toward certified low-emission substrates and compressing procurement cycles for uncertified suppliers.
Growth Catalysts
- Suburban residential construction:Engineered composite door systems are absorbing elevated housing completions in United States and Chinese suburban corridors as single-family and mid-density multifamily units accelerate.
- EPA TSCA Title VI:Formaldehyde emission standards for composite wood substrates are standardizing domestic production quality and unlocking specification access for compliant manufacturers in institutional and healthcare verticals.
- French door product type:Transparent visual connectivity without HVAC zone sacrifice is displacing solid-panel alternatives in open-plan commercial and hospitality layouts across Germany and United States.
Market Restraints
- Engineered wood substrate cost volatility:MDF and particleboard input prices fluctuate with resin and timber feedstock markets, compressing margin buffers for hollow-core flush door producers.
- CE marking friction:EU import eligibility rules create compliance timeline barriers for non-European manufacturers seeking specification access in German and French renovation channels.
- Steel and aluminum substitution:Fire-rated metal door systems capture share in high-rise residential and commercial egress applications where composite wood faces thermal performance limitations.
Strategic Opportunities
- Lifecycle contract bundling:Aftermarket refinishing and hardware retrofit services are being packaged into original sales, creating recurring revenue streams that pure product vendors cannot match.
- CE marking plus EU Green Deal dual certification:Cradle-to-gate verified products command specification premiums over first-cost procurement metrics in European architect-led channels.
- Acoustic separation technology:Sound-rated door assemblies are penetrating multi-family residential and co-working verticals where privacy zoning drives unit-level premiums in United States urban markets.
Industry Challenges
- Skilled millwork labor scarcity:Pre-hung frame assembly and job-site finishing trades face workforce gaps that extend lead times and elevate installation error rates in custom specification channels.
- Multi-jurisdiction certification complexity:Manufacturers must maintain parallel EPA, CE marking, and state-level fire-rating test data sets, fragmenting R&D budgets across compliance documentation rather than product innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interior Doors Market |
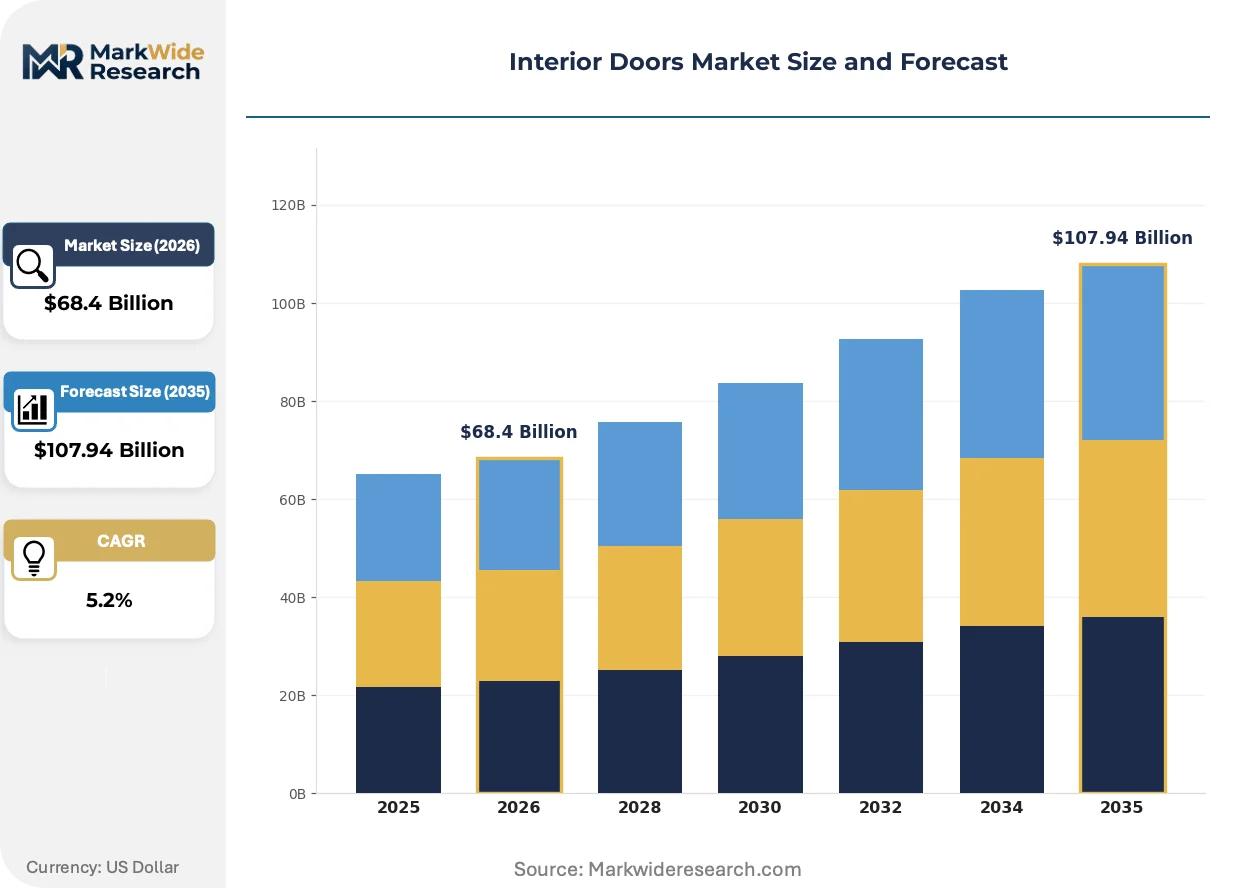
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $107.94 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flush Doors, Panel Doors, French Doors, Barn Doors, Louvered Doors, Folding Doors Material: Wood, Glass, PVC, Metal, Composite, MDF Application: Residential Buildings, Commercial Spaces, Hospitality Venues, Educational Institutions, Government Facilities, Recreational Centers End User: Homeowners, Property Developers, Facility Managers, Interior Designers, Contractors, Architects |
| Companies Covered | Steves & Sons, Simpson Door Company, Masonite International Corporation, Woodgrain, Lynden Door, Inc., Jeld-Wen Holdings Inc., Pella Corp., TruStile Doors, Marvin Windows and Doors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interior Doors Market Strategic Shifts & Innovations
Digital specification tools and material science advances are compressing traditional design-to-installation timelines while regulatory carbon accounting forces transparency into supply chain provenance.
Building information modeling (BIM) libraries for door assemblies are virtualizing the specification process, enabling architects to embed acoustic ratings, fire resistance, and hardware schedules directly into digital twins. Large commercial and hospitality developers in Germany and United States are mandating BIM-ready product data as a prequalification condition. This virtualization is compressing the traditional samples-to-specification cycle from weeks to days and marginalizing manufacturers without digital asset capabilities.
REACH and EU Green Deal embodied-carbon rules are tightening disclosure requirements for imported building products, forcing non-European suppliers to submit lifecycle assessment documentation or face specification exclusion. The industrial consequence is a bifurcation between certified low-emission material streams and conventional supply chains. German and French renovation markets are responding fastest, with facility managers embedding carbon thresholds into procurement scoring rubrics that overweight cradle-to-gate verified products.
Builder and developer procurement is consolidating around prefinished, pre-hung door systems that compress site labor and reduce finishing trade dependencies. Distributors are displacing traditional millwork houses in United States suburban residential channels by offering direct-to-site logistics and installation coordination. This concentration is most visible in Texas, Florida, and Arizona metro corridors where production homebuilders specify complete opening systems rather than component sourcing.
Interior Doors Market Segmentation
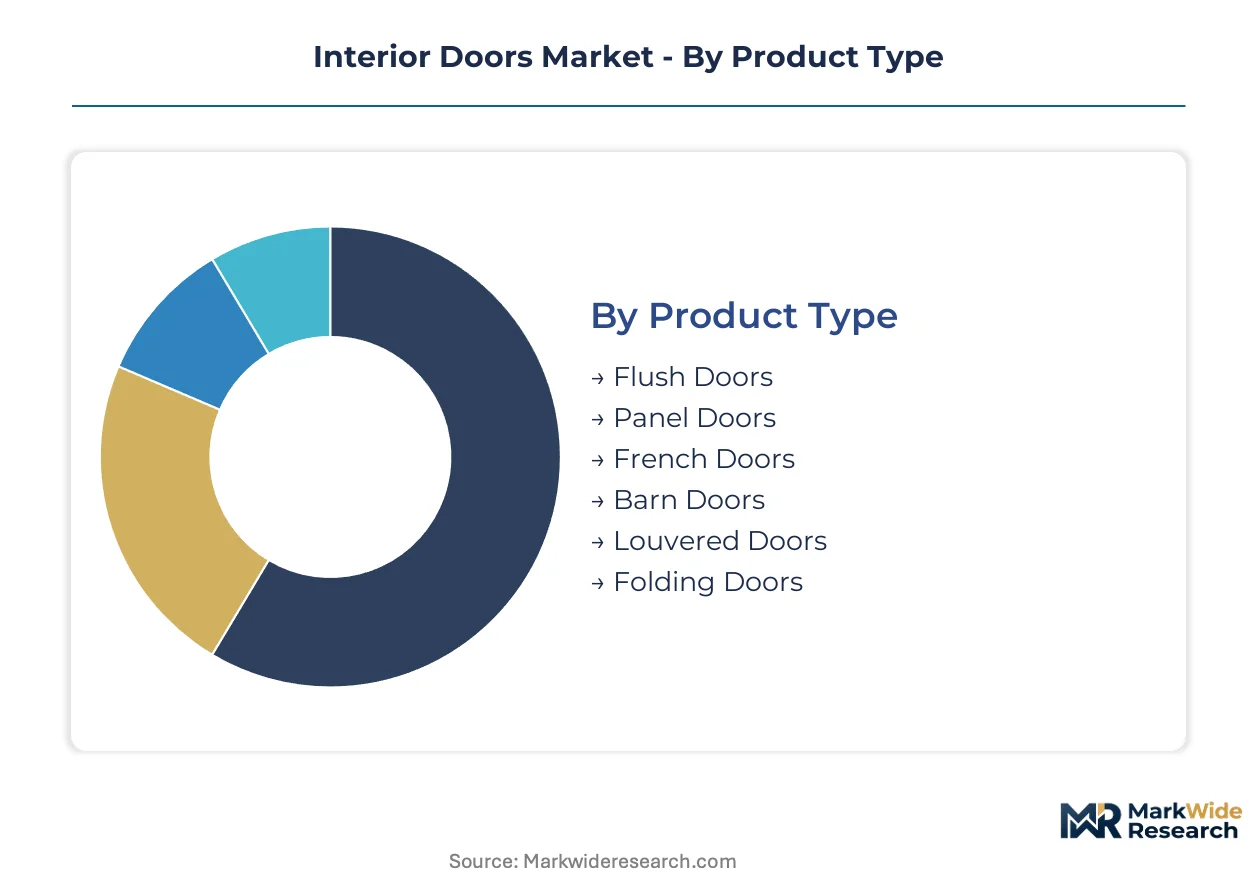
Interior door specification varies sharply across building types, with acoustic ratings, fire resistance, and aesthetic requirements driving distinct procurement patterns. Material substitution and pre-hung system preferences are fragmenting traditional supply channels as builders optimize for labor efficiency and code compliance.
Product Type:
Architects and developers select door configurations based on spatial flow requirements, privacy needs, and HVAC zone control priorities across residential and commercial environments.
- Flush Doors:Hollow-core construction with MDF skin lamination dominates volume production through standardized dimensions and economical manufacturing. United States production homebuilders in Texas and Florida corridors specify these for bedroom and closet applications where acoustic separation requirements remain minimal.
- Panel Doors:Stile-and-rail construction with raised or recessed panels commands specification premiums in heritage restoration and executive residential projects. German architect-led channels favor these for renovation cycles targeting embodied-carbon thresholds under EU Green Deal compliance frameworks.
- French Doors:Transparent visual connectivity without zone sacrifice is expanding most quickly in open-plan commercial and hospitality layouts.
- Barn Doors:Surface-mounted sliding hardware suits space-constrained urban residential retrofits where swing clearance is unavailable.
- Louvered Doors:Ventilated slat construction serves utility and laundry spaces requiring air circulation.
- Folding Doors:Multi-panel accordion systems enable wide opening conversions in recreational and hospitality applications.
Established volume favors flush door systems; emerging adoption favors French door configurations.
Material:
Substrate selection reflects cost tier positioning, regulatory emission standards, and performance specifications across climate zones.
- Wood:Solid and engineered lumber species deliver premium aesthetics and acoustic mass for architect-specified residential applications. Simpson Door Company's species-specific sourcing programs penetrate specification channels in United States coastal markets where moisture-resistant species command premiums.
- Composite:Engineered resin-bonded substrates balance dimensional stability against formaldehyde emission compliance under EPA TSCA Title VI. Masonite International Corporation leverages manufacturing scale across North American distribution to control material costs in suburban residential construction.
- MDF:Medium-density fiberboard skins provide uniform surface quality for painted finish applications.
- Glass:Tempered and laminated glazing enables visual transparency in commercial and hospitality partitions.
- PVC:Polyvinyl chloride extrusions resist moisture in coastal and institutional wet environments.
- Metal:Steel and aluminum cores satisfy fire-rated egress requirements in high-rise residential and commercial towers.
Composite materials capture mid-market volume expansion; wood species retain specification premium positioning.
Application:
Building type determines fire rating, acoustic performance, and hardware specification requirements with distinct procurement channels.
- Residential Buildings:Single-family and multifamily units drive hollow-core flush door volume through production builder procurement. United States suburban corridors in Arizona and Florida absorb prefinished, pre-hung systems that compress site labor dependencies.
- Commercial Spaces:Open-plan offices and co-working facilities demand sound-rated assemblies and French door transparency for HVAC zone flexibility. German facility managers embed carbon thresholds into procurement scoring that privileges cradle-to-gate verified products.
- Hospitality Venues:Guest room and public area specifications balance acoustic privacy with design statement requirements.
- Educational Institutions:Wear-resistant surfaces and lockset durability govern K-12 and university specifications.
- Government Facilities:Security hardware integration and blast resistance drive federal and municipal procurement.
- Recreational Centers:High-traffic durability and moisture resistance serve gymnasium and aquatic facility applications.
Residential construction absorbs material volume; commercial renovation drives specification complexity.
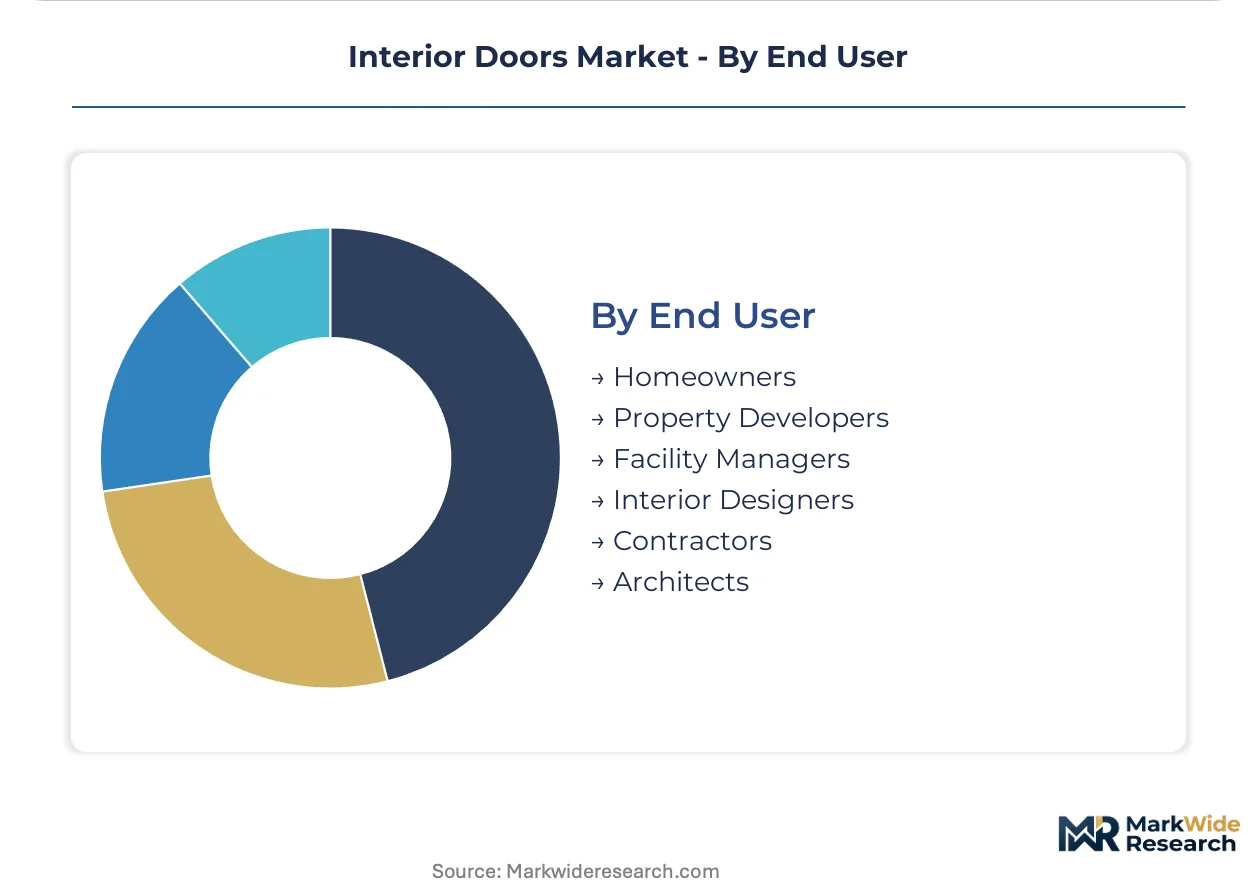
End User:
Procurement authority varies across project phases with distinct information requirements and decision criteria.
- Property Developers:Production homebuilders and multifamily developers consolidate purchasing around pre-hung opening systems with direct-to-site logistics. Jeld-Wen Holdings Inc. anchors position through millwork integration spanning slabs to frames.
- Architects:Design-led specification channels prioritize BIM-ready product data, acoustic ratings, and embodied-carbon documentation. German and United States commercial developers mandate digital asset prequalification.
- Homeowners:Retail and renovation procurement favors quick-ship prefinished options with installation support.
- Facility Managers:Lifecycle cost analysis governs replacement and retrofit decisions in institutional portfolios.
- Interior Designers:Aesthetic coordination with hardware and finish schedules drives custom specification.
- Contractors:Lead time reliability and installation error rates influence subcontractor preferences.
Developer consolidation favors integrated system suppliers; architect channels favor certified material transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Composite door manufacturing clusters in the United States, China, and Germany absorb the majority of specification volume as suburban housing completions and commercial renovation cycles accelerate. These three markets drive material substitution patterns and regulatory compliance investments across the industry.
United States
Production homebuilders in Texas, Florida, and Arizona metro corridors specify prefinished, pre-hung door systems that compress site labor dependencies. EPA TSCA Title VI formaldehyde emission standards govern composite wood substrates used in domestic manufacturing. Dallas-Fort Worth and Houston suburban construction absorbs engineered composite door volume as single-family housing completions accelerate.
China
Mid-density multifamily development in suburban corridors drives hollow-core flush door demand for bedroom and closet applications. The country's national building materials regulator enforces emission standards for engineered wood products that shape import eligibility. Yangtze River Delta manufacturing clusters produce standardized MDF-skin door systems for domestic distribution and export markets.
Germany
Architect-led specification channels favor panel door configurations in heritage restoration and executive residential projects targeting EU Green Deal embodied-carbon compliance. CE marking requirements create compliance timeline barriers for non-European manufacturers seeking renovation channel access. Bavaria and North Rhine-Westphalia facility managers embed carbon thresholds into procurement scoring rubrics.
Canada
Cross-border supply chain integration with United States manufacturers shapes specification patterns in Ontario and Quebec residential construction. Health Canada building product regulations align with EPA emission standards for composite wood substrates. Greater Toronto Area production builders specify pre-hung systems through integrated North American distribution networks.
France
Commercial renovation markets in Paris and Lyon respond fastest to EU Green Deal disclosure requirements for imported building products. ECHA REACH regulations tighten lifecycle assessment documentation requirements for specification eligibility. Île-de-France facility managers overweight cradle-to-gate verified products in procurement scoring against first-cost metrics.
Interior Doors Market Key Industry Players
Scale-driven manufacturers and millwork-integrated specialists split the market between volume production and specification premium positioning. The vendor base spans three strategic tiers: multinational composite material producers controlling North American distribution, vertically integrated millwork houses spanning slabs to pre-hung frames, and species-specific wood sourcing specialists penetrating architect channels. Dominant competitive moves include backward integration into substrate manufacturing and lifecycle contract bundling that captures aftermarket service revenue.
Within the scale-driven tier, Masonite International Corporation and Jeld-Wen Holdings Inc. occupy positions defined by manufacturing breadth and distribution control. Masonite exemplifies composite material production at continental scale, while Jeld-Wen anchors millwork integration across the value chain from door slabs to pre-hung frames. Simpson Door Company represents the species-specific sourcing archetype, penetrating specification channels where moisture-resistant wood programs command premiums.
| Leading Market Players |
|---|
| Steves & Sons |
| Simpson Door Company |
| Masonite International Corporation |
| Woodgrain |
| Lynden Door, Inc. |
| Jeld-Wen Holdings Inc. |
| Pella Corp. |
| TruStile Doors |
| Marvin Windows and Doors |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta manufacturing clusters anchor global hollow-core flush door capacity, translating resin and timber feedstock volatility into compressed margin buffers for producers serving United States and German specification channels. Their scale concentration creates asymmetric pricing power that downstream distributors and production homebuilders must navigate through long-term offtake arrangements or captive supply partnerships.
Pricing Analysis
EPA TSCA Title VI dictates the pricing tier structure across composite wood substrate categories, separating certified low-emission products from conventional alternatives in institutional and healthcare procurement. Three-tier pricing structure across premium architect-specified, standard production-builder, and economy retrofit tiers reflects certification grade and BIM-readiness differentiation. Cost compression in hollow-core flush segments is intensifying because MDF input prices fluctuate with resin markets. Production homebuilders in Texas and Florida corridors exhibit highest price sensitivity; architect-led specification channels in Germany demonstrate lowest sensitivity due to embodied-carbon compliance mandates.
Supply Chain Analysis
Contract manufacturing concentration rests with integrated millwork houses controlling pre-hung frame assembly and finishing operations rather than discrete component specialists. Geographic supply concentration centers on China, the United States, and Germany, with Yangtze River Delta, Dallas-Fort Worth, and Bavaria clusters feeding regional distribution networks. Raw material dependencies draw from timber feedstocks, resin binders, and steel hardware components. Single-source vulnerability in engineered wood substrate supply creates exposure to EUDR deforestation compliance timelines. Distribution runs through direct-to-site logistics providers displacing traditional millwork houses in suburban residential channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal embodied-carbon accounting is disrupting specification eligibility, creating technology-led inflection that privileges cradle-to-gate verified products over first-cost procurement across German and French renovation markets.
For Market Incumbents: Build certification moats around dual EPA TSCA Title VI and CE marking plus EU Green Deal compliance to defend against steel and aluminum substitution in fire-rated applications. Anchor backward integration into MDF substrate manufacturing to control resin cost volatility. Expand pre-hung system capacity in Dallas-Fort Worth and Houston corridors to capture production homebuilder consolidation. For New Entrants and Emerging Players: Pursue acoustic separation technology white space in United States multi-family residential and co-working verticals where sound-rated assemblies command unit-level premiums. Target French commercial renovation channels where ECHA REACH documentation gaps exclude non-European suppliers. Lead with BIM-ready digital asset capabilities as mandatory prequalification for German architect-led specification. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors lifecycle contract bundling specialists capturing recurring aftermarket revenue streams that pure product vendors cannot replicate. Five-to-ten year viability hinges on carbon accounting infrastructure maturity and regulatory enforcement consistency across EU member states. Monitor CE marking compliance timeline acceleration as inflection indicator for specification access barriers tightening against non-European supply.| Strategic Initiative | Industry Significance |
|---|---|
| Lifecycle Contract Bundling | Captures refinishing and hardware retrofit revenue streams from Masonite and Jeld-Wen service portfolios. |
| Dual Certification Investment | Unlocks German and French architect-led channels requiring CE marking plus EU Green Deal cradle-to-gate verification. |
| BIM-Ready Product Data Development | Meets Dallas-Fort Worth and Houston developer mandates for digital specification prequalification. |
| Acoustic Separation Technology R&D | Penetrates United States urban multi-family and co-working verticals where privacy zoning drives premiums. |
| Prefinished Pre-Hung System Expansion | Compresses site labor dependencies for Texas and Florida production homebuilders reducing finishing trade exposure. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with production homebuilder procurement directors, architect specification leads, facility managers in German commercial portfolios, millwork distributor operations heads, and composite substrate manufacturing plant managers. Secondary validation drew from EPA TSCA Title VI compliance databases, CE marking certification registries, EU Green Deal lifecycle assessment documentation, United States Census Bureau housing completion data, and ECHA REACH substance restriction filings. Bottom-up volume modeling triangulated against top-down construction spend allocation across the analysis window.
Calibration anchored on historical correlation between suburban housing completion velocity and flush door absorption rates, with segmentation across product type, material substrate, application building category, and end-user procurement authority. CAGRs derived from regression-weighted projection of renovation cycle timing, regulatory compliance phase-in schedules, and material substitution elasticity. Industry-specific inputs included MDF resin price indices, skilled millwork labor availability metrics, and BIM adoption rates in commercial specification channels.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories affecting housing starts or construction labor cost inflation would shift the trajectory. Forecasts embed assumptions regarding EU Green Deal enforcement consistency and EPA formaldehyde standard maintenance without expansion. Quarterly review of housing completion data, CE marking application volumes, and resin feedstock price movements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
North America Fiberglass Doors Market
Home Improvement and Renovation
Double-Hung Windows Market
Home Improvement and Renovation
Vietnam Home Improvement Market
Home Improvement and Renovation
DIY Home Decor Market
Home Improvement and Renovation
South Africa Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Global DIY Home Improvement Market
Home Improvement and Renovation
United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Melamine Door Market
Home Improvement and Renovation
Australia Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Bays and Bows Window Market
Home Improvement and Renovation
Brazil Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Automatic Curtain Market
Home Improvement and Renovation
Home Improvement Spending Market
Home Improvement and Renovation
Vietnam DIY Home Improvement Market
Home Improvement and Renovation
Home Improvement Market
Home Improvement and Renovation
Residential Interior Wood Doors Market