
 United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market | 2026-2036
United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market Insights
The UK Green Deal and ECO4 retrofit obligations is consolidating demand for insulation, draught-proofing, and low-carbon heating materials. Kingfisher plc leverages its B&Q and Screwfix banners to dominate big-box and trade-counter channels simultaneously. Wickes sustains strong kitchen and bathroom category leadership through installer-program loyalty. Travis Perkins plc anchors professional contractor supply with its extensive branch network and same-day delivery infrastructure.
United Kingdom Do-It-Yourself Home Improvement Retailing encompasses the sale of tools, building materials, decorative finishes, and garden products to consumers and tradespeople for self-executed residential projects. SKUs typically span power tools rated from 12V to 54V battery platforms, water-based acrylic paints meeting BS EN 13300 durability classifications, and pressure-treated timber graded to BS 4978 strength specifications. Paints & Coatings and Electrical Equipment represent the deepest margin pools, as colour-matching services and smart-home wiring accessories command price premiums over commodity hardware. E-commerce Platforms within the Sales Channel dimension are capturing disproportionate growth, driven by click-and-collect integration and augmented-reality colour visualisation tools that reduce return rates.
Building Regulations Part L conservation of fuel and power, PAS 2035 retrofit standards, and the Competition and Markets Authority green claims guidance collectively shape product certification requirements and marketing compliance for UK retailers. The Environment Agency's extended producer responsibility regulations for packaging and waste electrical equipment add operational cost layers that favour scaled distributors over independent merchants. Stakeholders must monitor how the Future Buildings Standard's fabric-efficiency thresholds will redefine the product mix between decorative and structural categories.
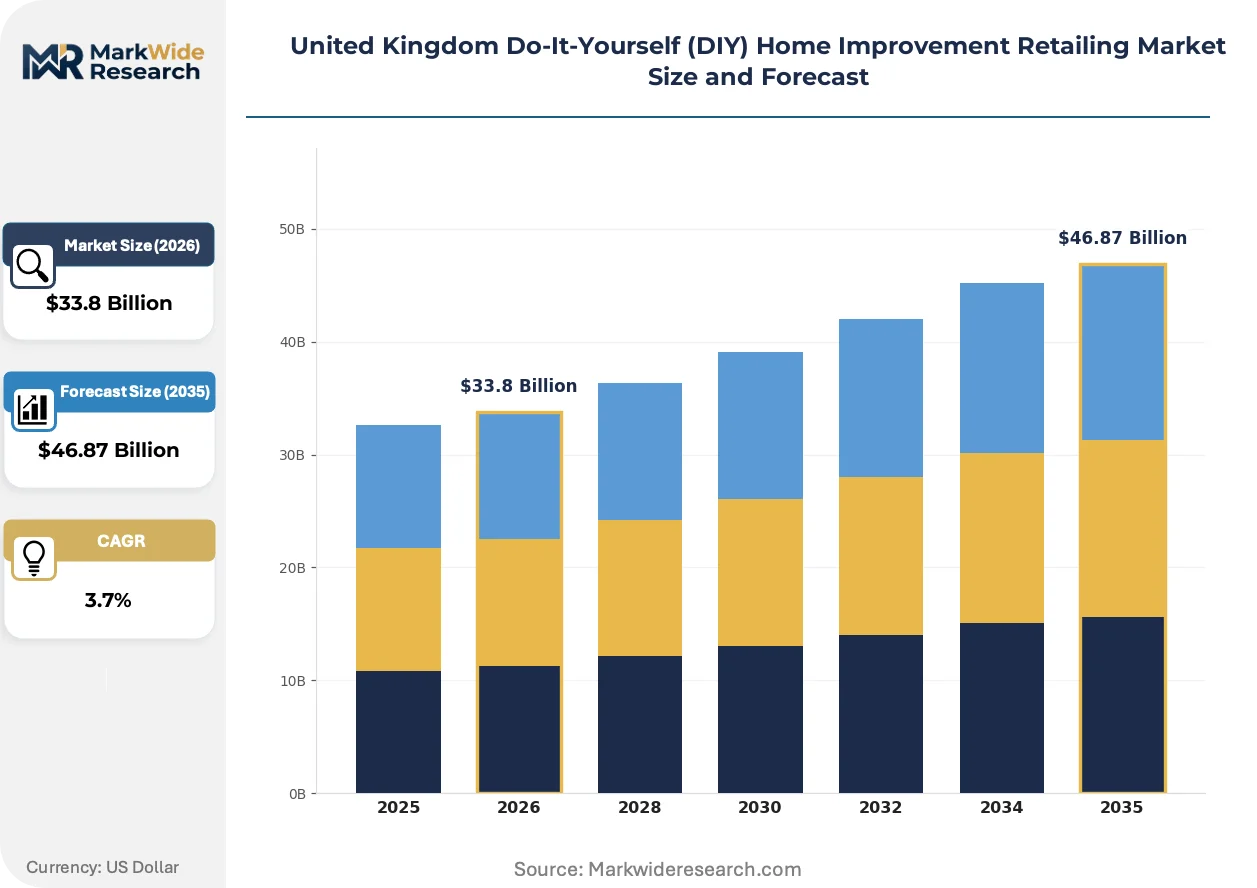
Market Dynamics
The UK DIY home improvement retailing market is undergoing structural recalibration as PAS 2035 retrofit standards and the Future Homes Standard reshape product certification requirements and inventory composition across the channel.
Growth Catalysts
- ECO4 retrofit obligations:Government-mandated energy-efficiency upgrades are consolidating demand for insulation, draught-proofing, and low-carbon heating materials across England and Wales.
- Aging housing stock:Pre-1919 dwellings comprise over one-fifth of English homes, driving replacement cycles for roofing, wiring, and plumbing systems.
- First-time buyer entry:New homeowners in Greater London and the South East are expanding tool and material purchases to customise recently acquired properties.
Market Restraints
- Timber supply volatility:Pressure-treated timber graded to BS 4978 specifications faces input cost fluctuations from Baltic and Scandinavian softwood markets.
- Extended producer responsibility:Environment Agency regulations for packaging and waste electrical equipment add operational cost layers that disadvantage smaller independent merchants.
- Trade skill shortages:Qualified installers for heat pumps and solar thermal systems remain scarce, limiting pull-through for associated materials.
Strategic Opportunities
- Click-and-collect integration:E-commerce platforms with augmented-reality colour visualisation tools are capturing disproportionate growth by reducing paint return rates.
- Smart-home wiring convergence:Battery platforms from 12V to 54V are creating cross-selling opportunities between power tools and domestic energy storage installations.
- Northern England penetration:Urban regeneration schemes in Manchester and Leeds present underexploited demand for renovation materials outside the South East concentration.
Industry Challenges
- PAS 2035 certification timelines:Retrofit coordinator accreditation delays are slowing project pipelines for whole-house energy improvements.
- Green claims compliance:Competition and Markets Authority guidance on environmental marketing requires retailers to substantiate sustainability assertions with verified data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market |
| Market Size in 2026 | $33.8 Billion |
| Market Size in 2035 | $46.87 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Tools, Hand Tools, Paints & Coatings, Plumbing Supplies, Electrical Equipment, Garden Supplies Customer Type: Individual Consumers, Hobbyists, Contractors, Small Business Owners, Property Managers Sales Channel: Physical Retail Stores, E-commerce Platforms, Direct Sales, Catalog Sales, Mobile Applications Application: Home Renovation, Garden Landscaping, Repairs & Maintenance, Decorating Projects, Installation Services |
| Companies Covered | Kingfisher plc, B&Q, Screwfix, Wickes, Homebase, Travis Perkins plc, Wolseley UK, Home Hardware (Scotland) Ltd, Toolstation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market Trends and Innovations
Digital tooling and regulatory stringency are compressing traditional retail margins while opening premium service layers around compliance and visualisation.
Water-based acrylic paints meeting BS EN 13300 durability classifications are absorbing market share from solvent-based alternatives as VOC restrictions tighten. Professional decorators and discerning retail buyers are specifying these formulations for interior and exterior applications. The shift is absorbing margin from commodity hardware while concentrating volume with distributors offering colour-matching services.
Building Regulations Part L conservation of fuel and power is mandating fabric-efficiency thresholds that elevate insulation and glazing categories above decorative finishes in project budgets. Retailers are reconfiguring floor space to accommodate thicker insulation batts and triple-glazing ancillaries. Kitchen and bathroom showrooms are responding by integrating heat-recovery ventilation into display suites.
Installer-program loyalty structures are consolidating professional demand around merchants offering same-day delivery and credit terms. Wickes and trade-counter competitors are capturing repeat contractor spend through project-account facilities and dedicated branch staff. The concentration is most visible in Greater London, where labour costs justify premium material sourcing over price-driven procurement.
United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market Segmentation
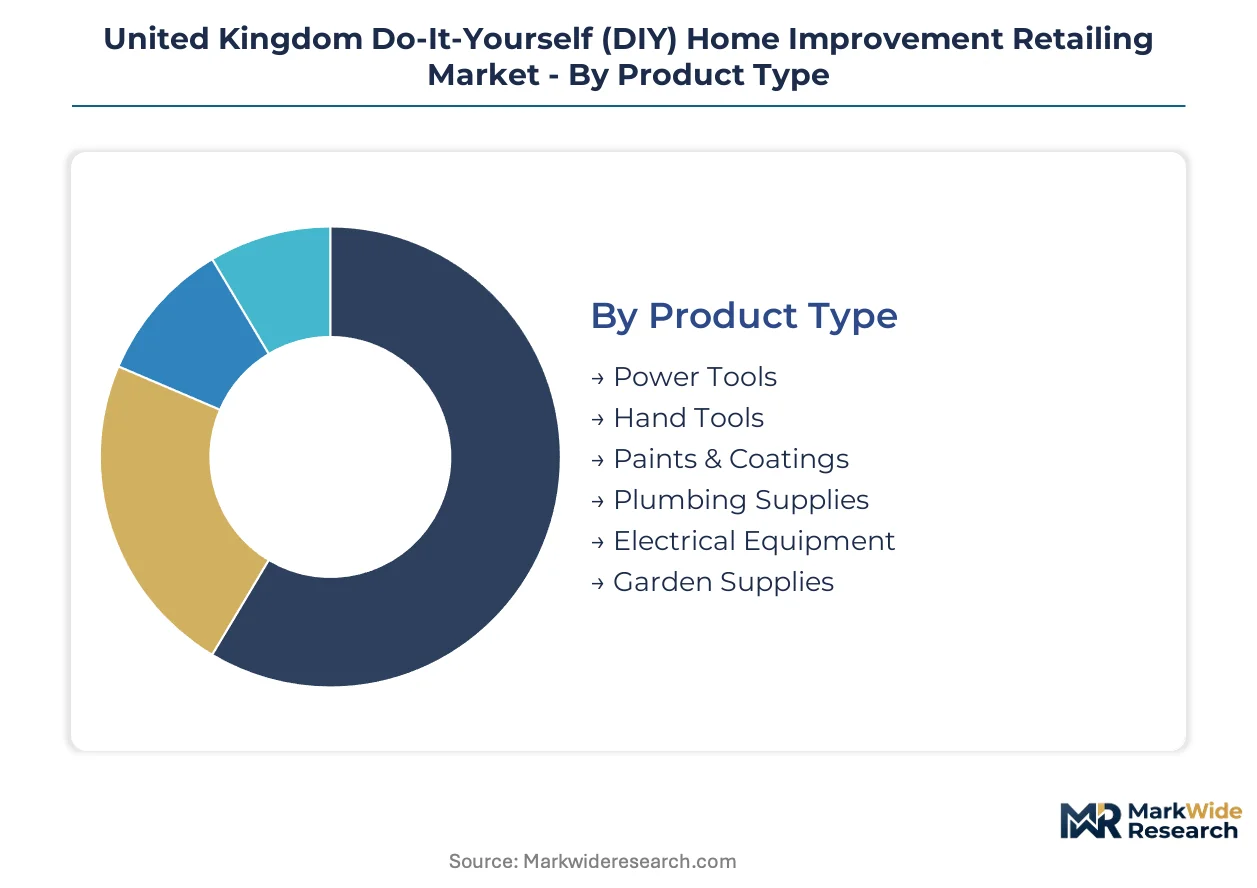
Buyer priorities diverge sharply between trade professionals seeking same-day availability and homeowners prioritising visualisation tools. Segmentation reveals how inventory depth, channel convenience, and project complexity reshape wallet allocation across the United Kingdom.
Product Type:
Purchase decisions track project complexity and margin potential rather than unit price alone.
- Paints & Coatings:Water-based acrylic formulations meeting BS EN 13300 durability classifications dominate specification sheets for interior and exterior work. Demand concentrates in Greater London and the South East where colour-matching services command price premiums over commodity hardware.
- Electrical Equipment:Smart-home wiring accessories and battery platforms from 12V to 54V create cross-selling opportunities with domestic energy storage installations. Retrofit coordinators under PAS 2035 are specifying these categories for whole-house efficiency upgrades across aging English housing stock.
- Power Tools:Cordless platforms rated from 12V to 54V battery systems serve both professional contractors and serious hobbyists.
- Hand Tools:Chrome-vanadium and carbon steel specifications persist for precision work where battery weight matters.
- Plumbing Supplies:Push-fit and press-fit systems reduce installation time for trade users on tight schedules.
- Garden Supplies:Pressure-treated timber graded to BS 4978 faces input cost volatility from Baltic softwood markets.
Volume sits with Paints & Coatings; growth tilts toward Electrical Equipment.
Customer Type:
Procurement authority separates recurring high-volume accounts from episodic discretionary spend.
- Contractors:Installer-program loyalty structures consolidate professional demand around merchants offering project-account facilities and dedicated branch staff. Same-day delivery infrastructure anchors repeat spend in Greater London where labour costs justify premium material sourcing.
- Individual Consumers:First-time homebuyers in the South East are expanding tool and material purchases to customise recently acquired properties. ECO4 retrofit obligations and Future Homes Standard awareness are pulling this segment toward insulation and draught-proofing categories.
- Hobbyists:Weekend project enthusiasts drive seasonal demand for garden and decorating categories.
- Small Business Owners:Landlords and tradespeople operating below VAT thresholds seek competitive pricing on repair cycles.
- Property Managers:Portfolio operators standardise specifications across multiple units to reduce maintenance variance.
Contractors capture the deepest volume; Individual Consumers are expanding most quickly.
Sales Channel:
Fulfilment speed and product touch requirements determine channel selection.
- E-commerce Platforms:Click-and-collect integration and augmented-reality colour visualisation tools reduce paint return rates while capturing disproportionate growth. Digital tooling compresses traditional retail margins while opening premium service layers around compliance documentation.
- Physical Retail Stores:Big-box and trade-counter formats dominate where immediate availability outweighs price comparison. Floor space reconfiguration toward thicker insulation batts and triple-glazing ancillaries responds to Building Regulations Part L fabric-efficiency thresholds.
- Direct Sales:Volume accounts for professional contractors bypass retail markup through negotiated supply agreements.
- Catalog Sales:Remains relevant for trade users in remote Scottish and Welsh postcodes with limited branch coverage.
- Mobile Applications:Order-and-collect functionality serves time-constrained professionals between job sites.
Physical Retail Stores retain volume leadership; E-commerce Platforms show the steepest expansion trajectory.
Application:
Budget allocation follows housing condition and regulatory compliance timelines.
- Home Renovation:Kitchen and bathroom showrooms are integrating heat-recovery ventilation into display suites as Building Regulations Part L tightens. Wickes sustains category leadership through installer-program loyalty structures in these high-ticket projects.
- Repairs & Maintenance:Pre-1919 dwellings comprising over one-fifth of English homes drive replacement cycles for roofing, wiring, and plumbing systems. ECO4 retrofit obligations are consolidating demand for insulation and low-carbon heating materials in this application.
- Garden Landscaping:Seasonal demand peaks align with planning permission timelines for permitted development rights.
- Decorating Projects:VOC restrictions are accelerating shift from solvent-based to water-based formulations.
- Installation Services:Trade skill shortages for heat pumps and solar thermal systems limit pull-through for associated materials.
Repairs & Maintenance holds the installed base; Home Renovation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater London and the South East concentrate the deepest renovation spending, with property values justifying premium material sourcing across kitchen, bathroom, and energy-efficiency upgrade projects.
London and the South East
First-time homebuyers and private renters drive tool and material purchases as housing stock ages across the capital and surrounding counties. Building Regulations Part L conservation of fuel and power mandates fabric-efficiency thresholds that elevate insulation and glazing categories. Kitchen and bathroom showrooms in the M25 corridor integrate heat-recovery ventilation into display suites.
Midlands
Urban regeneration schemes in Birmingham and Leicester present expanding demand for renovation materials outside the South East concentration. The UK government's Future Homes Standard tightens energy-efficiency requirements for residential properties across the region. Trade-counter formats in the West Midlands capture professional contractor spend through same-day delivery infrastructure.
North England
Manchester and Leeds regeneration projects generate underexploited demand for structural and decorative categories. ECO4 retrofit obligations consolidate demand for insulation, draught-proofing, and low-carbon heating materials across aging Victorian housing stock. Installer-program loyalty structures concentrate professional demand around merchants with project-account facilities in Greater Manchester.
Scotland
Pre-1919 dwellings comprise significant portions of Edinburgh and Glasgow housing stock, driving replacement cycles for roofing, wiring, and plumbing systems. The Scottish government's energy-efficiency targets align with PAS 2035 retrofit standards for whole-house improvements. Trade users in remote postcodes rely on catalog sales and mobile order-and-collect functionality where branch coverage remains limited.
Wales
Aging housing stock across Cardiff and Swansea generates steady repairs and maintenance demand. Environment Agency extended producer responsibility regulations for packaging and waste electrical equipment add operational cost layers that favour scaled distributors. E-commerce platforms with click-and-collect integration capture growth in Welsh valleys where physical retail density runs lower.
United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market Competitive Landscape
The competitive structure tilts toward dual-channel operators serving both big-box retail and trade-counter segments simultaneously. Kingfisher plc anchors volume leadership through its B&Q and Screwfix banners, while Wickes sustains kitchen and bathroom category leadership through installer-program loyalty. Travis Perkins plc commands professional contractor supply with extensive branch networks and same-day delivery infrastructure. Strategic moves concentrate on floor space reconfiguration toward insulation and energy-efficiency categories, plus digital tooling investments in augmented-reality visualisation.
Among UK-based retail operators, Kingfisher plc, Wickes, and Travis Perkins plc exemplify the three dominant archetypes: the dual-channel conglomerate, the category-specialist with trade loyalty programs, and the professional-grade distributor with logistics scale. Each occupies a distinct position in the value chain without direct overlap. Kingfisher plc represents the diversified portfolio approach spanning consumer and trade segments. Wickes anchors the mid-market renovation specialist tier. Travis Perkins plc sits within the professional supply tier where project scale and delivery speed determine procurement decisions. The remaining field fragments across regional independents and digital-native entrants without equivalent infrastructure depth.
| Leading Market Players |
|---|
| Kingfisher plc |
| B&Q |
| Screwfix |
| Wickes |
| Homebase |
| Travis Perkins plc |
| Wolseley UK |
| Home Hardware (Scotland) Ltd |
| Toolstation |
| Others |
Pricing and Supply Chain Analysis
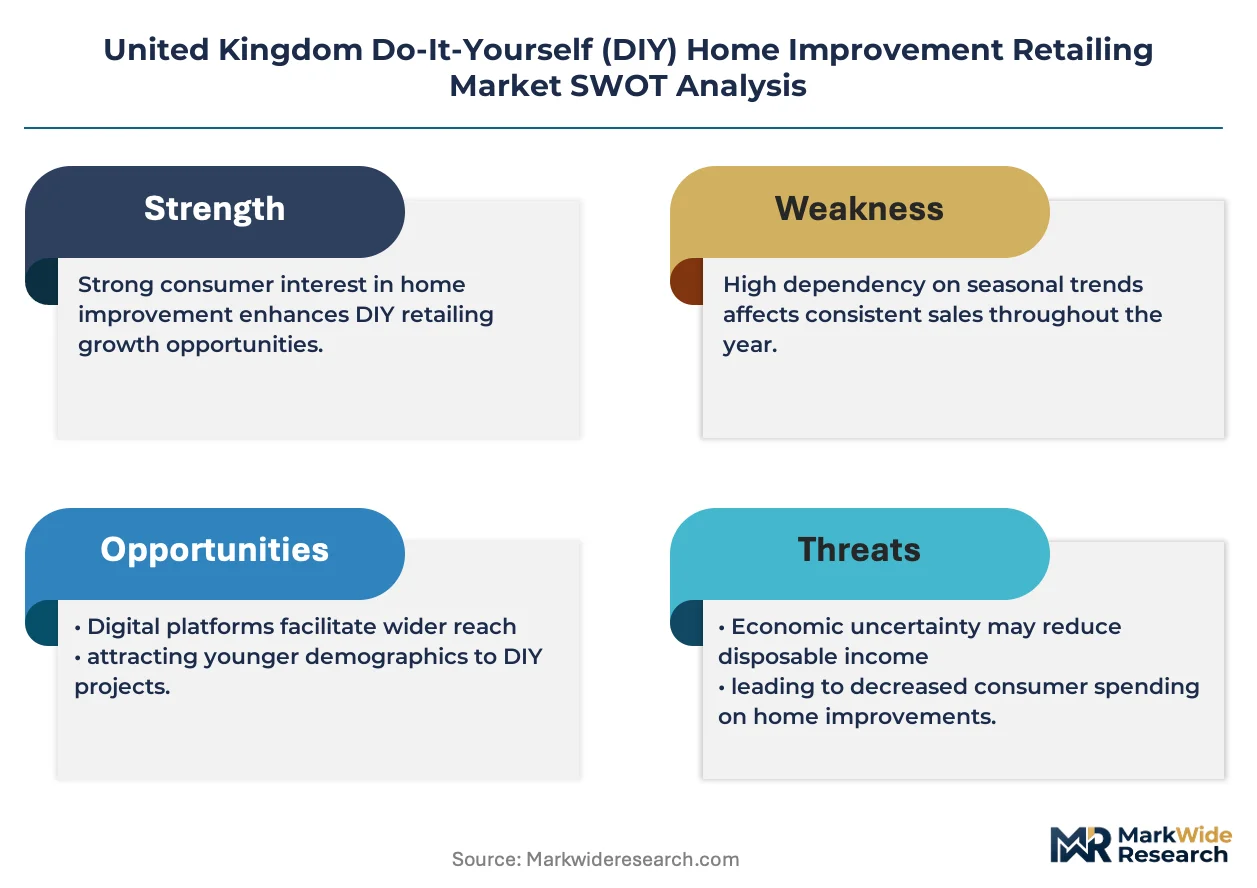
PAS 2035 retrofit coordinator demand is concentrating specification authority around certified insulation and low-carbon heating materials, forcing distributors to carry deeper inventory of premium-grade products and compressing margins on undifferentiated commodity hardware.
Pricing Analysis
Outcome-based pricing tied to energy-efficiency performance anchors premium tiers across insulation and smart-home electrical categories. Three-tier pricing structure across premium, standard, and economy levels separates PAS 2035-certified materials from trade-grade alternatives and entry-level DIY products. Cost compression in economy paint and hand tool segments is intensifying because Baltic softwood input volatility and extended producer responsibility fees disproportionately burden smaller merchants. Individual consumers in Greater London exhibit lowest price sensitivity where property values justify premium sourcing, while hobbyists and small landlords in Northern England drive hardest bargain comparisons.
Supply Chain Analysis
Regional distribution centers in the English Midlands and South East operate hub-and-spoke patterns feeding trade-counter networks and big-box retail floors. Baltic states, Sweden, and Finland supply pressure-treated timber graded to BS 4978 specifications, while China and Germany feed power tool battery platforms and smart-home wiring components. Single-source vulnerability concentrates in Scandinavian softwood markets where climate-related harvest disruptions ripple through treated timber pricing. Distribution runs through Travis Perkins plc's branch network and Kingfisher plc's dual-banner infrastructure, with same-day delivery capabilities anchoring contractor loyalty in Greater London and the M25 corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified installer scarcity for heat pumps and solar thermal systems is constraining pull-through capacity for associated materials, propping pricing power for merchants who bridge the skills gap through training-certified installer programs.
For Market Incumbents: Lock in PAS 2035 retrofit coordinator relationships through accredited training partnerships and dedicated project-account facilities. Deepen backward integration into insulation batts and triple-glazing ancillaries to capture margin from Building Regulations Part L compliance upgrades. Defend against digital-native entrants by embedding augmented-reality visualisation tools into mobile order-and-collect workflows. For New Entrants and Emerging Players: Begin with underexploited demand in Manchester and Leeds urban regeneration corridors where trade-counter density lags contractor population growth. Target ECO4 retrofit obligation workflows by offering bundled insulation-and-draught-proofing kits with embedded compliance documentation. Pursue installer-program loyalty structures through credit terms and same-day delivery commitments rather than price-led penetration. For Investors and Strategic Acquirers: The window for entry favors scaled distributors with last-mile logistics infrastructure and PAS 2035 certification capabilities. Long-term viability hinges on exposure to regulatory-driven renovation cycles rather than discretionary decorating demand. Monitor heat pump installation permit issuance rates across English local authorities as inflection indicator for low-carbon heating material pull-through.| Strategic Initiative | Industry Significance |
|---|---|
| PAS 2035 Certification Investment | Accreditation delays currently bottleneck project pipelines, creating first-mover advantage for certified coordinators. |
| Backward Integration into Insulation | In-house production of Part L-compliant batts captures margin from fabric-efficiency threshold upgrades. |
| Click-and-Collect Platform Expansion | Augmented-reality colour visualisation reduces paint return rates while compressing traditional retail margins. |
| Installer Training Partnership | Bridging heat pump and solar thermal skills scarcity locks in professional demand through loyalty structures. |
| Northern England Branch Network | Manchester and Leeds regeneration schemes present underexploited demand outside South East concentration. |
Research Methodology
Multi-period observation of ECO4 retrofit obligation uptake, PAS 2035 project pipeline velocity, and trade-counter same-day delivery penetration anchored the trend analysis, supplemented by interviews with merchant category managers, retrofit coordinators, professional contractor purchasing officers, and DIY retail operations directors. Secondary validation drew from Environment Agency extended producer responsibility filings, UK Building Regulations Part L consultation documents, Competition and Markets Authority green claims guidance, and customs data on Baltic softwood imports. Bottom-up SKU-level demand modeling and top-down housing stock age analysis were triangulated against channel shipment data.
Segment-weighting across product type, customer archetype, sales channel, and application dimensions informed volume allocation. Projected growth rates were derived from housing transaction velocity, regulatory compliance timeline modeling, and energy-efficiency upgrade adoption curves across the analysis window. Forecast inputs included Future Homes Standard implementation phasing, installer accreditation capacity constraints, and e-commerce platform adoption rates among first-time homebuyers.
Underlying measurement precision varies by segment; e-commerce platform growth and PAS 2035-certified material demand carry tighter precision than hobbyist discretionary spend projections. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and timber input cost stabilization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
Home Improvement Services Market
Home Improvement and Renovation
Home Improvement Spending Market
Home Improvement and Renovation
Residential Interior Wood Doors Market
Home Improvement and Renovation
South Africa Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Vietnam DIY Home Improvement Market
Home Improvement and Renovation
Global DIY Home Improvement Market
Home Improvement and Renovation
Home Improvement Market
Home Improvement and Renovation
Italy Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Vietnam Home Improvement Market
Home Improvement and Renovation
DIY Furnitures Market
Home Improvement and Renovation
Australia Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Home Remodeling Market
Home Improvement and Renovation
China Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
North America Fiberglass Doors Market
Home Improvement and Renovation
Double-Hung Windows Market
Home Improvement and Renovation
External Blinds Market