
 Tuberculosis Testing Market | 2026-2036
Tuberculosis Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Tuberculosis Testing Market Outlook
The divergence between premium molecular diagnostics and commodity tuberculin skin tests is hardening as procurement agencies split budgets between accuracy and coverage. QIAGEN leverages its QuantiFERON platform to anchor the latent TB detection segment in developed health systems. F. Hoffmann-La Roche competes through its cobas portfolio, sustaining integrated workflow automation for high-throughput laboratories. Cepheid (Danaher) dominates point-of-care molecular testing with cartridge-based systems designed for resource-limited settings.
Tuberculosis testing encompasses diagnostic methods that detect Mycobacterium tuberculosis infection or disease through immunological response measurement, bacterial genetic material identification, or radiological observation of pulmonary lesions. These methods serve public health programs, clinical practice, and research institutions by enabling treatment initiation, contact tracing, and drug resistance surveillance. The nucleic acid test segment leads value generation due to WHO policy recommendations for rapid molecular diagnosis, while blood test platforms capture expanding latent TB screening volumes in occupational health and immigration medical examinations. Imaging tests retain stable demand for monitoring treatment response and detecting extrapulmonary manifestations where bacteriological confirmation remains elusive.
The WHO prequalification program and FDA clearance pathways shape product commercialization timelines and eligibility for global procurement mechanisms such as the Global Drug Facility. EMA oversight of in vitro diagnostic medical devices under the EU MDR imposes clinical evidence requirements that filter market access for European manufacturers and importers alike. National regulators in India and South Africa enforce local quality standards that influence supplier selection for government tenders. Stakeholders must monitor evolving WHO policy guidance on novel diagnostic algorithms and track procurement consolidation among multilateral health financing institutions.
Market Dynamics
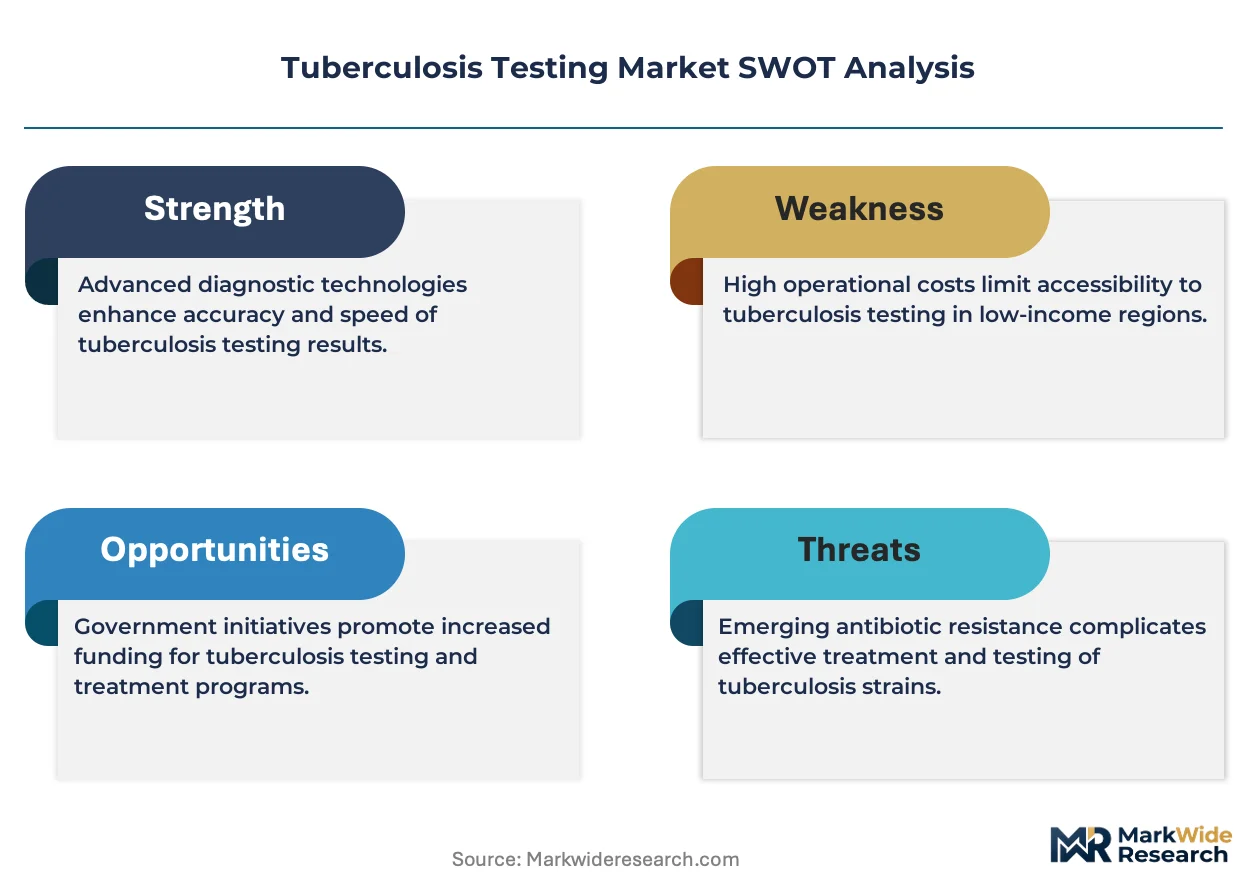
WHO policy guidance on rapid molecular diagnosis is redirecting procurement budgets from smear microscopy toward cartridge-based nucleic acid amplification platforms, compressing timelines for treatment initiation and contact tracing in high-burden settings.
Growth Catalysts
- End TB Strategy targets:WHO's 2035 mortality reduction goals mandate universal access to rapid diagnostics, compelling national TB programs in India, South Africa, and Indonesia to scale automated testing infrastructure.
- Cartridge-based NAAT platforms:Point-of-care molecular systems eliminate cold-chain dependencies and specialized laboratory requirements, expanding diagnostic reach to peripheral health facilities.
- Occupational health screening:Immigration medical examinations and healthcare worker surveillance programs in developed health systems drive recurring latent TB detection volumes through interferon-gamma release assays.
Market Restraints
- Reagent supply concentration:Proprietary cartridge ecosystems lock purchasers into single-source consumables, limiting price negotiation leverage for ministries of health.
- Technical limitation in paucibacillary disease:Sputum-scarce and extrapulmonary TB presentations evade molecular detection, forcing reliance on culture-based confirmation with extended turnaround times.
- EU MDR clinical evidence requirements:EMA oversight of in vitro diagnostic medical devices imposes documentation burdens that delay market access for European manufacturers and importers.
Strategic Opportunities
- Underpenetrated Indonesian archipelago:Dispersed island geography and limited laboratory infrastructure create demand for decentralized testing networks beyond Java and Sumatra.
- AI-assisted radiological screening:Computer-aided detection of pulmonary lesions on chest X-rays converges with smartphone-based image transmission to triage patients in settings lacking molecular capacity.
- Drug resistance surveillance:Second-line molecular tests for rifampicin and isoniazid resistance enable targeted therapy selection, opening procurement channels for resistance panels in reference laboratories.
Industry Challenges
- Biosafety containment capex:Culture-based confirmation and drug susceptibility testing require Biosafety Level 3 laboratory infrastructure, straining capital budgets in resource-constrained settings.
- Multidisease platform integration:Manufacturers face technical complexity in reconfiguring cartridge-based systems to simultaneously detect TB, COVID-19, and respiratory pathogens without compromising analytical sensitivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tuberculosis Testing Market |
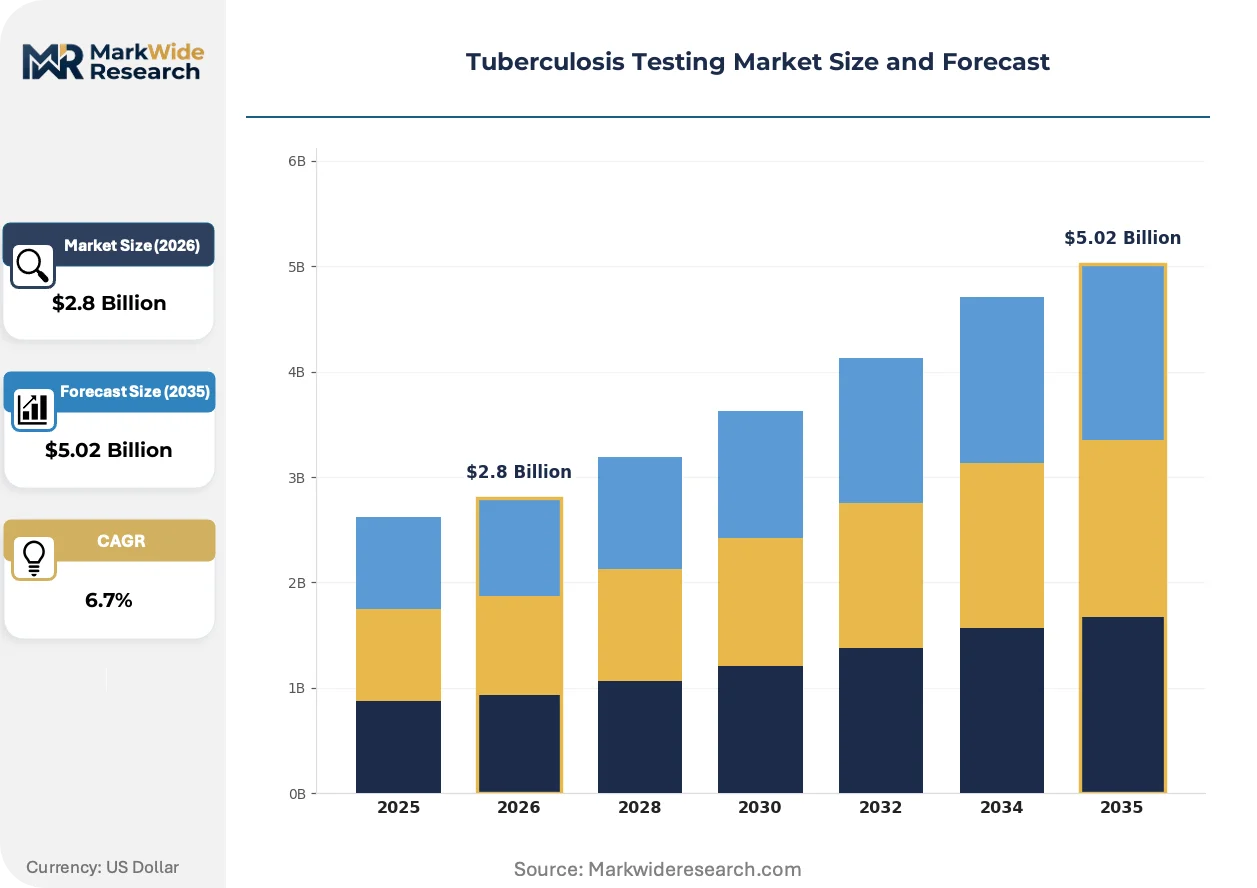
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Test, Blood Test, Nucleic Acid Test, Imaging Test Technology: Biochemical, Molecular, Radiological, Optical End User: Hospitals, Diagnostic Centers, Laboratories, Clinics Application: Screening, Diagnosis, Monitoring, Research |
| Companies Covered | QIAGEN, F. Hoffmann-La Roche, Abbott Laboratories, Thermo Fisher Scientific, Becton Dickinson, Cepheid (Danaher), bioMérieux, Hologic, Oxford Immunotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tuberculosis Testing Market Strategic Shifts
Diagnostic algorithm redesign is compressing the cascade from symptom onset to treatment initiation, with molecular platforms displacing sequential testing protocols that historically relied on microscopy confirmation.
Cartridge-based nucleic acid amplification technology is overtaking conventional laboratory workflows by embedding sample preparation, amplification, and detection within sealed disposable units. District hospitals and primary health centers in high-burden countries are adopting these platforms to bypass centralized laboratory bottlenecks. The technology is compressing diagnostic turnaround from weeks to hours, reducing pre-treatment loss to follow-up and enabling same-day treatment initiation.
EMA's Medical Device Regulation imposes post-market surveillance and clinical performance tracking obligations on in vitro diagnostic manufacturers operating in Europe. The regulation forces companies to maintain updated technical documentation and vigilance systems throughout product lifecycles. Smaller European manufacturers face disproportionate compliance costs, consolidating market access around established multinationals with dedicated regulatory affairs infrastructure.
Bulk procurement through multilateral financing institutions is consolidating supplier relationships and standardizing equipment platforms across national TB programs. The Global Drug Facility and UNITAID mechanisms now dominate volume purchasing for molecular diagnostics in low-income countries, displacing fragmented national tender processes. This concentration is most visible in sub-Saharan Africa and Southeast Asia, where ministries of health align procurement cycles with Global Fund disbursement timelines.
Tuberculosis Testing Market Segmentation
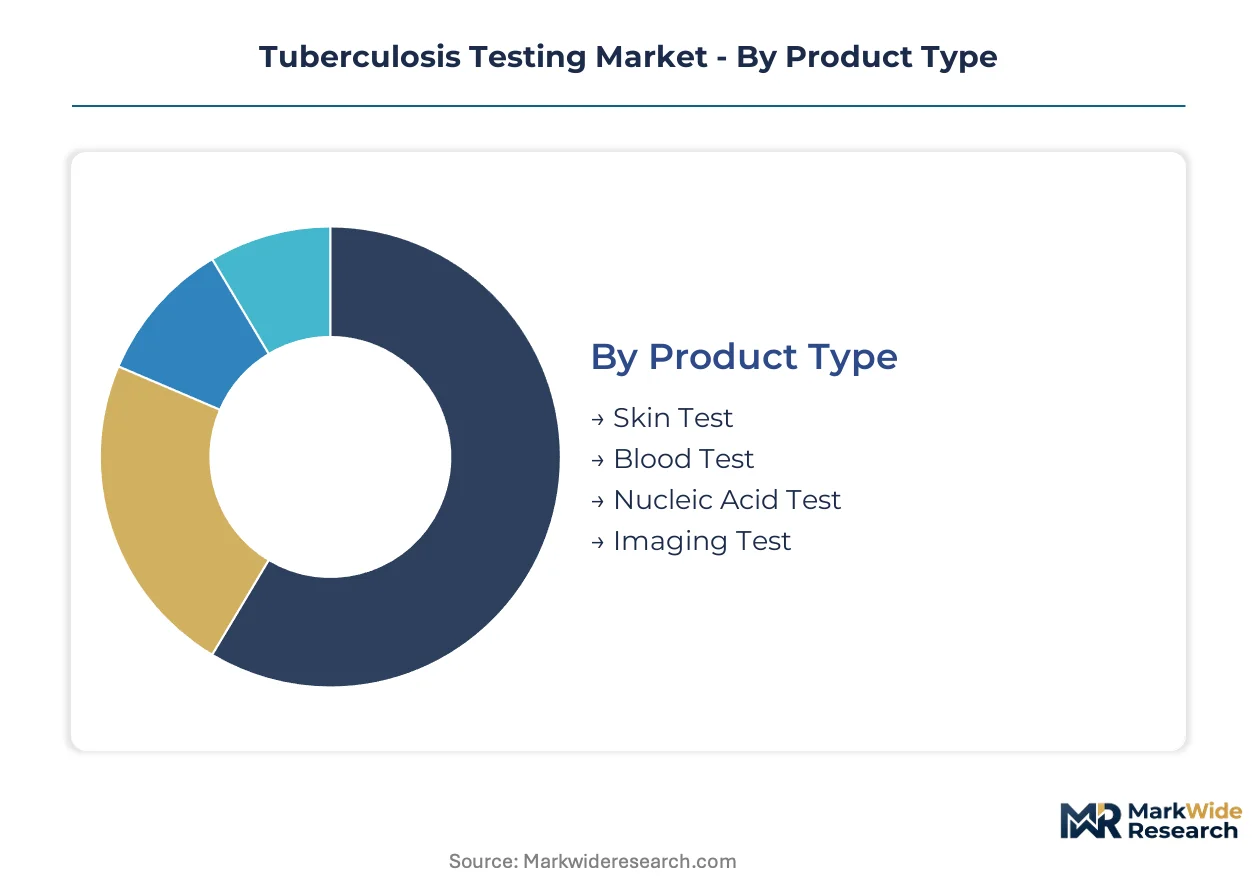
Segmentation in tuberculosis testing reveals divergent capital requirements across diagnostic modalities. Procurement agencies split budgets between high-accuracy molecular platforms and coverage-oriented conventional tests, creating distinct investment profiles for manufacturers and health systems.
Product Type:
Capital intensity peaks with nucleic acid amplification platforms requiring cartridge manufacturing ecosystems and cold-chain logistics, while skin tests demand minimal infrastructure.
- Nucleic Acid Test:Cartridge-based molecular systems embed sample preparation, amplification, and detection within sealed disposable units. District hospitals in India and South Africa deploy these platforms to bypass centralized laboratory bottlenecks, compressing diagnostic turnaround from weeks to hours. WHO prequalification requirements and Global Drug Facility procurement eligibility concentrate demand among approved suppliers.
- Imaging Test:Chest radiography and computed tomography detect pulmonary lesions and extrapulmonary manifestations where bacteriological confirmation remains elusive. AI-assisted radiological screening converges with smartphone-based image transmission to triage patients in Indonesian archipelago settings lacking molecular capacity, though Biosafety Level 3 infrastructure requirements strain capital budgets.
- Blood Test:Interferon-gamma release assays measure T-cell immune response for latent TB detection in occupational health and immigration medical examinations.
- Skin Test:Tuberculin purified protein derivative tests require minimal equipment investment and remain deployed for coverage expansion in peripheral health facilities.
Nucleic acid tests absorb the bulk of installed capacity in reference laboratories; imaging tests are expanding most quickly through AI-augmented deployment models.
Technology:
Margin profiles diverge sharply between proprietary molecular ecosystems and commodity biochemical platforms, with radiological methods occupying a mid-tier position.
- Molecular:Nucleic acid amplification technologies detect Mycobacterium tuberculosis genetic material with analytical sensitivity exceeding smear microscopy. Cepheid's cartridge-based systems and Roche's integrated workflow automation dominate procurement in high-burden countries, locking purchasers into single-source consumables that limit price negotiation leverage for ministries of health.
- Radiological:X-ray and CT modalities visualize pulmonary lesions for treatment monitoring and extrapulmonary case detection. Computer-aided detection algorithms are gaining regulatory clearance under FDA and EMA pathways, enabling deployment by radiographers rather than specialist physicians in South African district hospitals.
- Biochemical:Smear microscopy and culture-based methods remain reference standards for drug susceptibility testing despite extended turnaround times.
- Optical:Fluorescence microscopy and LED-based illumination systems upgrade conventional laboratory workflows with lower capital requirements than molecular platforms.
Molecular technology commands premium pricing through cartridge lock-in; radiological methods are climbing the fastest as AI integration reduces operator skill barriers.
End User:
Customer concentration varies by testing volume, with national TB programs consolidating procurement around diagnostic centers while clinics represent fragmented demand.
- Diagnostic Centers:High-throughput facilities process centralized samples from multiple catchment areas, prioritizing automated workflow integration and laboratory information system connectivity. India's national TB program channels molecular test volumes through accredited diagnostic centers meeting CDSCO quality standards and NABL accreditation requirements.
- Hospitals:Tertiary care institutions require comprehensive testing menus spanning screening, diagnosis, monitoring, and drug resistance surveillance. South Africa's academic hospital complexes anchor reference laboratory networks that confirm complex extrapulmonary cases and perform second-line molecular resistance testing.
- Laboratories:Public health and private reference laboratories serve as nodal points for quality assurance and external quality assessment distribution.
- Clinics:Primary health centers and occupational health clinics drive latent TB screening volumes through point-of-care blood test platforms.
Diagnostic centers capture the steepest expansion trajectory as national programs consolidate testing networks; hospitals retain stable demand for complex case confirmation.
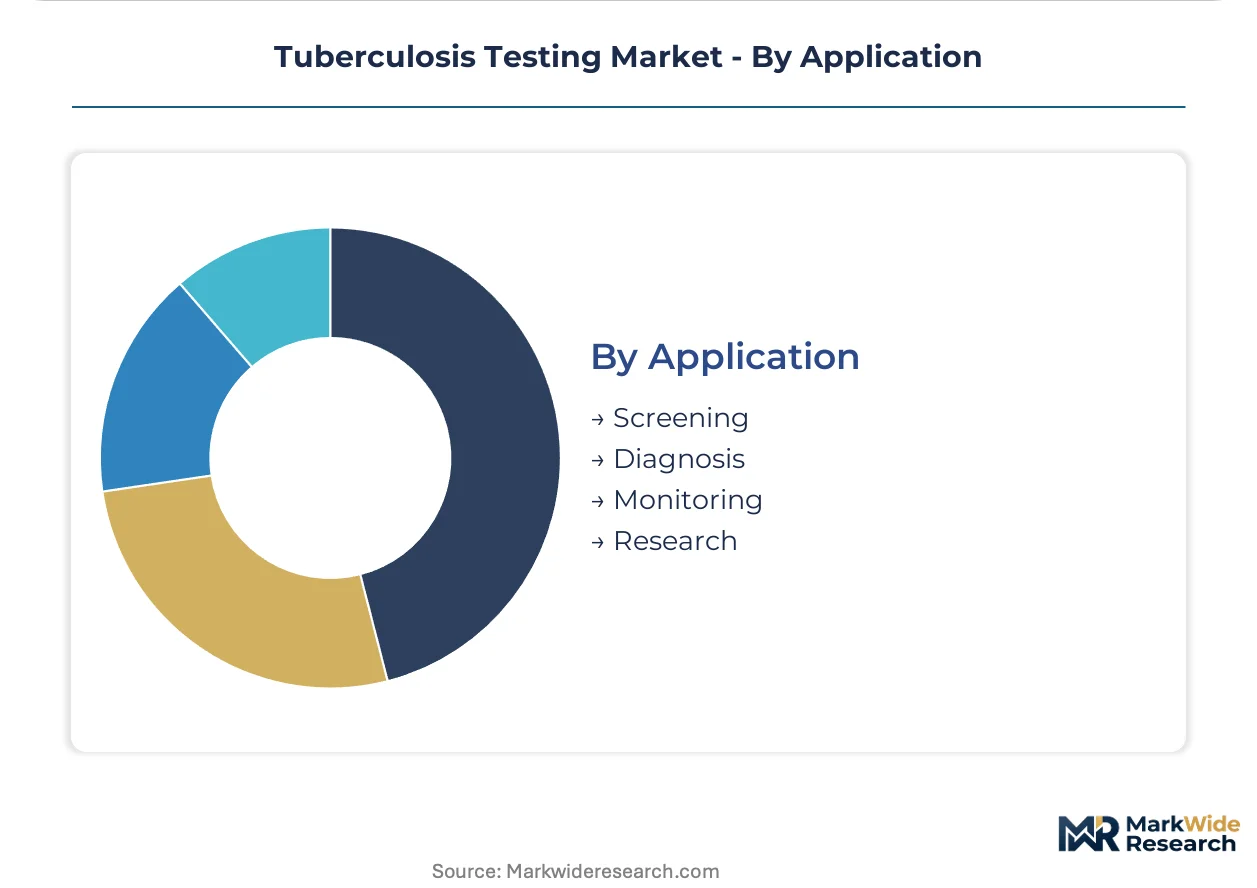
Application:
Revenue recurrence differs dramatically between one-time diagnosis and longitudinal monitoring, with screening programs offering predictable volume commitments.
- Diagnosis:Confirmatory testing for symptomatic patients initiates treatment cascades and contact tracing protocols. WHO End TB Strategy targets mandate universal access to rapid diagnostics, compelling procurement scale-up in Indonesia where dispersed island geography creates demand for decentralized testing networks beyond Java and Sumatra.
- Screening:Asymptomatic population testing in high-risk groups and immigration medical examinations generates recurring latent TB detection volumes. Healthcare worker surveillance programs in developed health systems sustain interferon-gamma release assay demand through annual testing protocols.
- Monitoring:Treatment response assessment requires serial imaging and bacteriological confirmation to document conversion and cure.
- Research:Clinical trials and epidemiological studies consume specialized drug resistance panels and novel biomarker platforms.
Diagnosis claims dominant procurement allocation under WHO guidance; screening is gaining share fastest through occupational health mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Johannesburg anchors diagnostic infrastructure investment across sub-Saharan Africa, with national TB programs channeling procurement through centralized reference laboratories serving dispersed catchment populations.
India
The National Tuberculosis Elimination Programme drives molecular platform deployment through accredited diagnostic centers meeting CDSCO quality standards. India's PLI scheme for medical devices incentivizes domestic manufacturing of diagnostic components. Delhi-NCR and Mumbai-Pune corridors concentrate procurement decision-making for cartridge-based systems serving high-burden states.
South Africa
Academic hospital complexes in Johannesburg and Cape Town anchor reference laboratory networks confirming complex extrapulmonary cases. The South African Health Products Regulatory Authority enforces local quality standards influencing government tender awards. KwaZulu-Natal and Eastern Cape provinces receive prioritized decentralization of point-of-care molecular capacity.
Indonesia
Dispersed island geography beyond Java and Sumatra creates structural demand for decentralized testing networks reaching peripheral health facilities. The national TB program aligns procurement with Global Fund disbursement timelines. Papua and Eastern Indonesia sub-regions represent underpenetrated expansion corridors for cartridge-based platforms.
United States
Occupational health surveillance programs and immigration medical examinations sustain recurring latent TB detection volumes through interferon-gamma release assays. FDA clearance pathways shape product commercialization timelines for domestic manufacturers. Boston and San Francisco metropolitan areas concentrate research institutions developing novel diagnostic algorithms.
Germany
EMA oversight of in vitro diagnostic medical devices under EU MDR imposes clinical evidence requirements filtering market access. Baden-Württemberg and Bavaria host precision engineering clusters supplying automated diagnostic system components. German reference laboratories participate in WHO external quality assessment schemes for molecular resistance testing.
Tuberculosis Testing Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the tuberculosis testing landscape, with integrated diagnostic conglomerates maintaining manufacturing scale advantages over specialized assay developers. The market structure consolidates around three strategic tiers: multinational platform manufacturers with cartridge ecosystems, reference laboratory service providers, and regional distributors securing government tender access. Dominant competitive moves include strategic partnerships with multilateral health financing institutions and portfolio diversification into multidisease platform configurations.
Among Swiss-German diagnostic conglomerates, F. Hoffmann-La Roche and QIAGEN occupy positions exemplifying integrated workflow automation and latent TB detection specialization respectively. Cepheid, operating within the Danaher corporation, represents the point-of-care molecular archetype designed for resource-limited settings. These three anchors illustrate the divergence between premium laboratory systems and decentralized cartridge-based platforms reshaping procurement patterns in high-burden countries.
| Leading Market Players |
|---|
| QIAGEN |
| F. Hoffmann-La Roche |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Becton Dickinson |
| Cepheid (Danaher) |
| bioMérieux |
| Hologic |
| Oxford Immunotec |
| Others |
Value Chain & Pricing Dynamics
National TB programs in India, South Africa, and Indonesia anchor procurement volume and enforce value-based pricing tied to diagnostic throughput and same-day treatment initiation rates. This buyer concentration compresses margin structures for cartridge-based molecular systems while elevating price sensitivity at the primary health center tier.
Pricing Analysis
Throughput-linked value pricing dominates cartridge-based nucleic acid amplification platforms, with ministries of health negotiating per-test rates scaled to annual volume commitments. Price differentiation rests on WHO prequalification status and cold-chain independence, with certified platforms commanding premiums over conventional laboratory workflows. Cost compression in the skin test segment intensifies as national programs prioritize coverage expansion over accuracy, while reference laboratories show lowest price sensitivity due to integrated workflow automation requirements and resistance panel complexity.
Supply Chain Analysis
Single-source vulnerability sits with proprietary cartridge manufacturing concentrated in the United States, Germany, and Switzerland, where precision molding and reagent stabilization capabilities anchor production. Raw material dependencies include specialized thermoplastics, lyophilized reagents, and optical detection components. Tariff exposure on diagnostic device imports strains procurement budgets in resource-constrained settings. Distribution runs through multilateral financing institutions such as the Global Drug Facility and UNITAID, which consolidate volume purchasing and standardize equipment platforms across national programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around platform manufacturers with cartridge ecosystems, as EU MDR compliance costs and WHO prequalification barriers force specialized assay developers toward acquisition or exit.
For Market Incumbents: To counter proprietary cartridge lock-in by point-of-care molecular specialists, deepen backward integration into reagent manufacturing and secure exclusive distribution agreements with multilateral health financing institutions. Prioritize multidisease platform reconfiguration to capture COVID-19 and respiratory pathogen procurement cycles alongside TB diagnostics. For New Entrants and Emerging Players: Begin with AI-assisted radiological screening in the Indonesian archipelago, where dispersed island geography and limited laboratory infrastructure create white-space demand beyond cartridge-based molecular capacity. Target occupational health clinics in developed health systems with interferon-gamma release assay alternatives, leveraging simplified workflow automation to displace incumbent latent TB detection platforms. For Investors and Strategic Acquirers: Distressed-cycle entries favor European in vitro diagnostic manufacturers facing disproportionate EU MDR compliance costs in Germany and Switzerland, where precision engineering clusters supply automated system components. Long-term viability hinges on WHO prequalification pathway completion and Global Drug Facility procurement eligibility. Watch for policy guidance shifts on novel diagnostic algorithms as the inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks Global Drug Facility procurement eligibility for high-burden country tenders. |
| Cartridge Manufacturing Scale-Up | Reduces per-test costs for ministries of health through volume-based production economics. |
| Multidisease Platform Integration | Captures respiratory pathogen procurement cycles alongside TB diagnostics in district hospitals. |
| AI-Assisted Radiological Screening | Enables deployment by radiographers rather than specialist physicians in resource-limited settings. |
| Reimbursement Strategy Development | Secures favorable coding for interferon-gamma release assays in occupational health surveillance programs. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with national TB program directors, hospital procurement committees, biomedical engineers, and GPO contracts managers. FDA 510(k) clearances, EMA MDR technical documentation, WHO prequalification assessments, and Global Fund disbursement records provided validation. Bottom-up installed base modeling and top-down procurement budget analysis were triangulated against manufacturer shipment disclosures.
Segment-level granularity modeled nucleic acid test, imaging test, blood test, and skin test categories across molecular, radiological, biochemical, and optical technologies. End-user splits covered diagnostic centers, hospitals, laboratories, and clinics. Application dimensions spanned diagnosis, screening, monitoring, and research. CAGRs were derived from multivariate regression against national TB program expenditure forecasts and WHO End TB Strategy target timelines. Resistance surveillance panel demand and AI-augmented radiological deployment curves informed technology-specific trajectory adjustments.
Regulatory approval delays, cartridge supply disruptions, and policy algorithm revisions are the dominant revision risks to installed base and procurement volume assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
US Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Global Direct-To-Consumer (DTC)Testing Market
Testing Services
Global Endotoxin and Pyrogen Testing Market
Testing Services
Carbapenem-Resistant Enterobacteriaceae Testing Market
Testing Services
Asia-Pacific Antimicrobial Susceptibility Testing Market
Testing Services
Europe Mass Spectrometry Market
Testing Services
Healthcare Analytical Testing Services Market
Testing Services
Global Roadside Drug Testing Devices Market
Testing Services
Thailand Point-Of-Care Testing (POCT) Market
Testing Services
North America Endotoxin and Pyrogen Testing Market
Testing Services
Biological Indicator Incubators Market
Testing Services
US at-Home Testing Kits Market
Testing Services
Global Rapid Test Market
Testing Services
Drug Tester Market
Testing Services
Global Ovulation Test Market
Testing Services
Rapid Sterility Testing Market