
 Sterilization Monitoring Technologies Market | 2026-2036
Sterilization Monitoring Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Sterilization Monitoring Technologies Market Analytics
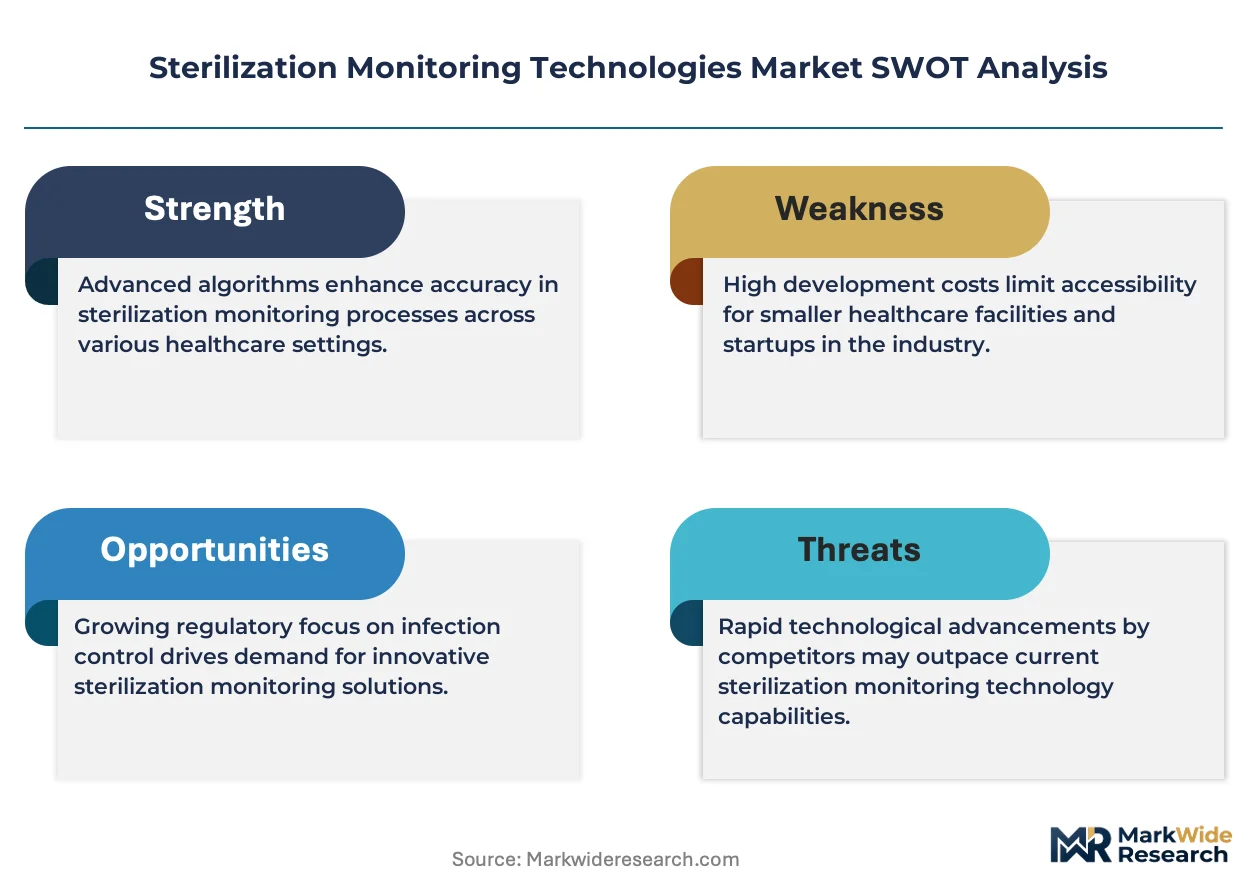
China's medical device manufacturing corridor is fragmenting as domestic producers build sterilization validation capacity for export markets. 3M Company anchors North American biological indicator supply through captive resin formulation and automated reader production. STERIS competes in vaporized hydrogen peroxide sterilizer monitoring with integrated software platforms that tie cycle data to hospital information systems. Getinge AB dominates steam sterilization monitoring in European hospital networks with washer-disinfector and autoclave bundled service contracts.
Sterilization monitoring technologies encompass biological indicators containing Geobacillus stearothermophilus or Bacillus atrophaeus spores, chemical indicators with calibrated color-change chemistry, and automated systems that capture pressure, temperature, and sterilant concentration parameters across each cycle to verify microbial lethality. Biological indicators sustain premium positioning due to their direct measurement of spore kill rates versus process surrogates. Chemical indicators occupy high-volume consumable roles in dental practices and outpatient clinics where rapid turnaround limits biological indicator incubation windows.
FDA's updated guidance on sterilization process controls and EPA's ethylene oxide emissions regulations are forcing healthcare facilities to document every sterilization cycle with auditable digital records. Europe's MDR and F-Gas Regulation restrict certain sterilant chemistries and mandate revalidation of legacy equipment, which expands replacement demand for compliant monitoring systems. Stakeholders must weigh hydrogen peroxide sterilizer adoption against existing ethylene oxide infrastructure as regulatory pressure intensifies without predictable phase-out timelines.
Market Dynamics
Centralized sterile supply departments in acute care hospitals are consolidating biological indicator procurement under multi-year service contracts, compressing vendor margins while locking in volume commitments. This procurement concentration is reshaping competitive positioning across biological and chemical indicator segments.
Growth Catalysts
- MDR compliance deadlines:Europe's Medical Device Regulation mandates revalidation of legacy sterilization equipment, forcing hospital networks to upgrade monitoring systems with continuous digital documentation capabilities.
- Ethylene oxide phase-out pressure:EPA emissions enforcement is accelerating vaporized hydrogen peroxide sterilizer deployment in US device manufacturing facilities, expanding demand for compatible chemical indicators.
- Dental service organization consolidation:DSO chains are standardizing sterilization protocols across multi-site practices, creating bulk purchasing pull for rapid-turnaround chemical indicator strips.
Market Restraints
- Biological indicator resin concentration:Polymer substrates for spore carriers concentrate among three specialty chemical suppliers in Germany and Japan, exposing indicator manufacturers to input cost volatility.
- Ethylene oxide infrastructure lock-in:Existing sterilization chambers and abatement systems represent sunk capital that delays hydrogen peroxide conversion timelines even where regulations permit.
- Incubation time physics:Seven-day biological indicator readouts remain necessary for terminal sterilization validation, limiting penetration into same-day surgical settings regardless of automation advances.
Strategic Opportunities
- China export corridor expansion:Domestic device manufacturers building sterilization validation capacity for EU and US markets need compliant monitoring systems with traceable documentation chains.
- Cloud-based cycle integration:Hospital information system vendors are opening APIs for sterilizer data ingestion, creating white space for middleware platforms that aggregate multi-vendor cycle logs.
- Point-of-care sterilization growth:Ambulatory surgery centers performing joint replacements outside hospital walls require portable monitoring solutions with wireless result transmission.
Industry Challenges
- Microbiology specialist scarcity:Hospital sterile processing departments struggle to hire technicians trained in spore culture interpretation and incubator calibration protocols.
- Legacy autoclave integration:Steam sterilizers installed before 2015 lack digital output ports, requiring expensive retrofit kits to enable automated cycle capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterilization Monitoring Technologies Market |
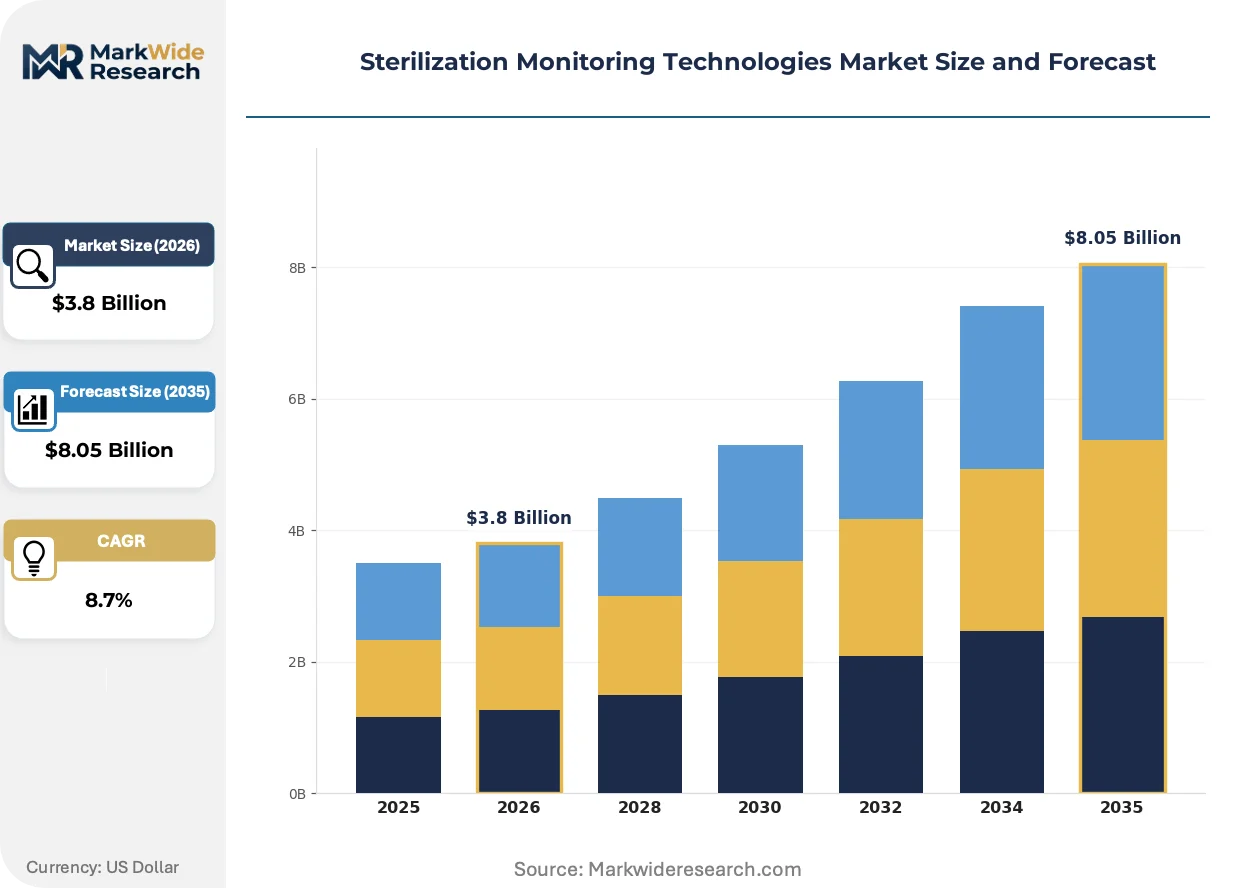
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Biological Indicators, Chemical Indicators, Automatic Monitoring Systems, Manual Monitoring Systems Application: Healthcare Facilities, Pharmaceutical Manufacturing, Laboratory Use, Veterinary Services Product Type: Steam Sterilizers, Ethylene Oxide Sterilizers, Hydrogen Peroxide Sterilizers, Dry Heat Sterilizers End User: Hospitals, Clinics, Research Laboratories, Dental Practices |
| Companies Covered | 3M Company, STERIS, Getinge AB, Cantel Medical, Mesa Laboratories, Cardinal Health, Propper Manufacturing, Matachana Group, Terragene, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterilization Monitoring Technologies Market Evolving Landscape
Digital integration is collapsing the latency between sterilization cycle completion and documentation availability, compressing instrument turnaround times while building audit-ready record trails. Three technology and behavioral shifts are reshaping competitive positioning.
Rapid-read fluorescent biological indicators are collapsing the traditional seven-day incubation window to under one hour through enzyme-based detection chemistry. Ambulatory surgery centers in the United States are adopting these systems at accelerated pace to support same-day discharge protocols. This speed compression is enabling procedure volume expansion in outpatient settings previously constrained by instrument flow logistics.
REACH restrictions on ethylene oxide precursors are forcing contract sterilizers toward vaporized hydrogen peroxide and nitrogen dioxide alternatives with different validation requirements. European device manufacturers are rebuilding sterilization process documentation from first principles to satisfy notified body scrutiny. Steam sterilization monitoring is gaining relative share in European hospital procurement as hydrogen peroxide adoption creates dual-protocol complexity.
Group purchasing organizations are unbundling sterilization monitoring from capital equipment contracts, creating direct relationships between indicator suppliers and sterile processing managers. This channel disintermediation is displacing distributor-mediated sales in US hospital networks. Academic medical centers with centralized supply chains are piloting consignment inventory models where vendors manage par levels directly.
Sterilization Monitoring Technologies Market Segmentation
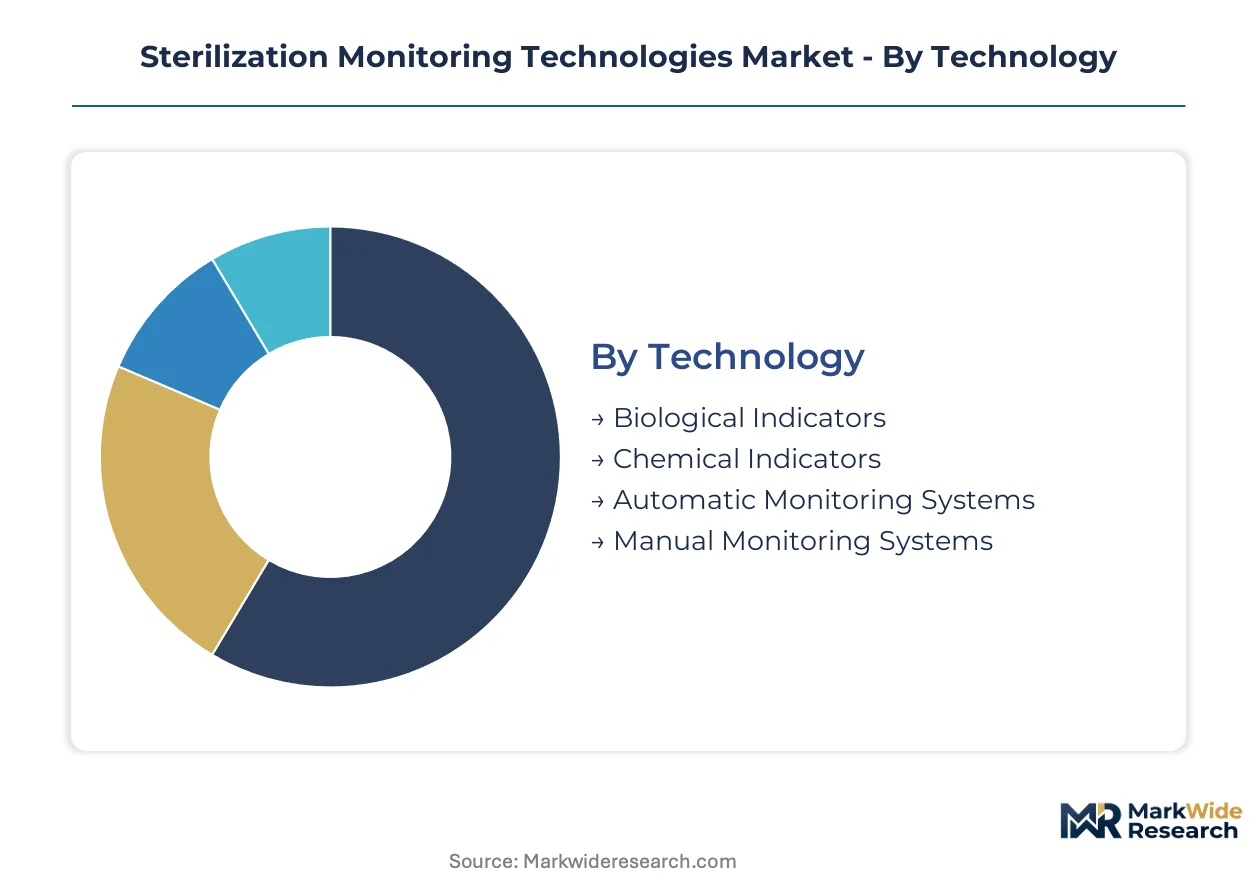
Sterilization monitoring technologies fragment across multiple axes that determine procurement patterns and margin structures. Cycle-time requirements, sterilant chemistry compatibility, and documentation intensity vary sharply by segment, creating distinct competitive arenas with little technology overlap.
Technology:
Cycle times range from under one hour for rapid-read enzyme systems to seven days for terminal biological indicator incubation, compressing addressable markets for slower technologies.
- Biological Indicators:Spore-based validation using Geobacillus stearothermophilus or Bacillus atrophaeus delivers direct microbial lethality measurement. Acute care hospitals in Germany mandate continuous biological indicator integration per centralized sterile supply protocols, though seven-day incubation physics limits same-day surgical penetration.
- Chemical Indicators:Calibrated color-change chemistry provides immediate visual confirmation of sterilant exposure. Dental practices and outpatient clinics in the United States drive high-volume consumable demand where rapid turnaround compresses biological indicator windows.
- Automatic Monitoring Systems:Pressure, temperature, and sterilant concentration capture with digital audit trails.
- Manual Monitoring Systems:Paper-based cycle logs and visual indicator interpretation for low-throughput settings.
Chemical indicators anchor the volume base while biological indicators gain share at the steepest rate.
Application:
Documentation stringency scales with patient risk exposure, creating four tiers of validation intensity from pharmaceutical terminal sterilization to veterinary instrument reprocessing.
- Healthcare Facilities:Acute care hospitals face FDA enforcement of medical device sterilization validations with mandatory digital record retention. Centralized sterile supply departments consolidate procurement under multi-year service contracts, compressing vendor margins while locking volume commitments.
- Pharmaceutical Manufacturing:Ethylene oxide and vaporized hydrogen peroxide process validation with full batch release documentation. EPA emissions enforcement accelerates hydrogen peroxide deployment, expanding compatible chemical indicator demand.
- Laboratory Use:Research-grade sterilization with flexible cycle parameter adjustment.
- Veterinary Services:Reduced regulatory burden permits simplified indicator protocols.
Healthcare facilities dominate procurement volume while pharmaceutical manufacturing expands most quickly on sterilant chemistry transition.
Product Type:
Steam sterilizers deliver the fastest cycle completion and lowest per-cycle documentation burden, while alternative chemistries require specialized indicator formulations.
- Steam Sterilizers:Autoclave-based sterilization with temperature-pressure monitoring dominates European hospital procurement. Getinge AB bundles washer-disinfector and autoclave service contracts across hospital networks, locking in monitoring system placement.
- Hydrogen Peroxide Sterilizers:Vaporized hydrogen peroxide alternatives gain share amid ethylene oxide phase-out pressure. STERIS competes with integrated software platforms tying cycle data to hospital information systems, capturing replacement demand from EPA-driven conversions.
- Ethylene Oxide Sterilizers:Legacy chamber infrastructure with specialized abatement systems.
- Dry Heat Sterilizers:Depyrogenation applications for heat-stable pharmaceutical containers.
Steam sterilizers retain the installed base while hydrogen peroxide systems climb the fastest on regulatory displacement.
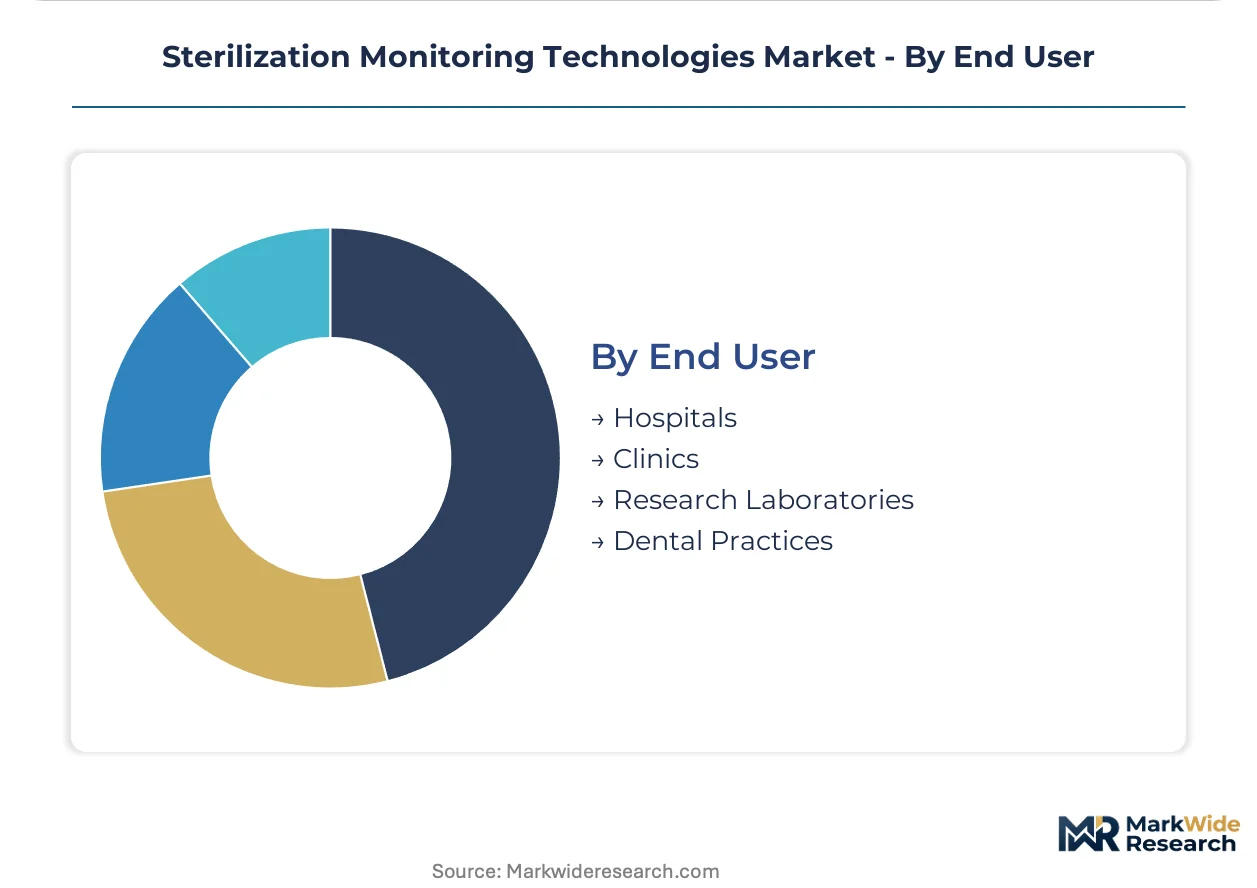
End User:
Procurement sophistication varies from enterprise-grade GPO-negotiated contracts in hospital systems to individual practice purchasing in dental settings.
- Hospitals:Centralized sterile supply departments with multi-vendor cycle log aggregation requirements. Group purchasing organizations unbundle monitoring from capital equipment contracts, creating direct supplier relationships and displacing distributor mediation.
- Dental Practices:Dental service organization consolidation standardizes protocols across multi-site chains, generating bulk purchasing pull for rapid-turnaround chemical indicator strips. Ambulatory settings prioritize speed over terminal validation.
- Clinics:Outpatient surgical centers with portable monitoring needs.
- Research Laboratories:Academic medical centers piloting consignment inventory models with vendor-managed par levels.
Hospitals concentrate procurement value while dental practices generate the steepest volume expansion on DSO consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Europe's sterilization validation supply chain, while Shanghai Yangshan deep-water port anchors Asia-Pacific device export corridors.
United States
EPA ethylene oxide emissions enforcement is accelerating vaporized hydrogen peroxide sterilizer deployment across device manufacturing facilities. FDA's updated sterilization process control guidance mandates auditable digital records for every cycle. Minneapolis-St. Paul's medical device cluster is rebuilding validation protocols to satisfy notified body scrutiny for EU market access.
Germany
Centralized sterile supply departments in university hospital networks mandate continuous biological indicator integration per MDR compliance deadlines. REACH restrictions on ethylene oxide precursors are forcing contract sterilizers toward alternative chemistries. Baden-Württemberg's precision engineering belt is supplying automated reader hardware for rapid-turnaround enzyme detection systems.
China
Domestic device manufacturers are building sterilization validation capacity for EU and US export markets, driving demand for compliant monitoring systems. NMPA's alignment with international standards is tightening process documentation requirements. Suzhou's medical device manufacturing corridor is fragmenting as producers establish captive sterilization facilities with traceable documentation chains.
Japan
PMDA's quality management system inspections are elevating documentation intensity for sterilization process validation. METI's industrial standards harmonization is accelerating adoption of ISO-compliant monitoring technologies. Osaka-Kobe's pharmaceutical manufacturing belt is retrofitting legacy autoclaves with digital output ports for automated cycle capture.
India
CDSCO's medical device rules are mandating sterilization validation for Class C and D device registrations, expanding indicator demand among domestic manufacturers. PLI scheme incentives for medical device production are attracting sterilization infrastructure investment. Gujarat's Special Economic Zones are hosting contract sterilization facilities serving export-oriented device makers.
Sterilization Monitoring Technologies Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin formulation and spore carrier production. Market structure consolidates around three specialty chemical suppliers in Germany and Japan for polymer substrates, while indicator assembly fragments across regional fabricators. Two archetypes dominate: captive resin formulators with backward integration into biological indicator production, and software-integrated sterilizer OEMs bundling monitoring into service contracts. Competitive moves center on multi-year hospital service contract lock-ins and distributor disintermediation through direct sterile processing manager relationships.
Among North American platform integrators, 3M Company and STERIS exemplify contrasting archetypes: the former anchors biological indicator supply through captive resin formulation, while the latter competes on vaporized hydrogen peroxide sterilizer monitoring with integrated software platforms. Getinge AB represents the European system-tier model, dominating steam sterilization monitoring through washer-disinfector and autoclave bundled service contracts across hospital networks.
| Leading Market Players |
|---|
| 3M Company |
| STERIS |
| Getinge AB |
| Cantel Medical |
| Mesa Laboratories |
| Cardinal Health |
| Propper Manufacturing |
| Matachana Group |
| Terragene |
| Others |
Value Network & Pricing Analysis
Undercapacity in Germany's specialty polymer substrate production is squeezing biological indicator manufacturers into multi-year offtake commitments, compressing margin flexibility while locking input cost exposure. This utilization tightness propagates through to sterilization monitoring pricing tiers, where resin concentration among three suppliers in Germany and Japan anchors supplier power across the value chain.
Pricing Analysis
Europe's MDR compliance deadlines dictate the pricing tier structure across sterilization monitoring technologies. Three-tier pricing structure across premium, standard, and economy levels separates rapid-read enzyme systems from conventional biological indicators and basic chemical strips. Price differentiation hinges on FDA 510(k) clearance status and ISO 11138 compliance tier. Cost compression in the standard tier is intensifying because GPOs are unbundling monitoring from capital equipment contracts. Dental service organizations exhibit the highest price sensitivity due to volume consolidation pressures, while German university hospital networks show lowest sensitivity given MDR-mandated revalidation timelines.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for resin substrate procurement, straining working capital for indicator assemblers. Polymer substrate supply concentrates in Germany and Japan, with spore carrier cultivation anchored in the United States. Raw material dependencies include specialty phenolic resins, Geobacillus stearothermophilus spore cultures, and calibrated color-change chemistry precursors. Single-source vulnerability in German resin formulation creates exposure to REACH regulatory restrictions. Distribution runs through group purchasing organizations and direct sterile processing manager relationships, displacing traditional distributor mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sterilization monitoring market is entering a cyclical recovery phase as MDR compliance deadlines and EPA ethylene oxide enforcement create replacement demand waves. Hospital capital expenditure cycles and regulatory revalidation timelines provide the cyclical driver.
For Market Incumbents: Entrench position through captive resin formulation capacity in Germany or Japan, securing substrate supply against specialty chemical supplier concentration. Lock in multi-year service contracts with centralized sterile supply departments before GPO unbundling accelerates. Defend against STERIS software-integrated platforms by embedding automated readers into washer-disinfector bundles. Priority lever: backward integration into spore carrier production to reduce input volatility.
For New Entrants and Emerging Players: China's domestic device manufacturers building EU export validation capacity represent the most penetrable entry point, as NMPA alignment with international standards creates documentation system demand gaps. Ambulatory surgery centers in the United States adopting same-day discharge protocols need portable rapid-read systems with wireless transmission. Go-to-market angle: cloud-based middleware platforms aggregating multi-vendor cycle logs through hospital information system APIs.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated monitoring system assembly due to digital output port retrofit requirements for legacy autoclaves. Long-term viability favors platform integrators with software-sterilizer bundling capability over component suppliers. Acquisition target archetype: rapid-read enzyme detection specialists with FDA-cleared one-hour incubation systems. Signal to watch: EPA ethylene oxide phase-out timeline clarity as hydrogen peroxide conversion acceleration indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR compliance deadlines force revalidation documentation upgrades across European hospital networks. |
| Hospital System Partnership | Centralized sterile supply departments consolidate procurement under multi-year service contracts. |
| Software Companion Development | Cloud-based middleware platforms capture cycle data through hospital information system APIs. |
| Backward Integration | Captive resin formulation secures polymer substrate supply against German-Japanese supplier concentration. |
| Reimbursement Strategy | Same-day surgical discharge protocols in ambulatory centers drive rapid-read system adoption. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EPA emissions enforcement records, and European notified body guidance documents. Primary interviews engaged sterile processing department managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads at sterilizer OEMs. Secondary validation drew from hospital procurement databases, MDR implementation timelines, and customs trade data for resin substrate flows. Bottom-up indicator demand modeling triangulated against top-down healthcare capital expenditure forecasts.
Forecast inputs span technology adoption curves across biological, chemical, and automated monitoring systems; sterilant chemistry transition timelines from ethylene oxide to hydrogen peroxide; and end-user segmentation by hospital, dental, pharmaceutical, and laboratory channels. Segmentation dimensions modeled include technology type, application intensity, product chemistry, and procurement sophistication tier. CAGRs were derived from installed base replacement cycles and regulatory compliance-driven upgrade patterns. Industry-specific inputs incorporate MDR revalidation deadlines and EPA emissions enforcement trajectories.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles or healthcare reimbursement rates would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline adherence and sterilant chemistry transition pace. Technological disruption from next-generation rapid-read systems, regulatory acceleration of ethylene oxide phase-outs, or supply chain disruption in specialty resin markets would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Cannabis Testing Market
Testing Services
Hbsag Testing Market
Testing Services
Global ADME Toxicology Testing Market
Testing Services
Global Endocrine Testing Market
Testing Services
Special Coagulation Tests Market
Testing Services
Home Care Testing Market
Testing Services
Global Creatinine Assay Kits Market
Testing Services
Pharmaceutical Analytical Testing Market
Testing Services
Asia-Pacific Viral Clearance Market
Testing Services
India GMP Testing Service Market
Testing Services
Irradiation Sterilization Services Market
Testing Services
Skin Perfusion Pressure Testing Devices Market
Testing Services
Viral Vector Integrity and Potency Analytics Test Instruments Market
Testing Services
Retrovirus Testing Market
Testing Services
Host Cell Protein Testing Market
Testing Services
Drug Testing Equipment Market