
 Ethyl Alcohol (Ethanol) Market | 2026-2036
Ethyl Alcohol (Ethanol) Market Size, Share, and Industry Trends Forecast 2026-2036
Ethyl Alcohol (Ethanol) Market Foresight
Buyer concentration among fuel blenders and chemical processors is rebalancing as renewable energy mandates fragment procurement across regional biofuel cooperatives and national oil companies. POET, LLC leverages its integrated grain-to-ethanol network across the US Midwest to sustain volume leadership in fuel-grade supply. Cargill anchors its position through diversified feedstock sourcing and global distribution infrastructure for industrial and beverage grades. Raízen competes in Brazil through its sugarcane-based ethanol platform and downstream biofuel retail operations.
Ethyl alcohol is a volatile, flammable, colorless liquid with the chemical formula C₂H₅OH, typically produced via fermentation of sugars by yeasts or petrochemical hydration processes, with purity grades ranging from 95% to absolute ethanol depending on end-use requirements. It serves as a universal solvent, fuel oxygenate, antiseptic agent, and intoxicating base in beverages across industrial, pharmaceutical, and consumer applications. Fuel-grade ethanol dominates volume throughput due to mandatory blending requirements in transportation fuels, while pharmaceutical-grade commands premium margins driven by stringent USP and EP purity standards for vaccine and drug formulation. Beverage-grade ethanol maintains stable demand through spirits manufacturing, though growth rates trail fuel and pharmaceutical applications.
The US EPA administers Renewable Fuel Standard obligations that mandate minimum ethanol volumes in transportation fuel pools, while Brazil's ANP enforces RenovaBio carbon intensity targets that favor sugarcane ethanol pathways. REACH registration requirements in Europe constrain import volumes by demanding full toxicological and environmental fate documentation for industrial ethanol uses. Stakeholders must monitor evolving lifecycle carbon accounting methodologies and feedstock sustainability certifications that will determine eligibility for premium biofuel markets and green chemistry procurement programs.
Market Dynamics
Mandatory biofuel blending quotas in the United States and Brazil are compressing fuel-grade ethanol margins while redirecting capital toward carbon intensity reduction technologies. This regulatory compression is forcing processors to choose between feedstock diversification and geographic consolidation.
Growth Catalysts
- RenovaBio Carbon Targets:Brazil's ANP enforces escalating carbon intensity benchmarks that reward sugarcane ethanol pathways with premium biofuel credits, accelerating investment in bagasse cogeneration and process efficiency upgrades.
- Advanced Yeast Strains:Metabolic engineering of Saccharomyces cerevisiae is pushing fermentation yields past theoretical limits, enabling corn processors to extract more ethanol per bushel without expanding physical capacity.
- Pharmaceutical Cold Chain Expansion:Vaccine formulation demand for USP-grade ethanol is tightening purity specifications, creating dedicated supply streams that bypass commodity fuel markets entirely.
Market Restraints
- Feedstock Price Volatility:Corn futures in Chicago and sugar futures in São Paulo swing ethanol production economics by double-digit percentages within single growing seasons, eroding forward contract viability.
- Midwest Processing Concentration:Over sixty percent of US fuel-grade capacity sits within 300 miles of Des Moines, creating systemic weather and logistics risk that no single processor can hedge effectively.
- Cellulosic Ethanol Substitution:Second-generation biofuel technologies using agricultural residues threaten first-generation corn ethanol's eligibility for advanced biofuel credits under evolving EPA methodology.
Strategic Opportunities
- India Ethanol Blending Program:The country's 20% ethanol blending target by 2025 is opening import substitution opportunities for domestic molasses and grain-based processors with access to distillery modernization capital.
- Green Hydrogen Coproduction:Electrolyzer integration at existing ethanol plants enables dual-output facilities serving both transport fuel and industrial gas markets from shared renewable electricity offtake.
- Carbon Capture and Storage:45Q tax credits in the United States are subsidizing fermentation CO2 sequestration projects that transform ethanol plants into negative-emission assets qualifying for sustainable aviation fuel feedstock premiums.
Industry Challenges
- Continuous Fermentation Expertise Gap:The shift from batch to continuous processing requires biochemical engineers with rare hybrid skills in process control and microbial ecology, commanding compensation premiums that smaller cooperatives cannot match.
- REACH Registration Burden:European industrial ethanol importers face multi-year toxicological dossier preparation costs exceeding seven figures, effectively ceding market share to domestic producers with established ECHA compliance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethyl Alcohol (Ethanol) Market |
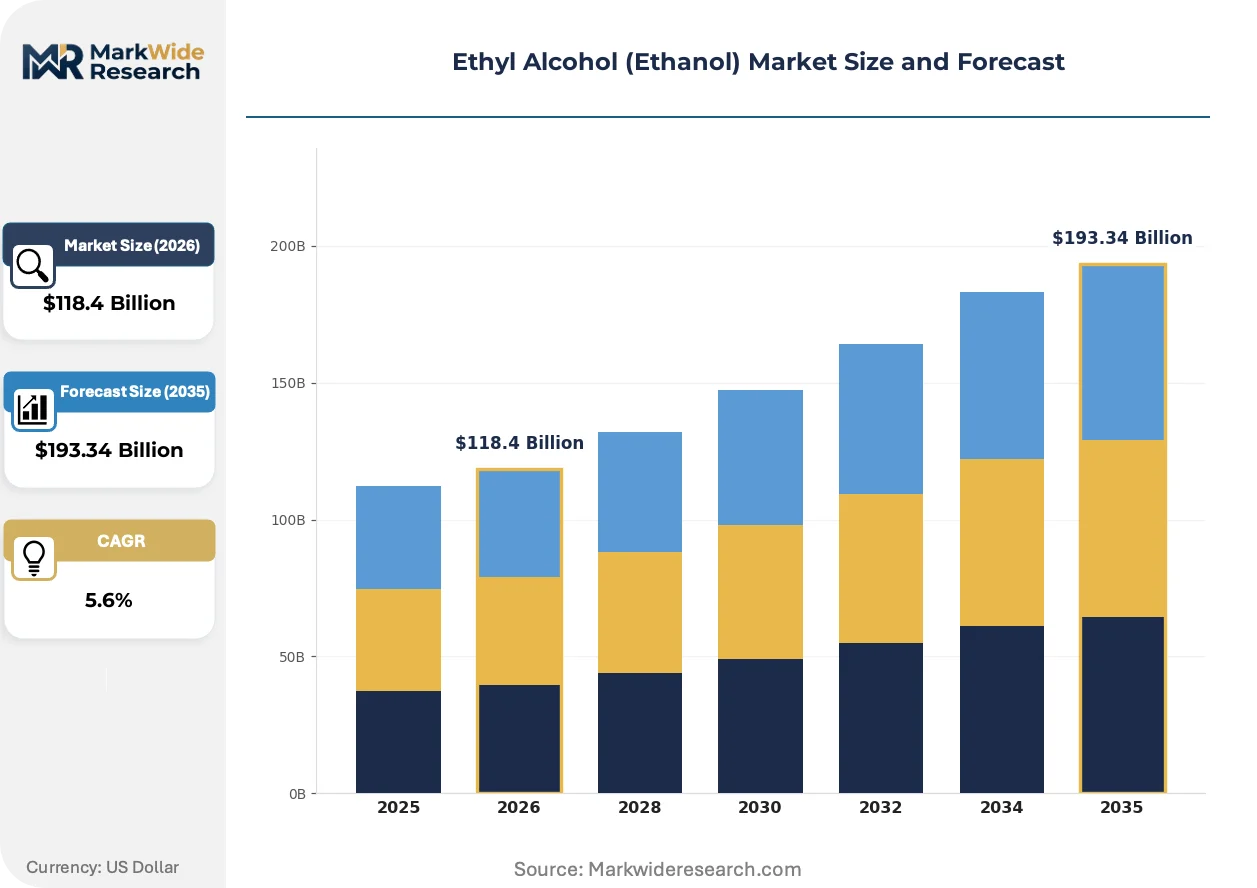
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $193.34 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Fuel Grade, Pharmaceutical Grade, Beverage Grade End User: Chemical Industry, Automotive, Food and Beverage, Pharmaceuticals Application: Solvent, Fuel Additive, Disinfectant, Preservative Distribution Channel: Direct Sales, Wholesale, Online Retail, Distributors |
| Companies Covered | Green Plains Inc., Koch Industries, POET, LLC, Cargill, The Andersons Inc., Valero Energy Corporation, Raízen, Flint Hills Resources, Archer Daniels Midland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethyl Alcohol (Ethanol) Market Shifts & Advancements
Carbon accounting methodologies are rewriting procurement criteria across transport fuel and chemical manufacturing, forcing ethanol suppliers to document feedstock provenance and process emissions with forensic precision. This traceability imperative is reshaping everything from farm-level agronomy to terminal blending operations.
Cellulosic pretreatment technology is consolidating around consolidated bioprocessing platforms that combine enzyme production, biomass hydrolysis, and fermentation in single-reactor systems. POET-DSM and Clariant are deploying these integrated configurations at commercial scale in Iowa and Romania, collapsing the capital cost gap between first and second-generation ethanol that has stalled cellulosic deployment for fifteen years. The technology is consolidating project finance around integrated technology licensors rather than engineering-procurement-construction consortia.
The EPA's Renewable Fuel Standard is tightening lifecycle carbon accounting through updated GREET model methodology, disqualifying ethanol pathways with high indirect land-use change scores from generating compliance credits. Fuel blenders in California and Oregon are responding by sourcing exclusively from certified low-carbon intensity facilities, creating a two-tier market where documentation quality determines price realization more than chemical specification.
Long-term offtake contracting is displacing spot market purchases among fuel blenders seeking supply security under blending mandate acceleration. Major oil companies in Brazil and the United States are locking in five to ten year supply agreements with specific carbon intensity ceilings, transferring price risk to processors while securing volume certainty. This pattern is most visible in São Paulo state, where Raízen and Copersucar have converted majority of output to contracted rather than merchant sales.
Ethyl Alcohol (Ethanol) Market Segmentation
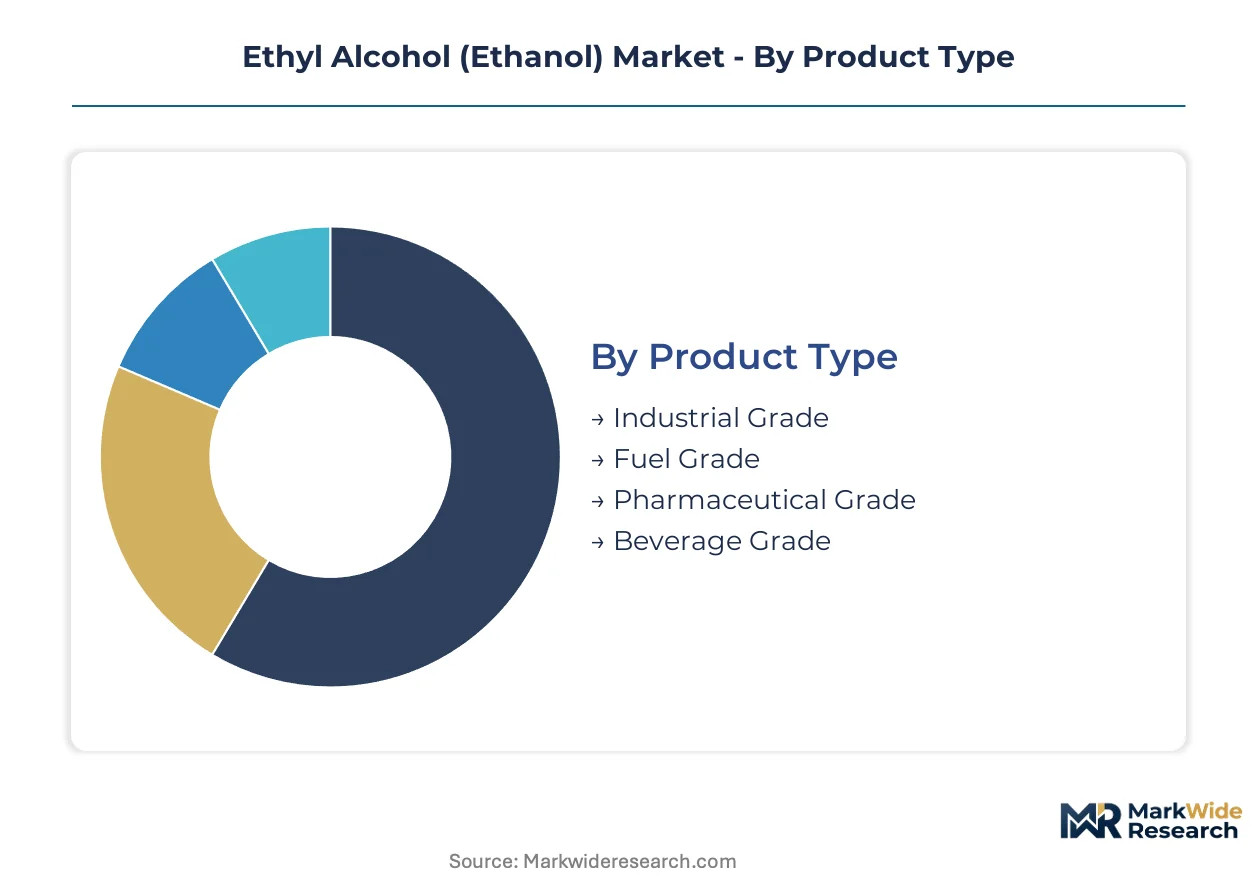
Ethanol procurement decisions pivot on purity specifications and regulatory compliance thresholds that vary sharply across fuel blending, pharmaceutical formulation, and industrial solvent applications. Buyers in each segment evaluate entirely different certification requirements, supply chain reliability metrics, and carbon intensity documentation standards.
Product Type:
Cost tier determines buyer access to certification tiers and end-use eligibility, with purity premiums separating commodity fuel markets from pharmaceutical-grade supply streams.
- Fuel Grade:Contains 92-95% ethanol with denaturants added to prevent human consumption, meeting ASTM D4806 specifications for gasoline blending. Demand concentrates among US fuel blenders in Iowa and Illinois under EPA Renewable Fuel Standard mandates, where corn-based supply chains face margin compression from carbon intensity accounting.
- Pharmaceutical Grade:Meets USP and EP monograph standards with 99.5%+ purity and strict impurity limits for vaccine and injectable drug formulation. Demand tightens around parenteral manufacturing clusters in New Jersey and North Carolina, driven by FDA validation requirements for excipient traceability.
- Industrial Grade:Serves chemical synthesis and solvent extraction with variable purity 95-99% depending on moisture tolerance.
- Beverage Grade:Complies with TTB and FDA food additive regulations for spirits production, requiring organoleptic neutrality and heavy metal testing.
Fuel grade leads on scale; pharmaceutical grade leads on momentum.
End User:
Application maturity shapes procurement contract structures, with established automotive blenders favoring long-term offtake while pharmaceutical buyers demand batch-specific documentation.
- Automotive:Fuel blenders at integrated oil companies and independent terminals purchase ethanol as an oxygenate to meet Clean Air Act reformulated gasoline requirements. Procurement concentrates along Gulf Coast and Midwest pipeline corridors, with EPA Renewable Fuel Standard volume obligations forcing continuous sourcing regardless of price swings.
- Pharmaceuticals:Drug manufacturers source USP-grade ethanol for tablet coating, extraction processes, and parenteral formulation. Demand clusters around FDA-registered facilities in Puerto Rico and Massachusetts, where validation protocols require locked supply chains with documented change control.
- Chemical Industry:Solvent users in coatings and adhesives production prioritize cost efficiency over certification tiers.
- Food and Beverage:Distillers and flavor extractors require TTB-permitted ethanol with documented grain or sugarcane provenance.
Automotive absorbs the highest volumes; pharmaceuticals command the steepest expansion trajectory.
Application:
Functional performance requirements split procurement between combustion optimization, microbial kill rates, and solvency power metrics.
- Fuel Additive:Ethanol raises gasoline octane ratings while reducing carbon monoxide emissions through oxygenation. Blenders in Brazil's São Paulo state and the US Corn Belt optimize for Reid Vapor Pressure compatibility, with ANP and EPA specifications diverging on allowable volatility limits.
- Disinfectant:Hospital and consumer antiseptic formulations require 60-95% ethanol concentration for effective pathogen inactivation. FDA and EPA registration as a healthcare disinfectant drives demand toward dedicated pharmaceutical-grade supply streams with batch sterility assurance.
- Solvent:Industrial extraction and coating applications exploit ethanol's polar-nonpolar hybrid solvency for resins and active pharmaceutical ingredients.
- Preservative:Food and cosmetic applications leverage ethanol's antimicrobial properties at lower concentrations than disinfectant use.
Fuel additive dominates volume throughput; disinfectant applications are climbing the fastest.
Distribution Channel:
Supply chain control preferences separate large-volume terminal operators from specialty chemical buyers needing technical service support.
- Direct Sales:Major fuel blenders and pharmaceutical manufacturers contract directly with ethanol producers for dedicated tanker or railcar delivery. Raízen and POET maintain direct relationships with Brazilian ANP-regulated distributors and US terminal operators, bypassing intermediary markup on multi-million gallon annual offtake.
- Distributors:Regional chemical distributors stock industrial and beverage grades for small-batch customers lacking storage infrastructure. Midwest ethanol cooperatives rely on distributor networks to reach craft distillers and specialty chemical formulators without dedicated logistics teams.
- Wholesale:Bulk terminal operators aggregate fuel-grade supply for spot market sales to independent blenders.
- Online Retail:Laboratory and small-scale industrial buyers purchase reagent-grade ethanol through B2B platforms with certificate of analysis downloads.
Direct sales capture the largest contract values; distributor channels are gaining share fastest among mid-scale industrial accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's sugarcane ethanol infrastructure outpaces India's emerging distillery network in scale, yet both countries now channel state capital toward blending mandate acceleration. The United States maintains the largest fuel-grade capacity base, while European processors navigate carbon accounting constraints.
United States
Corn Belt processors supply the bulk of EPA Renewable Fuel Standard compliance volumes, with Iowa and Illinois hosting the densest concentration of dry-mill facilities. The EPA's updated GREET model methodology now disqualifies high indirect land-use change pathways from generating credits. POET operates integrated grain-to-ethanol networks across the Midwest, leveraging rail terminal access to reach Gulf Coast blenders.
Brazil
São Paulo state anchors national production through sugarcane mills with attached distillery operations, serving both domestic hydrous ethanol demand and anhydrous blending requirements. ANP enforces RenovaBio carbon intensity benchmarks that reward bagasse cogeneration with premium biofuel credits. Raízen and Copersucar have converted majority output to long-term contracted sales rather than merchant spot markets.
India
Molasses-based distilleries in Maharashtra and Uttar Pradesh expand capacity to meet the 20% ethanol blending target by 2025, with grain-based units emerging in Punjab and Haryana. The central government's ethanol procurement program fixes purchase prices for oil marketing companies. Domestic processors with access to distillery modernization capital capture import substitution opportunities previously served by Brazilian and US suppliers.
Germany
Industrial ethanol processors in North Rhine-Westphalia and Bavaria serve chemical synthesis and pharmaceutical formulation demand, with REACH registration requirements constraining import competition. ECHA compliance infrastructure demands multi-year toxicological dossier preparation that favors established domestic producers. The country's national biofuel regulator enforces greenhouse gas reduction thresholds for transport fuel blending that privilege waste-based pathways over crop-derived ethanol.
China
Coal-to-ethanol demonstration plants in Shaanxi and Inner Mongolia supplement fermentation capacity for industrial solvent applications, though fuel-grade expansion remains constrained by grain security policies. The Ministry of Industry and Information Technology regulates ethanol gasoline pilot programs in select provinces. State-owned energy groups control downstream blending infrastructure, limiting independent processor market access.
Ethyl Alcohol (Ethanol) Market Competitive Landscape
US producers anchor the scale-driven tier; Brazilian specialists hold carbon-intensity advantages through sugarcane process economics. Market structure consolidates around integrated grain processors with captive feedstock supply, while smaller cooperatives face margin compression from regulatory compliance costs. Three archetypes dominate: agricultural conglomerates with ethanol divisions, dedicated biofuel platforms with downstream retail integration, and oil majors with renewable fuel mandates. Competitive moves center on backward integration into grain origination and fermentation CO2 capture for 45Q tax credit monetization.
Within the integrated agricultural processor tier, Archer Daniels Midland and Cargill exemplify diversified feedstock sourcing strategies that span multiple purity grades and geographic markets. POET, LLC occupies a position as a dedicated biofuel platform with concentrated Midwest capacity. These three entities represent the dominant competitive anchors, with Archer Daniels Midland and Cargill leveraging global distribution infrastructure for industrial and beverage grade supply, while POET sustains volume leadership in fuel-grade markets through direct terminal relationships.
| Leading Market Players |
|---|
| Green Plains Inc. |
| Koch Industries |
| POET, LLC |
| Cargill |
| The Andersons Inc. |
| Valero Energy Corporation |
| Raízen |
| Flint Hills Resources |
| Archer Daniels Midland |
| Others |
Supply & Pricing Matrix
Captive feedstock integration across the US Corn Belt and Brazil's São Paulo state anchors both supply security and pricing power for first-generation ethanol processors. POET and Raízen leverage in-house grain origination and sugarcane milling to buffer margin compression from EPA Renewable Fuel Standard compliance costs and ANP carbon intensity benchmarks.
Pricing Analysis
Capacity additions in Iowa and Illinois are reshaping price floors for fuel-grade ethanol as corn processors expand dry-mill output ahead of blending mandate acceleration. Contract-based long-term offtake dominates procurement, with carbon intensity documentation and USP certification tier separating pharmaceutical-grade premiums from commodity fuel markets. Pricing pressure intensifies in fuel-grade segments as cellulosic ethanol pathways compete for advanced biofuel credits. Fuel blenders exhibit highest price sensitivity due to mandate-driven volume obligations, while pharmaceutical manufacturers accept steep premiums for locked supply chains with batch traceability.
Supply Chain Analysis
Direct-to-blender channels handle hyperscale fuel-grade demand, with dedicated railcar and pipeline delivery bypassing intermediary terminals for multi-million gallon annual offtake. Supply concentrates in the United States, Brazil, and India, with corn, sugarcane, and molasses anchoring regional feedstock dependencies. Fermentation CO2 capture equipment and advanced yeast strains constitute critical input categories where supply bottlenecks constrain continuous processing upgrades. Single-source vulnerability runs through Midwest grain origination networks exposed to drought-induced yield volatility. Distribution runs through integrated oil company terminals and ANP-regulated Brazilian distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in carbon intensity reduction technologies and pharmaceutical-grade certification tiers, where process efficiency investments unlock premium pricing power beyond commodity fuel markets.
For Market Incumbents: Hedge feedstock exposure through geographic diversification into Brazilian sugarcane or Indian molasses supply bases, insulating against Chicago corn futures volatility. Prioritize fermentation CO2 capture infrastructure to monetize 45Q tax credits and qualify for sustainable aviation fuel feedstock premiums. Cellulosic ethanol substitution threatens first-generation corn ethanol eligibility under evolving EPA methodology. For New Entrants and Emerging Players: Specialty chemical buyers seeking USP-grade ethanol with dedicated technical service support represent an underserved archetype bypassed by volume-focused fuel processors. Target pharmaceutical formulation clusters in New Jersey and North Carolina with batch-specific documentation capabilities and locked supply chain validation. Deploy distributor partnerships to reach mid-scale industrial accounts lacking dedicated logistics teams. For Investors and Strategic Acquirers: Roll-up economics work for regional ethanol cooperatives with stranded fermentation assets because regulatory compliance costs are compressing smaller players unable to match compensation premiums for continuous fermentation expertise. Five-to-ten year viability hinges on carbon capture retrofit completion and RenovaBio credit generation capacity. Monitor EPA GREET model methodology updates as the inflection signal determining pathway eligibility for premium biofuel markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Origination | Captive corn and sugarcane supply locks in margin control against futures volatility. |
| Carbon Capture and Storage Deployment | 45Q tax credit monetization transforms fermentation plants into negative-emission assets. |
| Pharmaceutical-Grade Certification Investment | USP and EP compliance opens dedicated supply streams bypassing commodity fuel markets. |
| Continuous Fermentation Technology Upgrade | Process efficiency gains extract more ethanol per bushel without physical capacity expansion. |
| Long-Term Offtake Contracting | Five-to-ten year agreements with carbon intensity ceilings transfer price risk to processors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fuel blender procurement officers, pharmaceutical excipient managers, ethanol plant operations directors, and ANP regulatory specialists with secondary validation. Trade data from USITC and ANP, EPA Renewable Fuel Standard compliance reports, and ECHA REACH registration databases anchored supply-side quantification. Bottom-up capacity modeling and top-down mandate-driven demand triangulation cross-checked volume estimates.
Comparable-period anchoring tied projection assumptions to historical blending mandate implementation trajectories and carbon intensity accounting evolution. Segmentation modeling spanned purity grade tiers, end-use industries, distribution channel structures, and regional regulatory frameworks. CAGRs derived from elasticity-adjusted demand curves incorporating feedstock price volatility bands and policy acceleration scenarios. RenovaBio credit pricing and 45Q tax credit monetization timelines informed margin trajectory assumptions.
Inputs from EPA, ANP, and ECHA regulatory filings were available through the study window; gaps in cellulosic ethanol commercial deployment data introduce uncertainty bands around second-generation pathway penetration rates. Forecasts reflect documented assumptions regarding mandate enforcement stringency and carbon accounting methodology stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
North America Beer Market
Alcoholic Beverages
Asia-Pacific Wine Market
Alcoholic Beverages
White Wine Market
Alcoholic Beverages
Organic Wine Market
Alcoholic Beverages
North America Soju Market
Alcoholic Beverages
Industrial Alcohol Market
Alcoholic Beverages
Japanese Whisky Market
Alcoholic Beverages
Premium Spirit Market
Alcoholic Beverages
Beer Bottle Market
Alcoholic Beverages
Tequila Market
Alcoholic Beverages
Gluten-Free Beer Market
Alcoholic Beverages
Germany Tequila Market
Alcoholic Beverages
South America Fermented Drinks Market
Alcoholic Beverages
Microbrewery Supplies Market
Alcoholic Beverages
Asia-Pacific Spirits Market
Alcoholic Beverages
Turkey Tequila Market