
 Pressurized Wine Filter System Market | 2026-2036
Pressurized Wine Filter System Market Size, Share, and Industry Trends Forecast 2026-2036
Pressurized Wine Filter System Market Analytics
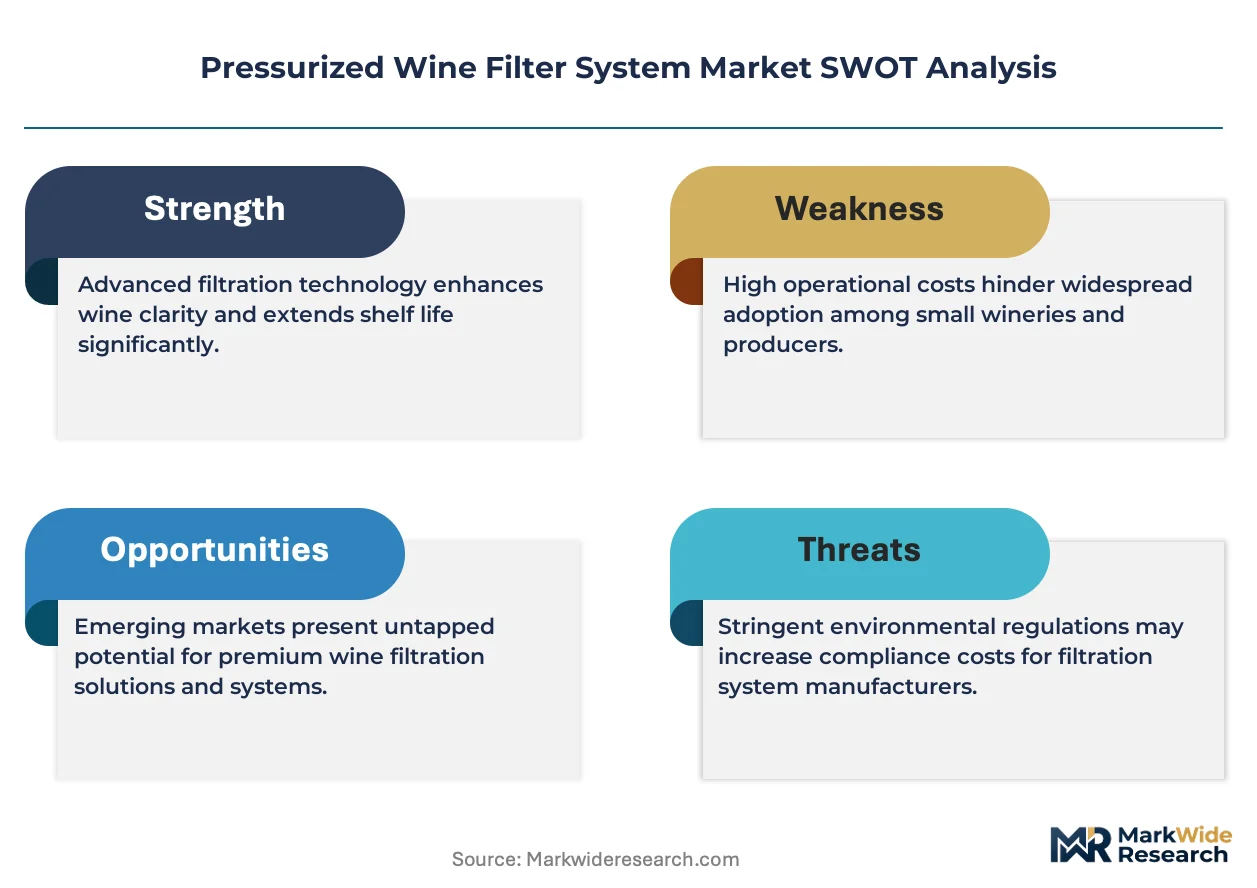
Preventive maintenance contracts and remote monitoring subscriptions is shifting how filter OEMs capture lifetime value from winery clients. Pall Corporation leverages its installed base of hollow-fiber membrane systems to anchor long-term service revenue across Napa Valley operations. Alfa Laval competes through integrated clean-in-place modules that reduce downtime between harvest batches. GEA Group extends its position with IoT-enabled pressure-differential sensors that predict cartridge replacement cycles.
A pressurized wine filter system employs enclosed housings with pump-driven flow to force must or finished wine through porous media at controlled differential pressures, typically operating between one and six bar to achieve sterile filtration without oxidation exposure. Membrane filters and cross-flow filtration technology lead commercial deployments where winemakers require microbiological stability prior to bottling, while depth filters retain share in cost-sensitive bulk wine processing. Cartridge formats dominate retrofit installations across smaller wineries with limited floor space, whereas plate filter configurations sustain demand in high-volume cooperative cellars.
FDA food-contact material regulations and EU REACH compliance on polymeric membrane substrates shape product development cycles for equipment sold into North American and European winery supply chains. California's CalRecycle packaging waste directives and Australia's FSANZ beverage standards further constrain material selection for filter housings and disposable elements. Stakeholders must monitor evolving PFAS restrictions in membrane chemistry and energy efficiency benchmarks for pump-driven systems as sustainability criteria penetrate procurement specifications.
Market Dynamics
Cross-flow membrane technology is compressing filtration cycle times while sterile bottling mandates from Australia's FSANZ and California's CalRecycle reshape equipment specifications across premium wine regions.
Growth Catalysts
- EU REACH compliance on polymeric substrates:Equipment manufacturers redesigning membrane chemistries for European export markets capture first-mover certification advantages.
- Automated filtration skids:Boutique wineries across Oregon and Sonoma Valley deploy these systems to reduce harvest-season labor dependencies.
- Barossa Valley estate bottlers:Australian producers prioritizing sterile bottling line integration drive demand for pressurized housings with integrated clean-in-place modules.
Market Restraints
- PFAS restrictions in membrane chemistry:Evolving EPA and state-level prohibitions on per- and polyfluoroalkyl substances constrain material selection for North American equipment sales.
- Pump energy intensity:Energy efficiency benchmarks for pressure-differential systems add capex burden to winery procurement decisions.
- Diatomaceous earth substitution:Traditional depth filtration retains cost advantage in bulk wine processing segments resistant to membrane upgrade cycles.
Strategic Opportunities
- California Central Coast AVA:Cooperative cellars with high-volume plate filter configurations present retrofit opportunities for IoT-enabled pressure monitoring.
- Remote monitoring subscriptions:Filter OEMs anchor lifetime value through predictive cartridge replacement algorithms.
- India's FSSAI beverage standards:Emerging wine production regions adopt pressurized systems to meet export-grade microbiological stability requirements.
Industry Challenges
- Cross-flow membrane integration:Wineries with legacy diatomaceous earth infrastructure face downtime and retraining costs during technology transitions.
- Clean-in-place validation:FDA food-contact material regulations require documented sanitation protocols that extend commissioning timelines for new installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressurized Wine Filter System Market |
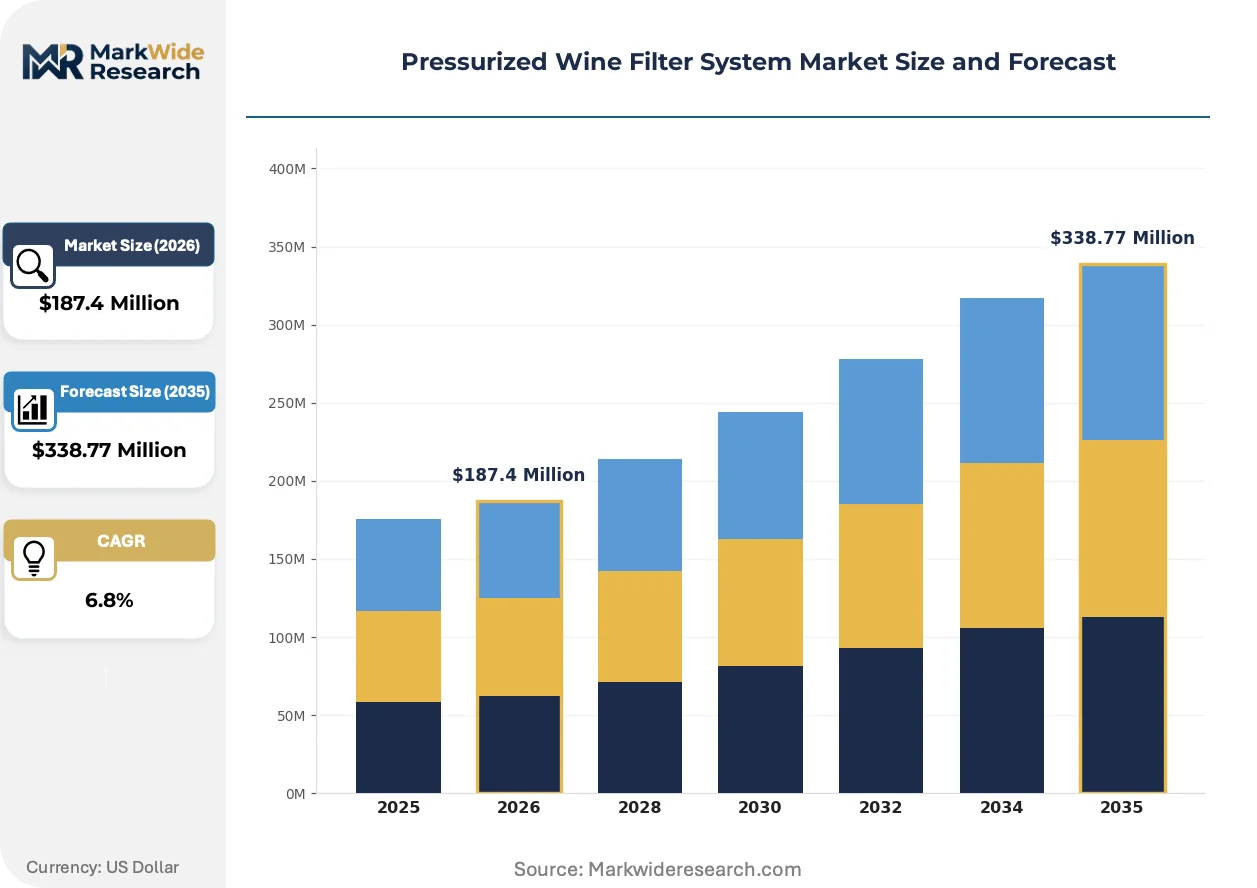
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filters, Cartridge Filters, Depth Filters, Plate Filters Technology: Cross-Flow Filtration, Vacuum Filtration, Gravity Filtration, Ultrafiltration End User: Wineries, Breweries, Food and Beverage Industries, Research Laboratories Application: Clarification, Stabilization, Sterilization, Wine Filtration |
| Companies Covered | Parker Hannifin Corporation, Alfa Laval, Pall Corporation, VA Filtration USA, GEA Group, Sartorius AG, 3M Company, Krones AG, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressurized Wine Filter System Market Evolving Landscape
Equipment manufacturers and winery operators are converging on predictive maintenance architectures and membrane material innovations that reduce oxidation exposure while compressing filtration throughput times.
Ceramic membrane elements with asymmetric pore structures deliver microbiological stability at lower differential pressures than polymeric alternatives. Premium red wine producers in Napa Valley and Bordeaux are adopting these elements for sterile pre-bottling filtration. Ceramic technology is expanding into mid-tier winery segments previously constrained by polymeric cartridge replacement economics.
Australia's FSANZ beverage standards and California's CalRecycle packaging waste directives are mandating filter housing materials with verified recyclability and reduced disposable element mass. Equipment vendors must certify polypropylene and stainless-steel configurations against these frameworks to maintain supply chain access. European REACH restrictions on phthalate plasticizers further constrain gasket and seal material selection for export-bound systems.
After-sales service unbundling is fragmenting traditional equipment procurement. Winery operators in Australia's Barossa Valley and California's Central Coast AVA separately contract membrane replacement logistics, pressure-differential sensor calibration, and clean-in-place chemical supply. Third-party service aggregators capture margin previously retained by original equipment manufacturers through bundled maintenance agreements.
Pressurized Wine Filter System Market Segmentation
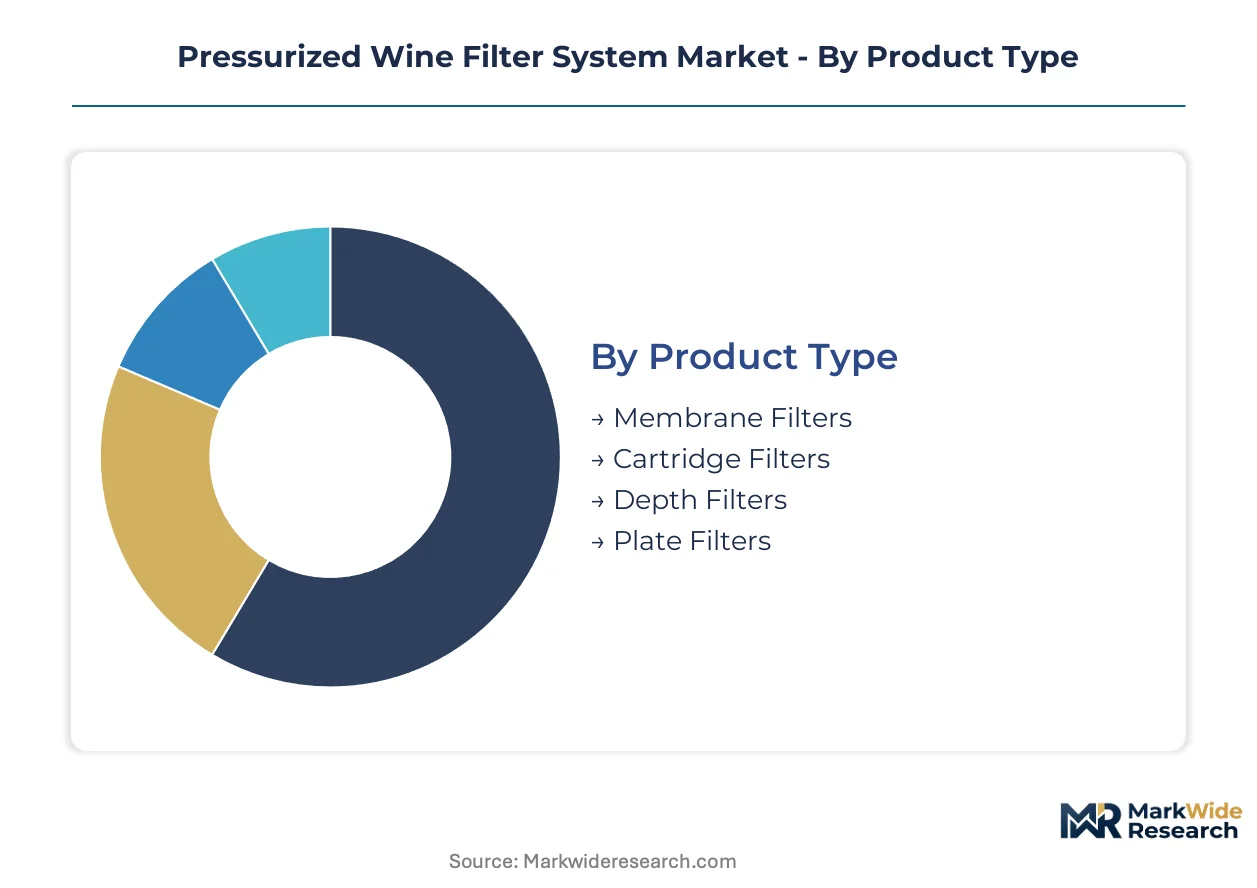
Pressurized wine filter systems serve divergent operational scales—from boutique estate bottlers to cooperative cellars—creating distinct equipment specifications across product formats and technology platforms. Understanding how capital deployment, throughput requirements, and regulatory compliance intersect across segments clarifies procurement patterns and vendor positioning strategies.
Product Type:
Capital intensity varies sharply across housing configurations, with plate filter installations demanding the highest upfront investment in stainless-steel infrastructure and automated clean-in-place modules.
- Membrane Filters:Polymeric or ceramic porous barriers rated for sterile filtration at controlled differential pressures. Napa Valley and Bordeaux premium red producers prioritize these systems for microbiological stability prior to bottling, driven by FSANZ and FDA food-contact mandates.
- Cartridge Filters:Disposable pleated elements in polypropylene or cellulose ester configurations suited for retrofit installations. Oregon's Willamette Valley boutique wineries favor cartridge formats where floor space constraints limit plate filter deployment.
- Depth Filters:Diatomaceous earth or perlite-based media retain cost advantage in bulk wine processing segments resistant to membrane upgrade cycles. California Central Coast cooperative cellars maintain these systems for high-volume harvest throughput.
- Plate Filters:Multi-sheet stainless-steel housings engineered for sterile bottling line integration. Barossa Valley estate bottlers specify plate configurations with integrated pressure-differential monitoring.
Most installed capacity flows through membrane filter deployments. Expansion is steepest in cartridge filter retrofits across smaller winery operations.
Technology:
Operational throughput and oxidation control differentiate technology selections, with cross-flow systems commanding premium pricing for reduced pump energy intensity and compressed cycle times.
- Cross-Flow Filtration:Tangential flow dynamics minimize membrane fouling through continuous shear at the filtration surface. Australia's Barossa Valley producers adopt these systems to reduce labor dependencies during harvest season.
- Vacuum Filtration:Negative pressure-driven flow through open filtration assemblies. Research laboratories and small-batch experimental wineries specify vacuum configurations for flexibility across must types.
- Gravity Filtration:Hydrostatic head-driven flow without pump energy input. Cost-sensitive bulk processors retain gravity systems where sterile bottling is not mandated.
- Ultrafiltration:Molecular weight cut-off membranes for protein and colloid removal prior to final filtration. Premium white wine producers in Sonoma Valley deploy ultrafiltration for heat stability assurance.
Cross-flow filtration dominates new capacity additions. Ultrafiltration is gaining share fastest among premium white wine specialists.
End User:
Procurement sophistication and service contract attachment rates vary by end-user category, with wineries exhibiting the highest lifetime value potential for predictive maintenance subscriptions.
- Wineries:Estate bottlers and cooperative cellars across California, Oregon, and Australia's premium regions. These operators prioritize sterile bottling line integration and IoT-enabled pressure monitoring.
- Breweries:Craft and industrial beer producers adapting wine filtration technology for haze stability and microbiological control. Equipment specifications emphasize clean-in-place validation protocols.
- Food and Beverage Industries:Juice, cider, and spirits processors requiring cross-functional filtration platforms. Procurement decisions center on multi-product flexibility and regulatory compliance breadth.
- Research Laboratories:Academic and commercial enology facilities conducting sensory and stability trials. Demand concentrates in bench-scale cartridge and vacuum configurations.
Wineries account for the dominant share of installed base. Food and beverage industries represent the fastest-expanding customer category.
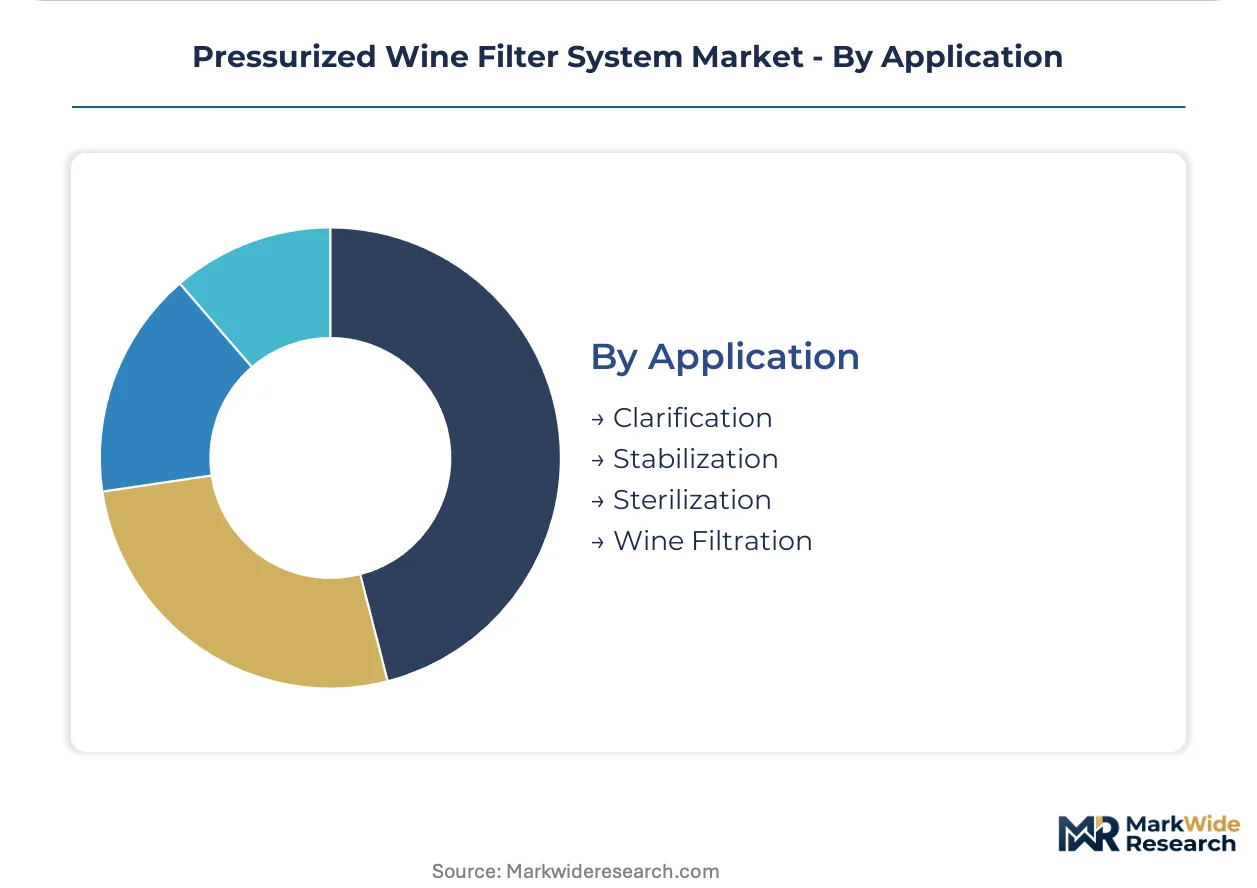
Application:
Filtration objectives determine equipment specification intensity, with sterilization applications demanding the most rigorous validation documentation and housing material certifications.
- Clarification:Removal of suspended solids and colloidal haze prior to final processing. Bulk wine operations specify depth filter configurations for cost-efficient solids reduction.
- Stabilization:Protein and tartrate precipitation prevention through selective filtration. Premium producers combine ultrafiltration with cross-flow membrane technology for heat and cold stability.
- Sterilization:Microbiological elimination at 0.45-micron absolute ratings for bottling line protection. FDA and EU REACH compliance on polymeric substrates shapes equipment selection for export-bound wineries.
- Wine Filtration:General-purpose must and finished wine processing encompassing multiple objectives. Multi-stage configurations integrate depth, membrane, and sterile filtration in sequence.
Sterilization applications command the highest equipment specification intensity. Stabilization is expanding most quickly as premium producers prioritize export-grade microbiological standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between jurisdictions with divergent compliance costs is redirecting equipment procurement toward markets with streamlined certification pathways. California's layered environmental mandates and Australia's stringent beverage standards create cost-of-compliance premiums that boutique producers seek to mitigate through technology selection.
United States
Boutique wineries across Oregon and Sonoma Valley are expanding automated filtration skid deployment to compress harvest-season labor dependencies. FDA food-contact material regulations constrain polymeric membrane substrate selection for equipment sold into domestic supply chains. Napa Valley operations anchor service revenue capture for hollow-fiber membrane system vendors through long-term preventive maintenance contracts.
Australia
Barossa Valley estate bottlers prioritize sterile bottling line integration with pressurized housings featuring clean-in-place modules. FSANZ beverage standards mandate filter housing materials with verified recyclability and reduced disposable element mass. South Australian wine regions concentrate cross-flow membrane adoption where producers seek microbiological stability for export-grade production.
Germany
EU REACH compliance on polymeric substrates and phthalate plasticizer restrictions shape gasket and seal material selection for filtration equipment. Baden-Württemberg and Rhineland-Palatinate wine cooperatives specify plate filter configurations with integrated pressure-differential monitoring for high-volume harvest throughput. German equipment fabricators leverage CE marking advantages to anchor European export positioning.
France
Bordeaux premium red wine producers adopt ceramic membrane elements with asymmetric pore structures for sterile pre-bottling filtration at lower differential pressures. ANSM and CNIL frameworks intersect with EU REACH to constrain material validation protocols for polymeric filtration media. Champagne and Burgundy clusters drive demand for ultrafiltration systems targeting protein and colloid removal prior to final processing.
Italy
Tuscan and Piedmont estate bottlers combine cross-flow membrane technology with stabilization filtration for heat and cold stability assurance in premium export wines. ECHA compliance requirements extend product development cycles for membrane chemistry redesigns targeting European markets. Northern Italian cooperative cellars present retrofit opportunities for IoT-enabled pressure monitoring across legacy plate filter installations.
Pressurized Wine Filter System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated filtration skid providers capturing premium positioning while component fabricators serve cost-sensitive retrofit demand. Market structure tilts toward consolidation among hollow-fiber membrane system vendors with established installed bases, though mid-tier cartridge specialists retain fragmentation in boutique winery procurement. Two strategic archetypes dominate: full-system integrators bundling hardware with predictive maintenance subscriptions, and component specialists unbundling membrane logistics from equipment sales. Competitive moves concentrate on M&A to secure clean-in-place module capabilities and strategic partnerships anchoring IoT-enabled sensor calibration networks.
Among diversified industrial technology conglomerates, Parker Hannifin Corporation and Eaton Corporation exemplify the full-system integrator archetype through their motion and filtration control portfolios. Pall Corporation and Sartorius AG occupy positions within the membrane technology specialist tier, with Pall leveraging its installed base across premium wine regions to anchor long-term service revenue. GEA Group sits within the European process equipment fabricator cluster, competing through integrated clean-in-place modules that reduce downtime between harvest batches. Alfa Laval represents the Nordic industrial engineering archetype with heat transfer and separation technology cross-application into wine processing workflows.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Alfa Laval |
| Pall Corporation |
| VA Filtration USA |
| GEA Group |
| Sartorius AG |
| 3M Company |
| Krones AG |
| Eaton Corporation |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up filtration specialists concentrate manufacturing scale across Germany and Italy, anchoring supply discipline while subscription bundling of membrane replacement services compresses transactional pricing for unbundled cartridge sales.
Pricing Analysis
Capacity additions in South Australia and California's Central Coast AVA are reshaping price floors for plate filter configurations, forcing incumbent vendors toward three-tier pricing structure across premium, standard, and economy levels. Ceramic membrane elements command quality-grade premiums against polymeric alternatives, while FDA food-contact certification tiers separate export-bound equipment from domestic-only configurations. Price erosion runs through cartridge retrofit segments as third-party service aggregators capture membrane logistics margin previously retained by OEMs. Cooperative cellars exhibit highest price sensitivity; estate bottlers with sterile bottling mandates show least.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Melbourne, and Napa Valley anchor hub-and-spoke patterns for filter housing and membrane element fulfillment. Manufacturing concentrates in Germany, Italy, and the United States for precision stainless-steel fabrication; polymeric membrane substrates draw from specialized chemical producers in Japan and the United States. Ceramic element supply rests on limited sintering capacity creating single-source vulnerability for asymmetric pore structures. Distribution runs through OEM-direct channels for integrated skids and aftermarket distributors for cartridge replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FSANZ beverage standards and California CalRecycle packaging directives continuously upgrade equipment replacement cycles, embedding demand visibility into compliance-driven procurement timelines.
For Market Incumbents: Deploy predictive maintenance algorithms to anchor lifetime value capture against third-party service aggregators eroding membrane replacement margins. Deepen backward integration into ceramic element sintering to secure asymmetric pore structure supply against Japanese capacity constraints. Cross-flow membrane substitution for diatomaceous earth infrastructure presents replacement revenue headwinds requiring defensive certification investments.
For New Entrants and Emerging Players: Regional distributors with established winery relationships offer lowest-friction channel access for cartridge retrofit specialists targeting Oregon's Willamette Valley floor-space-constrained boutiques. India's emerging wine production regions under FSSAI export-grade standards represent most penetrable geography. Clean-in-place module unbundling from integrated skid sales creates white-space for component specialists.
For Investors and Strategic Acquirers: Valuations sit cheapest among hollow-fiber membrane system vendors with installed base service revenue lagging predictive maintenance penetration. Five-to-ten-year viability favors OEMs consolidating clean-in-place capabilities through acquisition over pure hardware fabricators. Watch PFAS restriction enforcement velocity as inflection indicator for membrane chemistry redesign capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-in-Place Module Integration | Reduces harvest-season downtime between batches for Barossa Valley estate bottlers. |
| Ceramic Membrane Capacity Expansion | Secures asymmetric pore structure supply for Napa Valley premium red producers. |
| IoT Sensor Calibration Networks | Enables predictive cartridge replacement across California Central Coast cooperative cellars. |
| REACH Compliance Certification | Unlocks European export positioning for polymeric substrate equipment vendors. |
| Third-Party Service Aggregation | Captures membrane logistics margin from traditional OEM bundled maintenance agreements. |
Research Methodology
Direct dialogue with filtration equipment plant managers, winery operations directors, aftermarket service heads, and membrane chemistry R&D directors grounded qualitative findings in operational reality. Secondary validation drew from FDA food-contact material filings, ECHA REACH substance registrations, FSANZ beverage standard updates, and customs trade data for filtration equipment imports. Bottom-up winery procurement surveys triangulated against top-down equipment vendor revenue assessments.
Segment-level outputs across membrane, cartridge, depth, and plate filter configurations combined with cross-flow, ultrafiltration, and vacuum technology platforms to anchor volume and value estimates. End-user segmentation spanning wineries, breweries, and food and beverage processors intersected with clarification, stabilization, sterilization, and general wine filtration applications. CAGRs derived from equipment replacement cycle analysis and regulatory compliance upgrade frequencies across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PFAS chemistry prohibitions, ceramic element supply expansion, and harvest volume volatility in premium wine regions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Edible Alcohol Market
Alcoholic Beverages
GCC Beer Market
Alcoholic Beverages
Alcoholic Drinks Market
Alcoholic Beverages
Wine Enzymes Market
Alcoholic Beverages
Premixed Cocktail Shots Market
Alcoholic Beverages
RTD Bottled Cocktails Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
Portable Keg System Market
Alcoholic Beverages
Tea Beer Market
Alcoholic Beverages
South America Beer Market
Alcoholic Beverages
Malaysia Alcohol E-Commerce Market
Alcoholic Beverages
Global Premium Alcoholic Beverage Market
Alcoholic Beverages
Pub Cellar Equipment Market
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
Australia and New Zealand Tequila Market