
 North America Construction Equipment Rental Market | 2026-2036
North America Construction Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
North America Construction Equipment Rental Market Insights
Buyer concentration among large infrastructure developers and national contractors is repositioning fleet procurement toward long-term rental partnerships with tier-one providers. United Rentals, Inc. leverages its branch density and digital fleet management platform to sustain national coverage. Sunbelt Rentals anchors its position through specialized industrial equipment and energy-sector expertise. Herc Rentals Inc. differentiates via crane and aerial lift specialization serving contractor verticals.
Construction equipment rental denotes the temporary provision of heavy machinery—excavators, bulldozers, cranes, and scaffolding—to end users under contractual terms specifying hourly, daily, or monthly rates, with fleet units typically maintained to manufacturer duty-cycle specifications and emissions compliance standards. The primary commercial purpose transfers capital burden from ownership to operational expenditure while ensuring access to current-technology equipment. Excavators and bulldozers dominate product type revenue due to universal earthmoving demand across residential and commercial applications. Crane rentals command premium rate structures reflecting specialized operator requirements and infrastructure project scale. Short-term rental services exhibit the fastest structural expansion, driven by project-specific contractor needs and inventory flexibility preferences.
EPA Tier 4 Final emissions standards and OSHA worksite safety regulations shape fleet investment cycles, compelling rental providers to retire non-compliant diesel units and adopt telematics-linked maintenance protocols. The Federal Highway Administration's infrastructure funding disbursements direct regional equipment deployment patterns across state transportation departments. Stakeholders must monitor regulatory phase-in timelines and funding authorization continuity to align fleet composition with compliance deadlines and project pipeline visibility.
Market Dynamics
EPA Tier 4 Final emissions mandates and OSHA worksite safety protocols are forcing rental providers to accelerate fleet turnover cycles, converting capital-intensive ownership burdens into operational expenditures for contractors while concentrating procurement power among tier-one fleet operators with compliance-ready inventories.
Growth Catalysts
- Federal Highway Administration disbursements:Infrastructure funding authorizations direct state transportation department spending toward bridge and highway rehabilitation, expanding equipment deployment windows across the Texas-California corridor.
- Telematics-enabled predictive maintenance:Sensor-integrated fleet management platforms reduce unplanned downtime for excavators and bulldozers, improving asset utilization rates for rental providers serving metropolitan construction clusters.
- Energy sector infrastructure cycles:Utility-scale renewable installations and pipeline maintenance programs in the Permian Basin and Alberta oil sands generate recurring demand for specialized crane and aerial lift rentals.
Market Restraints
- Steel and hydraulic component cost volatility:Input price fluctuations for chassis fabrication and precision hydraulics compress margin stability for fleet operators managing multi-year depreciation schedules.
- Regional fleet concentration risk:Equipment availability imbalances between Texas-California demand centers and Midwest agricultural markets create repositioning inefficiencies during seasonal demand troughs.
- Diesel-electric substitution timelines:Battery-powered earthmoving equipment remains capacity-constrained for heavy-load continuous-duty applications, limiting compliance pathway options for rental providers.
Strategic Opportunities
- Canadian provincial infrastructure pipelines:Ontario and Quebec transportation modernization programs represent underpenetrated demand relative to US saturation levels, offering first-mover positioning for cross-border fleet operators.
- Modular micro-rental hubs:Urban infill construction and utility repair contractors in Los Angeles and Houston metropolitan zones favor distributed pickup locations over centralized branch networks.
- Inflation Reduction Act clean equipment incentives:Tax credit structures for low-emission machinery acquisitions accelerate rental provider investment in compliant fleet segments ahead of EPA phase-in deadlines.
Industry Challenges
- Certified crane operator scarcity:NCCCO credentialing bottlenecks and demographic retirement waves constrain specialized lifting capacity deployment for infrastructure scale projects.
- Telematics-legacy fleet integration:Retrofitting older diesel units with emissions monitoring and remote diagnostics systems creates hardware-software compatibility failures and warranty voidance risks.
- Cross-border regulatory misalignment:Divergent Canadian provincial and US state equipment transport permitting creates administrative friction for fleet operators serving integrated North American project portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Construction Equipment Rental Market |
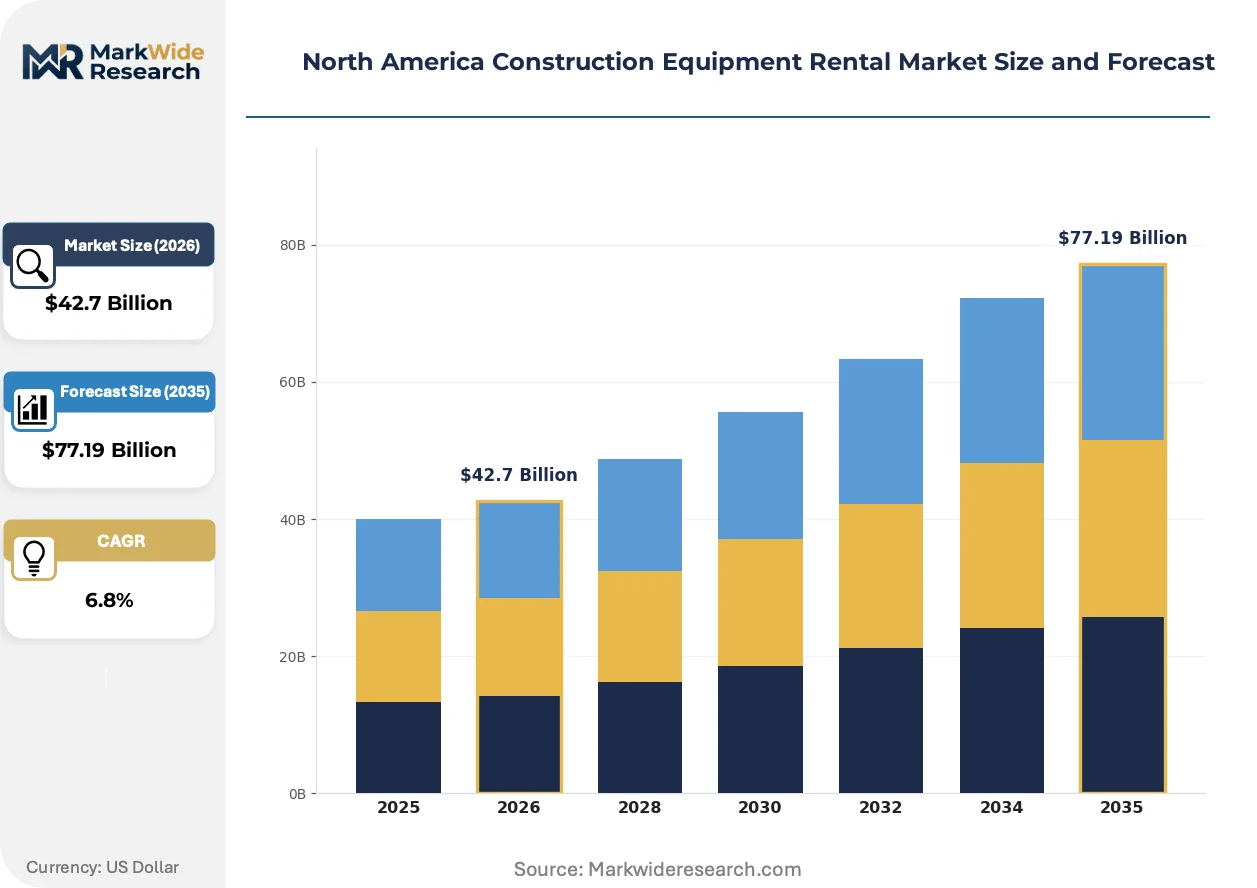
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $77.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Cranes, Scaffolding End User: Contractors, Construction Firms, Infrastructure Developers, Events Organizers Application: Residential, Commercial, Industrial, Infrastructure Service Type: Short-Term Rental, Long-Term Rental, Maintenance Services, Delivery Services |
| Companies Covered | United Rentals, Inc., Sunbelt Rentals, Herc Rentals Inc., H&E Equipment Services, Inc., Ahern Rentals, Caterpillar Inc., Deere & Company, Finning International Inc., Maxim Crane Works, L.P., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Construction Equipment Rental Market Trends and Innovations
Digital fleet management platforms and emissions-compliant powertrains are restructuring how rental providers deploy, maintain, and monetize construction equipment assets across fragmented contractor demand bases.
Telematics-integrated hydraulic systems are absorbing diagnostic and prognostic functions previously performed by field technicians. Mid-size contractors in Texas and California metropolitan zones are adopting sensor-enabled excavators at accelerated refresh rates. Equipment downtime compression is absorbing maintenance cost premiums into standard rental rate structures, flattening total cost of ownership comparisons against owned fleets.
OSHA silica exposure standards and EPA non-road diesel rules are tightening worksite equipment specifications. Rental providers must retire pre-Tier 4 Final units or face exclusion from federally funded infrastructure projects. Bridge and highway contractors in the US Southeast are responding by specifying compliant fleet requirements in procurement solicitations, shifting vendor qualification criteria toward emissions documentation rather than hourly rate alone.
Project-based rental procurement is displacing annual master service agreements among regional contractors. Equipment sourcing decisions now cluster around specific job timelines rather than consolidated fleet relationships, fragmenting volume commitments across multiple providers. This pattern concentrates most visibly in California residential development and Texas energy infrastructure verticals, where contractor liquidity preferences favor pay-as-deployed models over capital lock-in.
North America Construction Equipment Rental Market Segmentation
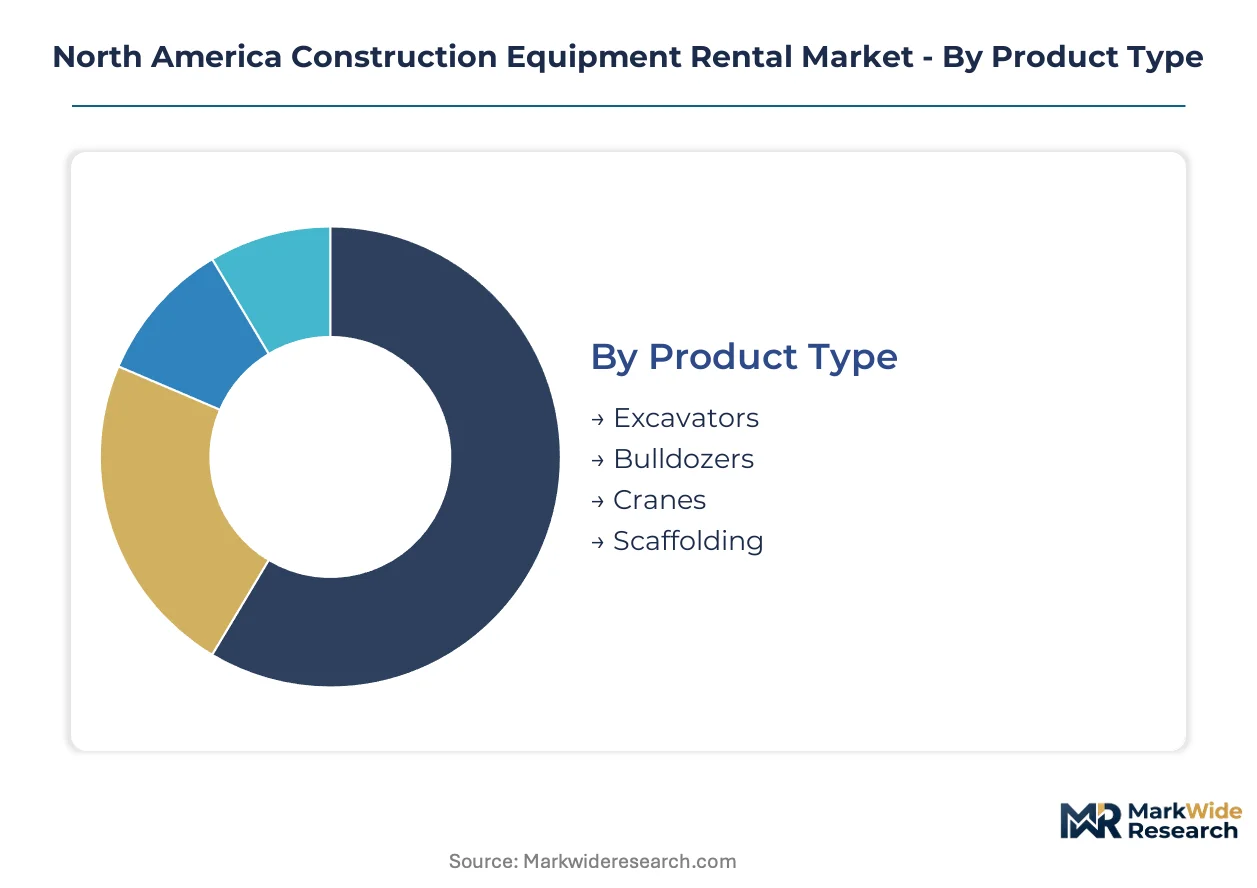
Segmentation in construction equipment rental exposes how contractor procurement priorities diverge across project scale, duration, and regulatory exposure. Fleet operators configure inventory depth and service bundling around these fault lines to capture volume without sacrificing utilization rates.
Product Type:
Contractor selection hinges on earthmoving intensity versus specialized lifting requirements, with fuel costs and operator certification thresholds driving rental-versus-own calculations.
- Excavators:Hydraulic track and wheel-mounted units dominate metropolitan trenching and foundation work. Demand clusters in Texas-California residential development corridors where EPA Tier 4 Final compliance filters out aging owned fleets.
- Bulldozers:Crawler and wheeled dozers handle grading and site preparation at scale. Infrastructure developers across the US Southeast specify compliant units for Federal Highway Administration-funded bridge rehabilitation, converting capital expenditure to operational outlays.
- Cranes:Mobile and tower configurations serve vertical construction and energy infrastructure. NCCCO-certified operator scarcity constrains deployment velocity for wind turbine installation in the Permian Basin.
- Scaffolding:Frame and system scaffolding support elevated work platforms. OSHA silica exposure mandates accelerate rental preference over contractor-owned inventory requiring compliance retrofit.
Excavators lead on scale; short-term rental uptake for bulldozers leads on momentum.
End User:
Procurement authority concentrates differently across organizational types, with credit capacity and project pipeline visibility determining rental term flexibility.
- Contractors:Specialty trades—electrical, mechanical, excavation—rent for job-specific equipment matching without balance sheet encumbrance. California residential contractors favor pay-as-deployed models over annual master agreements.
- Construction Firms:General contractors with multi-year backlogs negotiate fleet partnerships blending short-term surge capacity with long-term rate locks. Texas energy sector construction drives crane and aerial lift concentration.
- Infrastructure Developers:Public-private partnership sponsors require emissions documentation and telematics integration for federal funding eligibility. Bridge and highway portfolios in Ontario and Quebec generate cross-border equipment sourcing.
- Events Organizers:Temporary structure erection and staging deploys scaffolding and light lifting equipment on compressed timelines. Seasonal demand in Los Angeles and Houston metropolitan zones favors modular micro-hub proximity over branch density.
Infrastructure developers lead on scale; events organizers lead on momentum.
Application:
Project type dictates equipment specification intensity, with regulatory scrutiny and safety liability shaping rental-versus-own economics.
- Residential:Single-family and multifamily construction consumes compact excavators and mini-excavators for foundation and utility trenching. Zoning density in California metro markets drives equipment sharing across adjacent job sites.
- Commercial:Office, retail, and hospitality verticals require crane reach and scaffolding systems for envelope construction. Developer liquidity constraints in post-pandemic office markets extend rental terms over purchase.
- Industrial:Manufacturing and warehouse construction demands heavy-load earthmoving and precision grading. Alberta oil sands maintenance programs generate recurring demand for specialized crawler configurations.
- Infrastructure:Transportation, utility, and energy projects command the largest equipment footprints and longest deployment windows. Federal funding authorization timelines create demand volatility requiring rental flexibility.
Infrastructure leads on scale; residential leads on momentum.
Service Type:
Contractor cash flow management and project certainty determine service bundling preferences, with unplanned downtime costs pushing toward integrated offerings.
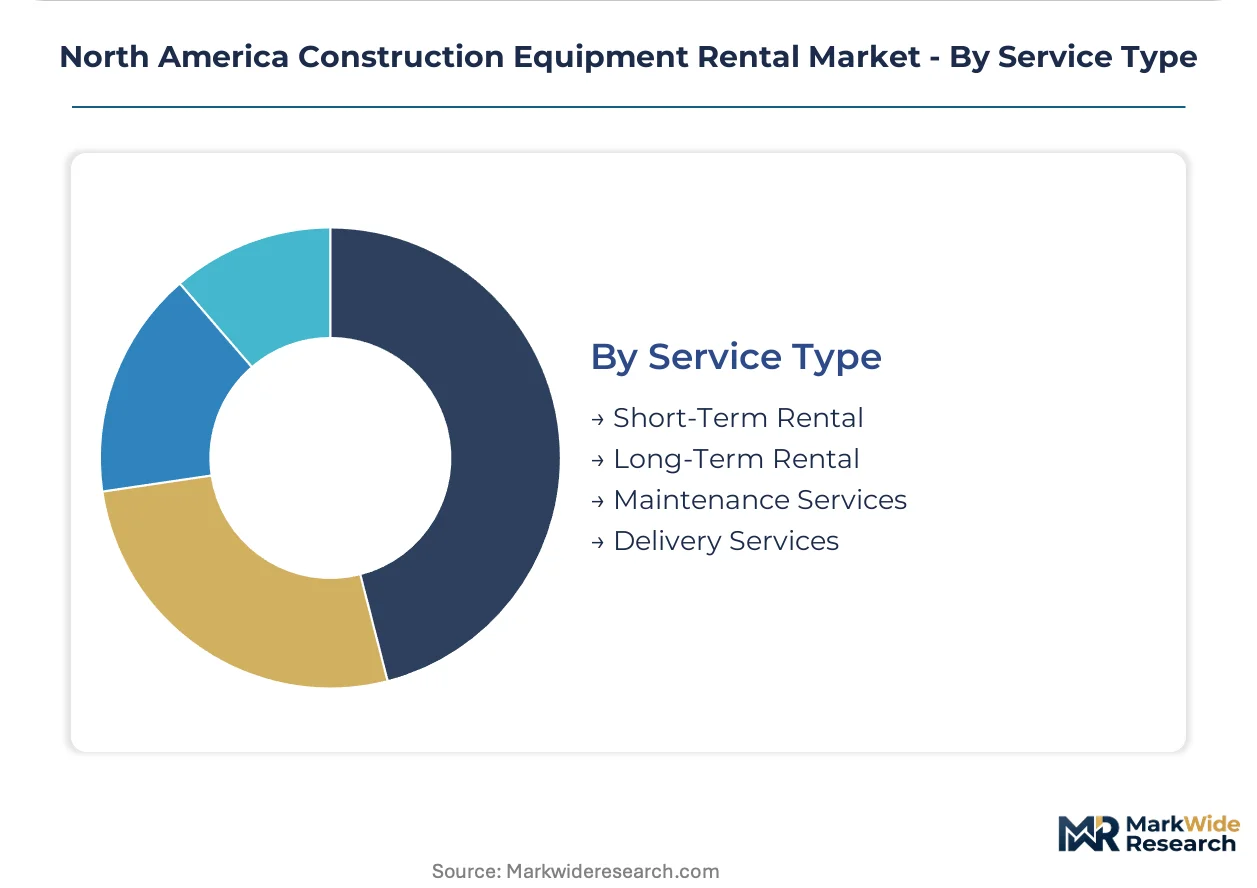
- Short-Term Rental:Daily and weekly terms serve project-specific surges and emergency replacement needs. Fragmenting procurement across multiple providers concentrates in California and Texas verticals.
- Long-Term Rental:Multi-month and annual agreements with maintenance inclusion convert capital burdens to predictable operational expenditures. National contractors leverage volume for rate concessions and fleet priority access.
- Maintenance Services:Predictive maintenance subscriptions using telematics-linked diagnostics reduce unplanned downtime for hydraulic systems. Service bundling absorbs cost premiums into standard rate structures.
- Delivery Services:Transport and logistics coordination addresses regional fleet concentration imbalances between demand centers and seasonal trough markets. Repositioning efficiency determines provider selection for dispersed project portfolios.
Long-term rental leads on scale; short-term rental leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States absorbs substantially higher rental equipment volumes than Canada, though Canadian provincial infrastructure programs are narrowing the per-capita gap through accelerated transportation modernization spending.
United States
The Texas-California corridor generates the densest equipment deployment, driven by metropolitan construction volume overlapping with Permian Basin energy infrastructure needs. EPA Tier 4 Final emissions standards filter aging diesel fleets from federally funded bridge and highway projects. Houston and Los Angeles metropolitan zones favor modular micro-rental hubs for utility repair and urban infill contractors.
Canada
Ontario and Quebec transportation modernization programs represent underpenetrated demand relative to US saturation levels, attracting cross-border fleet operators seeking first-mover positioning. Health Canada and provincial regulators enforce emissions documentation requirements aligned with EPA standards for integrated North American project portfolios. Alberta oil sands maintenance programs generate recurring demand for specialized crawler configurations in Calgary-Edmonton industrial clusters.
Mexico
Northern border states concentrate equipment demand from maquiladora manufacturing expansion and cross-border logistics infrastructure. Mexican federal transportation programs and state-level permitting frameworks create administrative friction for US-based fleet operators. Monterrey and Tijuana industrial corridors absorb short-term rental surges from automotive and electronics manufacturing construction cycles.
North America Construction Equipment Rental Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. Tier-one national operators leverage branch density and digital fleet management platforms to sustain coverage across fragmented contractor demand bases. Mid-size regional specialists anchor positions through energy-sector expertise or crane and aerial lift specialization. Competitive moves concentrate on strategic partnerships for telematics integration and geographic expansion into underpenetrated provincial markets.
Within the national-scale tier, United Rentals, Inc. and Sunbelt Rentals occupy positions defined by branch network density and digital platform deployment. Herc Rentals Inc. exemplifies specialization-focused positioning through crane and aerial lift concentration serving contractor verticals with certified operator networks.
| Leading Market Players |
|---|
| United Rentals, Inc. |
| Sunbelt Rentals |
| Herc Rentals Inc. |
| H&E Equipment Services, Inc. |
| Ahern Rentals |
| Caterpillar Inc. |
| Deere & Company |
| Finning International Inc. |
| Maxim Crane Works, L.P. |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up fleet specialists anchor supply concentration across the Texas-California corridor, converting fragmented regional yards into national platforms with rate-setting power over contractors seeking EPA-compliant earthmoving equipment. Their financing structures reward utilization discipline, pressuring mid-tier operators to match maintenance-included rate bundles or cede share to tier-one branch networks.
Pricing Analysis
Capacity additions in Texas and California are reshaping price floors for excavator and bulldozer rentals as tier-one operators absorb telematics costs into standard rate structures. Three-tier pricing separates premium telematics-integrated units from standard compliant fleets and economy-grade legacy equipment nearing retirement. Price differentiation rests on EPA Tier 4 Final certification status and bundled predictive maintenance subscriptions. Pricing pressure stems from steel and hydraulic component cost volatility compressing margins on multi-year depreciation schedules. Specialty contractors in the energy sector show least price sensitivity, while residential developers in California metro markets negotiate aggressively on short-term surge capacity.
Supply Chain Analysis
Chassis fabrication and precision hydraulic systems rest on integrated supply networks spanning the United States, Japan, and Germany for Tier 4 Final engine components and sensor-integrated control systems. Raw material dependencies include high-strength steel plate, precision-machined hydraulic valves, and emissions after-treatment modules. Supply chain risk centers on single-source vulnerability for proprietary telematics hardware from dominant industrial IoT providers. Distribution runs through company-owned branch networks with third-party logistics partnerships for rapid repositioning between seasonal demand troughs in Midwest agricultural markets and peak infrastructure deployment windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily through infrastructure funding authorization continuity, with Federal Highway Administration disbursements creating predictable equipment deployment windows across state transportation departments.
For Market Incumbents: Acquire certified crane operator training programs to lock in scarce NCCCO-credentialed labor pools before demographic retirement waves constrain specialized lifting capacity. Consolidate regional scaffolding specialists to capture OSHA silica compliance-driven rental conversion from contractor-owned inventory. Battery-electric earthmoving prototypes from emerging equipment manufacturers threaten first-mover positioning if tier-one fleets delay pilot deployments. For New Entrants and Emerging Players: Begin with modular micro-rental hubs in Los Angeles and Houston metropolitan zones, where urban infill contractors favor distributed pickup proximity over centralized branch density. Target Ontario and Quebec transportation modernization programs as underpenetrated demand relative to US saturation levels, offering cross-border fleet positioning ahead of established operators. Anchor go-to-market strategy through telematics-enabled predictive maintenance subscriptions that compress downtime costs into competitive rate positioning. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-size regional specialists with energy-sector crane concentration and underutilized telematics platforms ripe for national rollup integration. Long-term viability frames around decade-long infrastructure replacement cycles and EPA compliance phase-in deadlines that force fleet turnover regardless of macroeconomic conditions. Watch Inflation Reduction Act clean equipment incentive disbursement velocity as inflection signal for rental provider capital allocation toward low-emission fleet segments.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Sensor-linked diagnostics from OEMs like Caterpillar and Deere compress unplanned downtime into competitive rate structures. |
| Crane Operator Certification Network | NCCCO-credentialed labor pools differentiate specialized lifting providers serving Permian Basin wind installations. |
| Cross-Border Fleet Expansion | Ontario and Quebec infrastructure pipelines attract first-mover positioning from US-based tier-one operators. |
| Predictive Maintenance Subscription | Telematics-linked service bundles absorb cost premiums into standard rental rates for hydraulic system coverage. |
| Modular Micro-Hub Deployment | Urban infill contractors in Houston and Los Angeles favor distributed pickup locations over branch density. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market combining structured interviews with fleet operations directors, contractor procurement managers, infrastructure developer project controllers, and OEM aftermarket service heads. Secondary validation draws from EPA emissions compliance filings, Federal Highway Administration funding disbursement records, OSHA worksite safety enforcement data, and equipment registration databases. Bottom-up unit deployment estimates triangulate against top-down infrastructure spending projections.
Granularity-level modeling disaggregates volume and value across product type, end user, application, service type, and regional regulatory cluster throughout the forecast period. CAGRs derive from equipment replacement cycle analysis, EPA Tier 4 Final phase-in timelines, and infrastructure funding authorization continuity assumptions. Industry-specific forecast inputs include crane operator certification pipeline constraints and telematics adoption curves among mid-size contractors.
Several conditions sit outside the modeled scope, including unannounced federal infrastructure funding rescissions, rapid battery-electric equipment capacity breakthroughs, and cross-border trade policy disruptions affecting US-Canada equipment transport permitting. Forecasts reflect documented assumptions about regulatory phase-in adherence and funding authorization continuity. A small set of named triggers warrants ongoing watch: Inflation Reduction Act incentive disbursement velocity, NCCCO certification completion rates, and steel price volatility indices.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Self-Driving Dumpers Machine Market
Construction Equipment
Construction Equipment Tire Market
Construction Equipment
Friction Stir Welding Market
Construction Equipment
Rotary Dryers Market
Construction Equipment
Track Laying Equipment Market
Construction Equipment
Ceramic Tile Printing Machine Market
Construction Equipment
Yard Crane Market
Construction Equipment
Europe Multi Attachment Loaders Market
Construction Equipment
Autonomous Heavy Equipment Market
Construction Equipment
Welding and Cutting Equipment Market
Construction Equipment
Stud Welding Guns Market
Construction Equipment
Mini Cranes Market
Construction Equipment
Draw Heat Setting Winder Market
Construction Equipment
US Welding Consumables Market
Construction Equipment
Global Wheel Trenchers Market
Construction Equipment
Spray Washer Market