
 Global Buttock Augmentation Market | 2026-2036
Global Buttock Augmentation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Buttock Augmentation Market Foresight
Medical distributor networks across Latin America and Southeast Asia are reshaping how implant manufacturers reach board-certified plastic surgeons. AbbVie (Allergan Aesthetics) leverages its direct-to-clinic platform in the United States to sustain premium positioning for its silicone implant portfolio. Sientra Inc. competes through specialized textured and smooth implant lines that dominate safety-focused surgeon preferences. Merz Pharma extends its reach via hyaluronic acid and poly-L-lactic acid filler portfolios that occupy the non-surgical segment.
Buttock augmentation encompasses surgical and non-surgical procedures designed to enhance gluteal volume, projection, and contour through implant insertion, autologous fat transfer, or injectable biocompatible fillers. Silicone implants typically employ cohesive gel formulations with textured or smooth shells manufactured through room-temperature vulcanization to achieve specific durometer and tear-resistance specifications. Fat grafting procedures lead volume in Brazil and Mexico where liposuction infrastructure supports combination body-contouring workflows, while injectable fillers represent the fastest-expanding margin pool in North American dermatology clinics seeking lower-commitment alternatives. Lift surgeries remain a mature, slower-growing category concentrated among revision specialists and post-massive-weight-loss patients.
The FDA's premarket approval requirements for silicone implants and the EU Medical Device Regulation's enhanced clinical evidence standards are elevating barriers for new entrants while consolidating demand around established manufacturers with robust post-market surveillance infrastructure. Brazil's ANVISA and South Korea's MFDS maintain parallel but distinct approval pathways that shape regional product availability and influence multinational registration sequencing. Stakeholders must monitor evolving regulatory divergence between jurisdictions to optimize portfolio allocation and anticipate where next-generation biocompatible materials will achieve commercial access first.
Market Dynamics
Social media-driven aesthetic consultation volume is compressing decision cycles and forcing clinics to reconfigure patient acquisition infrastructure around influencer-referral pathways rather than traditional physician networks.
Growth Catalysts
- EU Medical Device Regulation:Enhanced clinical evidence standards are consolidating demand around manufacturers with established post-market surveillance, accelerating premium product adoption.
- Fat grafting workflows:Combination liposuction infrastructure in Brazil and Mexico enables same-session body contouring, expanding addressable patient pools.
- Cross-border medical tourism:São Paulo's surgical density attracts Latin American patients seeking cost-competitive procedures with board-certified specialists.
Market Restraints
- Silicone raw material concentration:Cohesive gel formulation supply chains cluster in East Asian chemical manufacturing zones, creating input vulnerability.
- FDA premarket approval timelines:Extended PMA review periods for novel implant designs delay commercialization and tie up R&D capital.
- Autologous fat transfer limitations:Variable graft retention rates (30-70%) necessitate revision procedures, capping patient satisfaction benchmarks.
Strategic Opportunities
- Non-surgical segment white space:Hyaluronic acid and poly-L-lactic acid fillers in North American dermatology clinics capture patients averse to operative recovery.
- South Korea's MFDS pathway:Accelerated approval timelines for next-generation biocompatible materials enable earlier market access than FDA or EMA routes.
- Telemedicine pre-consultation channels:Virtual assessment platforms reduce geographic friction for international patient acquisition.
Industry Challenges
- Board-certified plastic surgeon scarcity:Specialized gluteal anatomy training programs remain limited, constraining safe procedure volume expansion.
- Post-market surveillance infrastructure:Long-term implant safety tracking demands costly registry maintenance that smaller manufacturers cannot sustain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Buttock Augmentation Market |
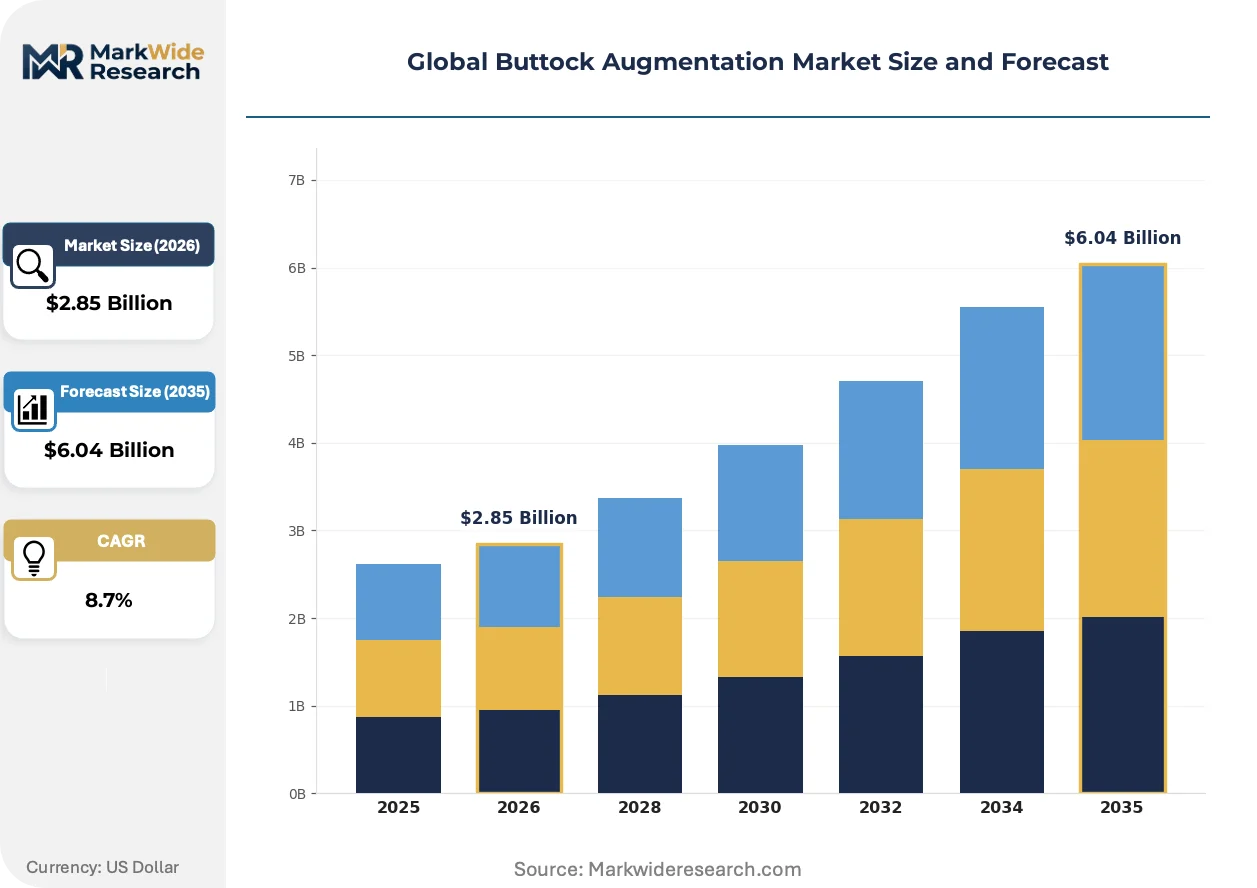
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $6.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Surgical Implants, Fat Grafting, Injectable Fillers, Combination Techniques, Lift Surgeries Material Used: Silicone Implants, Autologous Fat, Hyaluronic Acid, Poly-L-lactic Acid, Calcium Hydroxylapatite End User: Plastic Surgery Clinics, Cosmetic Surgery Centers, Dermatology Clinics, Medical Spas, Aesthetic Hospitals Sales Channel: Direct Sales, Medical Distributors, E-commerce Platforms, Specialized Retailers, Healthcare Providers |
| Companies Covered | Sientra Inc., Merz Pharma, AbbVie (Allergan Aesthetics), Silimed, Polytech Health & Aesthetics, GC Aesthetics, Implantech, Galderna, Sebbin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Buttock Augmentation Market Shifts & Advancements
Three-dimensional imaging and simulation software is displacing static consultation photography, enabling patients to visualize outcomes pre-operatively while forcing clinics to invest in rendering infrastructure.
Implant surface engineering is virtualizing traditional texturing methodologies. Micro-polyurethane and nano-patterned shells reduce capsular contracture incidence. Aesthetic hospitals in São Paulo and Seoul are adopting these surfaces fastest. The technology is virtualizing conventional smooth-shell procurement patterns among safety-focused surgeons.
ANVISA's 2023 updated silicone implant surveillance requirements are tightening adverse event reporting obligations. Brazilian manufacturers must now submit annual implant performance data. This policy shift advantages multinational firms with existing pharmacovigilance systems over domestic competitors lacking comparable infrastructure.
Patient acquisition through social media influencer partnerships is compressing traditional referral channel economics. Cosmetic surgery centers now allocate 25-40% of marketing spend to content creator collaborations. This channel shift concentrates in the United States and Brazil where platform penetration and aesthetic culture convergence are strongest.
Global Buttock Augmentation Market Segmentation
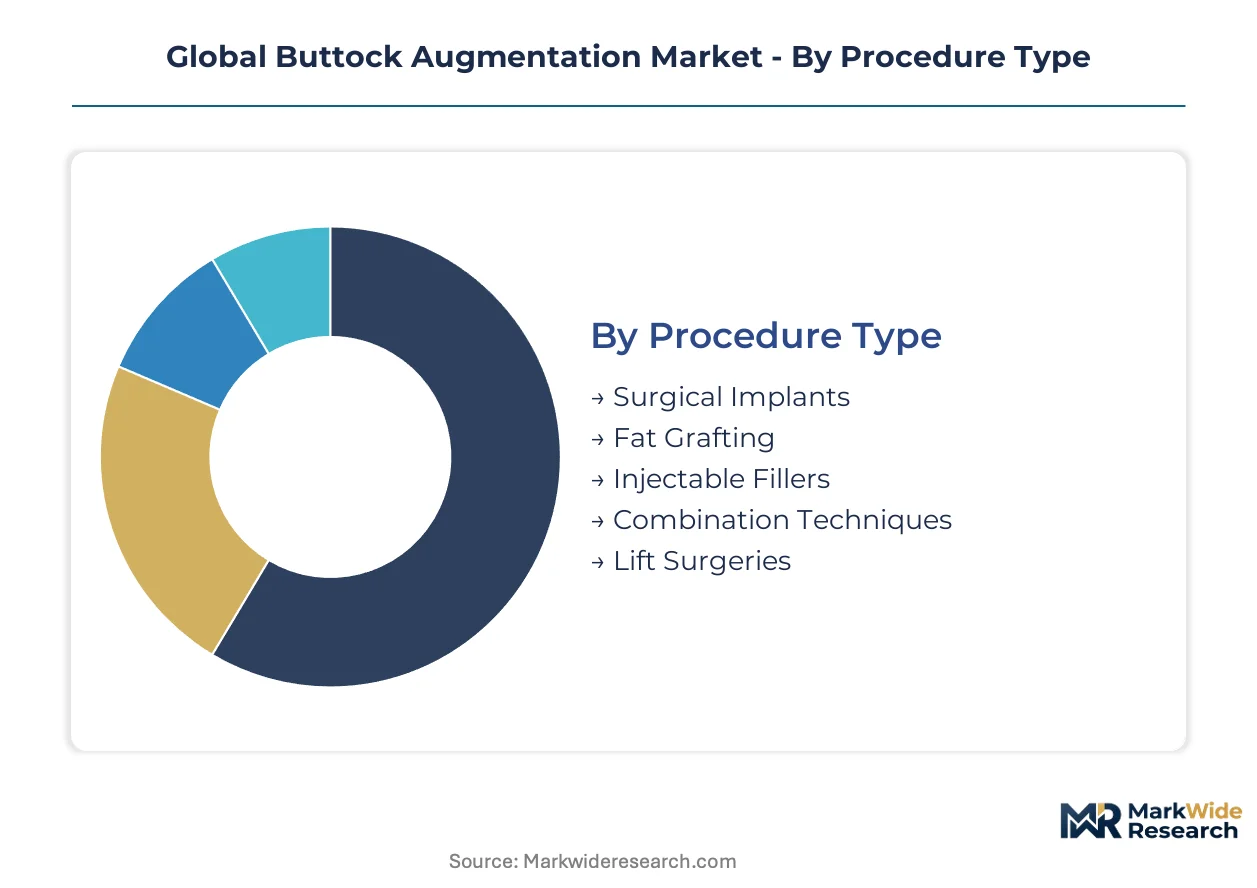
Procedure type determines capital intensity and patient throughput cycles. Material selection governs regulatory pathway complexity and margin structure. End-user configuration shapes geographic access patterns and pricing power.
Procedure Type:
Cycle times vary dramatically across modalities, with non-surgical options turning patients weekly while surgical implants require months from consultation to full recovery.
- Surgical Implants:Cohesive gel silicone devices with textured or smooth shells deliver permanent volume enhancement through submuscular or subfascial placement. São Paulo's aesthetic hospitals concentrate demand here, driven by cross-border medical tourism seeking board-certified surgical expertise at competitive price points.
- Fat Grafting:Autologous adipose tissue harvested via liposuction and purified for injection into gluteal planes. Brazilian and Mexican clinics dominate procedural volume, leveraging established liposuction infrastructure to enable same-session body contouring workflows that expand addressable patient pools.
- Injectable Fillers:Hyaluronic acid and biostimulatory compounds administered in outpatient settings with minimal downtime.
- Combination Techniques:Hybrid approaches integrating implant placement with fat grafting for customized contouring.
- Lift Surgeries:Excisional procedures addressing ptosis without volume addition, concentrated among post-massive-weight-loss patients.
Surgical implants dominate installed base. Injectable fillers are where expansion concentrates.
Material Used:
Cost tiers separate premium biocompatible formulations from commodity alternatives, with regulatory burden escalating alongside material sophistication.
- Silicone Implants:Room-temperature vulcanized shells with specific durometer and tear-resistance specifications manufactured through precision molding processes. FDA premarket approval requirements and EU MDR clinical evidence standards consolidate demand around established manufacturers with robust post-market surveillance infrastructure.
- Autologous Fat:Patient-derived tissue eliminating foreign body response risk while introducing graft retention variability between 30-70%.
- Hyaluronic Acid:Cross-linked gel formulations offering temporary enhancement with reversible outcomes, preferred by North American dermatology clinics.
- Poly-L-lactic Acid:Biostimulatory filler inducing collagenesis over multiple treatment sessions.
- Calcium Hydroxylapatite:Mineral-based microsphere suspension providing longer duration than hyaluronic acid alternatives.
Silicone implants anchor premium revenue. Hyaluronic acid formulations are climbing the fastest.
End User:
Customer type stratifies across surgical credential requirements, facility accreditation standards, and service line breadth.
- Plastic Surgery Clinics:Board-certified specialist practices performing the full spectrum of implant and grafting procedures. Brazil's São Paulo corridor concentrates global surgical density, attracting Latin American patients through competitive pricing and established specialist reputations.
- Cosmetic Surgery Centers:Multi-procedure facilities emphasizing aesthetic outcomes and patient experience infrastructure.
- Dermatology Clinics:Non-surgical filler administration dominating the fastest-expanding margin pool in North America as patients seek lower-commitment alternatives.
- Medical Spas:Medically supervised aesthetic services with varying physician oversight levels.
- Aesthetic Hospitals:Full-service surgical campuses with overnight recovery capabilities and emergency response protocols.
Plastic surgery clinics command procedural volume leadership. Dermatology clinics represent the steepest expansion trajectory.
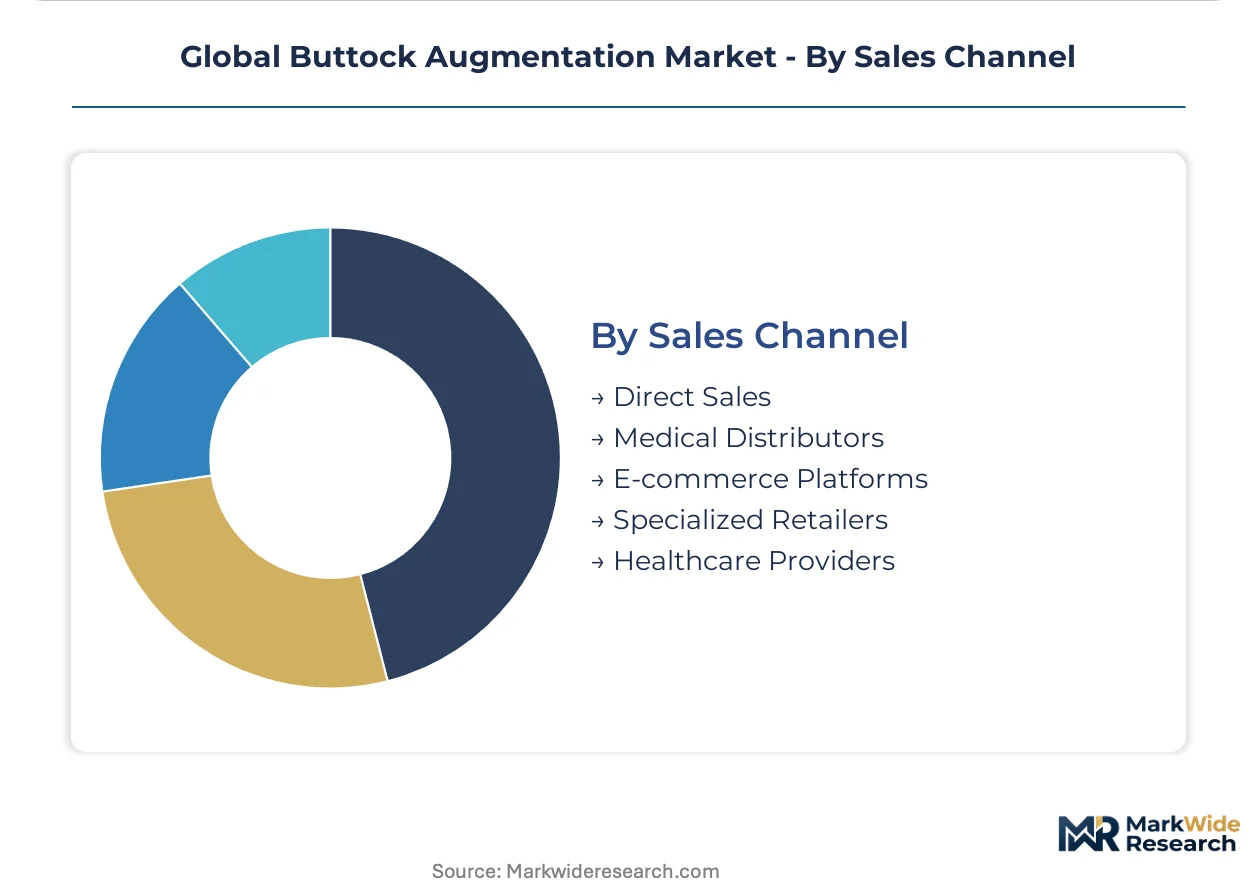
Sales Channel:
Supply concentration shapes channel economics, with direct relationships privileging volume purchasers and distributor networks extending geographic reach.
- Direct Sales:Manufacturer-to-clinic relationships enabling premium positioning and customized service agreements. AbbVie's direct-to-clinic platform in the United States sustains premium positioning for silicone implant portfolios through dedicated account management.
- Medical Distributors:Regional networks reshaping how implant manufacturers reach board-certified plastic surgeons across Latin America and Southeast Asia.
- E-commerce Platforms:Digital procurement channels gaining traction for consumables and non-implant products.
- Specialized Retailers:Focused aesthetic supply vendors serving independent practices.
- Healthcare Providers:Integrated health system procurement for hospital-based aesthetic services.
Medical distributors dominate installed base. Direct sales channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's São Paulo corridor commands pricing power through surgical density and cross-border medical tourism flows, while the United States sustains premium positioning through FDA-gated product access and direct-to-clinic distribution platforms.
United States
Social media-driven consultation volume compresses patient decision cycles, forcing cosmetic surgery centers to reconfigure acquisition infrastructure around influencer-referral pathways. FDA premarket approval requirements for silicone implants consolidate demand around established manufacturers with robust post-market surveillance infrastructure. Miami and Los Angeles concentrate procedural volume through high specialist density and celebrity culture amplification.
Brazil
ANVISA's 2023 updated silicone implant surveillance requirements tighten adverse event reporting obligations, advantaging multinational firms with existing pharmacovigilance systems. São Paulo's aesthetic hospitals attract Latin American patients seeking cost-competitive procedures with board-certified specialists. Same-session liposuction-to-fat-grafting workflows expand addressable patient pools beyond standalone augmentation demand.
South Korea
MFDS accelerated approval timelines for next-generation biocompatible materials enable earlier commercial access than FDA or EMA regulatory routes. Seoul's Gangnam district concentrates aesthetic hospital capacity with three-dimensional imaging infrastructure displacing static consultation photography. Micro-polyurethane and nano-patterned implant surfaces reduce capsular contracture incidence among safety-focused surgeons.
Mexico
Combination body-contouring workflows leverage established liposuction infrastructure to enable autologous fat grafting at price points competitive with Brazilian offerings. Tijuana and Mexico City attract North American patients seeking reduced procedural costs without trans-Atlantic travel. National pharmaceutical regulator oversight of implant safety parallels FDA frameworks but with compressed review timelines.
Germany
EU Medical Device Regulation enhanced clinical evidence standards elevate barriers for new entrants while consolidating demand around manufacturers with established post-market surveillance. Düsseldorf and Munich concentrate specialized plastic surgery practices serving Central European medical tourism flows. Polytech Health & Aesthetics anchors domestic manufacturing capacity for textured and smooth shell portfolios.
Global Buttock Augmentation Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material and surface engineering. The vendor base stratifies across three tiers: multinational conglomerates with direct-to-clinic distribution infrastructure, mid-cap specialists focused on implant surface innovation, and regional manufacturers serving price-sensitive markets through distributor networks. Strategic moves concentrate on M&A to capture complementary filler portfolios and geographic expansion through regulatory sequencing in South Korea and Brazil.
Within the multinational tier, AbbVie (Allergan Aesthetics) and Sientra Inc. exemplify divergent positioning strategies—AbbVie leveraging direct sales platforms in the United States, Sientra occupying specialized textured and smooth implant lines. Merz Pharma sits within the non-surgical segment through hyaluronic acid and poly-L-lactic acid filler portfolios. Among European manufacturers, Polytech Health & Aesthetics and Sebbin represent mid-cap specialists with concentrated implant engineering capabilities.
| Leading Market Players |
|---|
| Sientra Inc. |
| Merz Pharma |
| AbbVie (Allergan Aesthetics) |
| Silimed |
| Polytech Health & Aesthetics |
| GC Aesthetics |
| Implantech |
| Galderna |
| Sebbin |
| Others |
Supply & Pricing Matrix
São Paulo's surgical corridor anchors global pricing power through density-driven cost efficiency and cross-border patient flows from across Latin America. Brazil's ANVISA surveillance requirements and competitive specialist wages compress procedural costs relative to US benchmarks, while premium silicone implant tiers sustain margin separation through FDA-gated product access and direct-to-clinic distribution platforms.
Pricing Analysis
Customization-premium spreads separate configured-to-order surgical workflows from standardized filler administration across dermatology clinics. Three-tier pricing structure across premium, standard, and economy levels stratifies by implant surface engineering complexity and surgeon certification tier. Cost compression in the non-surgical segment intensifies as hyaluronic acid formulations commoditize, while plastic surgery clinics demonstrate lowest price sensitivity due to patient financing infrastructure and outcome-based value perception.
Supply Chain Analysis
Export-control regimes on medical-grade silicone polymers limit flows from East Asian chemical manufacturing zones to Western implant fabricators. Cohesive gel formulations, textured shell substrates, and biocompatible filler precursors draw from concentrated production in South Korea, Germany, and Japan. Single-source vulnerability in medical-grade silicone supply creates structural exposure to input disruption. Distribution runs through medical distributor networks across Latin America and direct-to-clinic platforms in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in post-pandemic aesthetic procedure recovery, with social media-driven consultation volume compressing patient decision cycles and accelerating capital deployment into influencer-referral infrastructure.
For Market Incumbents: Pre-empt regulatory consolidation by deepening pharmacovigilance infrastructure ahead of ANVISA's annual reporting mandates and EU MDR clinical evidence requirements. Secure backward integration into medical-grade silicone supply through captive partnerships with East Asian chemical manufacturers to mitigate raw material concentration risk. For New Entrants and Emerging Players: Pursue white-space expansion in North American dermatology clinics through hyaluronic acid and poly-L-lactic acid filler portfolios, where lower capital barriers and compressed approval timelines enable faster market access than surgical implant segments. Target telemedicine pre-consultation channels to reduce geographic friction for international patient acquisition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors surface-engineering specialists with micro-polyurethane and nano-patterned implant capabilities, as safety-focused surgeon preferences displace conventional smooth-shell procurement. Long-term viability hinges on post-market surveillance infrastructure scalability. Watch MFDS accelerated approval pathways as the signal for where next-generation biocompatible materials achieve commercial access first.| Strategic Initiative | Industry Significance |
|---|---|
| Surface Engineering Investment | Micro-polyurethane and nano-patterned shells reduce capsular contracture incidence among safety-focused surgeons. |
| Pharmacovigilance Infrastructure Buildout | Annual implant performance data submission to ANVISA advantages multinational firms over domestic competitors lacking comparable systems. |
| Telemedicine Platform Integration | Virtual assessment infrastructure reduces geographic friction for cross-border medical tourism patient acquisition. |
| Direct-to-Clinic Distribution Expansion | AbbVie's US platform demonstrates premium positioning sustainability through dedicated account management relationships. |
| Non-Surgical Filler Portfolio Diversification | Hyaluronic acid and poly-L-lactic acid formulations capture patients averse to operative recovery in North American dermatology clinics. |
Research Methodology
Initial hypotheses were tested against primary input from board-certified plastic surgeons, aesthetic hospital procurement directors, biomedical engineers, and medical distributor network managers and refined through secondary validation against FDA premarket approval filings, ANVISA regulatory databases, EU MDR technical documentation, and hospital procurement contract records. Bottom-up procedure volume estimates from clinic-level data were triangulated against top-down manufacturer shipment analytics.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled across procedure type, material sophistication tier, end-user facility accreditation level, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and replacement cycle dynamics, incorporating social media consultation velocity indices and cross-border patient flow patterns as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in discretionary healthcare spending sensitivity and medical tourism currency exchange dynamics would shift the trajectory. Material shifts in FDA premarket approval timeline compression or EU MDR enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Platysmaplasty Treatment Market
Aesthetic Medicine
Phototherapy Lamps and Units for Aesthetic Medicine Market
Aesthetic Medicine
Radio Frequency Beauty Equipment Market
Aesthetic Medicine
Chemical Peel Market
Aesthetic Medicine
Medical Aesthetic Dermal Filler Market
Aesthetic Medicine
Global Cellulite Treatment Market
Aesthetic Medicine
Aesthetic Laser Market
Aesthetic Medicine
Global Aesthetic Fillers Market
Aesthetic Medicine
Spa Market
Aesthetic Medicine
Global Aesthetic Threads Market
Aesthetic Medicine
Customized China Aesthetics Equipment Market
Aesthetic Medicine
Non-Surgical Fat Reduction Market
Aesthetic Medicine
Australia Facial Injectable Market
Aesthetic Medicine
Global Facial Fat Transfer Market
Aesthetic Medicine
Aesthetic Services Market
Aesthetic Medicine
Alexandrite Laser Treatment Market