
 Europe Dermal Fillers Market | 2026-2036
Europe Dermal Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dermal Fillers Market Foresight
Fragmentation among medical spa chains and independent aesthetic clinics is repositioning purchasing power across Europe's dermal filler supply chain. Galderma leverages its integrated dermatology portfolio to sustain shelf presence in high-volume clinic accounts. Merz Pharma anchors its position through specialized neuromodulator and filler combination protocols. Allergan Aesthetics (AbbVie) competes on brand strength and direct-to-practitioner training ecosystems.
Dermal fillers are injectable biocompatible substances, typically formulated as stabilized hyaluronic acid gels or synthetic collagen stimulators, designed to restore facial volume, smooth rhytides, and correct contour deficiencies through minimally invasive administration. The MDR mandates clinical evidence and notified body certification for Class III implantable devices, elevating barriers for new market entrants. Hyaluronic acid formulations dominate current volume flows due to reversibility with hyaluronidase and established safety profiles, while poly-L-lactic acid segments capture margin pools in collagen biostimulation protocols for mature patient cohorts. Fat-based applications remain niche, constrained by autologous harvesting complexity and operator-dependent outcomes.
EMA oversees centralized marketing authorization pathways for novel filler substances, while national competent authorities in Germany, France, and Italy enforce MDR compliance through post-market surveillance and vigilance reporting. The EU AI Act introduces transparency obligations for algorithmic diagnostic tools used in facial analysis and treatment planning software bundled with filler procedures. Stakeholders must monitor how notified body capacity constraints and evolving clinical evidence requirements reshape product registration timelines and competitive access.
Market Dynamics
The EU Medical Device Regulation reclassification of dermal fillers as Class III implantable devices is compressing product registration timelines and elevating clinical evidence requirements for all manufacturers seeking European market access.
Growth Catalysts
- MDR compliance infrastructure:Germany's notified bodies have expanded capacity for biological safety evaluations, accelerating conformity assessment for hyaluronic acid formulations with established equivalence pathways.
- Medical spa consolidation:France's aesthetic clinic chains are centralizing procurement through group purchasing organizations, creating volume commitments that stabilize manufacturer revenue forecasting.
- Hyaluronidase reversibility:The enzymatic dissolution capability of HA-based products reduces patient hesitation and malpractice exposure, driving first-time treatment rates in United Kingdom urban centers.
Market Restraints
- Notified body capacity bottlenecks:Only eleven EU-designated bodies currently handle Class III device certification, creating twelve-to-eighteen-month backlog queues for novel filler submissions.
- Raw material concentration:Pharmaceutical-grade hyaluronic acid fermentation depends on three European suppliers, exposing formulation costs to upstream bioreactor capacity constraints.
- Autologous fat transfer:Lipoharvesting techniques for facial volumization compete in mature patient segments, offering permanent correction without synthetic implant risks or recurring maintenance costs.
Strategic Opportunities
- Eastern European penetration:Poland and Czech Republic aesthetic markets remain undersupplied with premium filler portfolios, presenting first-mover advantages for MDR-certified portfolios.
- Combination protocol bundling:Collagen biostimulators paired with neuromodulators in single-visit treatments capture margin pools from time-constrained professional cohorts in metropolitan France.
- EU AI Act transparency:Algorithmic facial analysis tools for treatment planning face disclosure mandates, creating compliance service revenue streams for software-integrated device manufacturers.
Industry Challenges
- Injector certification scarcity:Advanced cannula techniques for vascular safety require supervised training hours that outpace qualified preceptor availability in high-volume markets.
- Post-market surveillance burden:MDR vigilance reporting obligations for serious incidents demand dedicated pharmacovigilance infrastructure that strains mid-tier manufacturer operating budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dermal Fillers Market |
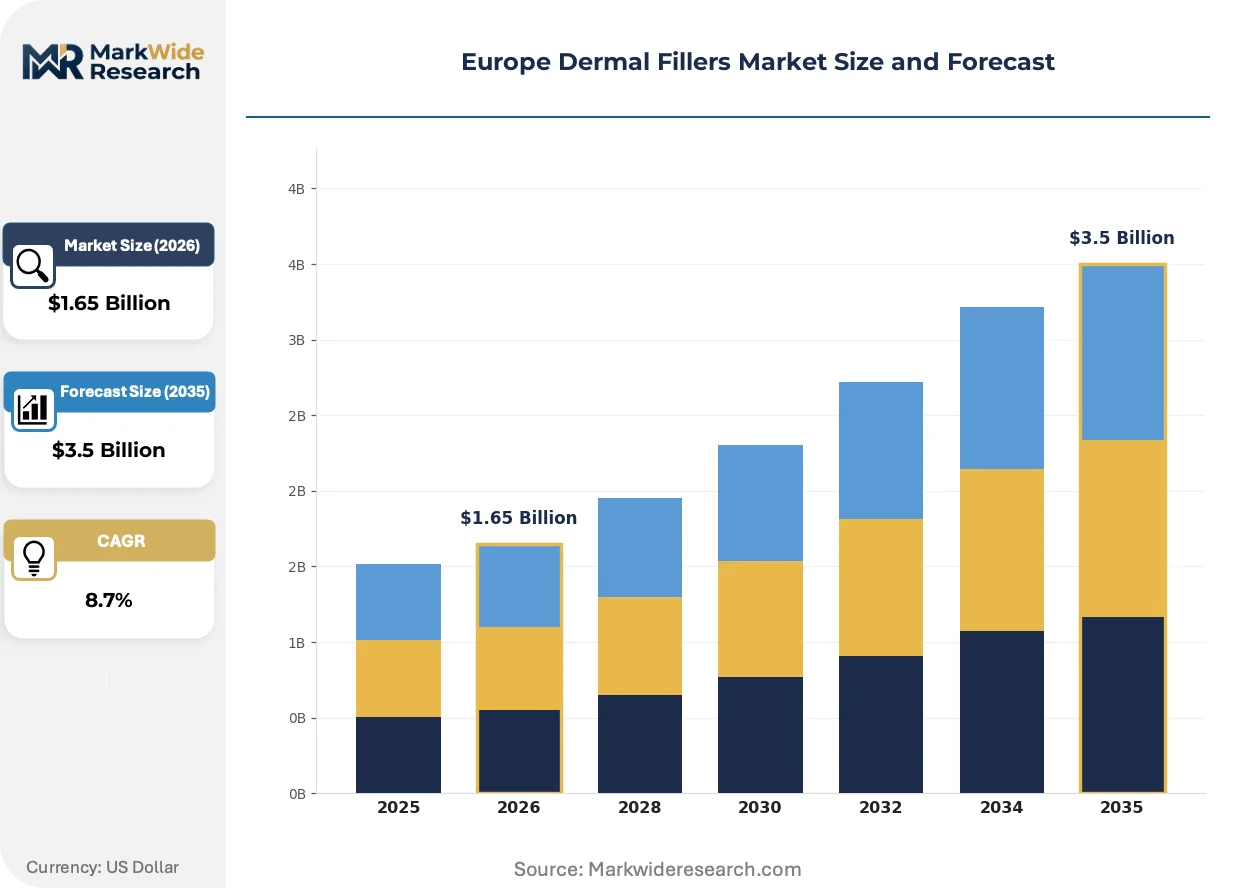
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $3.5 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyaluronic Acid, Calcium Hydroxylapatite, Poly-L-lactic Acid, Fat-based Application: Facial Contouring, Lip Enhancement, Wrinkle Reduction, Scarring End User: Clinics, Hospitals, Medical Spas, Home Users Distribution Channel: Direct Sales, Online Retail, Distributors, Medical Professionals |
| Companies Covered | Allergan Aesthetics (AbbVie), Galderma, Merz Pharma, Teoxane Laboratories, Sinclair Pharma, Bioxis Pharmaceuticals, Prollenium Medical Technologies, Suneva Medical, Revance Therapeutics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dermal Fillers Market Shifts & Advancements
Formulation science and digital treatment planning are converging to reshape how European practitioners deliver facial aesthetic outcomes, with regulatory compliance now embedded as a competitive differentiator rather than baseline threshold.
Cross-linked hyaluronic acid gels with modified rheological profiles are absorbing market share from first-generation formulations by enabling more precise volumization in thin-tissue zones. Physician-run aesthetic centers in Germany and the United Kingdom are adopting these advanced viscoelastic products for tear trough and perioral indications. The technology is absorbing training investment from manufacturers seeking to lock in high-volume clinic accounts through proprietary injection technique certifications.
EMA's centralized marketing authorization pathway for novel substances now requires extended follow-up data on immunogenicity and long-term tissue integration. The industrial consequence is delayed market entry for synthetic collagen stimulators and calcium hydroxylapatite innovations compared to hyaluronic acid equivalents with established equivalence claims. Italian and Spanish manufacturers are responding by prioritizing line extensions of existing CE-marked portfolios over novel entity development.
Patient acquisition through social media visual documentation is compressing consultation-to-treatment cycles and shifting channel economics toward direct-to-consumer marketing spend. Independent aesthetic clinics in United Kingdom secondary cities are disintermediating traditional referral networks by investing in in-house content production and influencer partnerships. This behavioral shift is most visible in London and Manchester, where younger demographic cohorts now discover providers through algorithmic content feeds rather than physician referrals or directory listings.
Europe Dermal Fillers Market Segmentation
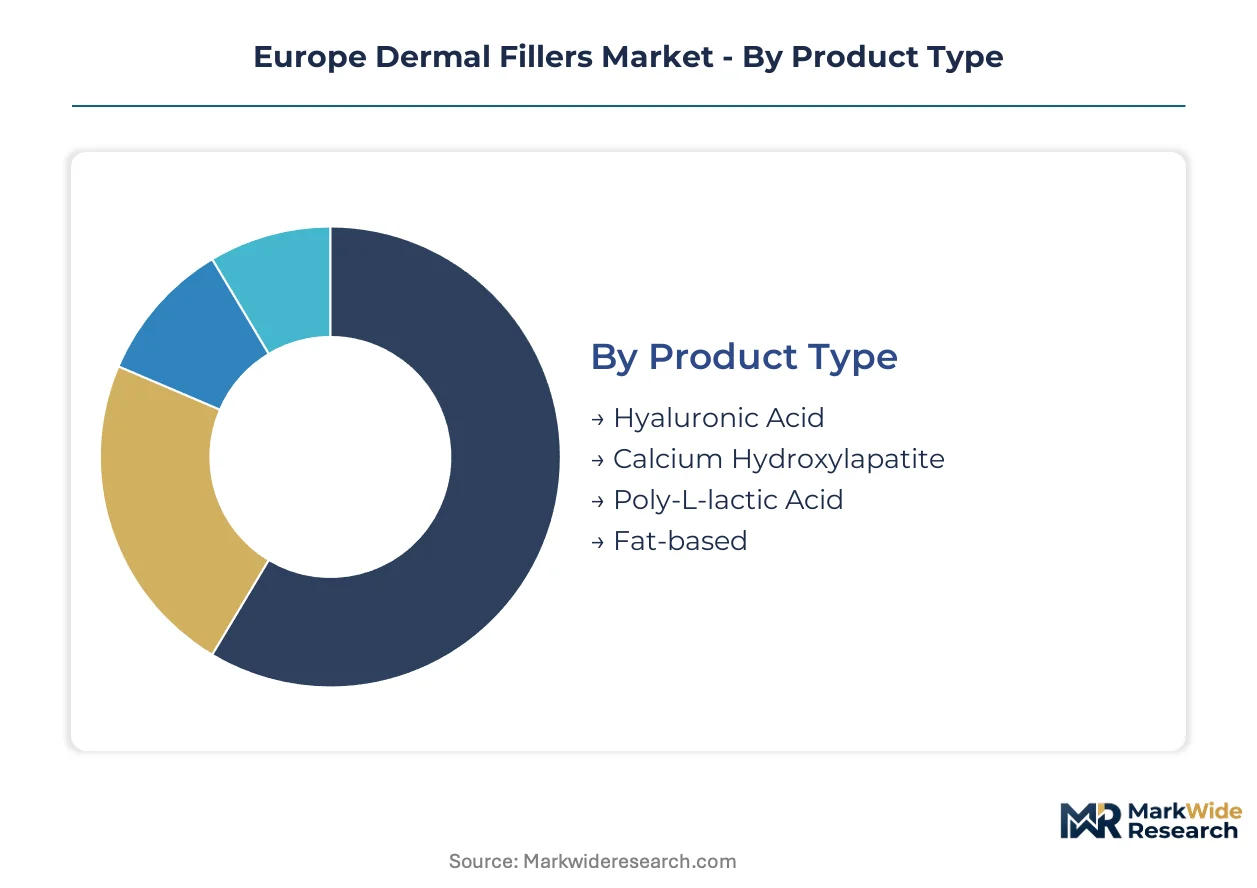
European dermal filler procurement splits sharply between high-volume hyaluronic acid formulations and premium collagen biostimulators. Understanding these segment boundaries clarifies where MDR compliance costs concentrate and which channels capture margin pools across Germany, France, and United Kingdom aesthetic markets.
Product Type:
Volume flows concentrate in reversible formulations, while premium pricing attaches to permanent collagen induction protocols.
- Hyaluronic Acid:Cross-linked polysaccharide gels dominate European procedure volumes due to enzymatic reversibility with hyaluronidase. Germany's physician-run aesthetic centers favor advanced viscoelastic profiles for tear trough and perioral precision work, with EMA equivalence pathways accelerating MDR recertification for established portfolios.
- Poly-L-lactic Acid:Microparticle suspensions stimulate neocollagenesis through gradual fibroblast activation. France's metropolitan clinic chains bundle these biostimulators with neuromodulators for time-constrained professional cohorts, capturing margin pools from patients seeking gradual rather than immediate volumization.
- Calcium Hydroxylapatite:Biocompatible mineral microspheres suspended in aqueous gel carrier for deeper structural support.
- Fat-based:Autologous adipocyte transfer via lipoharvesting competes in mature patient segments seeking permanent correction without synthetic implant risks.
Today's leader: Hyaluronic Acid. Tomorrow's challenger: Poly-L-lactic Acid.
Application:
Procedure frequency tracks facial zone visibility and social media documentation patterns.
- Facial Contouring:Midface volumization and jawline definition procedures concentrate purchasing power in United Kingdom urban centers. London and Manchester clinics report compressed consultation-to-treatment cycles as younger demographic cohorts discover providers through algorithmic content feeds rather than traditional referral networks.
- Wrinkle Reduction:Nasolabial fold and marionette line corrections absorb the majority of hyaluronic acid volume flows. Italian and Spanish manufacturers prioritize line extensions of existing CE-marked portfolios for these established indications over novel entity development given EMA's extended immunogenicity data requirements.
- Lip Enhancement:Vermillion border and philtrum column augmentation represents the fastest-growing trajectory among first-time patients.
- Scarring:Atrophic acne scar correction through subcision and filler combination protocols remains niche.
Wrinkle Reduction commands current volume. Lip Enhancement is climbing the fastest.
End User:
Purchasing authority fragments across institutional settings with divergent procurement sophistication.
- Clinics:Physician-run aesthetic centers in Germany's private clinic corridor command premium pricing through direct manufacturer relationships. These accounts stabilize revenue forecasting for Galderma, Merz Pharma, and Allergan Aesthetics through proprietary injection technique certifications and high-volume commitments.
- Medical Spas:France's aesthetic clinic chains are centralizing procurement through group purchasing organizations, creating volume commitments that reshape distributor economics. United Kingdom secondary city independents disintermediate traditional referral networks through in-house content production and influencer partnerships.
- Hospitals:Reconstructive and post-traumatic applications absorb smaller filler volumes under centralized procurement.
- Home Users:Regulatory barriers and MDR Class III implantable device classification effectively prohibit direct-to-consumer administration.
Clinics anchor manufacturer margin capture. Medical Spas are gaining procurement scale fastest.
Distribution Channel:
Channel selection correlates with account sophistication and regulatory compliance infrastructure.
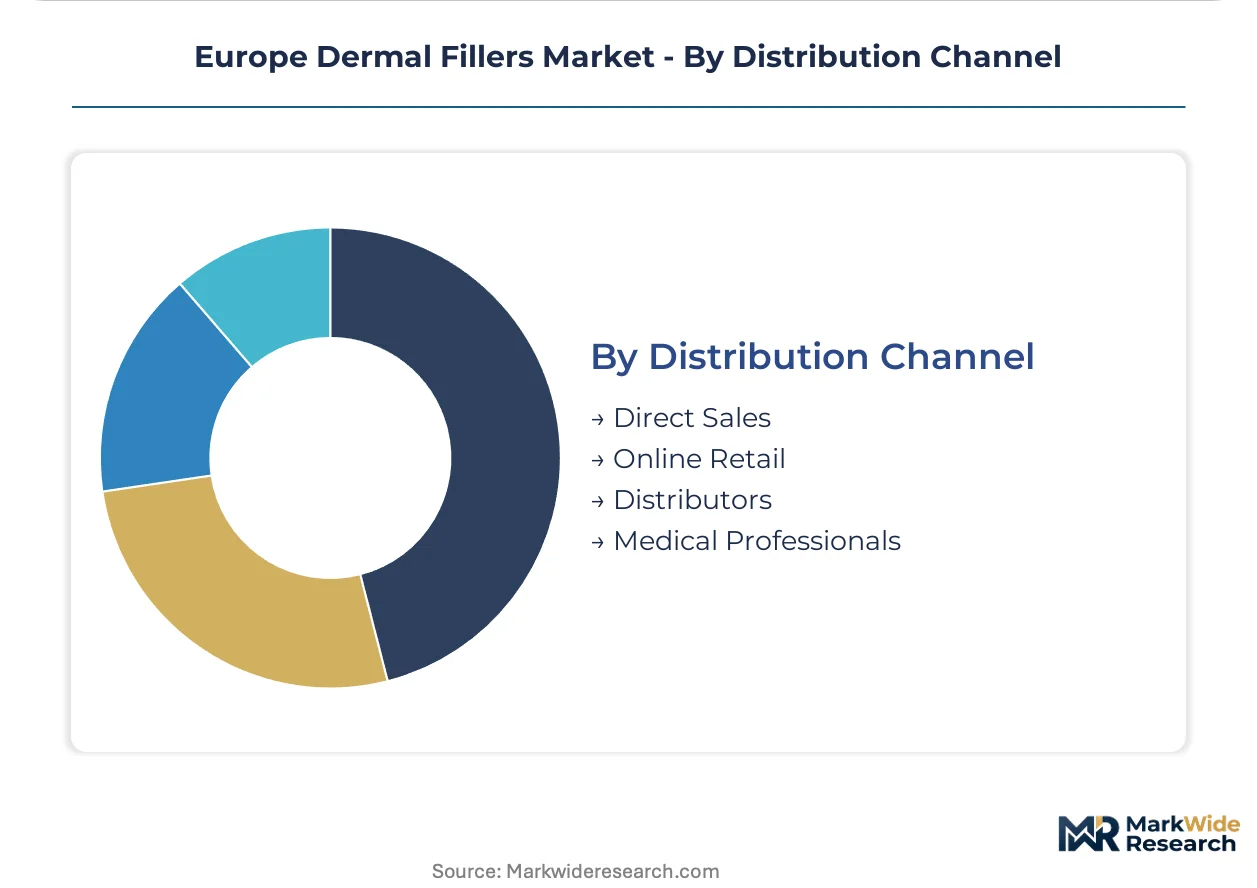
- Direct Sales:Manufacturer field forces maintain shelf presence in high-volume German and United Kingdom clinic accounts through bundled training ecosystems and loyalty programs. Direct relationships enable rapid MDR technical documentation transfer and vigilance reporting coordination.
- Distributors:Regional wholesalers serve fragmented independent aesthetic clinics in Italy, Spain, and emerging Eastern European markets where manufacturer direct coverage remains uneconomical.
- Medical Professionals:Injector-to-injector supply relationships persist in informal channels despite MDR traceability requirements.
- Online Retail:E-commerce penetration remains constrained by prescription device classification and cold chain logistics for hyaluronic acid formulations.
Direct Sales defends premium positioning. Distributors are expanding coverage most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's physician-run aesthetic corridor commands premium pricing power, while France's consolidating medical spa chains reshape procurement economics through centralized purchasing agreements.
Germany
Private clinic networks in Bavaria and North Rhine-Westphalia drive demand for advanced viscoelastic hyaluronic acid formulations. The Federal Institute for Drugs and Medical Devices enforces MDR conformity assessment through expanded notified body capacity for biological safety evaluations. Munich and Düsseldorf aesthetic centers stabilize manufacturer revenue through high-volume commitments and proprietary injection technique certifications.
France
Metropolitan Paris clinic chains bundle collagen biostimulators with neuromodulators for time-constrained professional cohorts. ANSM coordinates national vigilance reporting for Class III implantable devices under MDR post-market surveillance obligations. Lyon and Marseille medical spas centralize procurement through group purchasing organizations, compressing distributor margins while securing volume discounts.
United Kingdom
London and Manchester independents disintermediate traditional referral networks through algorithmic social media content and influencer partnerships. The Medicines and Healthcare products Regulatory Agency enforces MDR technical documentation requirements for CE-marked filler portfolios. Secondary city clinics report compressed consultation-to-treatment cycles as younger demographics discover providers through visual documentation platforms.
Italy
Lombardy and Emilia-Romagna manufacturers prioritize line extensions of existing CE-marked portfolios over novel entity development. The Italian Medicines Agency applies EMA's extended immunogenicity data requirements for centralized marketing authorization pathways. Milan aesthetic clinics absorb training investment from manufacturers seeking to lock in accounts through cannula technique certifications.
Poland
Warsaw and Krakow aesthetic markets remain undersupplied with premium MDR-certified filler portfolios, presenting first-mover advantages for compliant manufacturers. The Office for Registration of Medicinal Products, Medical Devices and Biocidal Products enforces national MDR implementation through post-market surveillance coordination. Private clinic expansion in urban centers outpaces qualified injector availability, creating certification bottlenecks.
Europe Dermal Fillers Market Competitive Landscape
Swiss and German producers anchor the premium-tier portfolio; French and UK specialists hold positions in biostimulator and combination protocol segments. Market structure consolidates around three multinational dermatology portfolios with integrated training ecosystems, while mid-tier manufacturers face MDR compliance cost pressures. Strategic archetypes include full-stack dermatology platforms, neuromodulator-filler combination specialists, and regional portfolio licensors. Dominant competitive moves involve proprietary injection technique certifications and direct-to-practitioner education infrastructure.
Within the integrated dermatology tier, Galderma and Allergan Aesthetics exemplify full-stack platforms with sustained shelf presence in high-volume clinic accounts. Merz Pharma occupies a specialized position through neuromodulator and filler combination protocols. These three anchors represent distinct geographic origins—Swiss, US-Irish, and German—and collectively demonstrate how manufacturer field forces defend premium positioning through bundled training ecosystems and loyalty programs.
| Leading Market Players |
|---|
| Allergan Aesthetics (AbbVie) |
| Galderma |
| Merz Pharma |
| Teoxane Laboratories |
| Sinclair Pharma |
| Bioxis Pharmaceuticals |
| Prollenium Medical Technologies |
| Suneva Medical |
| Revance Therapeutics |
| Others |
Supply & Pricing Matrix
Cross-linked hyaluronic acid fermentation scale-up in German and Swiss bioreactor facilities is compressing unit production costs while concentrating formulation expertise among three pharmaceutical-grade suppliers, simultaneously reshaping procurement economics and manufacturer margin structures across European aesthetic markets.
Pricing Analysis
Capacity additions in Germany's notified body ecosystem are reshaping price floors for MDR-certified Class III implantable devices. Three-tier pricing structure across premium, standard, and economy levels separates physician-run German clinics from French medical spa chains and Eastern European independents, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from raw material concentration among European hyaluronic acid fermenters. French group purchasing organizations exhibit highest price sensitivity; German private clinic corridors show lowest.
Supply Chain Analysis
Qualified fermentation technicians and biological safety evaluators concentrate in Germany, Switzerland, and France, constraining batch release capacity for novel filler submissions. Pharmaceutical-grade hyaluronic acid draws from three European bioreactor operators, with collagen biostimulator microparticles resting on Italian and French polymer synthesis. Single-source vulnerability runs through notified body certification queues. Distribution runs through manufacturer field forces in high-volume accounts, regional wholesalers in fragmented markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European dermal fillers hinges on MDR compliance cost amortization across expanding procedure volumes, with premium-tier collagen biostimulators capturing pricing power from time-constrained professional cohorts seeking gradual volumization protocols.
For Market Incumbents: Lock in high-volume German clinic accounts through proprietary cannula technique certifications and bundled neuromodulator-filler combination protocols. Defend against mid-tier MDR recertification delays by accelerating equivalence pathway documentation for established hyaluronic acid portfolios. Prioritize backward integration into pharmaceutical-grade hyaluronic acid fermentation to secure raw material allocation.
For New Entrants and Emerging Players: Algorithmic facial analysis software for treatment planning faces EU AI Act transparency mandates, creating compliance service revenue streams for software-integrated device manufacturers. Target Poland and Czech Republic aesthetic markets where premium MDR-certified portfolios remain undersupplied. Lead with direct-to-practitioner training ecosystems rather than distributor-dependent coverage.
For Investors and Strategic Acquirers: Roll-up economics work for neuromodulator-filler combination specialists because French medical spa consolidation centralizes procurement through group purchasing organizations, compressing standalone filler margins. Five-to-ten-year viability favors manufacturers with integrated dermatology platforms and vigilance reporting infrastructure. Watch notified body capacity expansion as inflection indicator for novel product registration timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Equivalence Pathway Investment | Accelerates CE-marking for established hyaluronic acid portfolios against novel entity delays. |
| Neuromodulator-Filler Combination Bundling | Captures margin pools from French metropolitan clinic chains serving time-constrained professionals. |
| Eastern European Direct Sales Expansion | Secures first-mover positioning in Poland and Czech Republic undersupplied premium segments. |
| EU AI Act Compliance Service Development | Creates recurring revenue from algorithmic facial analysis tool transparency obligations. |
| Proprietary Injector Certification Programs | Locks in German physician-run aesthetic centers through supervised cannula technique training. |
Research Methodology
Direct dialogue with aesthetic clinic medical directors, notified body biological safety officers, group purchasing organization procurement leads, and EMA regulatory affairs specialists grounded qualitative findings. Secondary validation drew from EMA centralized marketing authorization pathways, EU MDR technical documentation guidance, ANSM vigilance reporting databases, and hospital procurement contract registries. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue segmentation.
Segmentation outputs across product type, application, end user, and distribution channel dimensions fed into analytical framework spanning the projection horizon. CAGRs derived from regression against demographic aging curves, medical spa establishment rates, and MDR implementation phase transitions. Forecast inputs incorporated notified body capacity constraints and social media-driven patient acquisition velocity in United Kingdom urban centers.
The model holds under stable MDR notified body capacity and sustained hyaluronic acid fermentation supply; deviation in raw material bioreactor constraints or AI Act enforcement intensity would shift volume and value trajectories. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Platysmaplasty Treatment Market
Aesthetic Medicine
Global Dermal Filler Market
Aesthetic Medicine
Global Buttock Augmentation Market
Aesthetic Medicine
Phototherapy Lamps and Units for Aesthetic Medicine Market
Aesthetic Medicine
Aesthetic Medicine and Cosmetic Surgery Market
Aesthetic Medicine
Chemical Peel Market
Aesthetic Medicine
Global Aesthetic Fillers Market
Aesthetic Medicine
Skin Tightening Market
Aesthetic Medicine
Body Contouring Market
Aesthetic Medicine
Aesthetic Lasers and Energy Devices Market
Aesthetic Medicine
Global Facial Fat Transfer Market
Aesthetic Medicine
Aesthetic Services Market
Aesthetic Medicine
North America Aesthetic Dermatology Market
Aesthetic Medicine
Photorejuvenation Market
Aesthetic Medicine
Japan Facial Aesthetics Market
Aesthetic Medicine
Hirsutism Treatment Market