
 Hinged Food Containers Market | 2026-2036
Hinged Food Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Hinged Food Containers Market Foresight
Asset-light leasing models for thermoforming and injection molding equipment are narrowing the capital barrier for mid-scale entrants into hinged food container production. Pactiv Evergreen leverages its integrated resin-through-converting footprint to sustain cost discipline across North American quick-service accounts. Dart Container anchors its position through massive polystyrene and polypropylene capacity that dominates the institutional foodservice channel. Huhtamaki competes by extending its molded fiber technology leadership into hinged formats that meet emerging compostability requirements.
Hinged food containers are rigid enclosures with integrated living-hinge lids, typically thermoformed from polypropylene, polystyrene, or molded pulp, designed to seal prepared foods for transport, retail display, and temperature retention. The disposable segment leads volume but faces margin compression as material costs fluctuate, while the biodegradable category records the fastest expansion as foodservice operators respond to procurement mandates from corporate sustainability programs. Plastic retains dominant share in hot-food applications due to heat tolerance, though paper-based alternatives are capturing share in cold prepared meals where moisture resistance requirements are less severe.
The FDA governs food-contact substance compliance under 21 CFR, while the EPA regulates emissions from container manufacturing facilities, and the EU REACH framework restricts certain polymer additives in export-bound production. These overlapping standards compel manufacturers to maintain dual certification streams and reformulate compounds to satisfy divergent regional thresholds. Stakeholders must monitor how extended producer responsibility schemes in California, Germany, and France redefine cost allocation between resin suppliers, converters, and foodservice brands.
Market Dynamics
The EU Single-Use Plastics Directive is compressing polystyrene volumes while redirecting capital toward fiber-based thermoforming lines, creating a bifurcated supply structure where heat-tolerant plastic retains hot-food applications and molded pulp captures cold prepared meals.
Growth Catalysts
- Cloud Kitchen Proliferation:Ghost kitchen operators in the United States are standardizing on hinged formats for delivery-optimized packaging, pulling container volumes through centralized procurement hubs.
- REACH Additive Restrictions:The EU framework is accelerating reformulation investments that position early movers for premium positioning in export-bound production.
- Biodegradable Mandates:Corporate sustainability programs at quick-service chains are embedding compostability requirements into supplier scorecards, expanding addressable demand for molded fiber alternatives.
Market Restraints
- Resin Price Volatility:Polypropylene and polystyrene feedstock costs fluctuate with crude oil movements, compressing converter margins during upstream spikes.
- Thermoforming Equipment Concentration:German and Italian machinery suppliers control high-speed hinged-line manufacturing, creating capex bottlenecks for mid-scale entrants.
- Heat Tolerance Gap:Molded pulp containers face structural limitations above 85°C, locking them out of hot fried food and soup applications where polypropylene dominates.
Strategic Opportunities
- Indian Quick-Service Expansion:FSSAI compliance pathways for food-contact materials are stabilizing, enabling container suppliers to capture volume from organized foodservice growth in tier-1 cities.
- Extended Producer Responsibility:California's SB 54 implementation is creating fee structures that reward fiber-based formats with lower compliance costs versus plastic alternatives.
- Dual-Ovenable Formulations:Convergence of barrier-coated paperboard and microwave-safe films is opening refrigerated meal segments previously reserved for plastic.
Industry Challenges
- Molded Fiber Tooling Lead Times:Precision aluminum dies for hinged pulp formats require 16-20 week fabrication cycles, delaying product launches and customer conversions.
- Dual Certification Streams:Manufacturers must maintain parallel FDA 21 CFR and EU REACH compliance documentation, increasing quality assurance headcount and audit costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hinged Food Containers Market |
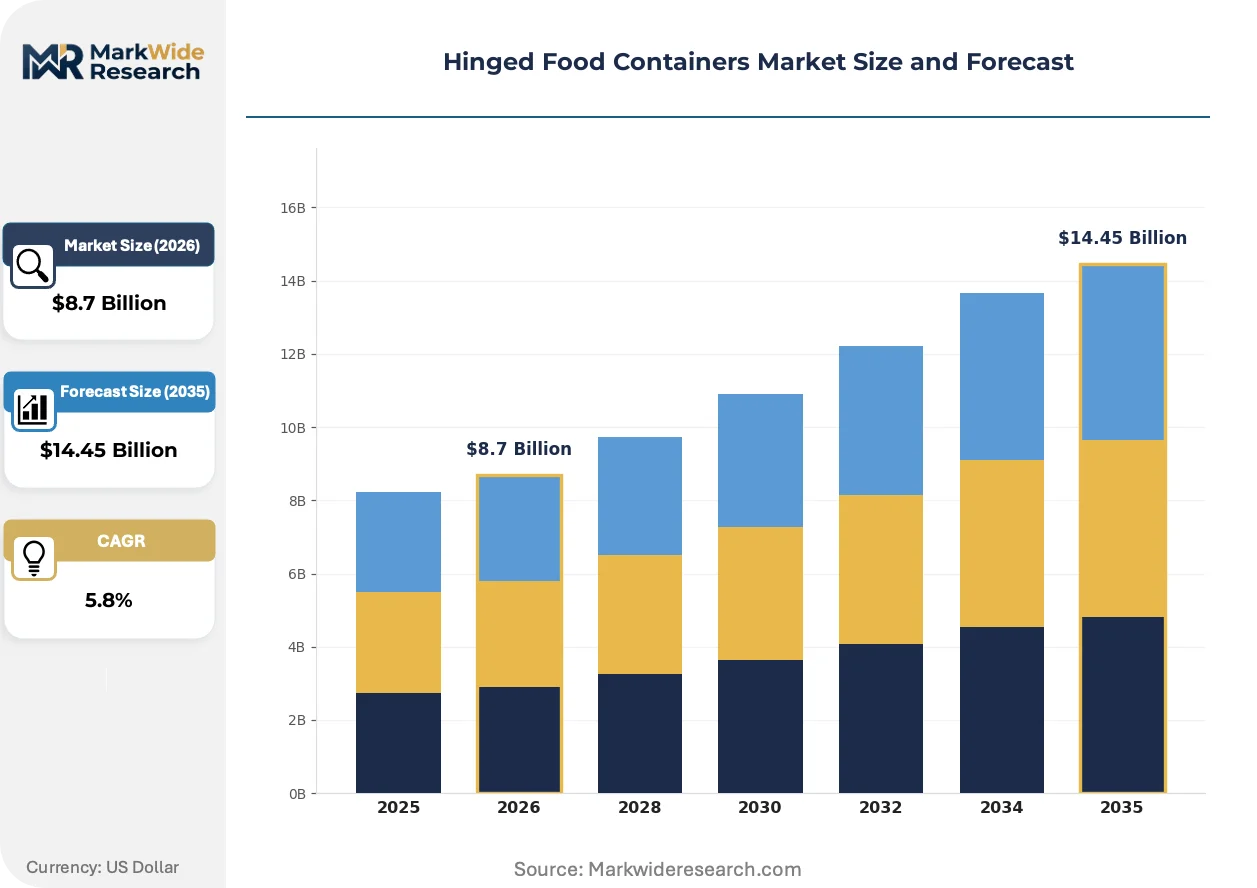
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Biodegradable, Insulated Material: Plastic, Paper, Aluminum, Glass End User: Restaurants, Catering Services, Home Use, Food Trucks Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Pactiv Evergreen Inc., Dart Container Corporation, Genpak LLC, Sabert Corporation, Anchor Packaging Inc., Placon Corporation, Novolex Holdings LLC, Fabri-Kal, Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hinged Food Containers Market Shifts & Advancements
Material science advances and regulatory compression are converging to redefine performance thresholds for hinged food containers, with functionality and compliance now inseparable design parameters rather than sequential considerations.
Barrier-coated molded fiber technology is rendering obsolete the moisture-resistance advantage that polypropylene held in refrigerated prepared meals. Retail grocery chains and meal-kit operators are adopting these formats at accelerating pace for cold pasta, grain bowls, and deli applications. The structural consequence is a volume migration out of plastic thermoforming lines and into pulp molding capacity expansions.
REACH restrictions on perfluorinated compounds are forcing reformulation of grease-resistant coatings across EU-bound production. Industrial consequence includes accelerated R&D spending on bio-based barrier alternatives and qualification delays for incumbent suppliers. The quick-service segment is most affected, with operators reformulating menu items to reduce fat content where coating performance gaps persist.
Direct procurement relationships between container converters and cloud kitchen networks are disintermediating traditional foodservice distributors. Aggregator platforms are consolidating buying power across dispersed kitchen operators, compressing supplier margins through volume-based negotiation. This pattern is most visible in United States urban corridors where delivery density supports dedicated logistics lanes.
Hinged Food Containers Market Segmentation
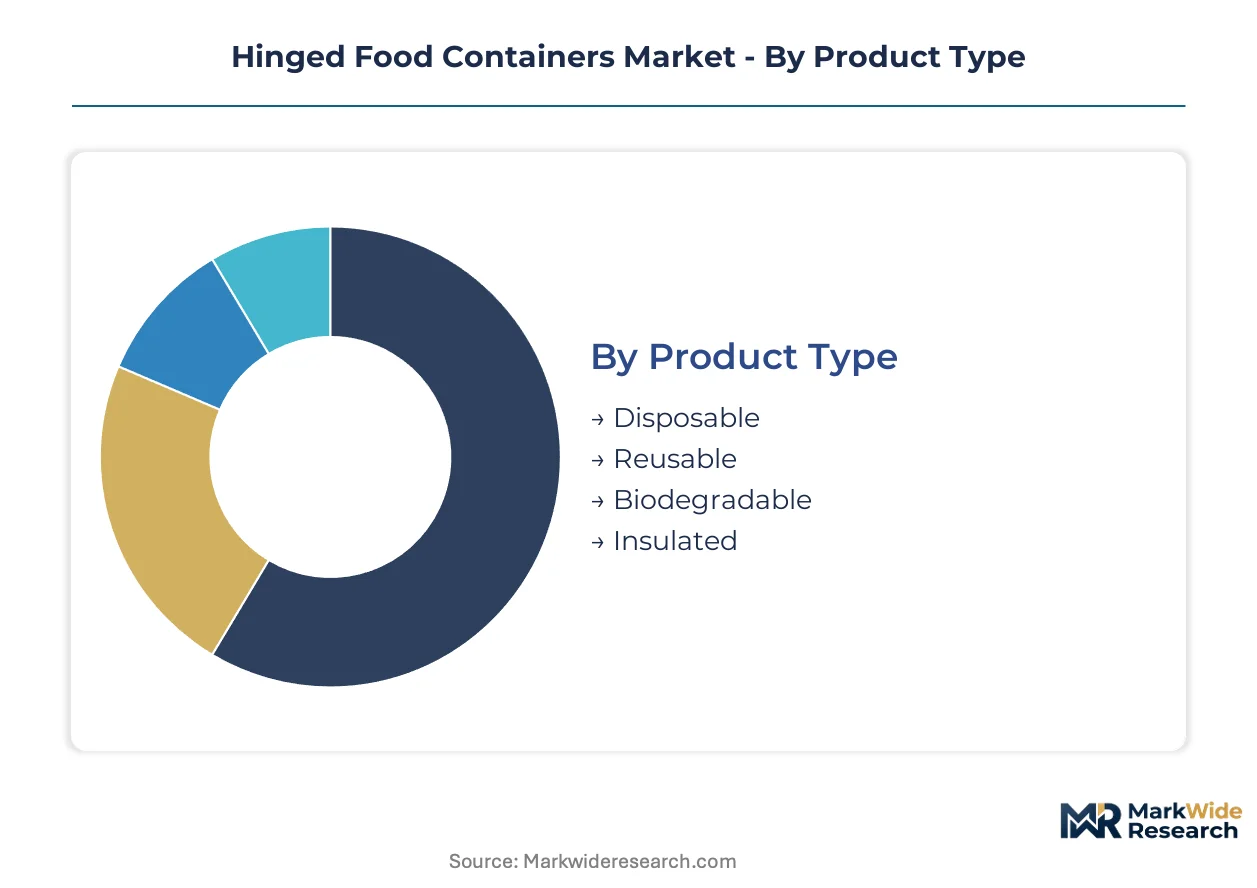
Hinged food container procurement cycles vary dramatically by segment, with disposable formats turning over weekly at quick-service chains while reusable systems amortize over years in institutional settings. Understanding these velocity differentials shapes inventory positioning and margin capture strategies for converters.
Product Type:
Disposable units rotate fastest through supply chains, while insulated formats sit longest in distributor warehouses awaiting seasonal demand spikes.
- Disposable:Thermoformed polypropylene and polystyrene enclosures dominate quick-service takeaway operations. Cloud kitchen networks in the United States pull these volumes through centralized procurement hubs with weekly replenishment cycles.
- Biodegradable:Molded fiber and bagasse-based hinged formats carry compostability certifications required by corporate sustainability programs. The EU Single-Use Plastics Directive accelerates substitution timelines across member state foodservice operations.
- Reusable:Durable polypropylene systems serve institutional cafeterias and corporate catering with return-logistics infrastructure. Higher unit economics depend on wash-cycle durability and RFID tracking integration.
- Insulated:Expanded polystyrene or vacuum-panel constructions target temperature-sensitive delivery applications. Seasonal demand concentration around summer catering and holiday meal kits creates inventory planning challenges.
Disposable formats anchor the volume base while biodegradable alternatives gain share at the steepest rate.
Material:
Cost tiers separate commodity resins from barrier-coated substrates, with aluminum and glass occupying premium positioning that limits addressable market scope.
- Plastic:Polypropylene dominates hot-food applications above 85°C where heat tolerance is non-negotiable. REACH additive restrictions are forcing reformulation investments for EU-bound production streams.
- Paper:Barrier-coated molded fiber captures cold prepared meals and deli applications where moisture resistance requirements moderate. Retail grocery chains are accelerating adoption for refrigerated grain bowls and pasta salads.
- Aluminum:Foil-laminated hinged formats serve premium ready-meal segments requiring extended shelf stability. Higher material costs restrict penetration to upscale retail channels and airline catering.
- Glass:Borosilicate and tempered glass containers target reusable meal-prep and premium home-delivery niches. Weight and fragility constraints exclude last-mile logistics applications.
Plastic retains the broadest installed base while paper-based alternatives climb the fastest among material transitions.
End User:
Customer concentration patterns diverge sharply, with restaurant chains consolidating procurement through GPOs while food trucks fragment across independent distributors.
- Restaurants:Full-service and quick-service operators standardize on hinged formats optimized for delivery platform compatibility. Ghost kitchen proliferation in dense urban corridors is disintermediating traditional foodservice distributors.
- Catering Services:Event and institutional caterers demand volume-scalable solutions with stackability and transport stability. Seasonal demand spikes around corporate events and wedding seasons stress converter capacity planning.
- Home Use:Retail-packaged hinged containers serve meal-prep enthusiasts and leftover storage needs. E-commerce subscription models for reusable systems are emerging through direct-to-consumer channels.
- Food Trucks:Mobile operators prioritize space-efficient nesting designs and rapid-service lid closure. Geographic dispersion and irregular order patterns complicate distributor route optimization.
Restaurant channels concentrate procurement volume while food truck segments expand most quickly as mobile foodservice proliferates.
Capacity:
Volume throughput and margin structure vary by size class, with medium formats achieving optimal manufacturing efficiency while extra-large units carry premium pricing for specialized applications.
- Medium:Standard entree portions dominate production line utilization across thermoforming and pulp molding equipment. Quick-service combo meals and single-serve retail applications drive consistent demand.
- Large:Family-size and shared-platter formats serve catering and group dining contexts with higher per-unit revenue. Stack height and nesting ratio constraints limit transport efficiency.
- Small:Side-dish and condiment portions complete meal packaging systems with lower material intensity. Portion-control trends in healthcare and weight-management segments sustain niche demand.
- Extra Large:Bulk catering and institutional tray formats require reinforced hinge designs and structural ribs. Limited production runs and custom tooling amortization elevate unit costs.
Medium capacity anchors manufacturing throughput while large formats command the strongest pricing premiums per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented container converters in Germany and China supply fiber-based formats to North American quick-service chains, while import-dependent markets in Southeast Asia source thermoforming equipment from Italian machinery suppliers. Trade flows concentrate where regulatory divergence creates arbitrage opportunities for dual-certified production.
United States
Cloud kitchen density in Los Angeles, Chicago, and New York Metro drives weekly replenishment cycles for disposable hinged formats. The FDA governs food-contact compliance under 21 CFR while California's SB 54 extended producer responsibility scheme penalizes polystyrene with higher compliance fees. Pactiv Evergreen anchors North American supply through integrated resin-through-converting operations.
Germany
REACH additive restrictions on perfluorinated compounds force reformulation of grease-resistant coatings for EU-bound production streams. The EU Single-Use Plastics Directive compresses polystyrene volumes while redirecting capital toward fiber-based thermoforming lines. Industrial clusters around Stuttgart and Munich host precision aluminum die fabricators serving molded fiber tooling demand.
China
Domestic quick-service expansion in Shanghai, Beijing, and Shenzhen pulls volumes through centralized procurement hubs. The country's national standards body governs food-contact material safety alongside import compliance requirements for export-bound production. Yangtze River Delta converters supply barrier-coated molded fiber to European retail grocery chains.
India
FSSAI compliance pathways for food-contact materials stabilize as organized foodservice penetrates tier-1 cities. Maharashtra and Karnataka host thermoforming equipment distributors serving quick-service chains expanding into Mumbai and Bangalore. Import duties on polypropylene resin fluctuate with currency movements, compressing converter margins.
Japan
Premium ready-meal segments in Tokyo and Osaka demand extended shelf stability from barrier-laminated formats. METI oversees industrial standards for food-contact materials while municipal composting infrastructure supports biodegradable container adoption. Kanto region converters specialize in small-batch customized hinged designs for convenience store chains.
Hinged Food Containers Market Competitive Landscape
On the supply side, the industry is consolidating around integrated resin-through-converting footprints and specialized molded fiber technology leaders. Tier-one players command quick-service accounts through scale economies, while mid-scale entrants lease thermoforming equipment to narrow capital barriers. Three archetypes dominate: integrated petrochemical-converters, pure-play fiber molders, and equipment-leasing specialists. M&A activity concentrates on regional distributors, while capacity expansion targets compostable fiber lines in EU-facing production.
Among North American integrated players, Pactiv Evergreen Inc. and Dart Container Corporation exemplify scale-driven archetypes with captive resin supply. Huhtamaki occupies a position within the fiber-specialist tier, representing technology leadership in molded pulp formats. These three anchors illustrate how competitive positioning stratifies across material integration depth and sustainability certification breadth.
| Leading Market Players |
|---|
| Pactiv Evergreen Inc. |
| Dart Container Corporation |
| Genpak LLC |
| Sabert Corporation |
| Anchor Packaging Inc. |
| Placon Corporation |
| Novolex Holdings LLC |
| Fabri-Kal |
| Huhtamaki |
| Others |
Supply & Pricing Matrix
Trans-Pacific container routes from Yangtze River Delta ports to Los Angeles and Long Beach transmit resin cost volatility directly into landed pricing for thermoformed hinged containers, amplifying spreads between integrated converters and resin-dependent competitors while forcing buyers toward annual contract structures that buffer spot-market swings.
Pricing Analysis
Quick-service procurement directors anchor pricing structures around three-tier differentiation across premium compostable, standard polypropylene, and economy polystyrene grades. Price differentiation rests on certification tier—FDA 21 CFR compliance versus EU REACH additive restrictions—and volume scale through centralized cloud kitchen procurement hubs. Cost compression in economy polystyrene tiers is intensifying because EU Single-Use Plastics Directive compliance fees elevate total delivered cost. Food truck operators exhibit highest price sensitivity due to irregular order patterns and limited storage capacity, while airline catering buyers absorb premium aluminum-laminated pricing without volume negotiation leverage.
Supply Chain Analysis
German and Italian machinery suppliers—Illig, Kiefel, and GDM—control high-speed thermoforming line manufacturing, creating equipment allocation bottlenecks for mid-scale entrants. Raw material procurement draws from Saudi Arabian and Qatari polypropylene resin streams, Brazilian bagasse pulp for fiber alternatives, and Chinese aluminum foil for barrier laminations. Single-source vulnerability concentrates in precision aluminum die fabrication for molded fiber tooling, where Stuttgart-area fabricators command 16-20 week lead times. Distribution runs through foodservice distributor networks in North America, direct converter relationships with cloud kitchen aggregators in dense urban corridors, and institutional GPO contracts for reusable system deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision thermoforming equipment access and REACH-compliant coating formulation capabilities constitute the binding constraints that separate viable competitors from stranded capacity, with molded fiber tooling lead times extending to five months and perfluorinated compound restrictions eliminating incumbent grease-barrier chemistries.
For Market Incumbents: Harden supply security through backward integration into resin compounding or captive pulp molding capacity expansions in EU-facing production zones. Anchor quick-service accounts by pre-investing in dual-certification documentation streams that satisfy simultaneous FDA and REACH compliance, insulating against reformulation-driven supplier switches. Prioritize cloud kitchen direct procurement relationships to disintermediate distributor margin capture in Los Angeles, Chicago, and New York Metro corridors. For New Entrants and Emerging Players: Pursue equipment-leasing partnerships with Italian machinery distributors to bypass 16-20 week thermoforming line procurement cycles and establish pilot capacity without resin-through-converting capital intensity. Tier-1 Indian cities—Mumbai, Bangalore, Delhi—present the most penetrable geography as FSSAI compliance pathways stabilize and organized quick-service penetration accelerates. Lead with biodegradable formats carrying compostability certifications that align with corporate sustainability procurement mandates at emerging cloud kitchen networks. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated paperboard packaging parents seeking to divest non-core molded fiber operations amid strategic portfolio rebalancing toward core consumer goods segments. Long-term viability over a multi-year horizon favors converters with demonstrated dual-certification maintenance capabilities and established cloud kitchen procurement relationships that survive distributor disintermediation. Monitor California SB 54 fee structure implementation as the signal to watch for fiber-based format demand acceleration versus polystyrene displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Pactiv Evergreen and Dart Container sustain margin discipline through captive polypropylene supply. |
| Molded Fiber Capacity Expansion | Huhtamaki extends technology leadership into EU-facing compostable production lines. |
| Dual Certification Investment | Converters maintaining parallel FDA 21 CFR and REACH documentation capture export-bound quick-service accounts. |
| Cloud Kitchen Direct Procurement | Aggregator platforms consolidate dispersed operator buying power through dedicated logistics lanes. |
| Equipment Leasing Partnership | Asset-light models narrow capital barriers for mid-scale entrants targeting biodegradable segment growth. |
Research Methodology
The analysis maps disposable thermoformed, biodegradable molded fiber, reusable institutional, and insulated delivery formats, each validated through procurement directors at quick-service chains, equipment leasing specialists, thermoforming machinery distributors, and foodservice distributor category managers. Primary interview data triangulates against secondary sources including FDA 21 CFR food-contact substance filings, EU ECHA REACH restriction updates, FSSAI compliance notifications, and trade flow records from Yangtze River Delta export documentation. Bottom-up volume estimates from converter capacity utilization cross-check against top-down demand aggregation from quick-service chain procurement disclosures.
Assumptions held fixed include EU Single-Use Plastics Directive enforcement timelines, California SB 54 extended producer responsibility fee structures, and cloud kitchen network expansion trajectories in dense urban corridors; variables tested include polypropylene resin price volatility bands, molded fiber tooling lead time compression, and REACH additive restriction scope expansion. Segmentation dimensions span product type, material substrate, end-user channel, and capacity class. CAGRs derive from unit volume trajectory analysis across the projection horizon, incorporating food delivery platform growth curves and corporate sustainability procurement mandate penetration rates as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by resin-integrated players or accelerated molded fiber tooling investment by equipment-leasing specialists would shift outcomes beyond modeled ranges. Quarterly review of EU ECHA restriction proposal advancement, California SB 54 fee schedule updates, and cloud kitchen aggregator procurement consolidation metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Sanitizer Bottles Market
Packaging Containers
Packing Boxes Market
Packaging Containers
Double Seam Bowl Market
Packaging Containers
Africa Flexitank Market
Packaging Containers
North America Food Cans Market
Packaging Containers
Global Food Re Close Pack Market
Packaging Containers
VCI Bags Market
Packaging Containers
Tamper Evident Pots and Tubs Market
Packaging Containers
Assembly Trays Market
Packaging Containers
Candle Box Market
Packaging Containers
Monobloc Aerosol Cans Market
Packaging Containers
Snap Single Dose Dispensers Market
Packaging Containers
Gable Boxes Market
Packaging Containers
Inverted Squeeze Bottle Market
Packaging Containers
Automotive Parts Packaging Market
Packaging Containers
Membrane Boxes Market