
 Africa Flexitank Market | 2026-2036
Africa Flexitank Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Flexitank Market Analytics
Market Context
The IMO 2023 greenhouse gas strategy is restructuring containerized liquid shipping economics across African ports. SIA FLEXITANKS leverages integrated manufacturing to control quality across multi-layer polyethylene assemblies. Bulk Liquid Transport anchors its position through dedicated fleet partnerships with regional shipping lines. Hillebrand Gori Group GmbH differentiates via temperature-sensitive cargo protocols for food-grade liquids.
Technical Definition and Segments
A flexitank is a collapsible, multi-layer bladder typically constructed from polyethylene and polypropylene barriers, designed to convert standard twenty-foot containers into bulk liquid transport systems carrying 16,000 to 24,000 liters. Standard Flexitank configurations dominate current African volume due to compatibility with existing container pools and lower per-unit capital outlay. Biodegradable Flexitank variants represent the fastest-expanding material segment as European importer mandates cascade through supply chains into Kenyan tea and Nigerian cocoa export corridors. Composite Material constructions capture premium margin pools where chemical resistance requirements exceed single-polymer performance thresholds.
Regulatory Frame
Kenya's Kenya Maritime Authority and Nigeria's Nigerian Maritime Administration and Safety Agency enforce container safety inspections that directly influence flexitank certification requirements for cross-border liquid shipments. The African Continental Free Trade Area rules of origin and phytosanitary protocols are tightening documentation standards for food-grade flexitank deployments. Stakeholders must monitor how harmonized African Union transport standards reshape equipment interoperability requirements across regional trade lanes.
Market Dynamics
The Africa Flexitank Market pivots on the tension between containerized bulk liquid demand and the fragmented regulatory landscape governing cross-border agricultural exports. Kenya Maritime Authority and Nigerian Maritime Administration and Safety Agency inspection protocols are forcing rapid equipment certification upgrades across East and West African trade corridors.
Growth Catalysts
- African Continental Free Trade Area Phytosanitary Protocols:Harmonized documentation standards for food-grade liquid shipments are accelerating flexitank adoption over traditional drum packaging in cocoa and tea export supply chains.
- Polyethylene Barrier Advancements:Multi-layer co-extrusion technologies now achieve oxygen transmission rates below 0.5 cc/m²/day, preserving edible oil quality through extended Mombasa-European port transits.
- Lagos-Apapa Port Cluster Congestion:Container turnaround compression is driving shippers toward single-use flexitank systems that eliminate cleaning logistics and reduce dwell time penalties.
Market Restraints
- Polypropylene Feedstock Volatility:Crude-linked resin pricing swings of 30-40% within fiscal quarters compress converter margins and destabilize contract pricing for 24,000-liter capacity units.
- Single-Source Valve Component Concentration:Precision injection-molded discharge fittings rely on a limited supplier base concentrated in Southeast Asian manufacturing zones, exposing African assemblers to extended lead times.
- IMO 2023 Greenhouse Gas Strategy Compliance Costs:Container fleet decarbonization mandates are redirecting carrier capital away from flexitank-compatible equipment toward alternative fuel infrastructure.
Strategic Opportunities
- Ethiopian Coffee Processing Corridor:Underdeveloped liquid transport infrastructure between Addis Ababa industrial zones and Djibouti port creates first-mover positioning for integrated flexitank service providers.
- Biodegradable Polymer Mandates:European Union Single-Use Plastics Directive cascading requirements through importer supply chains are accelerating demand for compostable barrier films in Kenyan horticultural exports.
- Rail-Sea Intermodal Integration:Standard Gauge Railway connectivity between Mombasa and Nairobi inland container depots enables flexitank deployment across multimodal corridors previously restricted to tanker truck economics.
Industry Challenges
- Multilayer Film Welding Technician Shortage:Specialized heat-sealing expertise for 5+ ply polyethylene assemblies remains concentrated in Asian manufacturing bases, constraining African localization ambitions.
- Container Pool Compatibility Certification:Individual shipping line approval processes for flexitank brands create fragmented equipment acceptance standards across Maersk, MSC, and CMA CGM networks serving West Africa.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Flexitank Market |
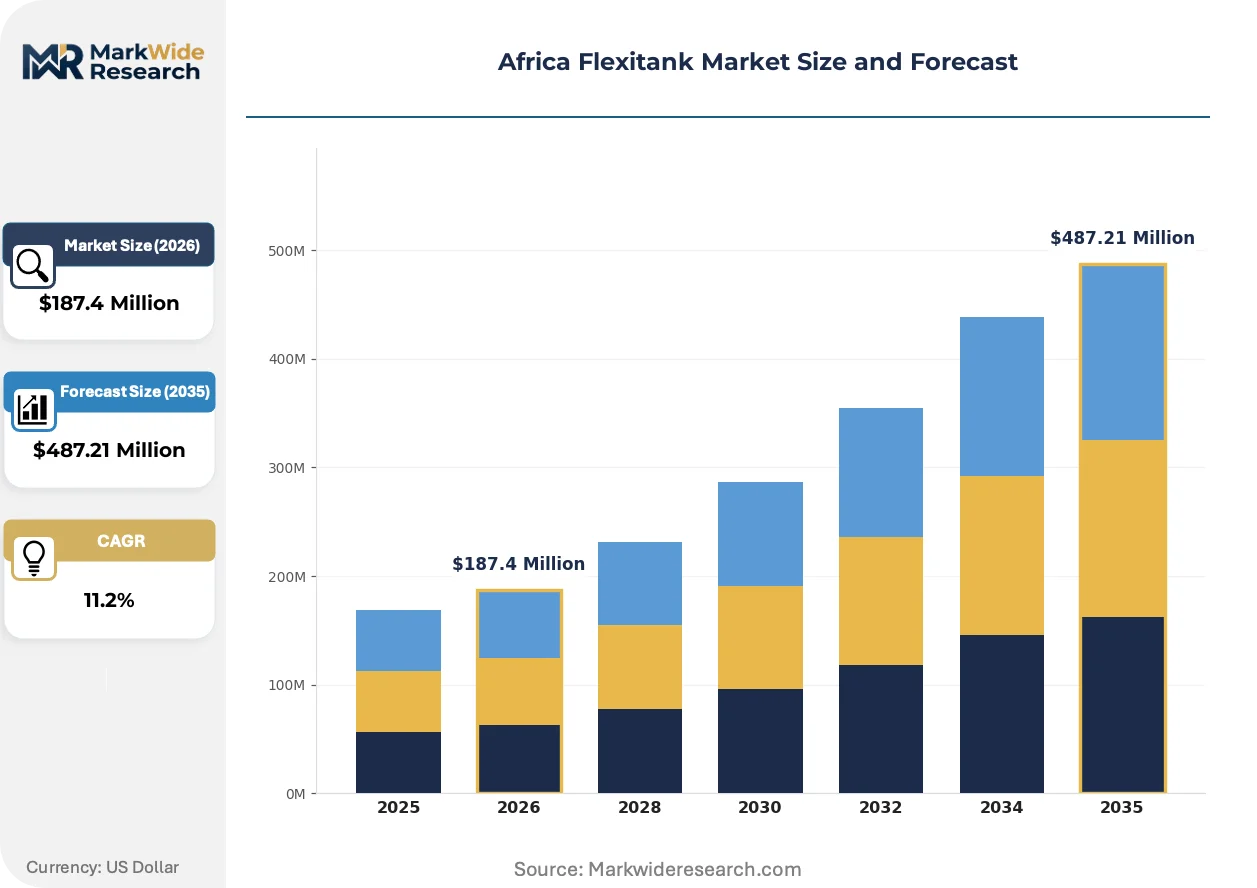
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $487.21 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Flexitank, Conductive Flexitank, Custom Flexitank, Biodegradable Flexitank Material: Polyethylene, Polypropylene, Composite Material, PVC End User: Agriculture, Chemicals, Food and Beverage, Oil and Gas Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | SIA FLEXITANKS, Bulk Liquid Transport, MYFLEXITANK, Hillebrand Gori Group GmbH, Büscherhoff Packaging Solutions GmbH, Qingdao LAF Technology Co., Ltd., Bulk Liquid Solutions, TRUST Flexitanks, Techno Group USA, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Flexitank Market Evolving Landscape
Active transformation across the Africa Flexitank Market centers on material science breakthroughs converging with regulatory pressure and procurement model compression. These forces are restructuring competitive advantage around barrier performance, sustainability credentials, and logistics integration depth.
Barrier film technology is integrating graphene oxide nanocomposite layers into conventional polyethylene assemblies to achieve sub-1% water vapor transmission rates. Nigerian palm oil exporters operating through Lagos-Apapa are adopting these enhanced configurations for 45-day transits to European refineries. The technology is integrating quality preservation capabilities that previously required refrigerated tank containers, collapsing the cost differential between ambient and temperature-controlled bulk liquid logistics.
Kenya Maritime Authority implementation of container safety inspection protocols modeled on International Maritime Organization guidelines is mandating third-party flexitank pressure testing at 6 PSI for 60 minutes. This regulatory friction is disqualifying uncertified regional assemblers from food-grade deployments. Kenyan tea exporters are responding by consolidating procurement around pre-certified equipment providers with documented Kenya Bureau of Standards traceability.
Shipper procurement patterns are compressing contract durations from annual frameworks to spot-market alignment with harvest cycles. Ghanaian cocoa processors are disintermediating traditional logistics aggregators to contract directly with flexitank operators for October-March peak season coverage. This behavioral shift is most visible across West African corridors where commodity price volatility makes long-term equipment commitments economically untenable.
Africa Flexitank Market Segmentation
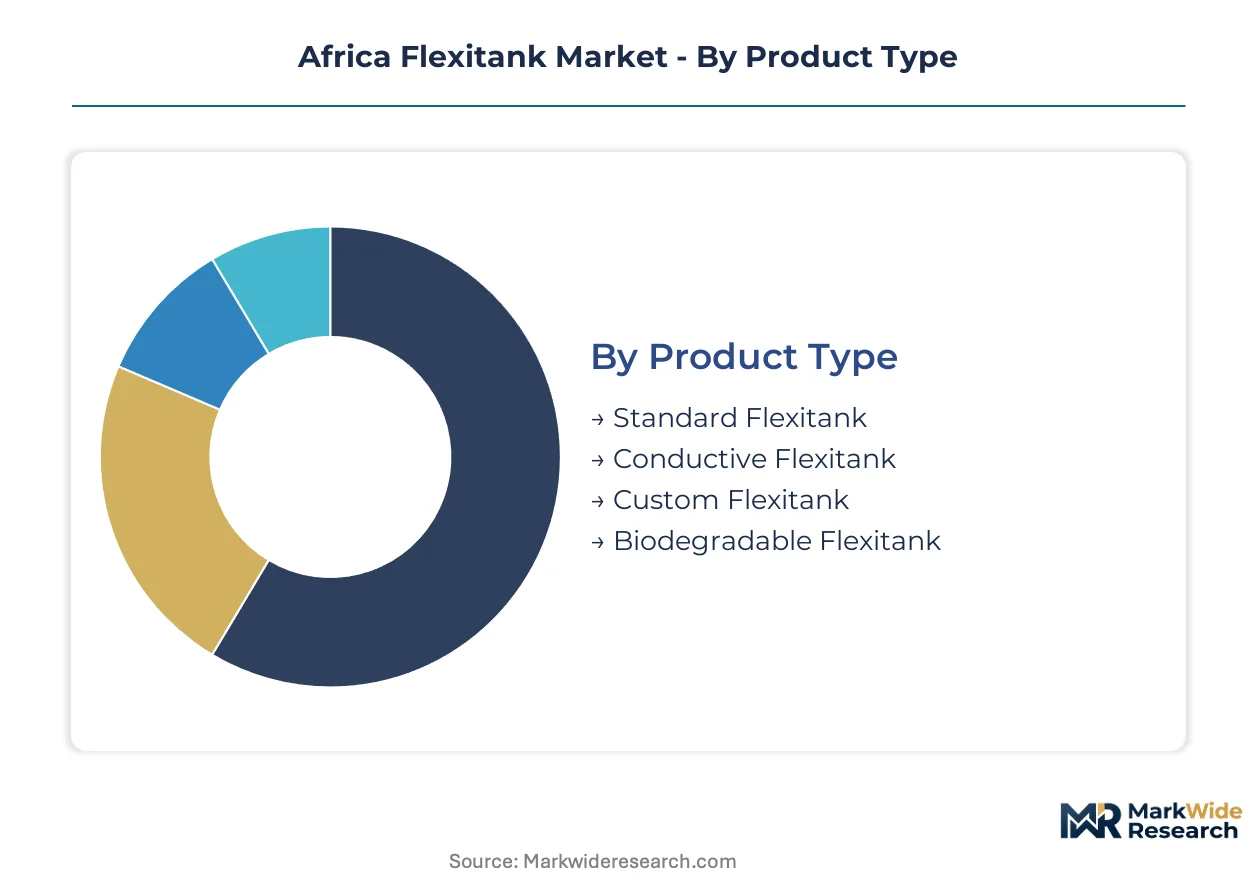
Flexitank segmentation across Africa maps directly to operational trade-offs between capital efficiency, cargo protection, and sustainability compliance. Equipment choices cascade through port handling protocols, insurance requirements, and end-market access permissions.
Product Type:
Standalone single-use configurations dominate Lagos-Apapa and Mombasa corridors where container pool constraints favor rapid turnaround over return logistics. Embedded reusable systems remain marginal due to cleaning infrastructure gaps across inland depots.
- Standard Flexitank:Multi-layer polyethylene assemblies with 16,000-24,000 liter capacity anchor Nigerian palm oil and Kenyan tea export volumes. Compatibility with existing 20-foot container pools across Maersk, MSC, and CMA CGM networks serving West Africa drives procurement concentration.
- Biodegradable Flexitank:Compostable barrier films incorporating polylactic acid layers are penetrating European-facing supply chains where EU Single-Use Plastics Directive compliance is mandatory. Kenyan horticultural exporters to Amsterdam and Rotterdam are piloting these configurations for edible oil and liquid fertilizer shipments.
- Conductive Flexitank:Anti-static polymer formulations address chemical cargo safety requirements for solvent and hydrocarbon transport through Dar es Salaam corridors.
- Custom Flexitank:Tailored dimensional specifications serve specialized chemical and pharmaceutical liquid requirements with non-standard density or temperature profiles.
Standard configurations lead volumes today; biodegradable variants are gaining share fastest.
Material:
Cost tiers stratify sharply around resin price volatility and barrier performance requirements, with chemical resistance commanding premium positioning over food-grade oxygen transmission specifications.
- Polyethylene:Low-density and linear low-density formulations constitute the baseline for agricultural commodity transport, with oxygen transmission rates below 0.5 cc/m²/day now achievable through co-extrusion. Nigerian cocoa butter and Ghanaian crude shea oil exports rely on these specifications for 30-45 day transits to European refineries.
- Composite Material:Multi-polymer laminates combining polyethylene, polypropylene, and ethylene vinyl alcohol layers capture premium chemical resistance applications. South African specialty chemical exporters to mining operations across the Copperbelt utilize these configurations for aggressive solvent containment.
- Polypropylene:Higher melting point and chemical resistance serve hot-fill applications and caustic liquid transport where polyethylene barriers degrade.
- PVC:Legacy material presence persists in low-cost, non-food-grade industrial liquid applications with limited regulatory scrutiny.
Polyethylene leads volumes today; composite materials are climbing the fastest on chemical sector demand.
End User:
Application-driven procurement patterns concentrate in agricultural export corridors where phytosanitary documentation and food-grade certification gates determine equipment eligibility.
- Agriculture:Liquid fertilizer, molasses, and agricultural chemical transport dominates East African volume through Mombasa-Nairobi Standard Gauge Railway integration. Ethiopian coffee processing zones are emerging as a deployment frontier for liquid inputs to wet mill operations.
- Food and Beverage:Edible oils, wine, and fruit juice exports from South African and North African production zones require Kenya Bureau of Standards and Nigerian Maritime Administration and Safety Agency certified barrier assemblies.
- Chemicals:Industrial solvent, lubricant, and process chemical movements serve mining and manufacturing clusters across the Copperbelt and South African industrial heartland.
- Oil and Gas:Base oil, lubricant, and drilling fluid transport supports upstream and downstream petroleum operations with specialized compatibility requirements.
Agriculture leads volumes today; food and beverage is expanding most quickly on AfCFTA harmonized standards adoption.
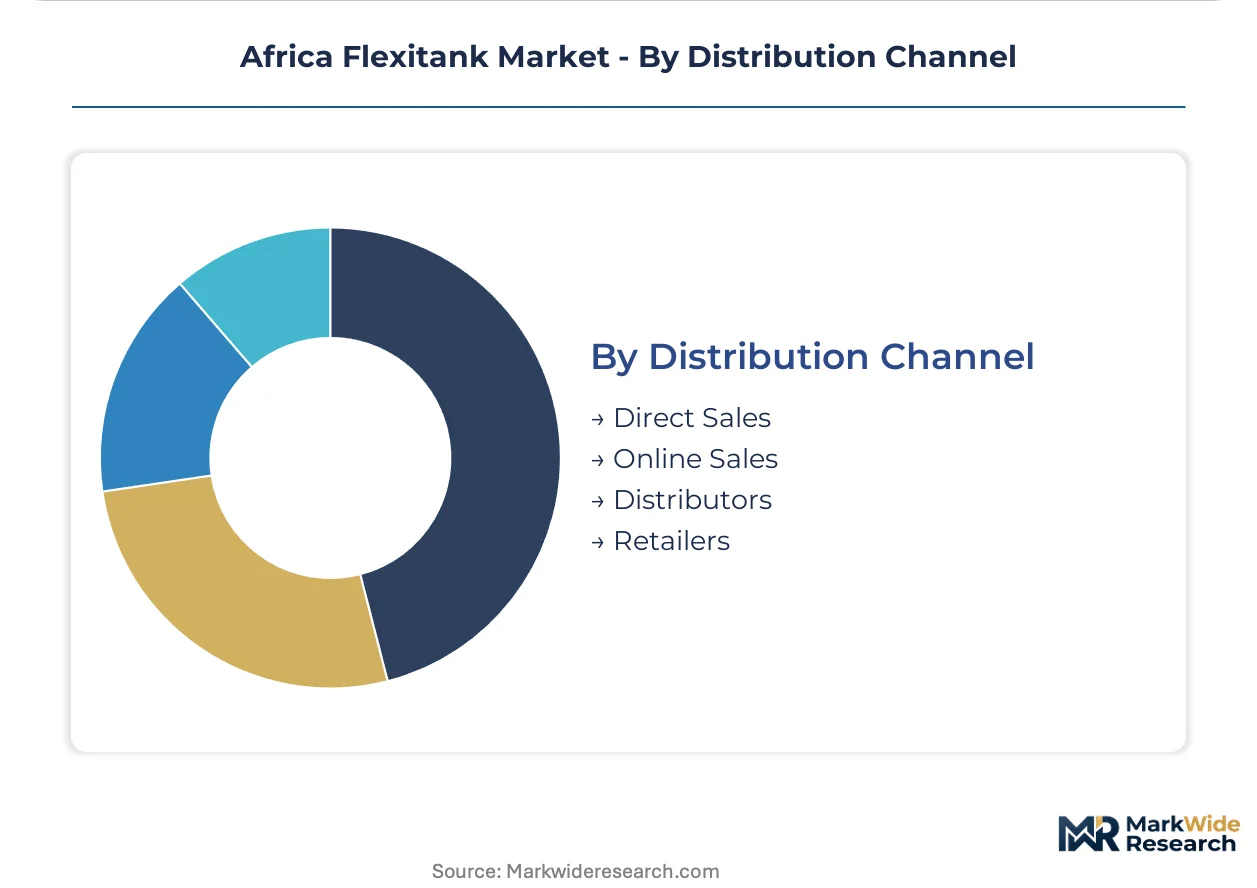
Distribution Channel:
Customer type and procurement scale dictate channel selection, with large agricultural processors bypassing intermediaries while smaller traders rely on distributor inventory buffers.
- Distributors:Regional logistics aggregators with Mombasa, Lagos, and Durban warehousing hold inventory for spot-market agricultural harvest cycles. Ghanaian cocoa processors access flexitank capacity through these channels for October-March peak season coverage.
- Direct Sales:Annual framework agreements between integrated flexitank operators and multinational agricultural exporters provide volume certainty and customized logistics integration. SIA FLEXITANKS and Bulk Liquid Transport secure capacity commitments through this channel.
- Online Sales:Digital procurement platforms are emerging for standardized specifications and smaller lot sizes, though physical inspection requirements limit penetration in food-grade segments.
- Retailers:Hardware and agricultural supply stores serve informal sector liquid transport needs with minimal regulatory compliance overhead.
Distributors lead volumes today; direct sales are gaining share fastest on procurement model compression toward shipper-operator alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flexitank logistics first achieved commercial scale in European agricultural export corridors before migrating to African trade lanes during the 2000s containerization wave. The technology now anchors bulk liquid movement across East and West African port gateways.
Nigeria
Lagos-Apapa port cluster congestion drives single-use flexitank adoption for palm oil and cocoa butter exports to European refineries. The Nigerian Maritime Administration and Safety Agency enforces container safety inspections that mandate third-party pressure certification for food-grade liquid shipments. Port operators in the Lagos corridor report container turnaround compression is eliminating return logistics for reusable systems.
Kenya
Mombasa gateway handles tea and edible oil exports requiring Kenya Bureau of Standards traceability for flexitank barrier assemblies. The Kenya Maritime Authority implements IMO-aligned container inspection protocols that disqualify uncertified regional assemblers from phytosanitary-compliant deployments. Standard Gauge Railway connectivity to Nairobi inland container depots enables rail-sea intermodal flexitank logistics previously restricted to tanker trucking.
Ghana
Cocoa processors deploy flexitanks for October-March peak season liquid chocolate and butter exports to European confectionery manufacturers. The country's national food safety regulator enforces documentation standards that accelerate equipment certification upgrades across Tema port operations. Accra-Tema industrial zone processors are disintermediating traditional logistics aggregators to contract directly with flexitank operators.
South Africa
Durban and Cape Town corridors serve specialty chemical exports to mining operations across the Copperbelt with composite material flexitank configurations. The country's national standards body maintains barrier performance specifications that exceed baseline agricultural requirements. Johannesburg industrial heartland chemical formulators utilize multi-polymer laminates for aggressive solvent containment in cross-border shipments.
Ethiopia
Addis Ababa industrial zones and coffee processing wet mills create emerging demand for liquid fertilizer and agricultural chemical transport to Djibouti port. The Ethiopian Investment Commission infrastructure development programs are targeting logistics gap closure between production zones and maritime export gateways. First-mover flexitank service providers are positioning integrated offerings across this underdeveloped corridor.
Africa Flexitank Market Competitive Landscape
Capital-heavy integrated manufacturers compete with asset-light logistics service providers across the African flexitank value chain. The market structure concentrates around three strategic archetypes: vertically integrated producers controlling multi-layer polyethylene assembly quality, dedicated fleet operators securing carrier partnerships, and temperature-sensitive cargo specialists differentiating through food-grade protocols. Dominant competitive moves include backward integration into captive resin supply and geographic expansion through regional shipping line certification programs.
Within the integrated manufacturing tier, SIA FLEXITANKS and Bulk Liquid Transport exemplify capital-intensive positioning through in-house production control over barrier film assemblies. Hillebrand Gori Group GmbH represents the specialized logistics archetype, occupying a position defined by temperature-sensitive cargo handling protocols. Qingdao LAF Technology Co., Ltd. anchors the Asia-origin supply vector, while Büscherhoff Packaging Solutions GmbH and MYFLEXITANK sit within the European fabrication cluster serving African export demand.
| Leading Market Players |
|---|
| SIA FLEXITANKS |
| Bulk Liquid Transport |
| MYFLEXITANK |
| Hillebrand Gori Group GmbH |
| Büscherhoff Packaging Solutions GmbH |
| Qingdao LAF Technology Co., Ltd. |
| Bulk Liquid Solutions |
| TRUST Flexitanks |
| Techno Group USA |
| Others |
Value Network & Pricing Analysis
Multinational agricultural exporters concentrated in Nigerian palm oil and Kenyan tea corridors dictate contract structures that favor annual volume commitments over spot-market flexibility. Their procurement leverage compresses converter margins while rewarding integrated operators with captive resin supply and carrier certification depth.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement, with composite material barriers commanding 40-60% premiums over baseline polyethylene configurations due to chemical resistance specifications. Price differentiation hinges on Kenya Bureau of Standards certification tier and volume scale, with October-March cocoa harvest cycles triggering demand surges that strain converter capacity. Cost compression in standard-grade polyethylene assemblies is intensifying because polypropylene feedstock volatility transmits directly to contract renegotiation frequency. Smallholder agricultural traders exhibit highest price sensitivity, while integrated chemical exporters demonstrate lowest elasticity due to specialized barrier performance requirements.
Supply Chain Analysis
Multi-layer polyethylene film supply rests on Southeast Asian petrochemical complexes in Thailand, Singapore, and South Korea, with precision valve injection molding concentrated in Chinese manufacturing zones. Raw material dependencies span linear low-density polyethylene resin, ethylene vinyl alcohol coextrusion barriers, and polypropylene discharge fittings. Single-source vulnerability in precision-molded valve components exposes African assemblers to 8-12 week lead time extensions during regional production disruptions. Distribution runs through Mombasa, Lagos-Apapa, and Durban port logistics aggregators holding inventory buffers for agricultural harvest cycle alignment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa Flexitank Market functions as a geographic-arbitrage play between European sustainability mandates and African agricultural export infrastructure gaps, with EU Single-Use Plastics Directive compliance costs in origin markets creating procurement pull for certified barrier equipment.
For Market Incumbents: To counter biodegradable polymer mandate acceleration from European importer supply chains, SIA FLEXITANKS and Bulk Liquid Transport should deepen backward integration into polylactic acid barrier film supply and secure preemptive Kenya Maritime Authority certification extensions ahead of harmonized African Union transport standards implementation. For New Entrants and Emerging Players: AfCFTA phytosanitary protocol harmonization across East African Community member states opens a window for integrated flexitank service providers to establish first-mover positioning in Ethiopian coffee processing corridors between Addis Ababa industrial zones and Djibouti port, leveraging direct shipper-operator contracting models that bypass traditional logistics aggregators. For Investors and Strategic Acquirers: Integrated logistics service providers with container fleet partnerships are the most active acquirer in this space, targeting mid-scale flexitank operators with existing Maersk, MSC, or CMA CGM carrier approvals. Long-term viability centers on sustainability credential depth and multimodal rail-sea integration capability. The signal to watch is Kenya Bureau of Standards traceability mandate expansion into Nigerian and Ghanaian regulatory frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Barrier Certification | EU Single-Use Plastics Directive compliance secures access to Amsterdam and Rotterdam import corridors. |
| Rail-Sea Intermodal Integration | Standard Gauge Railway connectivity collapses Mombasa-Nairobi logistics costs below tanker truck economics. |
| Carrier Certification Expansion | Maersk, MSC, and CMA CGM equipment approval unlocks container pool access across West African trade lanes. |
| Resin Supply Backward Integration | Captive polyethylene coextrusion capacity insulates margins from 30-40% quarterly resin price volatility. |
| Phytosanitary Documentation Pre-Certification | Kenya Maritime Authority pressure testing alignment accelerates food-grade deployment eligibility. |
Research Methodology
Direct dialogue with flexitank manufacturing plant managers, agricultural exporter procurement leads, Mombasa and Lagos-Apapa port logistics coordinators, Kenya Maritime Authority inspection officials, and Nigerian cocoa processor supply chain directors grounded qualitative assessment. Secondary validation drew from International Maritime Organization greenhouse gas strategy filings, Kenya Bureau of Standards certification registries, AfCFTA phytosanitary protocol documentation, and customs trade data through East African Community revenue authorities. Bottom-up equipment shipment tallies and top-down containerized liquid trade flow estimates were triangulated to anchor volume assumptions.
Segment-level projections across product type, material grade, end-use application, and distribution channel were generated through the analysis window using elasticity-adjusted demand curves. CAGRs were derived from regression against agricultural export volume forecasts, resin price trajectory scenarios, and carrier fleet deployment schedules. Key model inputs included IMO 2023 compliance cost pass-through rates to container shipping economics and biodegradable polymer substitution elasticity in European-facing supply chains.
Revisions become necessary when polypropylene feedstock volatility exceeds historical quarterly bands, when harmonized African Union transport standards disrupt existing national certification reciprocity, or when rail-sea intermodal infrastructure deployment timelines shift materially. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
VCI Bags Market
Packaging Containers
Acrylic Boxes Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
Trigger Spray Bottle Market
Packaging Containers
Insulated Food Containers Market
Packaging Containers
Monobloc Aerosol Cans Market
Packaging Containers
Automotive Parts Packaging Market
Packaging Containers
Pillow Pack Packaging Market
Packaging Containers
Cluster Packaging Market
Packaging Containers
Euro Box Market
Packaging Containers
Candle Box Market
Packaging Containers
Insulated Icebox Market
Packaging Containers
Eyewear Packaging Market
Packaging Containers
Dosage Cups Market
Packaging Containers
Cooler Box Market
Packaging Containers
Clamshell Packaging Market