
 Candle Box Market | 2026-2036
Candle Box Market Size, Share, and Industry Trends Forecast 2026-2036
Candle Box Market Outlook
Specialty paperboard converters in the United States is pivoting toward rigid candle box production to capture premium packaging contracts. McKenzieCrest Inc. leverages its domestic manufacturing footprint to serve mid-market candle brands with quick-turn orders. PakFactory sustains competitive pricing through digital print workflows that reduce minimum order thresholds. Elite Custom Box specializes in foil-stamped rigid boxes that anchor luxury candle lines at specialty retailers.
A candle box is a structurally engineered paperboard or rigid packaging enclosure designed to protect, display, and transport candles, typically constructed from 18-24 point SBS board or corrugated E-flute with aqueous or UV coating for heat resistance and shelf appeal. Its primary commercial purpose is to merge protective logistics with brand storytelling at the point of unboxing. Glass jar packaging dominates value pools in the candle box segment because breakage protection commands premium substrate specifications. Cardboard boxes represent the fastest-growing packaging type as e-commerce fulfillment demands lighter, shippable formats. Soy wax candle lines drive disproportionate box innovation since sustainable material claims require FSC-certified or recycled-content packaging alignment.
The EPA regulates volatile organic compound emissions from print coatings used on candle packaging manufactured in the United States, while REACH restricts phthalate-based inks and adhesives in European-sourced boxes. FDA food-contact standards indirectly shape wax-adjacent packaging when candles carry botanical or edible-oil positioning that triggers substrate migration testing. Stakeholders must monitor how state-level extended producer responsibility laws in California and New York reshape box recycling accountability and material specification mandates.
Market Dynamics
Direct-to-consumer candle brands are compressing order cycles and demanding quick-turn rigid box production, forcing paperboard converters to retool for smaller batch sizes with premium finishing capabilities.
Growth Catalysts
- Subscription box economics:Candle brands in the United States are scaling monthly delivery programs that require durable, visually distinctive packaging to sustain unboxing-driven retention.
- REACH material mandates:European compliance requirements for phthalate-free inks and adhesives are accelerating substrate innovation toward bio-based coatings.
- Soy wax alignment:Sustainable wax claims require FSC-certified or recycled-content packaging, pulling premium paperboard specifications into mid-market product lines.
Market Restraints
- Pulp cost volatility:SBS board pricing fluctuates with North American softwood pulp supply, squeezing converter margins on fixed-price annual contracts.
- Coating supply concentration:Aqueous and UV coating formulations for heat resistance depend on a limited supplier base in the United States.
- Glass jar substitution:Premium candles in molded pulp or naked glass formats bypass rigid box requirements entirely in boutique retail channels.
Strategic Opportunities
- California EPR leverage:Extended producer responsibility laws create first-mover advantage for converters offering closed-loop recyclable rigid box systems.
- Digital print convergence:Hybrid inkjet and offset workflows enable economic production of SKU-specific candle boxes at sub-500 unit minimums.
- Botanical-oil positioning:FDA food-contact migration testing requirements for edible-oil-adjacent candles open specialized substrate certification services.
Industry Challenges
- Structural engineer scarcity:Rigid box design for candle protection requires specialized paperboard engineering talent concentrated in legacy packaging hubs.
- Coating compliance timelines:EPA volatile organic compound emission testing for new print coatings extends product development cycles by 4-8 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Candle Box Market |
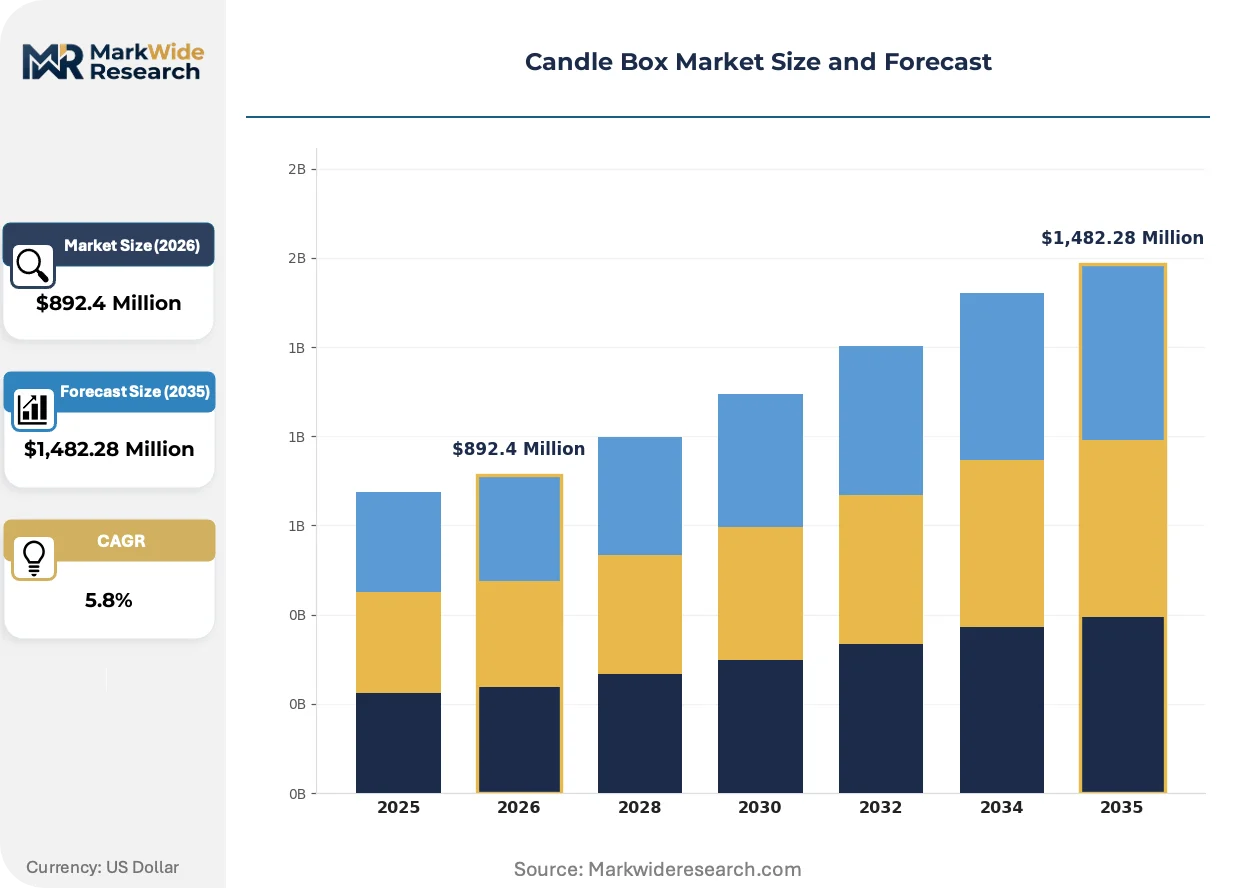
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,482.28 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Candles, Scented Candles, Unscented Candles, Votive Candles Material: Soy Wax, Paraffin Wax, Beeswax, Palm Wax Packaging Type: Glass Jars, Metal Tins, Cardboard Boxes, Plastic Containers Use Case: Home Decor, Gifting, Aromatherapy, Religious Ceremonies |
| Companies Covered | McKenzieCrest Inc., ICM Custom Packaging, BlueBox Packaging, ClipnBox, Elite Custom Box, PakFactory, Refine Packaging, The Custom Boxes, Packlane, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Candle Box Market Strategic Shifts
Digital finishing technologies and regulatory material mandates are converging to compress minimum viable production runs while elevating substrate compliance requirements across candle packaging supply chains.
Hybrid digital-analog print systems is unifying short-run flexibility with foil-stamp and emboss quality previously restricted to offset workflows. Mid-market candle brands in the United States are adopting these systems for seasonal limited editions. The technology is unifying premium aesthetic access with inventory risk reduction, collapsing the traditional volume threshold for rigid box entry.
REACH restrictions on phthalate-based inks and adhesives are tightening substrate specifications for European-sourced candle boxes. ECHA compliance timelines are forcing converters to validate alternative polymer formulations. Luxury candle lines with EU distribution exposure are responding by front-loading packaging qualification budgets.
Buyer-side specification behavior is fragmenting as direct-to-consumer brands internalize packaging design and disintermediate traditional broker relationships. Quick-turn digital converters are capturing specification authority previously held by legacy folding carton suppliers. This pattern concentrates in coastal United States markets where subscription candle startups cluster.
Candle Box Market Segmentation
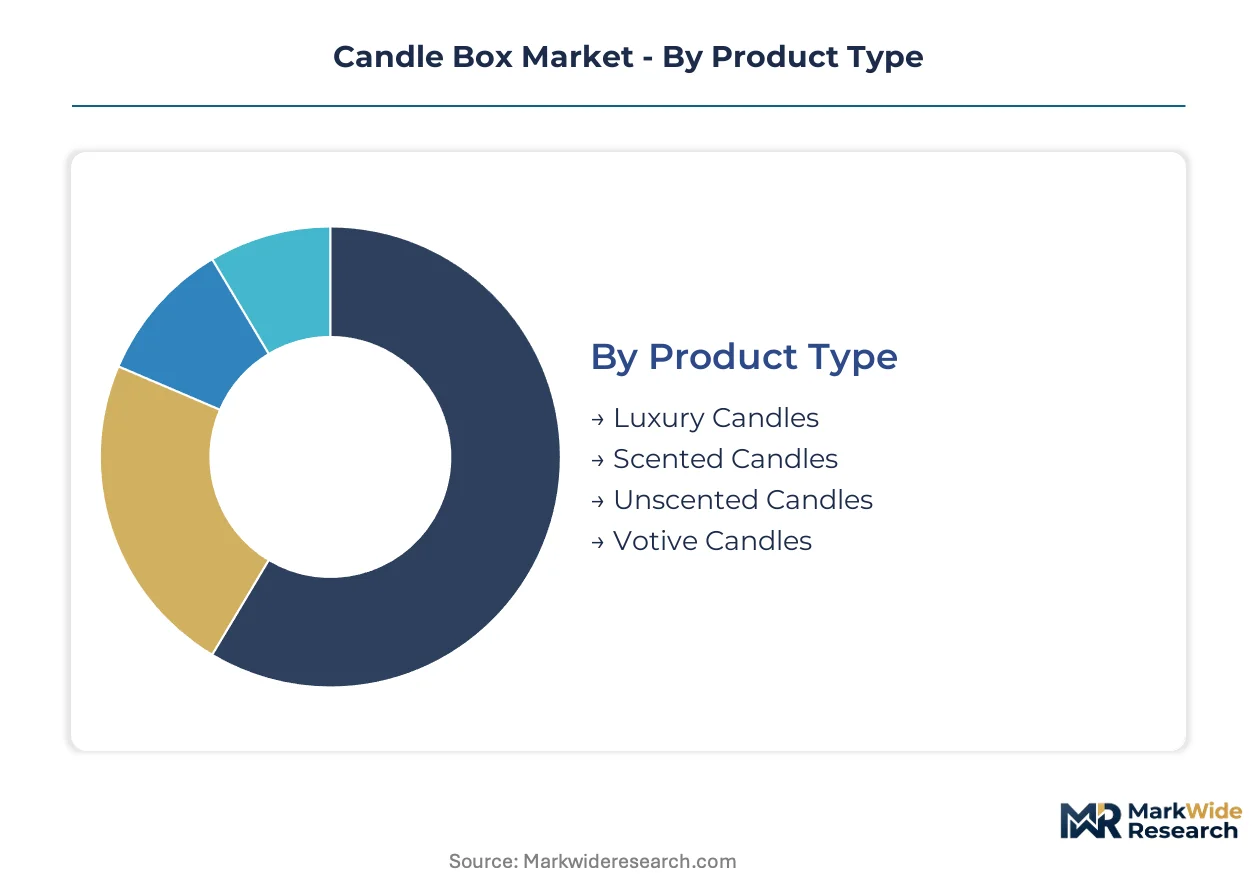
Candle box procurement patterns diverge sharply across product positioning tiers, with luxury and scented lines demanding rigid structural engineering while votive and unscented formats prioritize cost-efficient folding carton solutions. Material chemistry and packaging substrate selection cascade through compliance requirements, particularly where FDA food-contact migration testing or REACH phthalate restrictions apply.
Product Type:
Standalone premium candles command dedicated rigid box architectures with foil-stamp and emboss finishing, while embedded multi-candle sets integrate modular insert systems for transport protection.
- Luxury Candles:Rigid boxes constructed from 18-24 point SBS board with aqueous coating dominate specifications. Demand concentrates in United States coastal markets where direct-to-consumer brands scale subscription programs requiring unboxing-driven retention.
- Scented Candles:Packaging must integrate vapor barrier properties to preserve fragrance integrity during shelf storage. Soy wax scented lines in California and New York drive FSC-certified substrate requirements ahead of state extended producer responsibility mandates.
- Unscented Candles:Folding carton formats with basic UV coating satisfy functional protection needs at lower unit economics.
- Votive Candles:Multi-count tuck-top boxes with partition inserts predominate for religious and hospitality bulk procurement.
Scented candles lead volumes today; luxury candles are gaining share fastest.
Material:
Cost tier stratification separates premium botanical waxes with certified packaging alignment from commodity paraffin formats where substrate specifications remain minimal.
- Soy Wax:FSC-certified or recycled-content rigid boxes anchor brand sustainability claims. United States mid-market brands are pulling premium paperboard specifications into previously standard-tier product lines to capture clean-label positioning.
- Beeswax:Natural wax positioning triggers FDA food-contact migration testing when botanical oil adjacency creates substrate interaction risk. Specialty converters in California and Texas are building certification service capabilities around this requirement.
- Paraffin Wax:Cost-optimized folding cartons with standard aqueous coating dominate mass retail channels.
- Palm Wax:RSPO certification alignment extends to packaging procurement specifications in European-sourced product lines.
Paraffin wax commands current volume leadership; soy wax is climbing the fastest.
Packaging Type:
Application context determines structural intensity, with retail display formats requiring shelf-ready aesthetics and e-commerce fulfillment prioritizing dimensional weight reduction.
- Glass Jars:Breakage protection mandates premium rigid box specifications with foam or molded pulp inserts. United States specialty retailers specify these formats for luxury candle lines where damage rates directly impact margin.
- Cardboard Boxes:E-commerce fulfillment demands lighter, shippable formats with quick-turn digital print capabilities. Direct-to-consumer brands in coastal United States markets compress order cycles to sub-500 unit minimums.
- Metal Tins:Slipcase or sleeve formats provide secondary branding surface without full rigid box investment.
- Plastic Containers:Minimal outer packaging requirements concentrate in mass retail private label programs.
Glass jars anchor premium value pools; cardboard boxes are expanding most quickly.
Use Case:
Customer type fragmentation splits procurement between recurring subscription models and seasonal gifting surges with divergent inventory risk profiles.
- Gifting:Unboxing aesthetics drive specification authority toward rigid boxes with foil-stamp, ribbon closures, and magnetic lids. United States holiday seasonal demand creates production capacity bottlenecks at specialty converters.
- Home Decor:Permanent display positioning requires shelf-ready packaging with UV coating for lightfastness in retail environments.
- Aromatherapy:Wellness brand positioning aligns with sustainable substrate claims and bio-based coating formulations.
- Religious Ceremonies:Volume procurement through institutional channels prioritizes unit cost over finishing complexity.
Home decor sustains baseline demand; gifting applications show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States candle box procurement outpaces German volume by a factor of three, yet German converters command higher unit values through precision finishing standards that REACH compliance necessitates.
United States
Subscription candle brands in coastal metros compress order cycles to sub-500 unit minimums, forcing quick-turn rigid box production. EPA volatile organic compound regulations on print coatings extend product development timelines by 4-8 months. Specialty converters cluster in California and New York to serve direct-to-consumer startups ahead of state extended producer responsibility mandates.
Germany
Luxury candle exporters require REACH-compliant phthalate-free substrates for EU distribution, elevating bio-based coating specifications. ECHA compliance timelines push converters to validate alternative polymer formulations ahead of regulatory deadlines. Industrial packaging hubs in Bavaria and North Rhine-Westphalia concentrate rigid box engineering talent for premium fragrance brands.
China
E-commerce fulfillment demands from cross-border candle sellers drive cardboard box volume at compressed unit economics. GB standards on packaging material safety shape substrate selection for export-oriented manufacturers. Pearl River Delta converters specialize in digital print workflows that reduce minimum order thresholds for mid-market brands.
United Kingdom
Gifting-oriented candle lines command foil-stamp and emboss finishing for seasonal retail surges. Post-Brexit regulatory divergence from REACH creates dual compliance burdens for exporters serving continental Europe. London and Southeast England host specification-heavy boutique brands that internalize packaging design authority.
France
Luxury heritage candle houses anchor rigid box demand with magnetic closure and ribbon specifications. ANSM oversight of cosmetic-adjacent fragrance products influences packaging material migration testing requirements. Île-de-France converters serve Paris-based prestige brands with shelf-ready UV-coated formats for selective distribution.
Candle Box Market Competitive Environment
United States producers anchor the quick-turn subscription tier; European specialists hold premium finishing capabilities that REACH compliance locks in. The vendor base splits between digital-native converters serving sub-500 unit minimums and legacy folding carton suppliers defending annual contract relationships. Three archetypes dominate: domestic quick-turn rigid box fabricators, REACH-certified European precision finishers, and hybrid digital-analog print specialists. Competitive moves concentrate on geographic expansion into coastal startup clusters and backward integration into coating formulation capabilities.
Among United States-based fabricators, McKenzieCrest Inc., PakFactory, and Elite Custom Box occupy distinct positionings within the tiered structure. McKenzieCrest Inc. represents the domestic manufacturing footprint archetype leveraged for mid-market quick-turn service. PakFactory exemplifies digital workflow-driven competitive positioning that compresses minimum viable order thresholds. Elite Custom Box anchors the luxury-tier vector through foil-stamp rigid box specialization for specialty retail channels.
| Leading Market Players |
|---|
| McKenzieCrest Inc. |
| ICM Custom Packaging |
| BlueBox Packaging |
| ClipnBox |
| Elite Custom Box |
| PakFactory |
| Refine Packaging |
| The Custom Boxes |
| Packlane |
| Others |
Value Chain & Pricing Dynamics
North American softwood pulp futures cascade through candle box pricing tiers, compressing margins on fixed-price annual contracts while spot buyers absorb volatility through quarterly renegotiation clauses. Converter consolidation around aqueous coating suppliers in the United States amplifies cost pass-through power toward mid-market candle brands.
Pricing Analysis
Direct-to-consumer channel margins absorb premium finishing costs that wholesale distributors compress through volume-tiered rebates. Three-tier pricing structure across premium, standard, and economy levels separates foil-stamped rigid boxes from digital-print folding cartons and uncoated commodity formats. Pricing pressure stems from pulp cost volatility squeezing converter margins on legacy contracts. Subscription candle brands exhibit lowest price sensitivity due to unboxing-driven retention economics, while mass retail private labels negotiate aggressively on unit economics.
Supply Chain Analysis
Dual-sourcing mandates from United States direct-to-consumer brands require qualification of at least two coating suppliers to mitigate single-source risk on heat-resistant formulations. Supply concentrates in the United States, Germany, and China, with specialty converters clustering in California and Bavaria for regulatory proximity. Raw material dependencies center on SBS board, aqueous coatings, and bio-based adhesives. Tariff exposure on European-sourced phthalate-free inks creates compliance cost uncertainty. Distribution runs through converter-direct relationships with coastal startup clusters, bypassing traditional broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The candle box market functions as a stable compounder anchored by subscription retention economics that sustain recurring packaging procurement regardless of macroeconomic softness.
For Market Incumbents: Acquire digital print workflow capabilities to defend quick-turn specification authority against emerging hybrid converters. Incumbents must consolidate coating formulation expertise in-house to offset supplier concentration risk. California extended producer responsibility mandates threaten legacy recycling pass-through models; first-mover certification investments will lock in premium brand relationships.
For New Entrants and Emerging Players: The premium-economy price-point gap in mid-market soy wax lines offers white-space entry for FSC-certified rigid box specialists. Target coastal United States subscription clusters where sub-500 unit minimums disintermediate legacy folding carton suppliers. Go-to-market positioning should emphasize closed-loop recyclable systems ahead of state EPR enforcement.
For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid digital-analog print specialists that collapse minimum order thresholds while maintaining foil-stamp quality access. Long-term viability frames around coating chemistry IP and regulatory qualification speed rather than capacity scale. Watch EPA volatile organic compound emission testing timeline compression as inflection signal for product development cycle advantage.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Formulation | Captive aqueous and UV coating supply mitigates EPA compliance timeline risk for United States converters. |
| Digital Print Workflow Deployment | Hybrid inkjet-offset systems enable economic production at sub-500 unit minimums for subscription brands. |
| FSC Certification Investment | Forest Stewardship Council chain-of-custody credentials unlock soy wax brand procurement specifications. |
| California EPR System Development | Closed-loop recyclable rigid box platforms create first-mover advantage under extended producer responsibility law. |
| REACH-Compliant Substrate Qualification | Phthalate-free adhesive validation secures European luxury candle exporter contracts requiring ECHA compliance. |
Study Parameters
Bottom-up candle brand procurement modeling reconciled against top-down paperboard converter capacity tracking forms the analytical core of this study. Primary interviews with packaging procurement managers at direct-to-consumer candle companies, rigid box plant managers in California and New York, coating formulation chemists, and specialty retail buyers combined with secondary validation from EPA emission filings, FDA food-contact guidance documents, Forest Stewardship Council certification databases, and United States Census trade data. Triangulation between demand-side order flow analysis and supply-side equipment utilization rates ensures cross-verified volume estimates.
Historical trendline analysis of SBS board pricing volatility and converter margin compression patterns anchored projection frameworks across the analysis window. Segmentation dimensions modeled include wax chemistry tier, packaging structural intensity, distribution channel archetype, and regional regulatory cluster. CAGRs derived from weighted average of brand procurement growth trajectories and converter capacity expansion plans. Forecast inputs incorporated subscription box shipment velocity and REACH compliance timeline acceleration for European export exposure.
The model assumes a particular technology adoption path; alternative pathways for bio-based coating chemistry would alter the outlook if polymer performance validation timelines compress unexpectedly. Deviation in North American softwood pulp supply disruptions or EPA emission testing backlog accumulation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Self - Locking Trays Market
Packaging Containers
Non-Corrugated Boxes Market
Packaging Containers
Trigger Spray Bottle Market
Packaging Containers
Europe Punnet Trays Market
Packaging Containers
Monobloc Aerosol Cans Market
Packaging Containers
Foldable Mailer Box Market
Packaging Containers
Dosage Cups Market
Packaging Containers
Pump Dispenser Market
Packaging Containers
Cluster Packaging Market
Packaging Containers
Insulated Storage Vessel Market
Packaging Containers
Portion Packs Market
Packaging Containers
Mini Refillable Spray Dispenser Market
Packaging Containers
Logistics Packaging Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Middle East and Africa Aerosol Cans Market
Packaging Containers
Glass Vape Cartridge Market