
 Global Food Re Close Pack Market | 2026-2036
Global Food Re Close Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Re Close Pack Market Intelligence
The development of high-barrier mono-material films is rewriting the rules for recyclability in flexible packaging. This shift allows for re-close functionality without compromising environmental goals. Amcor Ltd. leverages its global R&D scale to lead in this material science innovation. Berry Global Inc. competes on manufacturing efficiency for high-volume applications, while Sonoco Products Co. differentiates with integrated packaging solutions for specific food segments.
Food re-close packs are flexible or semi-rigid containers featuring an integrated mechanism for repeated opening and sealing. These packs, often constructed from multi-layer laminates like PET/PE, maintain product freshness and support portion control. Among product types, stand-up pouches command a significant share due to their shelf presence. Demand for reclosable zipper closures continues to expand, particularly for products in the frozen foods and confectionery end-use categories.
Regulations governing food contact materials, such as those from the US FDA and China's GB standards, set baseline safety requirements. Concurrently, the EU's Packaging and Packaging Waste Regulation (PPWR) pressures manufacturers to design for recyclability and incorporate recycled content. These divergent compliance demands create complexity in global supply chains. Stakeholders must now decide between region-specific material strategies or developing a universally compliant, albeit more costly, packaging portfolio.
Market Dynamics
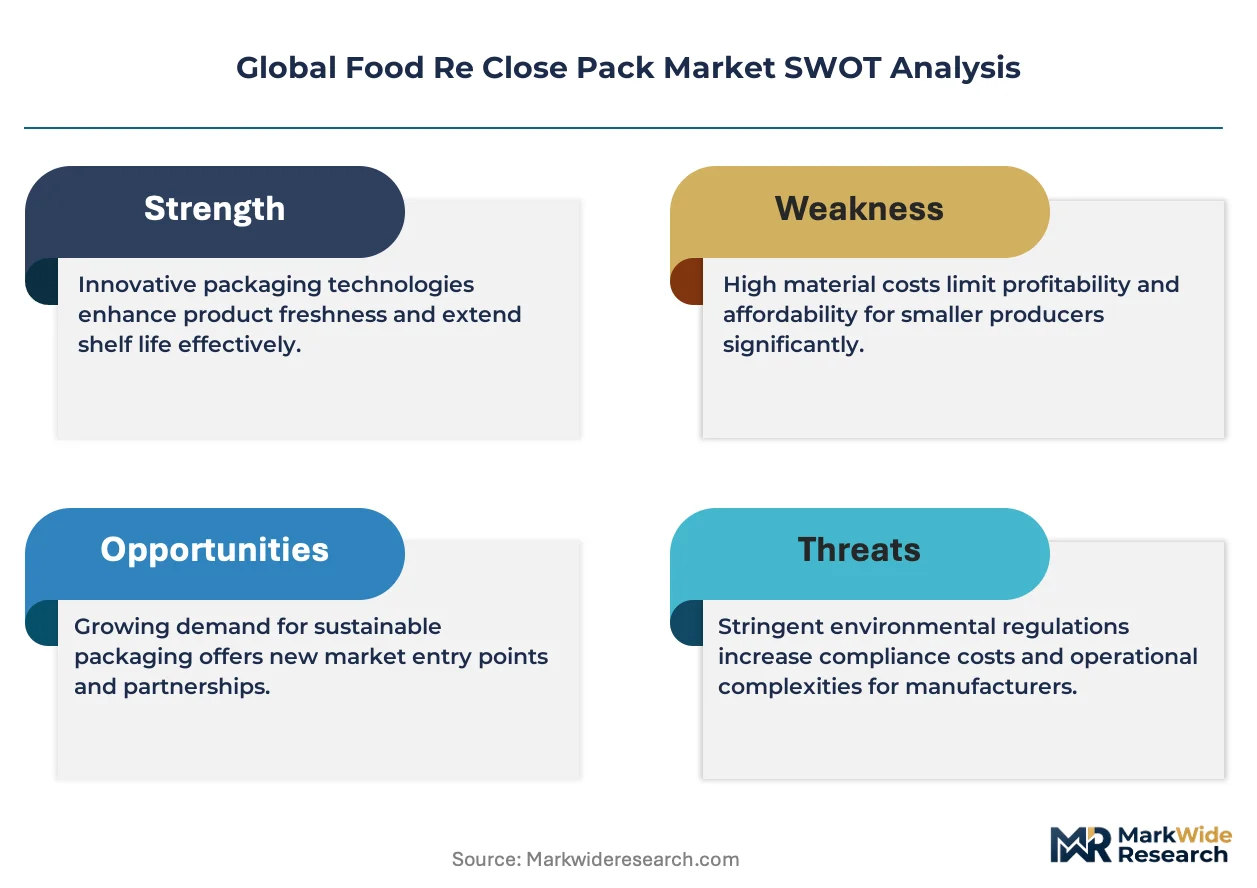
The central dynamic shaping the food re-close pack market is the structural tension between circular economy mandates and food preservation requirements. Regulatory pressures, exemplified by the EU's Packaging and Packaging Waste Regulation, are forcing a rapid shift to mono-materials, while food producers simultaneously demand equivalent or superior barrier performance to extend shelf life and reduce food waste.
Growth Catalysts
- Sustainability Mandates:The EU Green Deal and similar policies are accelerating the transition to mono-material films like PE and PP, which are designed for recyclability and drive investment in compatible re-close technologies.
- Consumer Lifestyle Shifts:Demand for portion control and on-the-go consumption, particularly within the ready meals and snack food segments, elevates the value of integrated re-close features that maintain product freshness over multiple uses.
- Processed Food Industry Expansion:Strong manufacturing bases in countries like Germany and the United States, coupled with high consumer spending on packaged foods, provide a consistent volume base for re-close pack adoption.
Market Restraints
- Cost-Performance Trade-offs:High-barrier mono-material films, while recyclable, often carry a cost premium and can present technical challenges in matching the oxygen and moisture barrier properties of conventional multi-layer laminates.
- Recycling Infrastructure Gaps:The lack of standardized, at-scale collection and sorting systems for flexible packaging in many regions hinders the realization of a circular economy, limiting the environmental benefit of design-for-recycling efforts.
- Regulatory Divergence:Conflicting requirements between regulations like the EU's PPWR, focused on recycled content, and the US FDA's stringent rules for post-consumer recycled materials in food contact applications create compliance complexity.
Strategic Opportunities
- Fresh Produce Applications:There is a significant opportunity to penetrate the fresh produce category, such as for berries and salad greens, where re-close packs can extend freshness, reduce food waste, and improve consumer convenience.
- Emerging Market Penetration:Rapid urbanization and rising disposable incomes in Southeast Asian nations are creating new demand for convenient, shelf-stable packaged foods, representing an underpenetrated market for advanced re-close solutions.
- Integration with Smart Packaging:Combining re-close functionality with digital technologies like QR codes or NFC tags offers a pathway to enhanced consumer engagement, traceability, and authentication for premium food products.
Industry Challenges
- Material Science Expertise:A shortage of polymer scientists and packaging engineers skilled in developing high-performance, recyclable mono-material films creates a bottleneck for innovation and product development across the industry.
- Capital Investment for Re-tooling:Converting existing packaging lines designed for traditional laminates to run newer, more sensitive mono-material films requires significant capital expenditure and can lead to operational downtime during transition.
- Supply Chain Transparency:Verifying the source and composition of recycled content to meet mandates like the PPWR demands a level of supply chain transparency and certification that many converters currently lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Re Close Pack Market |
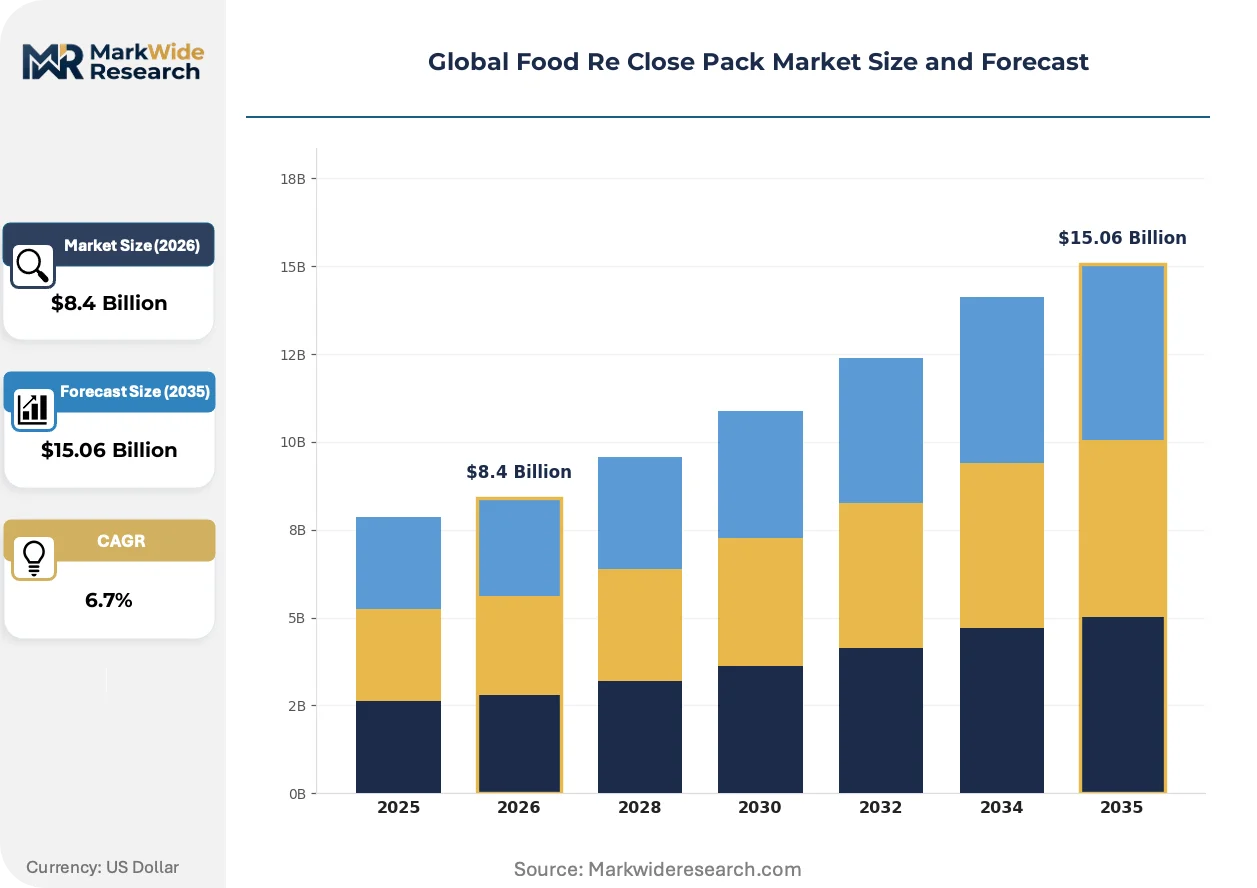
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-up Pouches, Retort Bags, Ziplock Bags, Vacuum Pouches, Spout Pouches, Flat Pouches Closure Type: Reclosable Zipper, Snap-on Cap, Adhesive Tape, Slider Zipper, Press-to-Close Seal, Velcro Closure End Use Industry: Bakery Goods, Confectionery, Frozen Foods, Seafood, Dairy Products, Ready Meals Distribution Channel: Supermarkets, E-commerce Platforms, Specialty Stores, Convenience Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Amcor Ltd., Sonoco Products Co., Bostik (Arkema Group), Avery Dennison Corp., ANL plastics N.V., Coveris, Berry Global Inc., Huhtamaki Oyj, Winpak Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Re Close Pack Market Strategic Shifts & Innovations
Material science innovation is fundamentally altering the value proposition of re-close packaging. The primary focus is on decoupling barrier performance from material complexity, enabling recyclability without compromising the core function of product protection. This shift is creating new competitive dynamics based on polymer and coating expertise.
Advanced coating technology is hybridizing the functionality of mono-material films. These ultra-thin barrier coatings, often silicon oxide or aluminum oxide, are applied to recyclable PE or PP substrates to block oxygen and moisture. Food manufacturers in sensitive categories like cheese and processed meats are rapidly adopting these solutions. This approach is hybridizing the robust barrier properties of multi-layer laminates with the circular economy compliance of single-substrate packaging.
The EU's Packaging and Packaging Waste Regulation (PPWR) is forcing a systemic redesign of flexible packaging. Its mandates for recyclability and minimum recycled content are making non-recyclable multi-material constructions commercially unviable in the European market. The frozen foods and confectionery segments are most affected, now prioritizing investments in mono-material pouches with compatible re-close zippers or labels to ensure future market access.
Consumer demand for product visibility is altering package design and material selection. Shoppers increasingly prefer transparent packaging to visually assess the quality and freshness of contents like nuts, dried fruits, and salads. This trend is disrupting the dominance of opaque, fully printed pouches, pushing brands toward formats with large, clear windows or entirely transparent structures. This shift is most pronounced in North American and Western European retail channels.
Global Food Re Close Pack Market Segmentation
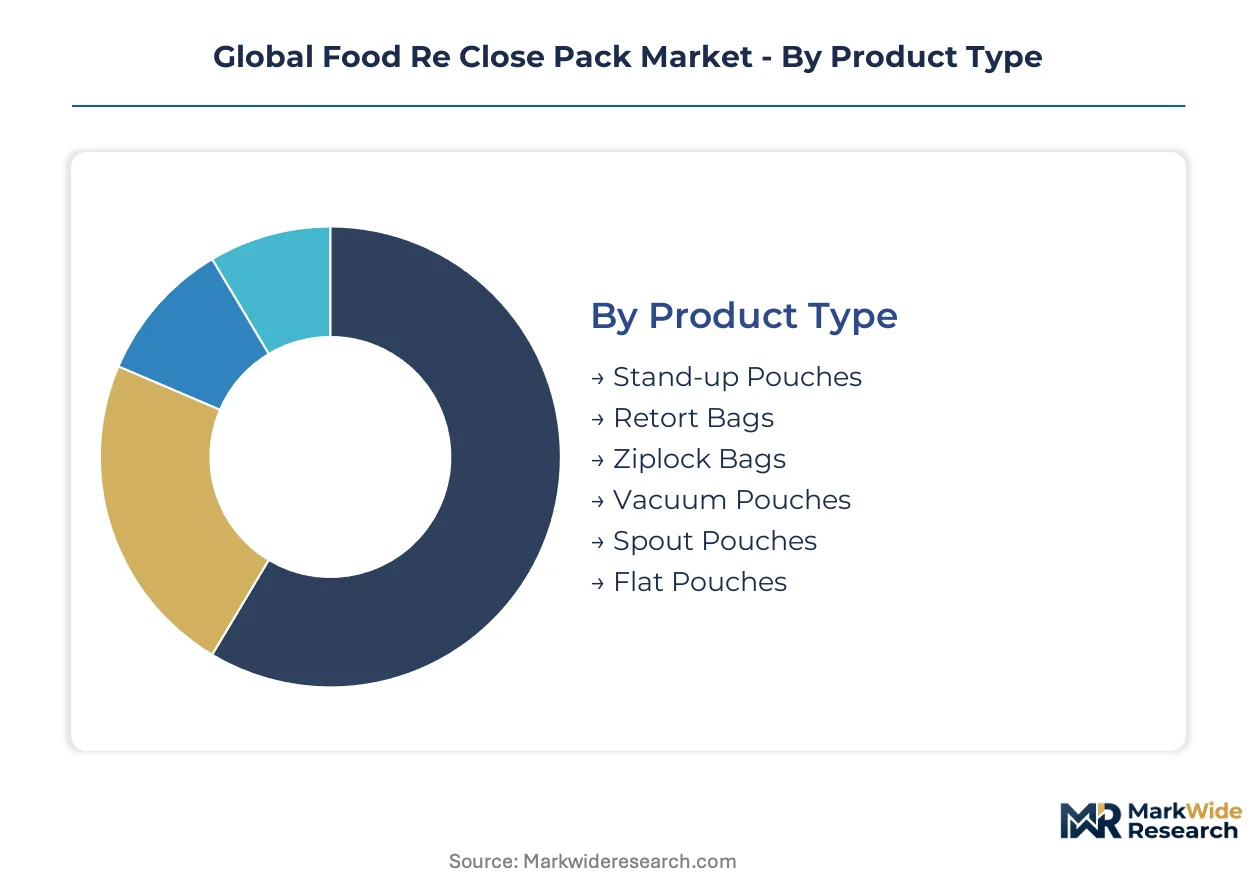
Segmentation of the global food re-close pack market reveals distinct opportunities and challenges across various product forms, closure mechanisms, and end-use applications. Understanding these segments is critical for manufacturers to align product development with evolving consumer preferences for convenience and sustainability. Strategic targeting of specific channels also optimizes market penetration.
Product Type:
The spectrum of product types for food re-close packs addresses diverse preservation and presentation needs across the food industry.
- Stand-up Pouches:These flexible containers feature a flat base, allowing them to stand upright for prominent shelf display and consumer convenience. Demand concentrates in snack foods and pet food, driven by their visual appeal and portion control benefits.
- Ziplock Bags:Featuring an integrated, press-to-close plastic zipper, these bags offer straightforward re-sealability for various dry goods. Adoption is widespread for cereals and dried fruits, supported by their cost-effectiveness and ease of use in households.
- Retort Bags:These heat-resistant, flexible pouches allow for in-pack sterilization, extending shelf life for ready-to-eat meals and pet food.
- Vacuum Pouches:Designed to remove air, these pouches extend the freshness of perishable items like processed meats and cheeses by inhibiting bacterial growth.
- Spout Pouches:Equipped with a pouring spout and cap, these pouches are ideal for liquid or semi-liquid products, enhancing convenience for sauces and baby food.
- Flat Pouches:Simple, two-dimensional pouches are used for single-serve portions or small items, offering basic protection and compact storage.
Established volume favors Ziplock Bags; emerging adoption favors Spout Pouches.
Closure Type:
Cost tier considerations significantly influence the selection of closure mechanisms for various food applications.
- Reclosable Zipper:This ubiquitous closure system allows for repeated opening and sealing, maintaining product freshness and preventing spillage. Its versatility makes it a preferred choice for confectionery and frozen food products across North America.
- Slider Zipper:A more robust and user-friendly variant, the slider zipper employs a small plastic tab that glides along the track, offering superior sealing and ease of operation. Premium snack brands in Germany increasingly adopt this closure for enhanced consumer experience.
- Snap-on Cap:Primarily used on semi-rigid containers, this cap provides a secure, audible seal for products like dairy tubs and deli containers.
- Adhesive Tape:Often found on bakery items, this closure offers a temporary re-seal, providing basic freshness protection for a short duration.
- Press-to-Close Seal:This simple, integrated seal requires pressure to close, commonly seen on flexible bags for dry goods and cereals.
- Velcro Closure:Utilizing hook-and-loop technology, this closure offers a durable and easy-to-use re-seal for bulkier or frequently accessed items.
Growth is concentrated in Reclosable Zipper due to its versatility, while Slider Zipper is gaining traction for enhanced user convenience.
End Use Industry:
The application landscape for food re-close packaging spans a wide array of food categories, each with unique preservation demands.
- Ready Meals:Re-close packs for ready meals provide convenience and portion control, allowing consumers to consume part of the meal and store the rest. The segment's expansion in the United States drives innovation in microwave-safe and easy-open formats.
- Frozen Foods:These products require packaging that withstands low temperatures and prevents freezer burn, while re-close features enable multi-serving use. Consumer demand for frozen vegetables and fruits in Europe elevates the need for robust re-sealable solutions.
- Bakery Goods:Re-close packaging helps maintain the freshness and texture of baked items, preventing them from drying out or becoming stale.
- Confectionery:For candies and chocolates, re-close packs offer portion control and protect against moisture and aroma loss, extending shelf life.
- Seafood:Re-close solutions for seafood prevent odor transfer and maintain freshness, crucial for both raw and cooked products.
- Dairy Products:Packaging for dairy items benefits from re-close features to preserve freshness and prevent spoilage after initial opening.
Demand for re-close solutions is particularly pronounced in Ready Meals, with Frozen Foods showing considerable expansion.
Distribution Channel:
Volume considerations dictate the primary distribution channels for food re-close packs, connecting producers to end consumers.
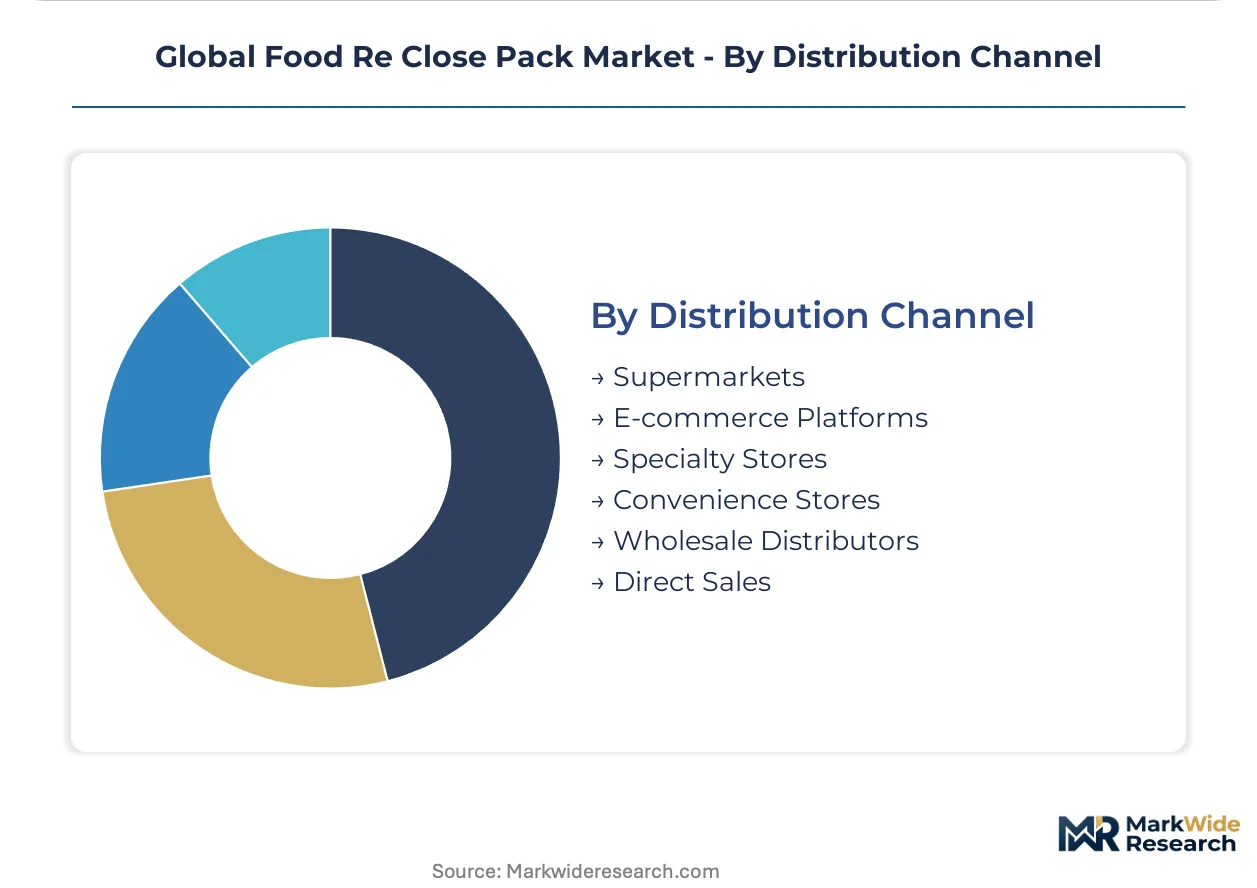
- Supermarkets:These large retail outlets represent the primary sales channel for a vast array of packaged food products, including re-close packs. Their extensive reach and consumer foot traffic ensure high volume sales across all food categories.
- E-commerce Platforms:Online retail channels are experiencing significant growth, driven by consumer demand for home delivery and convenience. This channel necessitates durable packaging that withstands shipping and maintains product integrity upon arrival.
- Specialty Stores:These outlets focus on niche products or gourmet items, often featuring premium re-close packaging that aligns with brand image.
- Convenience Stores:Catering to immediate consumption needs, these stores stock smaller, single-serve re-close packs for snacks and beverages.
- Wholesale Distributors:These entities supply bulk quantities of re-close packaging to businesses, including food manufacturers and foodservice providers.
- Direct Sales:Some brands utilize direct-to-consumer models, leveraging their own websites or subscription services for product distribution.
The largest volume flows through Supermarkets, with E-commerce Platforms experiencing significant channel diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global demand for food re-close packs concentrates in regions with advanced processed food industries and high consumer convenience preferences. Germany, with its extensive manufacturing base, and the United States, driven by ready meals, represent significant buyer archetypes. Emerging markets like China and India are also rapidly adopting these packaging solutions.
Germany
Demand in Germany stems from its extensive processed food manufacturing and strong consumer preference for portion-controlled packaging. The EU's Packaging and Packaging Waste Regulation (PPWR) pressures manufacturers for recyclability and recycled content. North Rhine-Westphalia, a major food processing hub, actively pursues mono-material packaging innovations.
United States
The United States market is propelled by the expansion of the ready meals segment and high consumer spending on packaged foods. US FDA regulations govern food contact materials, influencing the adoption of post-consumer recycled content. California's food processing industry drives demand for convenient and fresh-keeping re-close solutions.
China
China's market expansion is fueled by rapid urbanization and rising disposable incomes, creating demand for convenient, shelf-stable packaged foods. China's GB standards set baseline safety requirements for all food contact materials. The Yangtze River Delta region, a key food production and packaging hub, sees significant re-close pack adoption.
India
Rising disposable incomes and evolving consumer lifestyles in India increase the need for convenient, shelf-stable food packaging. The Food Safety and Standards Authority of India (FSSAI) oversees packaging material compliance. Maharashtra, a major center for food processing and FMCG, experiences substantial growth in re-close pack usage.
France
Consumer demand for fresh produce applications and convenience drives the French market for re-close packaging. European Green Deal directives promote sustainable packaging choices and waste reduction across the country. Brittany, known for its agro-food sector, is a focal point for advanced re-close packaging development.
Global Food Re Close Pack Market Key Industry Players
Channel-controlling players compete with product-specialist players across the food re-close pack market, which exhibits a tiered structure based on technological capability and scale. Global innovators leverage extensive R&D to lead in material science, developing advanced mono-materials for recyclability. High-volume manufacturers focus on operational efficiency and cost-effectiveness for broad market penetration. Integrated packaging solution providers differentiate by offering tailored solutions for specific food segments. Portfolio diversification and strategic partnerships are dominant competitive moves.
Global innovators such as Amcor Ltd. exemplify leadership in material science, particularly with the development of high-barrier mono-material films designed for enhanced recyclability. Berry Global Inc. occupies a significant position among high-volume manufacturers, consistently competing on manufacturing efficiency to serve widespread applications across various food categories. Sonoco Products Co. represents integrated packaging solution providers, offering specialized and comprehensive packaging for specific food segments to effectively differentiate its market presence and value proposition.
| Leading Market Players |
|---|
| Amcor Ltd. |
| Sonoco Products Co. |
| Bostik (Arkema Group) |
| Avery Dennison Corp. |
| ANL plastics N.V. |
| Coveris |
| Berry Global Inc. |
| Huhtamaki Oyj |
| Winpak Ltd. |
Cost & Logistics Intelligence
Trans-Atlantic shipping lanes face increasing cost dynamics, directly influencing the supply concentration of specialized polymer resins and impacting downstream price differentiation for advanced re-close packaging solutions. This cost pressure drives manufacturers to optimize material sourcing and production locations.
Pricing Analysis
Cost-plus contract patterns, often indexed to polymer resin and energy costs, govern a significant portion of re-close pack pricing. Price differentiation stems from material innovation, particularly high-barrier mono-material films, and the level of customization required for specific food applications. Pricing pressure intensifies due to the cost premium associated with recyclable mono-materials and stringent regulatory compliance in regions like the EU. Small-to-mid-sized food producers exhibit the highest price sensitivity, while large multinational food corporations prioritize regulatory alignment and performance over minimal cost savings.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are increasingly common, supporting working capital management for material converters and packaging producers. Geographic supply for food re-close packs concentrates in major manufacturing hubs such as Germany, China, and the United States. The supply chain relies heavily on polymer resins like polyethylene (PE) and polypropylene (PP), along with specialized barrier coatings and adhesives. Raw material price volatility represents a significant structural risk for the industry. Distribution runs primarily through wholesale distributors, who then supply food manufacturers, eventually reaching consumers via supermarkets and e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, as consumer lifestyle shifts toward portion control and on-the-go consumption create numerous niches for specialized re-close formats.
For Market Incumbents: Entrench leadership by investing heavily in R&D for next-generation high-barrier mono-materials. Consolidate market share through strategic acquisitions of smaller, innovative material science firms. This proactive stance mitigates the threat posed by regulatory-driven material shifts and the cost-performance trade-offs of emerging solutions. Leverage existing global production capacity for efficient scale-up of compliant packaging solutions across diverse geographies.
For New Entrants and Emerging Players: Southeast Asian nations represent a geographic underpenetration for advanced re-close packaging solutions. Target the fresh produce category, offering sustainable, shelf-life extending re-close packs for berries and salad greens. A go-to-market strategy focused on sustainability certifications and convenience features will resonate with environmentally conscious consumers and retailers. Focus on flexible mono-material stand-up pouches with integrated re-close zippers.
For Investors and Strategic Acquirers: Carve-out targets emerge from non-core packaging divisions of large chemical or diversified material conglomerates seeking to streamline operations. The long-term viability of re-close packaging remains strong, driven by convenience and sustainability mandates over the next decade. Identify acquisition targets with proven expertise in high-barrier mono-material film production or advanced re-close closure technologies. The signal to watch is the widespread uptake of standardized mono-material solutions by major food brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Mono-Material R&D | Develops sustainable packaging solutions to meet EU PPWR mandates and consumer demand for recyclability. |
| Expand Fresh Produce Applications | Captures new market share by extending shelf life and enhancing convenience for perishable items. |
| Standardize Recyclable Zipper Technology | Facilitates broader adoption of mono-material pouches across frozen foods and confectionery segments. |
| Acquire Coating Technology Specialists | Strengthens barrier performance of mono-materials, matching multi-layer laminate capabilities. |
| Develop Smart Packaging Integration | Enhances consumer engagement and product traceability for premium food products. |
Research Approach
Findings reconcile primary fieldwork against secondary review of government regulatory documents, industry association reports, and public company financial filings. This approach incorporates insights from packaging engineers, food manufacturers, material suppliers, and retail buyers. The methodology employs both bottom-up and top-down triangulation to ensure robust data validation and market sizing accuracy.
The forecast inputs considered include polymer resin pricing trends, regulatory adoption timelines, and consumer preference shifts for convenience. The analytical framework projects market trajectories across the analysis window, segmenting by product type, closure mechanism, end-use industry, and geographic region. Compound annual growth rates are derived from historical data analysis and projected market dynamics, incorporating processed food production volumes as a key input.
The forecast holds incumbent behavior within observed patterns; aggressive moves by major CPGs or material science innovators would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and technological progression. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Logistics Packaging Market
Packaging Containers
Candle Box Market
Packaging Containers
VCI Bags Market
Packaging Containers
Thermoform Cups Market
Packaging Containers
Euro Box Market
Packaging Containers
Self - Locking Trays Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Food Portion Pack Market
Packaging Containers
Sanitizer Bottles Market
Packaging Containers
Packing Boxes Market
Packaging Containers
Portion Packs Market
Packaging Containers
Foldable Mailer Box Market
Packaging Containers
Membrane Boxes Market
Packaging Containers
Global Acrylic Airless Bottle Market
Packaging Containers
Latin America Aerosol Cans Market
Packaging Containers
Hinged Food Containers Market