
 Packing Boxes Market | 2026-2036
Packing Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Packing Boxes Market Analytics
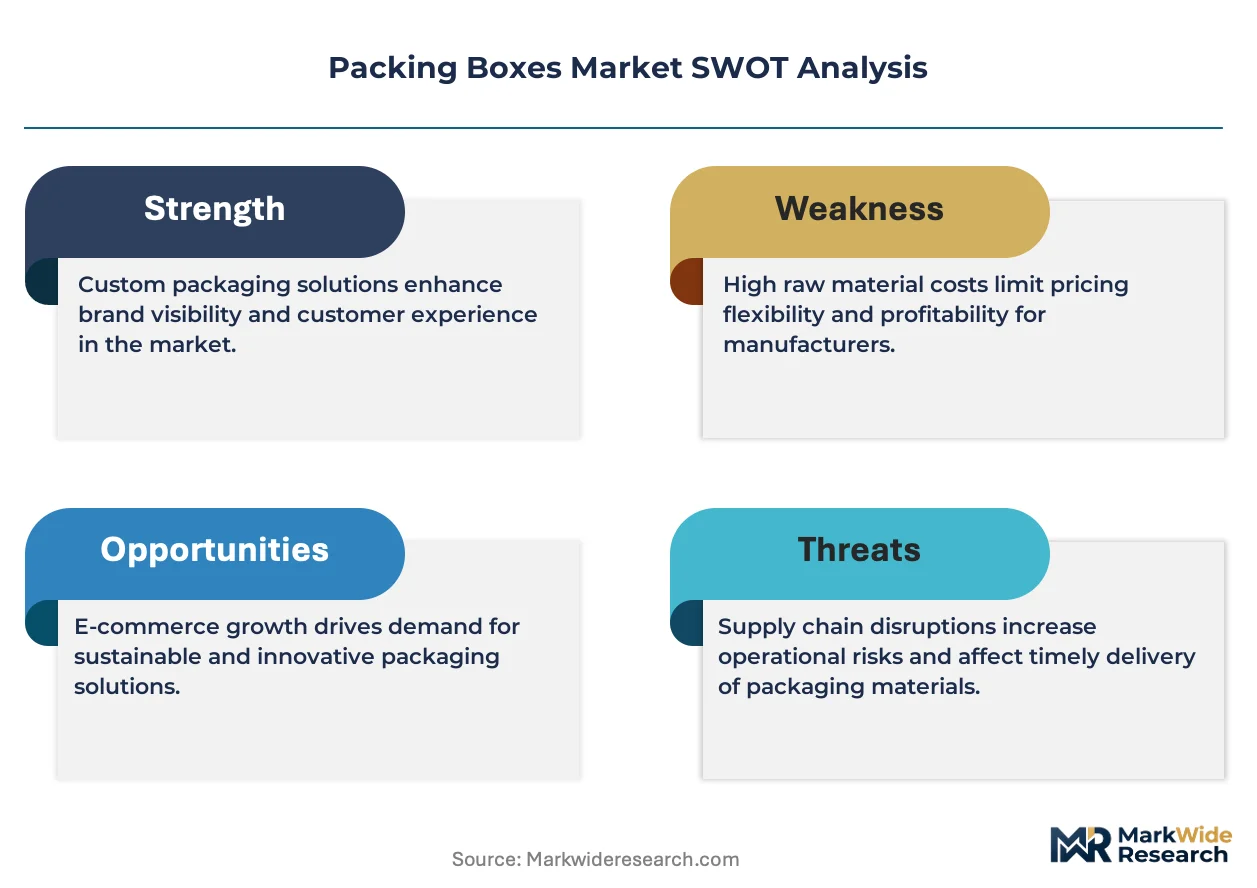
Buyer concentration in e-commerce fulfillment is decoupling from traditional retail procurement patterns as direct-to-consumer channels fragment order volumes across smaller, more frequent shipments. International Paper leverages its North American mill network to sustain integrated containerboard supply. WestRock anchors its position through specialty packaging grades that differentiate performance for fragile goods transit.
Packing boxes are structural enclosures manufactured from corrugated fiberboard, solid fiber, or alternative substrates, engineered to specific burst strength and edge crush test specifications for load-bearing protection during distribution. Their primary commercial purpose centers on unitizing, protecting, and identifying goods through supply chain handling. Cardboard material type leads volume due to cost-efficient recycling loops, while rigid box style commands premium positioning in electronics and luxury retail where unboxing experience shapes brand perception. E-commerce end user segment exhibits the fastest structural expansion as last-mile durability requirements intensify.
The EPA regulates corrugated medium emissions under Clean Air Act standards, while OSHA enforces workplace safety in converting facilities; together these frameworks elevate capital requirements for domestic producers. The EU Packaging and Packaging Waste Regulation extends producer responsibility mandates across European markets, reshaping material recovery obligations. Stakeholders must monitor recycled content thresholds and extended producer responsibility expansions as compliance costs redirect investment toward circular design capabilities.
Market Dynamics
E-commerce fulfillment networks are fragmenting order volumes into smaller, more frequent shipments that demand corrugated solutions with enhanced last-mile durability specifications.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are accelerating investment in circular design capabilities and material recovery infrastructure across European markets.
- China manufacturing clusters:Export logistics hubs in Guangdong and Zhejiang provinces require sustained high-volume box supply for cross-border e-commerce fulfillment.
- Recycled fiber processing:Closed-loop recycling systems for corrugated medium are reducing virgin pulp dependency and aligning procurement with sustainability commitments.
Market Restraints
- Recovered paper price volatility:OCC (old corrugated containers) input costs fluctuate with municipal collection rates and export demand from Asian mills.
- Containerboard mill concentration:North American integrated producers control a disproportionate share of linerboard supply, creating bottleneck risk during demand spikes.
- Lightweighting limits:Edge crush test specifications impose floor thresholds below which further material reduction compromises load-bearing performance.
Strategic Opportunities
- India e-commerce penetration:Underdeveloped cold chain and fragile goods logistics create demand for specialized protective packaging grades.
- Smart packaging convergence:Integration of RFID tracking and temperature sensors with corrugated substrates enables premium positioning in pharmaceutical distribution.
- US IRA clean manufacturing incentives:Tax credits for energy-efficient converting equipment are lowering barrier to entry for regional box plants.
Industry Challenges
- Die-cutting automation expertise:Shortage of technicians skilled in servo-driven rotary die systems limits throughput optimization at mid-scale converters.
- EPR compliance timelines:EU member state implementation variations create certification complexity for pan-European suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packing Boxes Market |
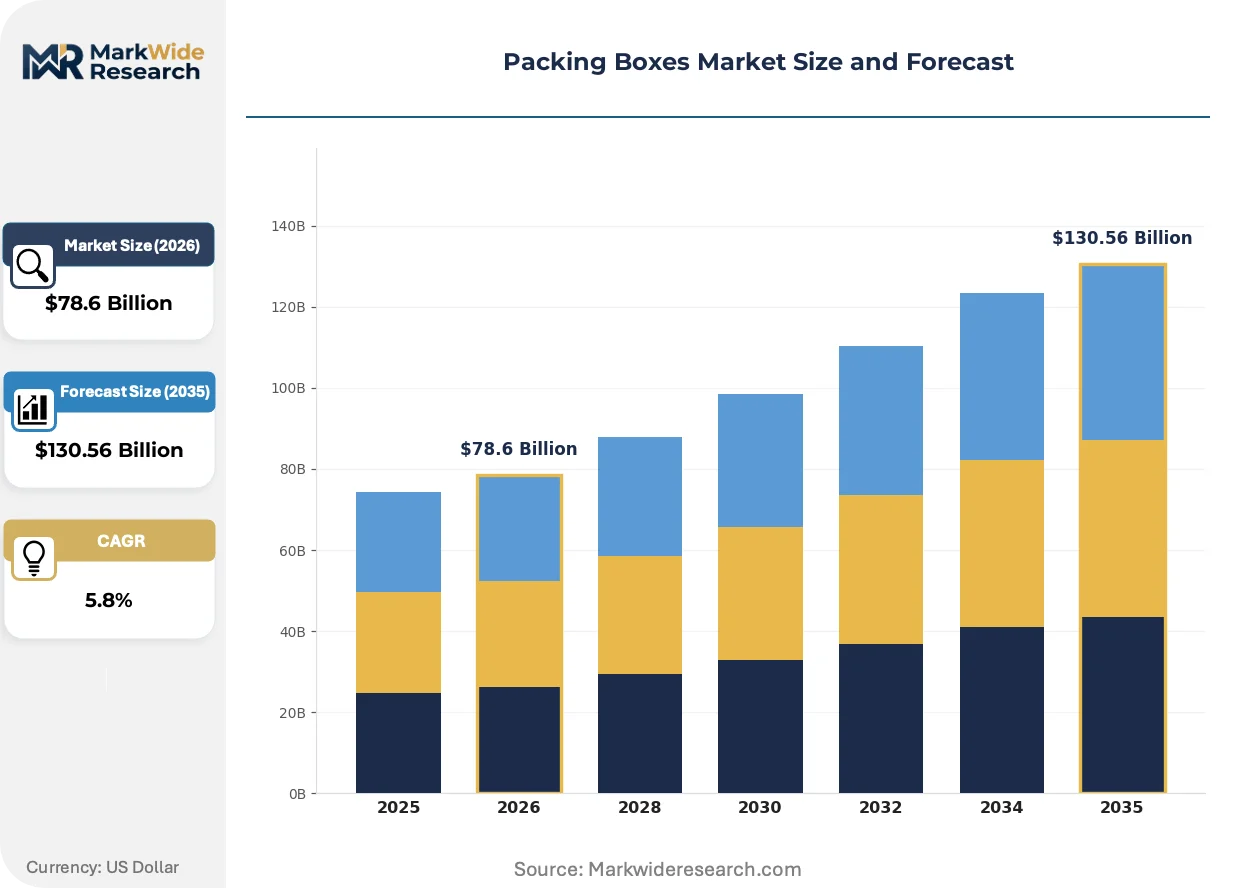
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $130.56 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cardboard, Plastic, Wood, Metal Box Style: Folding, Rigid, Sliding, Telescope End User: Retail, E-commerce, Food & Beverage, Electronics Size: Small, Medium, Large, Custom |
| Companies Covered | International Paper, WestRock, DS Smith, Smurfit Kappa Group, Packaging Corporation of America, Mondi Group, Rengo Co. Ltd, Nine Dragons Paper, Oji Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packing Boxes Market Evolving Landscape
Digital printing and automation are compressing production lead times while regulatory mandates force material composition changes across supply chains.
Water-based flexographic printing with high-definition photopolymer plates is overtaking traditional litho-lamination for short-run branded packaging. E-commerce sellers with SKU proliferation needs are adopting this technology within 12-18 month equipment payback windows. The shift is overtaking the economic advantage of centralized large-run printing and enabling distributed manufacturing closer to fulfillment centers.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating oil and grease resistant coatings from food-contact corrugated applications. EU-based converters must reformulate barrier treatments or exit the fresh produce and prepared foods segments. German and French packaging suppliers are accelerating migration to bio-based wax alternatives and clay-coated liners to maintain category participation.
Subscription box merchants are consolidating supplier relationships around vertically integrated converters offering design-to-delivery service bundles. Direct-to-consumer brands in cosmetics and specialty foods are replacing transactional box purchasing with annual partnership agreements that embed structural engineering support. This pattern concentrates procurement volume most visibly in California and New York metro logistics corridors where same-day fulfillment requirements dominate.
Packing Boxes Market Segmentation
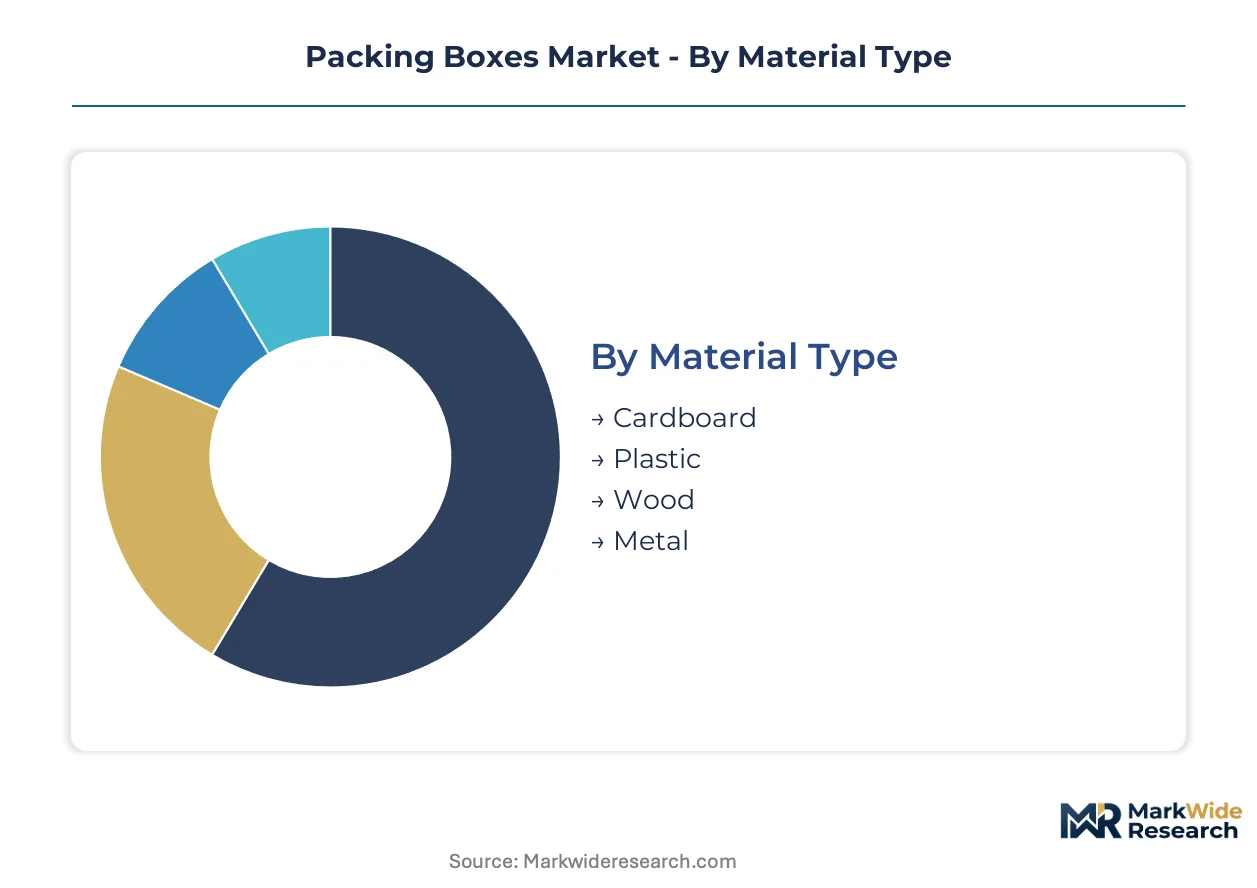
Packing boxes serve divergent functional requirements across material grades, structural formats, and end-use specifications. Segmentation reveals how procurement patterns split between commodity volume plays and specialized performance premiums.
Material Type:
Customization intensity varies sharply across this category, from standardized recycled fiber streams to engineered substrate combinations demanding precise barrier specifications.
- Cardboard:Corrugated fiberboard constructed from fluted medium sandwiched between linerboard faces dominates commercial volume. E-commerce fulfillment networks in China and the United States absorb the majority of output as last-mile durability specifications intensify for cross-border shipments.
- Plastic:Polypropylene and polyethylene terephthalate formulations deliver moisture resistance and reusability for cold chain logistics. Food & Beverage distributors in Europe favor this material as EU Packaging and Packaging Waste Regulation tightens recyclability mandates for multi-use containers.
- Wood:Plywood and oriented strand board crates serve heavy machinery and industrial equipment transit with ISPM-15 heat treatment compliance for international phytosanitary requirements.
- Metal:Steel and aluminum enclosures protect high-value electronics and aerospace components through extended supply chain exposure to extreme handling conditions.
Leading the category by volume: Cardboard. Expanding most quickly: Plastic.
Box Style:
Structural complexity correlates directly with margin capture, separating commodity folding cartons from value-added rigid formats requiring specialized converting equipment.
- Folding:Single-piece die-cut blanks that ship flat and erect at point of use minimize freight cube and storage footprint. Retail replenishment operations in Germany and Japan standardize on this format for high-velocity consumer goods distribution.
- Rigid:Set-up boxes with thick paperboard walls and wrapped exterior finishes command premium positioning. Electronics manufacturers in South Korea and luxury cosmetics brands in France specify this style where unboxing experience shapes brand perception and repeat purchase rates.
- Sliding:Matchbox-style construction with sleeve and tray components enables compartmentalized presentation for gift sets and limited-edition product releases.
- Telescope:Two-piece designs with separate lid and base sections accommodate variable content heights for irregular-shaped merchandise in artisanal food and specialty retail segments.
Highest volume concentration: Folding. Steepest expansion trajectory: Rigid.
End User:
Procurement scale and specification intensity diverge across customer types, from fragmented SKU proliferation in digital commerce to consolidated contract structures in brick-and-mortar retail.
- Retail:Big-box and specialty store chains procure standardized case packs through annual bidding cycles with strict cube efficiency requirements. Walmart and Target distribution centers in Texas and Illinois drive specifications for pallet-compatible master cartons.
- E-commerce:Direct-to-consumer fulfillment demands smaller, more frequent shipments with enhanced individual parcel durability. Amazon and Shopify merchants in California and New York metro corridors are consolidating supplier relationships around design-to-delivery service bundles.
- Food & Beverage:Temperature-sensitive and contamination-critical applications require barrier coatings and sanitary design compliance with FDA and EFSA contact material standards.
- Electronics:Anti-static and shock-absorbing specifications protect semiconductors and consumer devices through multi-modal international transit from Shenzhen and Seoul manufacturing clusters.
Dominant procurement volume: Retail. Gaining share fastest: E-commerce.
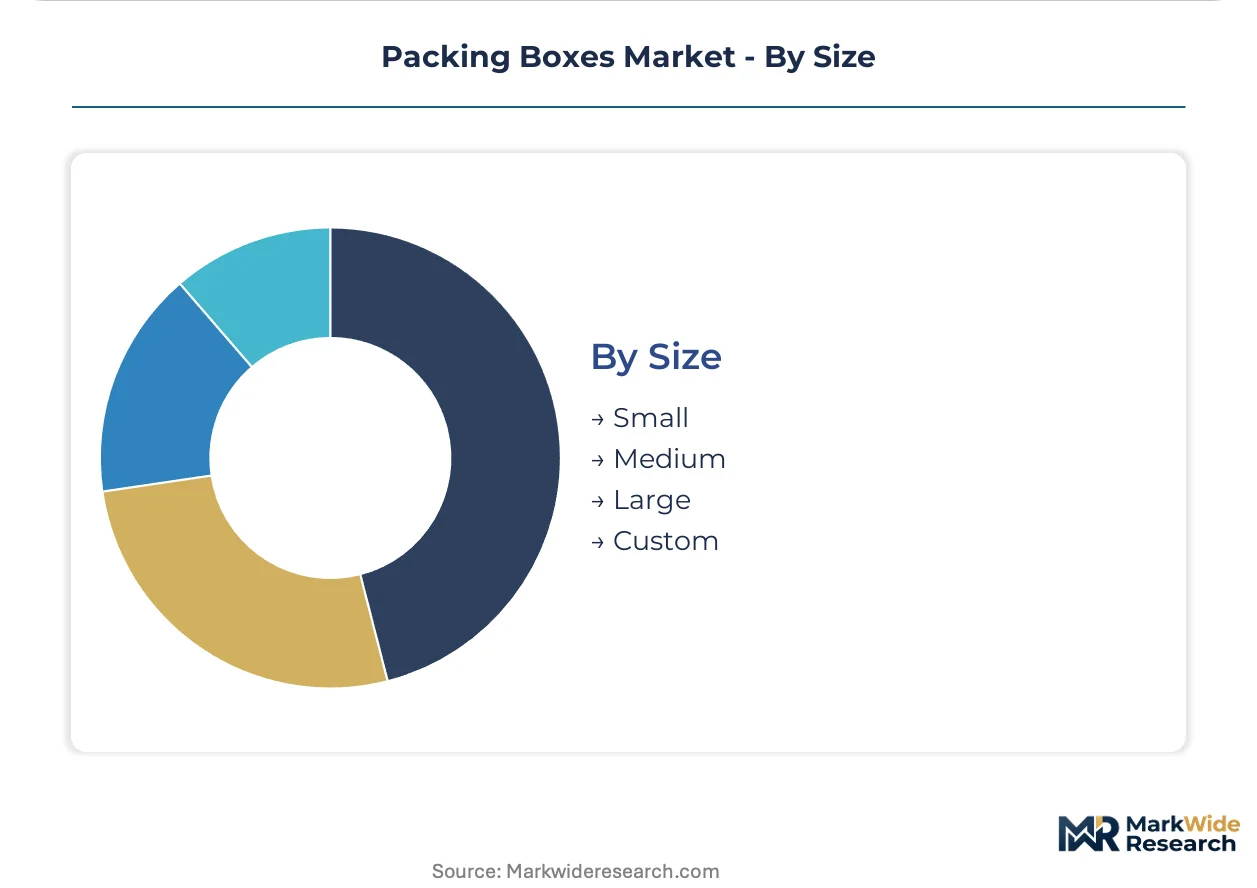
Size:
Dimensional standardization enables supply chain interoperability while custom formats capture margin from non-cuboidal merchandise requirements.
- Small:Dimensions under 12 inches on longest edge accommodate jewelry, cosmetics, and consumer electronics accessories. Subscription box merchants in cosmetics and specialty foods specify this format for mailbox compatibility and unboxing presentation.
- Medium:12-24 inch range captures the majority of apparel, footwear, and home goods shipments through parcel carrier networks with dimensional weight pricing breakpoints.
- Large:Exceeding 24 inches, these formats serve furniture, appliances, and bulk industrial components requiring mechanical handling equipment and specialized last-mile delivery fleets.
- Custom:Non-standard dimensions engineered to specific product geometry minimize void fill requirements and dimensional weight charges for irregular-shaped merchandise.
Highest shipment frequency: Medium. Climbing fastest: Custom.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the largest share of packing box procurement as manufacturing clusters and export logistics networks require sustained high-volume corrugated supply. Regional variations in regulatory stringency and e-commerce penetration create divergent growth trajectories across major economies.
United States
Amazon and Walmart fulfillment networks in Texas and Illinois drive specifications for pallet-compatible master cartons with enhanced last-mile durability. EPA Clean Air Act standards regulate corrugated medium emissions, elevating capital requirements for domestic converters. California and New York metro corridors concentrate design-to-delivery service bundles for direct-to-consumer brands.
China
Guangdong and Zhejiang province export logistics hubs require sustained high-volume box supply for cross-border e-commerce fulfillment. MEE dual carbon goals pressure mills to reduce energy intensity in linerboard production. Shenzhen manufacturing clusters generate demand for anti-static and shock-absorbing specifications protecting semiconductors through international transit.
Germany
Retail replenishment operations standardize on folding carton formats for high-velocity consumer goods distribution through automated warehouses. EU Packaging and Packaging Waste Regulation extends producer responsibility mandates, reshaping material recovery obligations. Bavaria and North Rhine-Westphalia host vertically integrated converters accelerating migration to bio-based wax alternatives.
India
Underdeveloped cold chain and fragile goods logistics create demand for specialized protective packaging grades as e-commerce penetration accelerates. FSSAI contact material standards govern food-grade barrier coatings for temperature-sensitive applications. Maharashtra and Gujarat manufacturing corridors attract regional box plant investment supported by PLI scheme incentives.
Japan
Electronics manufacturers in South Korea and luxury cosmetics brands source rigid set-up boxes where unboxing experience shapes brand perception. METI efficiency standards drive automation adoption in converting facilities. Kanto and Kansai industrial belts concentrate high-definition flexographic printing capacity for short-run branded packaging.
Packing Boxes Market Competitive Landscape
North American integrated producers anchor one tier; Asian specialty converters hold differentiated positions in barrier-coated and rigid formats. Containerboard mill concentration creates bottleneck risk during demand spikes, while mid-scale converters face throughput constraints from die-cutting automation expertise shortages. Three archetypes dominate: vertically integrated giants with captive pulp supply, regional specialists in premium grades, and agile short-run digital printers. Competitive moves center on M&A for geographic footprint expansion and strategic partnerships embedding design services into annual procurement agreements.
Among North American integrated producers, International Paper and WestRock exemplify scale-driven archetypes with mill network control. DS Smith represents the European specialist tier navigating EPR compliance complexity. These three occupy positions that illustrate how geographic origin and corporate structure map to strategic options: the US-based corporations leverage fiber supply security, while the UK-listed firm aligns with circular design capability investment cycles.
| Leading Market Players |
|---|
| International Paper |
| WestRock |
| DS Smith |
| Smurfit Kappa Group |
| Packaging Corporation of America |
| Mondi Group |
| Rengo Co. Ltd |
| Nine Dragons Paper |
| Oji Holdings Corporation |
| Others |
Value Network & Pricing Analysis
EU Packaging and Packaging Waste Regulation recyclability thresholds gate qualified supply for premium-tier corrugated contracts, forcing converters to absorb certification costs or surrender margin to commodity spot markets. Buyers with sustainability mandates now pay structural premiums for verified recycled content, while uncertified producers face exclusion from European e-commerce fulfillment networks.
Pricing Analysis
Volume-margin splits separate integrated mill operators from regional converters. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume commitment scale. Price differentiation hinges on EU EPR compliance status and captive fiber supply security. Cost compression in standard-grade folding cartons is intensifying because Asian export demand for OCC scrap tightens recovered fiber availability. Small-batch e-commerce merchants exhibit highest price sensitivity; pharmaceutical cold-chain distributors show least.
Supply Chain Analysis
Single-source vulnerability sits with North American integrated producers controlling linerboard supply through concentrated mill networks. Production gravity centers on the United States, China, and Germany. Raw material flows draw from OCC collection streams, virgin kraft pulp, and bio-based barrier coatings. Tariff exposure on Canadian softwood pulp imports threatens cost stability at US East Coast converters. Distribution runs through direct mill relationships for volume accounts and regional converter networks for short-run fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Containerboard mill concentration creates structural supply constraint that props pricing power for integrated producers. Qualified converter capacity bottlenecks limit rapid supply response to demand spikes.
For Market Incumbents: Cement fiber supply security through backward integration into recovered paper collection infrastructure. Lock in multi-year offtake agreements with Guangdong and Zhejiang export logistics hubs before regional competitors capture e-commerce volume. Defend against specialty converter encroachment by embedding structural engineering services into annual procurement contracts. For New Entrants and Emerging Players: Subscription box merchants in California and New York metro corridors represent underserved buyers seeking design-to-delivery bundles. Penetrate this segment through digital printing capability paired with same-day fulfillment proximity. Cold chain logistics for Indian specialty foods offers white-space expansion with FSSAI barrier coating compliance as entry credential. For Investors and Strategic Acquirers: DS Smith's circular design capability investment cycle completion is the leading indicator that European EPR compliance complexity will consolidate procurement volume toward certified converters. Five-to-ten year viability favors specialists with captive recycling infrastructure and pharmaceutical cold-chain certification. Watch for German and French packaging supplier M&A activity as REACH barrier reformulation deadlines approach.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Fiber Collection | Captive OCC supply insulates against Asian export demand spikes and price volatility. |
| Digital Printing Capability Expansion | Short-run flexographic capacity captures SKU-proliferating e-commerce merchant demand in California corridors. |
| EPR Compliance Certification Investment | EU Packaging and Packaging Waste Regulation alignment unlocks premium-tier European retail contracts. |
| Design-to-Delivery Service Bundling | Annual partnership agreements with cosmetics and specialty food brands concentrate procurement volume. |
| Bio-Based Barrier Coating Migration | REACH-compliant wax alternatives preserve food-contact corrugated participation in German and French markets. |
Research Methodology
Document review covered SEC 10-K filings from integrated producers, EU regulatory impact assessments, and trade flow data from customs authorities, complemented by interviews with corrugated plant managers, e-commerce fulfillment procurement leads, and sustainability compliance officers at consumer goods brands. Secondary validation drew from EPA emissions databases, ECHA REACH substance restrictions, and OCC price indices. Bottom-up volume estimates triangulated against top-down macroeconomic consumption models.
Cross-referencing historical linerboard production trends against panel input from mill operators and converter executives anchored the analytical framework. Segmentation dimensions modeled include material grade, box style complexity, end-use sector, and regional regulatory cluster. CAGRs were synthesized from demand elasticity coefficients and capacity expansion announcements. Forecast inputs incorporated e-commerce penetration trajectories and recycled content threshold enforcement timelines.
Revisions become necessary when EU member state EPR implementation variations accelerate, OCC export demand shifts abruptly, or lightweighting technology breaches edge crush test floor thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Thermoform Cups Market
Packaging Containers
Chalk Boxes Market
Packaging Containers
Correx Trays Market
Packaging Containers
Wrist Watch Packaging Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
Foldable Mailer Box Market
Packaging Containers
Automotive Parts Packaging Market
Packaging Containers
Non-Corrugated Boxes Market
Packaging Containers
Glass Vape Cartridge Market
Packaging Containers
Slide Tray Box Market
Packaging Containers
Middle East and Africa Aerosol Cans Market
Packaging Containers
Child Resistant Bottles Market
Packaging Containers
Sanitizer Bottles Market
Packaging Containers
Trigger Spray Bottle Market
Packaging Containers
Eyewear Packaging Market
Packaging Containers
VCI Bags Market