
 Hiking Accessories Market | 2026-2036
Hiking Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Hiking Accessories Market Analysis
Recycled polyester is shifting from niche premium to mainstream cost parity across hiking backpacks and shell layers. Columbia Sportswear leverages vertical manufacturing partnerships to control nylon sourcing for its trail footwear division. Arc'teryx anchors its reputation on laminated waterproof-breathable membranes with hydrostatic head ratings exceeding 20,000 mm. Black Diamond Equipment specializes in load-bearing hardware and trekking pole mechanisms for technical alpine terrain.
Hiking accessories comprise portable equipment designed to support human locomotion, hydration, shelter, and safety during unpaved trail traversal, typically incorporating ripstop weaves, aluminum or carbon fiber structural members, and thermoplastic polyurethane coatings for abrasion resistance. Backpacks constructed from waterproof fabric command margin premiums in the adventure tourist channel where river crossings and monsoon exposure create failure-risk aversion. Trekking poles in lightweight carbon fiber configurations represent the fastest-growing product type as aging demographics in North America and Western Europe seek joint-impact reduction on extended descents. Nylon retains volume leadership across mid-tier casual hiker segments where cost sensitivity outweighs gram-counting optimization.
REACH restrictions on per- and polyfluoroalkyl substances in the European Union compel reformulation of durable water repellent treatments across nylon and polyester outerwear, raising compliance costs for brands distributing in Germany, France, and Italy. The EPA's emerging framework on textile microfiber shedding in the United States will likely mandate filtration standards for washing waterproof fabric garments within the next regulatory cycle. Stakeholders must monitor material certification pipelines and pre-position alternative chemistries before jurisdiction-specific bans fragment product portfolios into incompatible regional SKUs.
Market Dynamics
EU Green Deal extended producer responsibility rules are compressing brand margins while forcing rapid supply chain reconfiguration toward recycled nylon and polyester streams.
Growth Catalysts
- REACH chemical restrictions:PFAS phase-outs in the European Union are accelerating reformulation of durable water repellent chemistries, opening procurement windows for fluorine-free alternatives.
- Adventure tourism infrastructure:Guided expedition operators in Patagonia, New Zealand, and Nepal are scaling technical route offerings that require professional-grade load-bearing hardware.
- Carbon fiber manufacturing scale:Chinese producers have expanded filament winding capacity, reducing per-unit trekking pole shaft costs and enabling mass-market lightweight configurations.
Market Restraints
- Petrochemical feedstock volatility:Nylon 6,6 polymer prices fluctuate with benzene and adipic acid spot markets, squeezing margin predictability for mid-tier backpack manufacturers.
- Membrane supplier concentration:ePTFE waterproof-breathable film production concentrates among three Japanese and US specialty chemical firms, creating single-source vulnerability for shell layer brands.
- Substrate performance ceiling:Recycled polyester tensile strength remains 15-20% below virgin fiber specifications, limiting deployment in high-load suspension systems.
Strategic Opportunities
- Indian outbound trekking segment:Domestic Himalayan operators in Uttarakhand and Himachal Pradesh are professionalizing equipment standards, creating first-mover advantage for certified hydration system suppliers.
- EU Green Deal circularity mandates:Textile take-back and recycling targets will favor brands with closed-loop nylon recovery partnerships by 2030.
- Direct-to-expedition channel:Adventure tourism aggregators are consolidating group procurement, bypassing traditional retail markup structures for volume trail footwear contracts.
Industry Challenges
- PFAS-free chemistry validation:Brands must complete 20,000+ wash cycle testing for new DWR formulations before EU market entry, extending product development timelines by 8-14 months.
- Multi-jurisdiction SKU proliferation:Divergent state-level microfiber filtration proposals in the US threaten to fragment waterproof garment variants into incompatible regional compliance batches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hiking Accessories Market |
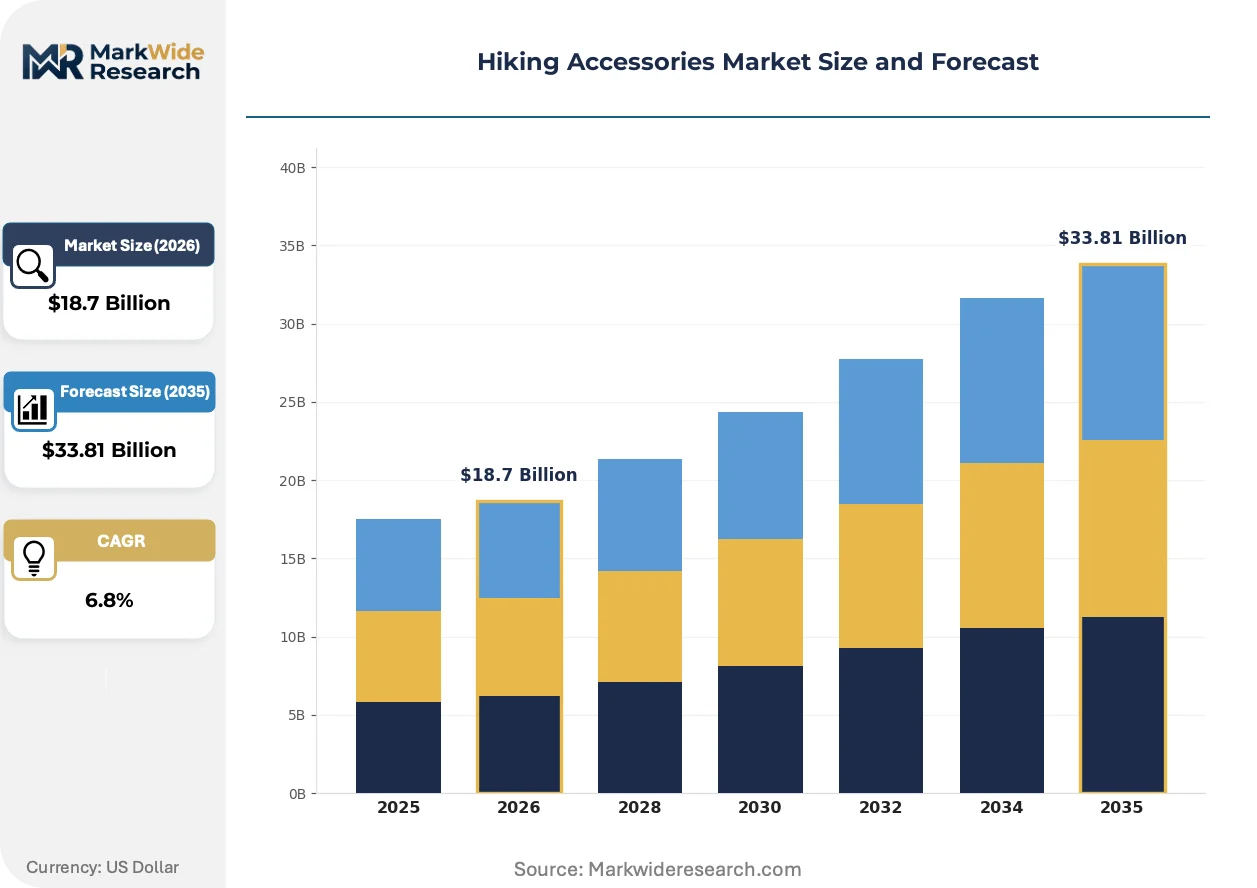
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Backpacks, Trekking Poles, Hydration Systems, Camping Gear Material: Nylon, Polyester, Leather, Waterproof Fabric Feature: Lightweight, Reflective, Multi-Functional, Ergonomic Design End User: Casual Hikers, Backpackers, Outdoor Enthusiasts, Adventure Tourists |
| Companies Covered | Amer Sports, Columbia Sportswear, Newell Brands, The North Face, Patagonia, Arc'teryx, Black Diamond Equipment, Marmot, Decathlon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hiking Accessories Market Emerging Trajectories
Material substitution and regulatory chemistry bans are compressing traditional competitive advantages while opening entry points for specialized membrane and hardware suppliers.
Bio-based polyamide yarns derived from castor oil feedstocks are expanding into alpine shell layers and technical backpacks. European mountaineering cooperatives have adopted these fibers for guided ascent programs above 4,000 meters. The shift is expanding into premium price tiers previously dominated by petroleum-derived nylon 6,6, forcing incumbent fiber producers to accelerate bio-polymer pilot lines.
EPA's emerging textile microfiber shedding framework is mandating filtration compatibility disclosures for waterproof fabric garments sold in the United States. Outdoor apparel brands are redesigning care labels and pre-treating fleece components to reduce fiber release during consumer washing cycles. The regulation is reshaping product development priorities for brands distributing across California, Washington, and New York state jurisdictions.
Expedition operators are consolidating equipment procurement through specialized buying cooperatives that negotiate direct manufacturer contracts. Traditional outdoor retail chains in Germany and Austria are losing volume share to these aggregated purchasing entities. The consolidation is most pronounced in the alpine guiding sector, where group size and route standardization enable bulk shell layer and trekking pole specifications.
Hiking Accessories Market Segmentation
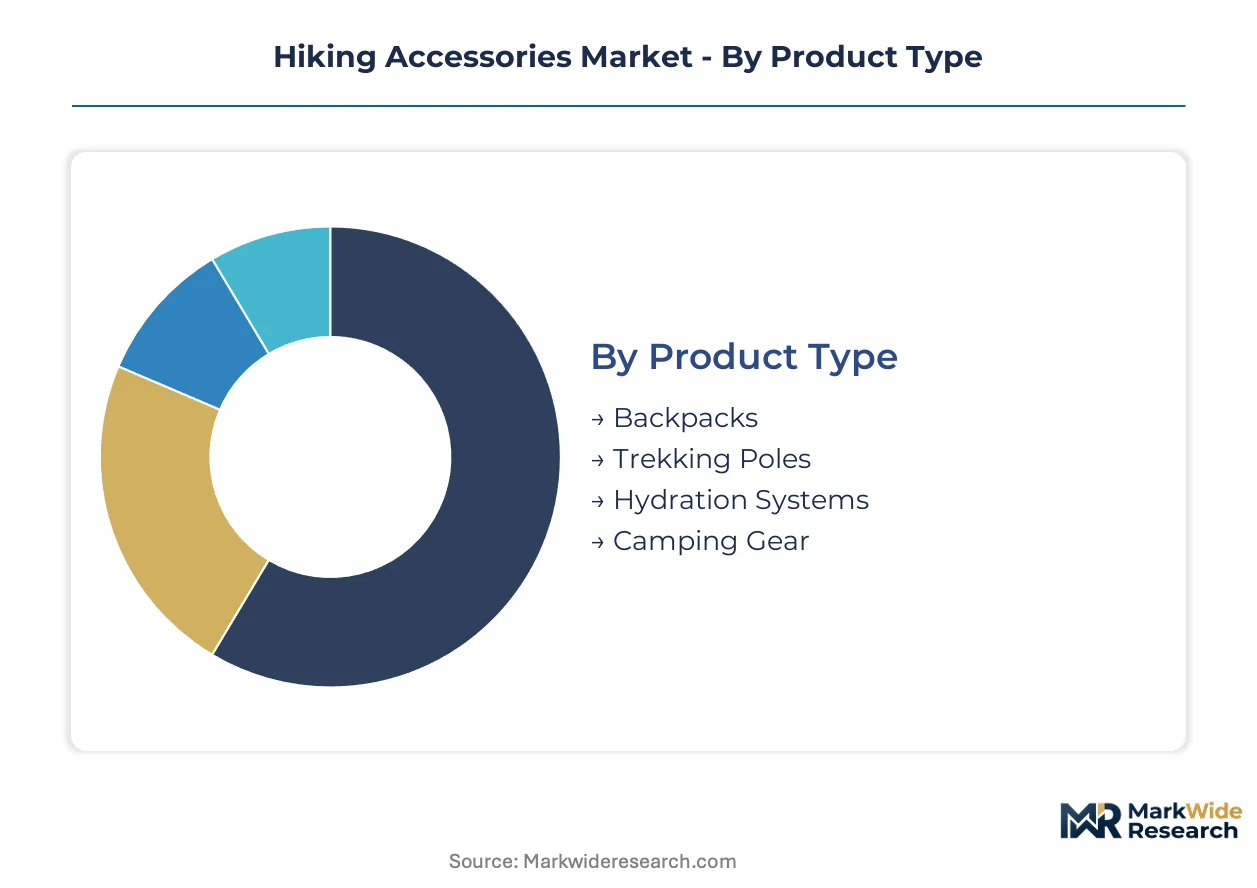
Segmentation in hiking accessories reveals how technical specifications, material science, and user proficiency create distinct procurement channels. Manufacturers must align production capacity with the divergent durability and weight requirements of casual day-trippers versus alpine expedition operators.
Product Type:
Customization intensity varies sharply across this category, from standardized trekking pole shafts to expedition backpacks requiring torso-length adjustment systems.
- Backpacks:Suspension systems integrate aluminum stays, HDPE framesheets, and ripstop nylon shells rated for 30-70 liter capacities. Demand concentrates among adventure tourists in Nepal and Patagonia where porter-supported treks require load-bearing durability across multi-week itineraries.
- Trekking Poles:Carbon fiber and 7075 aluminum shafts with flick-lock or twist-lock mechanisms reduce knee impact on descents. Aging demographics in Germany and Austria drive replacement cycles for lightweight configurations with ergonomic cork grips.
- Hydration Systems:Bladder reservoirs and hose assemblies with antimicrobial treatments support continuous fluid intake.
- Camping Gear:Shelter components, cookware, and sleep systems complete overnight equipment kits.
Most installed capacity flows through Backpacks. Expansion is steepest in Trekking Poles.
Material:
Cost tier stratification separates petroleum-derived synthetics from bio-based alternatives and performance laminates.
- Nylon:Nylon 6 and 6,6 polymers deliver tensile strength for high-load suspension points and abrasion-resistant pack bottoms. Mid-tier casual hiker segments in the United States and France prioritize cost predictability over gram-counting optimization.
- Polyester:Recycled PET filament yarns achieve near-cost parity with virgin fiber in shell layer applications. EU Green Deal circularity mandates in Italy and Spain accelerate procurement shifts toward certified recycled streams.
- Leather:Full-grain and nubuck treatments appear in heritage-styled boot uppers and accessory trims.
- Waterproof Fabric:Laminated membranes with ePTFE or polyurethane coatings achieve hydrostatic head ratings above 10,000 mm.
Nylon retains the largest production footprint. Recycled polyester is climbing the fastest.
Feature:
Application context determines which performance attributes command price premiums versus baseline inclusion.
- Lightweight:Sub-kilogram pack designs and carbon fiber pole shafts target thru-hikers covering 20+ kilometer daily distances. Alpine guiding services in Switzerland specify maximum base weights for client safety on technical routes.
- Reflective:Retroreflective tape and piping enhance visibility during dawn and dusk trail segments. Urban-adjacent trail systems in Japan and South Korea mandate reflective elements for mixed-use path safety compliance.
- Multi-Functional:Convertible pack lids, detachable hip belts, and modular attachment systems adapt to variable trip durations.
- Ergonomic Design:Gender-specific torso sizing, pre-curved shoulder straps, and adjustable sternum straps distribute load across biomechanically optimized contact points.
Lightweight specifications dominate manufacturing output. Reflective treatments are gaining share fastest.
End User:
Customer type segmentation maps directly to distribution channel strategy and margin structure.
- Casual Hikers:Day-trip participants on marked trails under 10 kilometers purchase entry-level packs and aluminum trekking poles. Retail chains in the United Kingdom and Germany serve this volume segment through seasonal promotional cycles.
- Backpackers:Multi-day wilderness travelers prioritize weight-to-durability ratios and repairability in remote conditions. Pacific Crest Trail and Appalachian Trail corridors in California and Virginia concentrate specialized outfitter demand.
- Outdoor Enthusiasts:Technical climbers, trail runners, and ski mountaineers require discipline-specific equipment configurations.
- Adventure Tourists:Guided expedition clients in New Zealand and Nepal procure professional-grade hardware through operator-bundled packages, bypassing traditional retail markup structures.
Casual Hikers absorb the highest unit volume. Adventure Tourists are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors manufacturing capacity for carbon fiber trekking pole shafts and laminated waterproof membranes serving global outdoor brands. Demand concentrates in alpine tourism corridors across Switzerland, Austria, and Norway where wet-weather trekking dominates seasonal activity. Regulatory fragmentation around PFAS chemistry and microfiber shedding is reshaping procurement patterns across these markets.
United States
Pacific Crest Trail and Appalachian Trail corridors drive specialized outfitter demand for ultralight backpacks and carbon fiber poles. The EPA's emerging textile microfiber shedding framework will mandate filtration compatibility disclosures for waterproof garments within the next regulatory cycle. Colorado and Utah cluster domestic manufacturing of technical shell layers for high-altitude mountaineering segments.
Germany
Aging demographics in Bavaria and Baden-Württemberg accelerate replacement cycles for ergonomic trekking poles with joint-impact reduction features. REACH restrictions on PFAS chemicals compel reformulation of durable water repellent treatments across nylon outerwear distributed in Germany, France, and Italy. Munich anchors European headquarters for several technical outdoor brands managing alpine route certification programs.
China
Domestic Himalayan operators in Sichuan and Yunnan provinces are professionalizing equipment standards for outbound trekking segments. MIIT industrial standards for textile recycling are accelerating closed-loop nylon recovery partnerships among Yangtze Delta manufacturers. Shenzhen and Dongguan concentrate filament winding capacity for carbon fiber trekking pole shafts serving mass-market lightweight configurations.
Switzerland
Alpine guiding services specify maximum base weights for client safety on technical routes above 3,000 meters. Swissmedic-equivalent textile certification requirements enforce hydrostatic head ratings for waterproof-breathable membranes used in professional expedition contexts. Zurich and Geneva cluster R&D facilities for laminated membrane technologies serving premium shell layer producers.
India
Domestic operators in Uttarakhand and Himachal Pradesh are scaling technical route offerings requiring professional-grade load-bearing hardware. BIS textile standards for recycled content are creating procurement windows for certified hydration system suppliers entering the market. Bangalore and Delhi-NCR concentrate e-commerce distribution infrastructure for adventure tourism equipment aggregators.
Hiking Accessories Market Vendor Landscape
Global majors compete with regional champions across membrane technology and carbon fiber hardware sourcing. The vendor base separates into three tiers: integrated apparel conglomerates controlling nylon supply chains, specialized equipment houses focusing on alpine technical hardware, and mass-market retailers leveraging manufacturing scale for entry-level configurations. Strategic moves concentrate on supply chain reconfiguration toward recycled feedstocks and direct procurement partnerships with expedition operators bypassing traditional retail markup structures.
Within the integrated apparel tier, Columbia Sportswear and Arc'teryx exemplify divergent approaches to material sourcing and technical positioning. Columbia's vertical manufacturing partnerships control nylon feedstock for trail footwear divisions, while Arc'teryx anchors premium positioning on laminated waterproof-breathable membrane performance. Black Diamond Equipment occupies a specialist position in load-bearing hardware and trekking pole mechanisms for technical alpine terrain, representing the equipment-house archetype against the integrated majors.
| Leading Market Players |
|---|
| Amer Sports |
| Columbia Sportswear |
| Newell Brands |
| The North Face |
| Patagonia |
| Arc'teryx |
| Black Diamond Equipment |
| Marmot |
| Decathlon |
| Others |
Supply Flow & Price Mechanics
EU Green Deal extended producer responsibility rules gate qualified supply access and premium-tier pricing power, compressing margins for brands lacking certified recycled nylon partnerships while rewarding early movers with circularity credentials in Germany and France.
Pricing Analysis
Input-cost pass-through from benzene and adipic acid spot volatility squeezes mid-tier backpack manufacturers in the United States and France. Three-tier pricing structure across premium, standard, and economy levels separates hydrostatic head-rated shell layers from basic ripstop configurations. Cost compression in standard tiers intensifies because Chinese carbon fiber producers expanded filament winding capacity. Casual hikers in the United Kingdom exhibit highest price sensitivity; alpine guiding services in Switzerland show least sensitivity due to bundled procurement contracts.
Supply Chain Analysis
Certification gating through REACH PFAS restrictions and BIS recycled content standards fragments supplier qualification across European and Indian markets. Manufacturing gravity centers on China, Vietnam, and Bangladesh for woven nylon shells and laminated membrane assembly. Feedstock dependencies rest on petrochemical-derived adipic acid, castor oil bio-polymer pilot streams, and ePTFE membrane films from Japanese specialty chemical producers. Single-source vulnerability concentrates in waterproof-breathable film supply. Distribution runs through expedition operator buying cooperatives bypassing traditional retail markup structures in Germany and Austria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in the European Union exceed those in China's MIIT-regulated recycling corridors by a factor that rewards dual-sourcing strategies.
For Market Incumbents: Anchor membrane technology leadership through captive R&D partnerships with Yangtze Delta laminators before bio-based polyamide scales erode petroleum-derived nylon premiums. Defend position by locking multi-year recycled PET offtake agreements with certified suppliers in Vietnam. Prioritize backward integration into ePTFE alternative chemistries as Japanese membrane concentration creates supply vulnerability.
For New Entrants and Emerging Players: Direct-to-expedition digital channels offer lowest customer acquisition cost entry into professional-grade hardware segments. White-space targets concentrate in Indian Himalayan operator procurement and North American ultralight thru-hiker communities. Penetrate through hydration system certification under BIS standards where incumbent presence remains thin.
For Investors and Strategic Acquirers: Roll-up economics work for regional equipment houses with established alpine guiding relationships because expedition operator consolidation favors bundled procurement platforms. Long-term viability hinges on circularity infrastructure ownership rather than brand equity alone. Watch for MIIT textile recycling standard acceleration as inflection signal for Chinese manufacturing asset repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Nylon Recovery | EU Green Deal circularity mandates favor brands with closed-loop partnerships by 2030. |
| Direct-to-Expedition Channel Expansion | Adventure tourism aggregators in Nepal and New Zealand consolidate group procurement volumes. |
| PFAS-Free Chemistry Certification | REACH restrictions compel 20,000+ wash cycle validation for DWR formulations in Germany. |
| Carbon Fiber Filament Winding Scale-Up | Chinese producers reduced per-unit trekking pole shaft costs enabling mass-market penetration. |
| Bio-Based Polyamide Pilot Line Investment | European mountaineering cooperatives adopted castor oil fibers for guided ascents above 4,000 meters. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand supply chain directors, alpine guiding service procurement leads, textile certification specialists, and adventure tourism operators with secondary validation against customs trade data, ECHA REACH registration databases, MIIT industrial standard filings, and SEC 10-K disclosures from listed outdoor apparel conglomerates. Bottom-up demand modeling across product types and materials triangulated against top-down market sizing.
Comparable-period anchoring linked projection assumptions to historical capacity utilization and pricing patterns across the analysis window. Segmentation dimensions modeled include product type, material composition, feature specification, and end-user proficiency tier alongside regional regulatory cluster differentiation. CAGRs derived from trend extrapolation of carbon fiber manufacturing scale, recycled polyester cost parity achievement, and expedition tourism infrastructure expansion rates.
The model assumes a particular technology adoption path; alternative pathways for bio-based polyamide commercialization would alter the outlook. Forecasts reflect assumptions about REACH enforcement consistency and EPA microfiber framework implementation timing. A model refresh is warranted upon material change in EU Green Deal circularity mandate acceleration or Chinese dual carbon policy stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Kitesurf Kites Market
Outdoor and Adventure Activities
Skiing Equipment Market
Outdoor and Adventure Activities
US Spectator Sports Market
Outdoor and Adventure Activities
Hiking Gear and Equipment Market
Outdoor and Adventure Activities
Outdoor Living Product Market
Outdoor and Adventure Activities
Snowshoes Market
Outdoor and Adventure Activities
India Spectator Sports Market
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
Adventure Gear Market
Outdoor and Adventure Activities
Spain Sports Tourism Market
Outdoor and Adventure Activities
North America Personal Watercraft Market
Outdoor and Adventure Activities
Kayak Market
Outdoor and Adventure Activities
Mountain Bike Market
Outdoor and Adventure Activities
Recreational Sports Activities Market
Outdoor and Adventure Activities
Global Water Bikes Market
Outdoor and Adventure Activities
Hiking Cleats Market