
 Sports Hydration Market | 2026-2036
Sports Hydration Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Hydration Market Analytics
Electrolyte micro-dosing technology is fragmenting traditional beverage formulation paradigms, enabling precision hydration tailored to sweat-rate profiles and activity intensity. PepsiCo leverages its global bottling infrastructure to sustain cost advantages in mainstream electrolyte drinks. The Coca-Cola Company anchors its position through Powerade's institutional sports partnerships and locker-room distribution networks. Nuun Hydration differentiates with tablet-based delivery that reduces shipping weight and plastic waste versus ready-to-drink formats.
Sports hydration encompasses fluid and semi-fluid products engineered with specified electrolyte concentrations, typically sodium and potassium, alongside carbohydrate matrices designed to sustain plasma volume and delay neuromuscular fatigue during sustained physical exertion. Electrolyte drinks command the largest revenue pool, though sports gels represent the fastest-expanding category among endurance athletes seeking portable, gut-tolerable fuel. Distribution through online retail is gaining share as subscription models and direct-to-consumer personalization reduce reliance on supermarket shelf-space competition. Flavor innovation clusters around berry profiles, which mask mineral bitterness more effectively than citrus variants while appealing to younger fitness demographics.
FDA nutrition labeling requirements and state-level sugar-sweetened beverage taxes in California, Colorado, and Washington reshape formulation priorities toward reduced-sugar and natural sweetener alternatives. The USDA's National School Lunch Program standards indirectly influence youth-oriented product development by restricting competitive beverage offerings in educational settings. Stakeholders must monitor evolving EPA packaging regulations and state extended producer responsibility laws that will determine cost structures for single-use bottles versus concentrated or dissolvable formats.
Market Dynamics
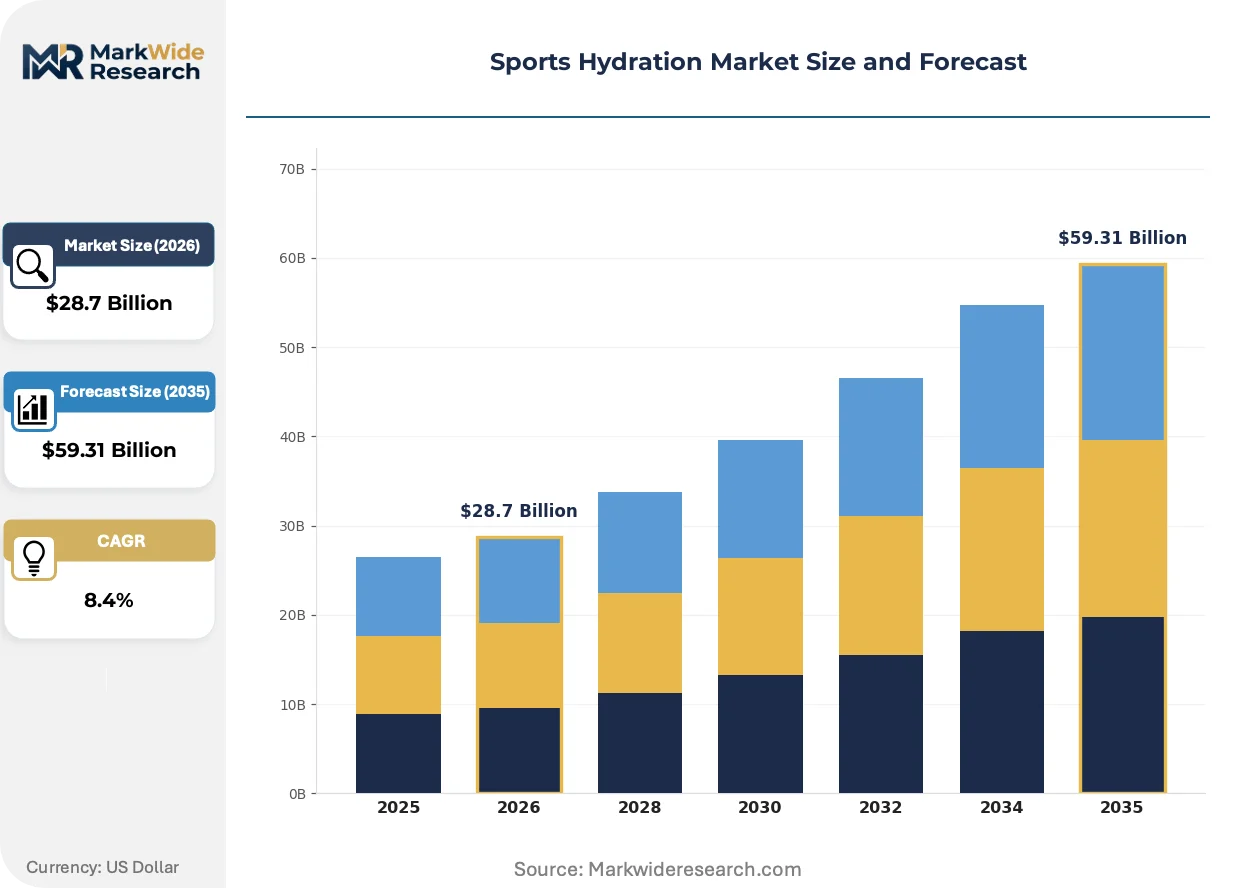
Clean-label formulation mandates and sugar taxation frameworks are compressing legacy beverage architectures while accelerating precision hydration technologies that match electrolyte delivery to individual sweat profiles.
Growth Catalysts
- Dual carbon goals in China:The country's national environmental regulator is tightening packaging waste standards, forcing domestic sports beverage manufacturers toward concentrated tablet and powder formats that slash plastic intensity.
- Professional athletic programs:Collegiate and professional team procurement departments are deepening consumption of sweat-rate-matched hydration protocols, creating institutional demand pull for micro-dosing electrolyte systems.
- Extended Producer Responsibility laws:State-level frameworks in California, Colorado, and Washington are altering cost structures for single-use bottles, advantaging dissolvable and concentrated delivery formats over ready-to-drink alternatives.
Market Restraints
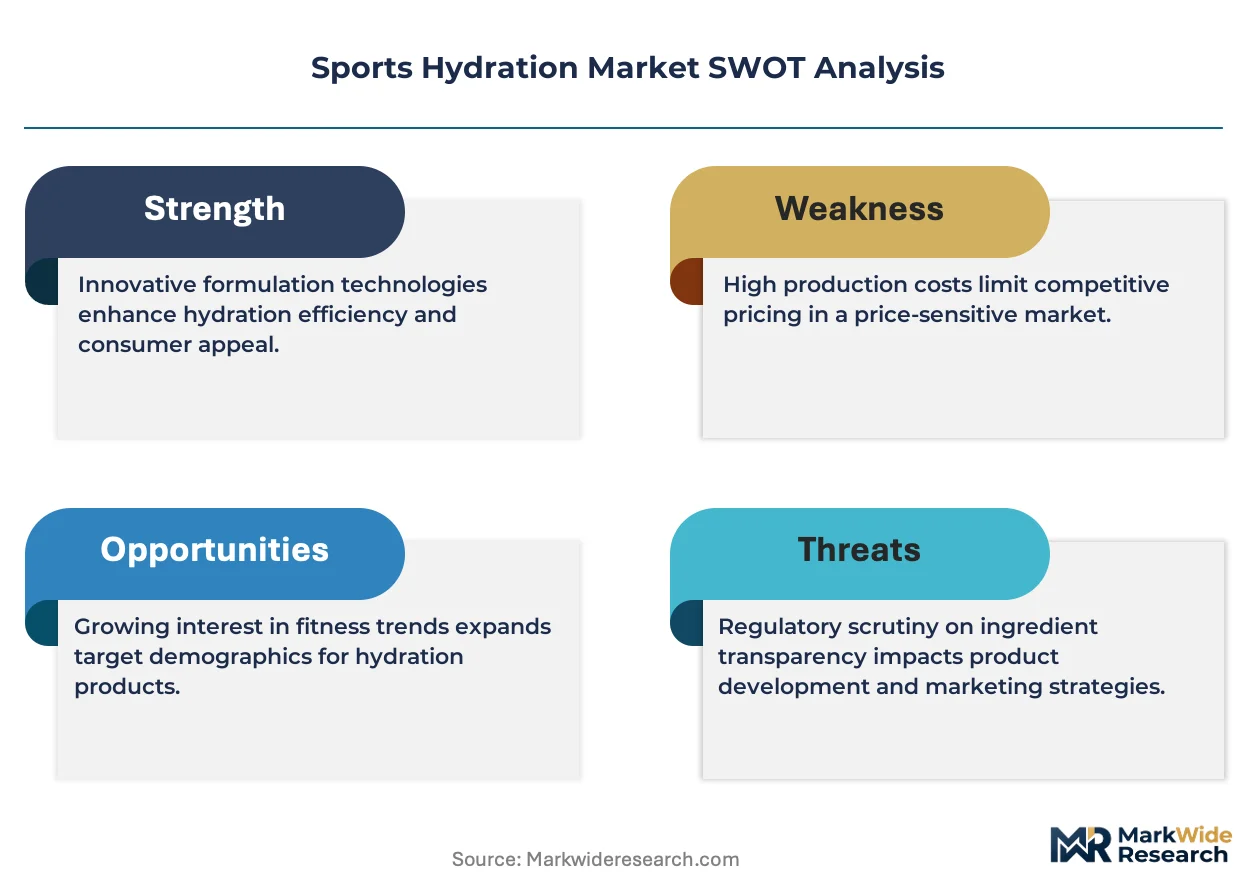
- Natural sweetener input volatility:Stevia and monk fruit extract supply concentrates in specific growing regions, exposing formulation costs to agricultural yield fluctuations and extraction capacity bottlenecks.
- Electrolyte mineral sourcing concentration:High-purity sodium and potassium chloride supply chains cluster with industrial chemical processors in China and Germany, creating geographic concentration risk for clean-label product lines.
- FDA nutrition labeling complexity:Evolving serving-size definitions and added-sugar disclosure requirements extend product reformulation timelines and compliance verification costs.
Strategic Opportunities
- Youth athletic programs:USDA National School Lunch Program beverage restrictions have created an underserved channel for electrolyte-enhanced water products that meet sodium and sugar thresholds for competitive placement.
- Subscription personalization platforms:Direct-to-consumer sweat-testing kits paired with algorithmic flavor and electrolyte matching are opening recurring-revenue models outside traditional retail shelf competition.
- EU Green Deal packaging mandates:The bloc's accelerating single-use plastic reduction targets are creating regulatory tailwinds for tablet-based and refillable-concentrate formats with lower lifecycle carbon footprints.
Industry Challenges
- Food-science talent scarcity:Formulation chemists with dual expertise in mineral bioavailability and natural flavor masking are in short supply, extending R&D timelines for clean-label electrolyte products.
- ISO 22000 certification complexity:Food safety management system audits for electrolyte manufacturing facilities face backlog delays, slowing facility expansions and co-manufacturer onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Hydration Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolyte Drinks, Sports Gels, Energy Bars, Pouches Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops End User: Athletes, Fitness Enthusiasts, Casual Exercisers, Trainers Flavor Type: Citrus, Berry, Tropical, Mixed Fruit |
| Companies Covered | PepsiCo, The Coca-Cola Company, BodyArmor, Nuun Hydration, Prime Hydration, Monster Beverage Corporation, Red Bull GmbH, BA Sports Nutrition, AJE Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Hydration Market Evolving Landscape
Electrolyte delivery architectures are fragmenting as precision hydration technologies, regulatory packaging pressures, and direct-to-consumer channel shifts simultaneously reshape product form factors and go-to-market economics.
Micro-dosing electrolyte technology is migrating from one-size-fits-all beverage formulations toward sweat-rate-calibrated delivery systems. Endurance athletes and professional training facilities are adopting portable electrolyte tablets and customizable powder sachets at accelerating pace. This migration is compressing the addressable market for mass-market ready-to-drink sports beverages while expanding margins for precision-formulation specialists.
REACH chemical registration requirements in Europe are tightening scrutiny of artificial colorants and synthetic mineral carriers used in conventional sports drinks. Industrial consequence includes accelerated reformulation timelines and supplier qualification costs for brands accessing EU distribution. The ready-to-drink segment is responding most visibly, with berry-flavored natural colorant systems displacing synthetic alternatives faster than citrus variants due to superior mineral bitterness masking.
Subscription-based replenishment models are capturing share from supermarket impulse purchasing among core fitness demographics. Direct-to-consumer channels are disrupting traditional beverage distribution economics by reducing slotting fee burdens and enabling flavor personalization algorithms. California and Texas fitness club density corridors are exhibiting the most visible concentration of this behavioral shift, with urban subscription penetration outpacing suburban retail reliance.
Sports Hydration Market Segmentation
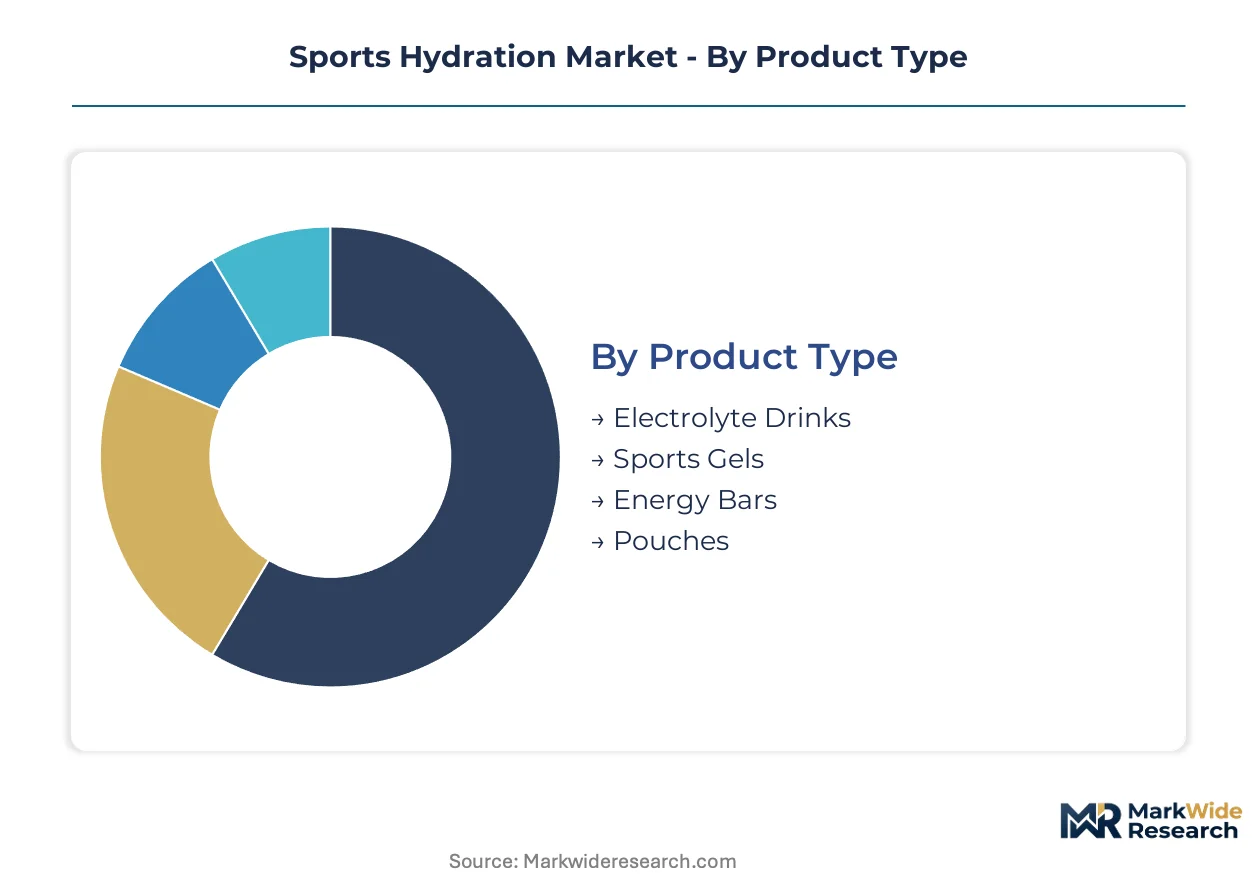
Sports hydration manufacturers must navigate divergent replenishment cycles across product formats, with ready-to-drink beverages turning inventory weekly while concentrated tablets rotate monthly. Channel and user segmentation further complicates portfolio planning, as institutional procurement operates on annual contracts counter to fitness subscription renewals.
Product Type:
Inventory velocity varies dramatically across formats, with liquid beverages requiring cold-chain replenishment cycles that compressed tablets and gels avoid entirely.
- Electrolyte Drinks:Ready-to-drink formulations with specified sodium and potassium concentrations dominate institutional procurement through locker-room distribution networks. Collegiate athletic programs in Texas and California anchor volume concentration, though single-use bottle regulations in multiple states compress margin structures.
- Sports Gels:Semi-fluid carbohydrate-electrolyte matrices packaged in single-serve sachets deliver portable fuel calibrated to endurance activity intensity. Marathon and triathlon participants drive demand concentration, with gut-tolerance formulation standards separating premium from commodity tiers.
- Energy Bars:Solid-form nutrition combining electrolytes with protein and carbohydrate matrices for pre- or post-workout consumption. Hiking and outdoor recreation segments in Colorado and Washington state exhibit above-average adoption.
- Pouches:Flexible-format liquid or gel concentrates in lightweight packaging optimized for backpacking and ultralight athletics. Extended backcountry athletes and military procurement units represent core demand pockets.
Electrolyte drinks anchor the volume base while sports gels gain share at the steepest rate.
Distribution Channel:
Channel economics diverge sharply on customer acquisition cost and margin retention, with direct relationships capturing lifetime value that retail intermediaries sacrifice for shelf placement.
- Online Retail:Subscription-based replenishment models paired with algorithmic flavor personalization bypass slotting fee burdens. Fitness enthusiasts in urban California corridors exhibit the highest subscription penetration rates.
- Supermarkets:Impulse-purchase placement in beverage aisles drives trial among casual exercisers. Berry-flavored variants outperform citrus in this channel due to superior mineral bitterness masking.
- Health Stores:Curated assortments emphasizing clean-label and organic certifications attract premium-seeking consumers. Staff consultation drives conversion for electrolyte tablet formats unfamiliar to mainstream shoppers.
- Specialty Shops:Running, cycling, and triathlon retailers provide expert guidance on sweat-rate-matched protocols. Endurance athletes in Austin and Boulder metropolitan areas concentrate purchases through this channel.
Online retail captures margin expansion while specialty shops sustain the highest customer lifetime value.
End User:
Usage intensity and formulation sophistication create distinct product requirements across participant commitment levels.
- Athletes:Collegiate and professional competitors require sweat-rate-calibrated electrolyte delivery through institutional procurement channels. Training facilities in Texas and Florida deepen consumption of micro-dosing protocols.
- Fitness Enthusiasts:Regular gym attendees and recreational runners sustain the mass-market volume base. Subscription personalization platforms capture this segment through direct-to-consumer channels.
- Casual Exercisers:Weekend warriors and health-conscious consumers drive trial purchases in supermarket and convenience formats. Low-sugar variants align with household beverage taxation exposure.
- Trainers:Personal training professionals and coaching staff influence institutional purchasing decisions and individual athlete recommendations. Certification programs increasingly include hydration science modules.
Fitness enthusiasts generate the steadiest recurring revenue while athletes command the highest per-capita consumption intensity.
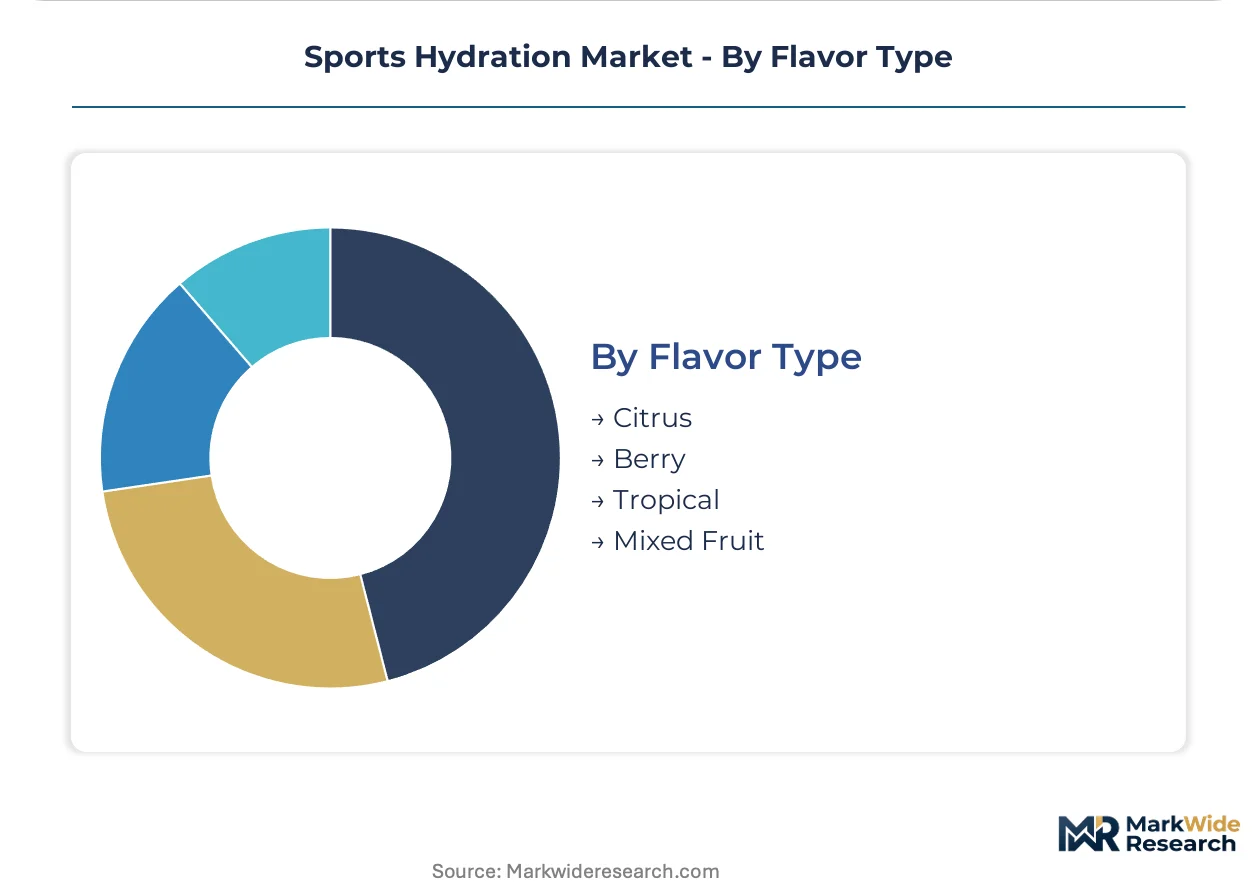
Flavor Type:
Formulation chemistry and demographic targeting determine flavor performance, with mineral bitterness masking capabilities separating viable from failed launches.
- Berry:Anthocyanin-based natural colorants and flavor compounds most effectively obscure sodium and potassium chloride bitterness. Younger fitness demographics in California and Texas exhibit strongest preference concentration.
- Citrus:Traditional lemon-lime and orange profiles face reformulation pressure as REACH requirements tighten artificial colorant scrutiny. Natural citrus extracts carry higher agricultural input volatility.
- Tropical:Mango, pineapple, and coconut variants target endurance athletes seeking palate variety during prolonged exertion. Hawaii and Florida regional preferences influence national portfolio decisions.
- Mixed Fruit:Blended profiles balance familiarity with differentiation in crowded retail sets. Clean-label positioning requires explicit fruit juice concentration disclosure.
Berry profiles dominate current formulation pipelines while tropical variants expand most quickly among endurance specialty channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Elite athletic programs and fitness infrastructure density concentrate procurement power in specific metropolitan corridors, while regulatory packaging mandates reshape manufacturing footprints across major consumption centers.
United States
Professional sports franchises and collegiate athletic departments anchor institutional demand through sweat-rate-calibrated hydration protocols. FDA nutrition labeling requirements and state-level extended producer responsibility laws in California, Colorado, and Washington compress single-use bottle economics. Austin and Boulder metropolitan areas concentrate endurance athlete purchases through specialty retail channels.
China
Domestic sports beverage manufacturers face tightening packaging waste standards under national dual carbon goals from the Ministry of Ecology and Environment. Fitness club expansion in tier-one cities drives consumption among urban professionals. Yangtze River Delta manufacturing clusters pivot toward concentrated tablet formats to reduce plastic intensity.
Germany
REACH chemical registration requirements accelerate reformulation away from artificial colorants and synthetic mineral carriers. Endurance sports culture in Bavaria and Baden-Württemberg sustains demand for precision electrolyte delivery systems. Industrial chemical processors in the Rhine-Ruhr region supply high-purity sodium and potassium chloride for clean-label product lines.
United Kingdom
Subscription-based replenishment models capture share from supermarket channels among London and Southeast fitness demographics. EU Green Deal packaging mandates create regulatory tailwinds for tablet-based formats with lower lifecycle carbon footprints. Health store networks in urban centers drive conversion for unfamiliar electrolyte delivery formats.
Australia
Outdoor recreation and endurance racing cultures sustain above-average adoption of portable electrolyte gels and pouches. TGA regulatory frameworks influence formulation standards for mineral bioavailability claims. Sydney and Melbourne metropolitan fitness club density supports direct-to-consumer subscription penetration.
Sports Hydration Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent go-to-market economics. Beverage conglomerates leverage global bottling infrastructure and institutional sports partnerships against nimble specialists betting on precision hydration and reduced packaging formats. Three archetypes dominate: mass-market electrolyte drink purveyors, tablet-based delivery innovators, and endurance-focused gel specialists. Competitive intensity manifests through M&A consolidation of regional brands and vertical integration into mineral sourcing.
Among mass-market beverage conglomerates, PepsiCo and The Coca-Cola Company occupy positions sustained by locker-room distribution networks and global supply chain scale. Nuun Hydration exemplifies the tablet-delivery archetype, reducing shipping weight and plastic waste versus ready-to-drink alternatives. These three anchors represent the structural tension between incumbent channel control and specialist format innovation reshaping competitive positioning.
| Leading Market Players |
|---|
| PepsiCo |
| The Coca-Cola Company |
| BodyArmor |
| Nuun Hydration |
| Prime Hydration |
| Monster Beverage Corporation |
| Red Bull GmbH |
| BA Sports Nutrition |
| AJE Group |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta manufacturing clusters in China anchor electrolyte tablet and powder production capacity, with their scale dynamics directly translating to pricing leverage over downstream ready-to-drink bottlers in North America and Europe. Extended producer responsibility laws in California, Colorado, and Washington compress single-use bottle economics, forcing cost pass-through negotiations between concentrated tablet suppliers and fragmented retail buyers.
Pricing Analysis
Cost-plus contracts with stevia and monk fruit extract indexation dominate natural sweetener procurement, exposing finished goods pricing to agricultural yield volatility in specific growing regions. Three-tier pricing structure across premium precision-hydration, standard electrolyte drinks, and economy private-label tiers separates sweat-rate-matched protocols from mass-market formulations. Pricing pressure stems from sugar taxation frameworks in multiple jurisdictions accelerating reformulation costs. Casual exercisers in supermarket channels exhibit highest price sensitivity, while collegiate athletic programs demonstrate lowest sensitivity due to institutional procurement budgets.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for electrolyte mineral sourcing. High-purity sodium and potassium chloride production concentrates in China and Germany, with natural flavor extraction anchored in specific agricultural regions. Raw material dependencies center on stevia leaf supply, monk fruit harvest cycles, and berry-derived anthocyanin colorants. Single-source vulnerability persists for food-grade mineral processing capacity. Distribution runs through global bottling networks for ready-to-drink formats, while direct-to-consumer subscription platforms bypass traditional retail slotting fee structures entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists possessing dual expertise in mineral bioavailability and natural flavor masking represent the critical talent bottleneck constraining clean-label product development timelines across the competitive landscape.
For Market Incumbents: Build captive supply chain moats through backward integration into high-purity electrolyte mineral processing in the Rhine-Ruhr region or Yangtze River Delta. Incumbents should secure ISO 22000 certification priority for co-manufacturer onboarding to preempt audit backlog delays threatening capacity expansion. Tablet-based delivery innovators threaten ready-to-drink margin structures through reduced shipping weight and plastic waste advantages. For New Entrants and Emerging Players: USDA National School Lunch Program beverage restrictions in the United States represent the most penetrable white-space channel for electrolyte-enhanced water products meeting sodium and sugar thresholds. Youth athletic programs in Texas and California suburban districts offer concentrated demand pockets with limited incumbent presence. Direct-to-consumer sweat-testing kits paired with algorithmic flavor matching provide the optimal go-to-market angle for bypassing retail shelf competition entirely. For Investors and Strategic Acquirers: Long-term, this sits as a format-conversion play because regulatory packaging mandates across multiple jurisdictions structurally advantage concentrated and dissolvable delivery systems over single-use bottles. Acquisition targets should display precision-hydration technology capabilities or established subscription personalization platforms. The signal to watch is state-level extended producer responsibility law expansion beyond current California, Colorado, and Washington boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolyte Minerals | Captive supply of high-purity sodium and potassium chloride from Rhine-Ruhr processors reduces geographic concentration risk. |
| Subscription Personalization Platform Launch | Algorithmic flavor and electrolyte matching paired with sweat-testing kits captures recurring revenue outside retail competition. |
| Clean-Label Certification Investment | USDA Organic and Non-GMO Project verification accelerates placement in health store channels and school nutrition programs. |
| Tablet Format Manufacturing Scale-Up | Concentrated delivery reduces plastic intensity and shipping weight, aligning with EU Green Deal packaging mandates. |
| Institutional Sports Partnership Expansion | Locker-room distribution networks in Texas and California collegiate programs anchor volume concentration and brand loyalty. |
Research Methodology
Cross-validation between primary interviews with formulation chemists, collegiate athletic procurement directors, and health store category buyers anchors the qualitative findings against Nielsen retail audit data and FDA nutrition labeling guidance documents. Bottom-up triangulation incorporates customs records for electrolyte mineral imports and SEC filings from beverage conglomerates, while top-down validation draws from fitness club density correlations in California and Texas metropolitan corridors.
Calibration against historical adoption curves for precision-hydration technologies and subscription commerce penetration rates informs the projection framework across the analysis window. Segmentation dimensions modeled include product format, distribution channel, end-user commitment level, and flavor profile chemistry. CAGRs derive from weighted scenario analysis incorporating regulatory packaging mandate implementation timelines and natural sweetener supply volatility patterns.
Practitioners should monitor state-level extended producer responsibility law expansion, agricultural yield fluctuations in stevia and monk fruit growing regions, and ISO 22000 certification backlog durations for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
United States Weight Management Market
Sports Nutrition
Africa Sports Drink Market
Sports Nutrition
Creatine Market
Sports Nutrition
Asia-Pacific Sports Drink Market
Sports Nutrition
Sports Supplement Market
Sports Nutrition
ACF Supplements Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
United Kingdom Sports Drink Market
Sports Nutrition
GCC Sports Nutrition Market
Sports Nutrition
Europe Protein Based Sports Drinks Market
Sports Nutrition
Europe Protein Bar Market
Sports Nutrition
Pre-Workout Supplements Market
Sports Nutrition
United States Sports Drink Market
Sports Nutrition
Weight Management Supplements Market
Sports Nutrition
Hydroxymethylbutyrate Supplement Market
Sports Nutrition
North America Sports Drink Market