
 Recreational Sports Activities Market | 2026-2036
Recreational Sports Activities Market Size, Share, and Industry Trends Forecast 2026-2036
Recreational Sports Activities Market Analysis
Certified coaching shortages across padel, pickleball, and indoor golf is reorganizing how facilities scale operations and retain members. Selkirk Sport leverages its manufacturing scale to dominate the pickleball equipment vertical. TOCA Football sustains technology leadership through automated ball-delivery systems in indoor soccer training. Playtomic anchors digital court-booking infrastructure across European recreational club networks.
Recreational sports activities encompass organized and informal physical pursuits conducted outside professional leagues, typically requiring purpose-built surfaces, protective apparatus, or specialized implements manufactured to ISO 203, ASTM F1148, or EN 913 standards depending on activity risk classification. These activities generate revenue through facility access fees, equipment sales, instruction services, and digital platform subscriptions across consumer and institutional buyer segments. Team sports capture the largest revenue pool due to league infrastructure and recurring facility rental economics, while adventure sports represent the fastest-expanding category as climbing gyms, aerial parks, and guided outdoor experiences attract younger demographics seeking shareable experiential consumption. Equipment type segmentation shows protective gear commanding premium margins as liability-conscious facilities mandate certified headgear, joint supports, and impact-absorbing surfaces.
FDA oversight applies to sports nutrition products sold through recreational facility channels, while ASTM International and ISO govern equipment safety testing protocols that determine market access for domestic and imported goods. OSHA workplace wellness incentives indirectly expand corporate-sponsored recreational sports participation through insurance premium reductions. State-level concussion protocols in youth sports are mandating protective equipment upgrades and certified coach training. Stakeholders must monitor evolving equipment certification requirements and workforce credentialing standards as regulatory layering intensifies across facility operations and product categories.
Market Dynamics
Certified coaching shortages across padel, pickleball, and indoor golf are reorganizing how facilities scale operations and retain members, forcing capital reallocation toward automated training systems and digital instruction platforms.
Growth Catalysts
- OSHA Workplace Wellness Incentives:Insurance premium reductions for employers sponsoring recreational sports participation are expanding corporate-funded facility memberships and league registrations among working adults.
- Urban Infrastructure Investment:Municipal bond issuances in the United States are accelerating development of multi-sport complexes and adaptive reuse of industrial properties into climbing gyms and indoor golf centers.
- ISO 203 Equipment Certification:Standardized safety testing for impact-absorbing surfaces and protective headgear is reducing liability exposure and enabling facility insurance coverage expansion.
Market Restraints
- Specialized Surface Material Costs:Polyurethane and rubber composite flooring for padel and pickleball courts face petrochemical feedstock price volatility that compresses facility construction margins.
- Coach Certification Bottlenecks:Accrediting body capacity constraints in the United States and Spain are extending hiring timelines for certified instructors, limiting member acquisition velocity.
- Outdoor Recreation Substitution:Unstructured hiking, cycling, and running require no facility fees or equipment certification, capturing price-sensitive participants in mild-climate regions.
Strategic Opportunities
- Corporate Wellness Mandates:United States employers are expanding on-site recreational facilities and subsidized memberships as retention tools in tight labor markets.
- Sensor-Enabled Performance Tracking:Integration of motion-capture systems with automated ball-delivery machines is creating subscription revenue streams beyond facility access fees.
- Adaptive Reuse Real Estate:Vacant retail anchors and industrial warehouses in suburban United States markets offer lower-cost conversion opportunities for indoor golf and padel centers.
Industry Challenges
- Multi-Sport Coach Cross-Training:Facilities struggle to find instructors certified across padel, pickleball, and indoor golf simultaneously, forcing redundant staffing or reduced programming breadth.
- Concussion Protocol Compliance:State-level youth sports regulations in the United States mandate protective equipment upgrades and documented incident response procedures that extend facility onboarding timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recreational Sports Activities Market |
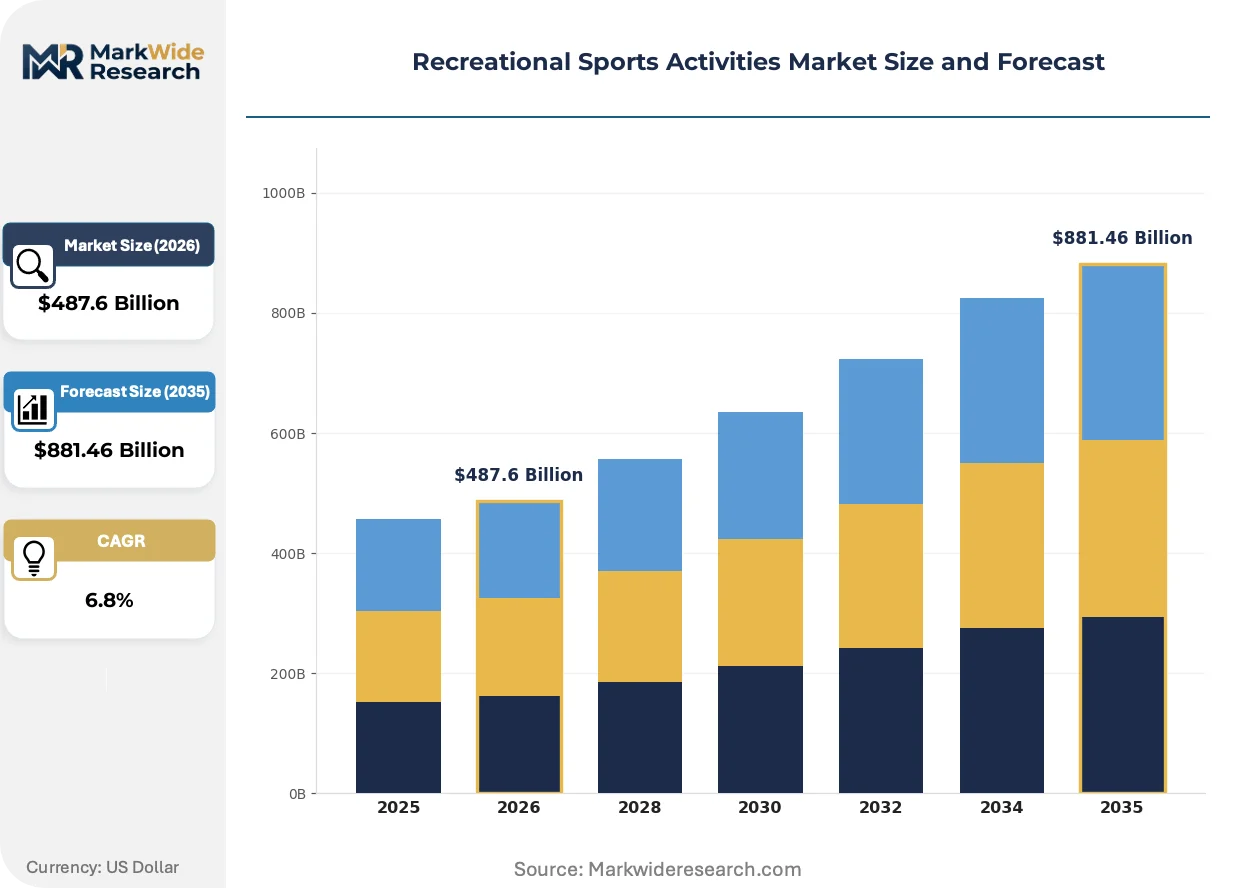
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $881.46 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Activity Type: Team Sports, Individual Sports, Adventure Sports, Water Sports Participation Level: Competitive, Recreational, Professional, Amateur Demographic: Children, Adults, Seniors, Families Equipment Type: Protective Gear, Apparel, Accessories, Sporting Equipment |
| Companies Covered | Selkirk Sport, TOCA Football, The Sports Facilities Companies, Splash Sports, Epic Padel, Legacy Sports Group, Playtomic, Seat Unique, Five Iron Golf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recreational Sports Activities Market Emerging Trajectories
Automated training systems and digital booking infrastructure are compressing the traditional facility-operator relationship, while regulatory layering around equipment safety and coach credentialing is reshaping competitive requirements.
Automated ball-delivery technology is bifurcating indoor soccer and golf training into self-directed practice sessions versus instructor-led instruction. Premium facilities in the United States and Spain are deploying these systems to extend operating hours without labor cost escalation. The technology is bifurcating membership tiers between algorithm-guided skill development and traditional coaching relationships, compressing mid-market positioning.
ASTM F1148 playground and recreational equipment standards are tightening impact-testing requirements for climbing structures and aerial adventure installations. Manufacturers serving United States facilities must recertify product lines against updated fall-height and surface-absorption metrics. Indoor climbing gym operators in California and Texas are responding by extending equipment replacement cycles and negotiating supplier warranty terms.
Corporate procurement of recreational sports benefits is consolidating through third-party wellness platform aggregators rather than direct facility contracting. Human resources departments at United States technology and professional services firms are shifting budget authority to integrated wellness vendors that bundle gym access, mental health apps, and nutrition counseling. This channel migration is most visible in metropolitan United States markets where facility density supports platform-scale aggregation.
Recreational Sports Activities Market Segmentation
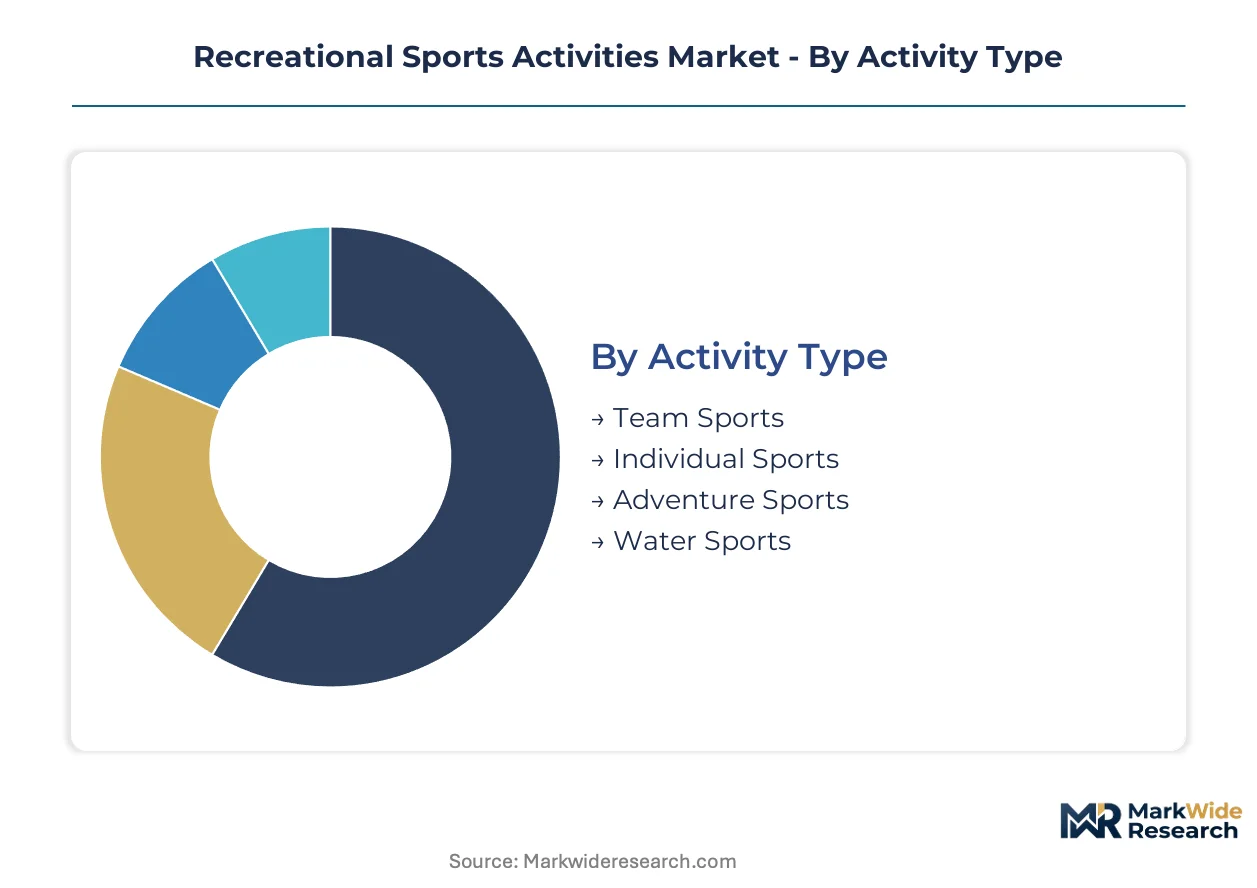
Segmentation in recreational sports reveals how ISO 203, ASTM F1148, and EN 913 certification requirements fragment procurement strategies across facility operators and consumer buyers. Equipment safety classifications and coach credentialing standards create distinct purchasing workflows that reshape channel economics and margin structures.
Activity Type:
ISO 203 surface-impact standards and ASTM F1148 fall-height protocols apply differentially across activity categories, with climbing structures and aerial installations facing the most stringent recertification timelines.
- Team Sports:League infrastructure and recurring facility rental contracts generate the largest revenue pool. Municipal bond issuances in the United States are accelerating multi-sport complex development, while corporate wellness programs expand adult league registrations through insurance premium incentives.
- Adventure Sports:Climbing gyms, aerial parks, and guided outdoor experiences attract younger demographics seeking shareable experiential consumption. California and Texas operators are extending equipment replacement cycles as ASTM F1148 impact-testing requirements tighten for fall-height and surface-absorption metrics.
- Individual Sports:Self-directed practice formats reduce coach dependency and extend facility operating hours. Automated ball-delivery systems in indoor golf and soccer training compress labor costs while enabling algorithm-guided skill development tiers.
- Water Sports:Specialized facility requirements and seasonal demand patterns limit geographic penetration to coastal and lake-adjacent markets. Equipment corrosion standards and lifeguard certification protocols add operational complexity.
Established volume favors Team Sports; emerging adoption favors Adventure Sports.
Participation Level:
Cost tier differentiation separates facility access fees from instruction premiums, with competitive and professional segments commanding certified coaching surcharges that amateur and recreational tiers avoid.
- Competitive:League infrastructure and tournament travel create recurring revenue streams through registration fees, officiating services, and sanctioned equipment mandates. United States youth sports concussion protocols are mandating protective gear upgrades and documented incident response procedures.
- Recreational:Casual participation through drop-in access and digital booking platforms captures price-sensitive demand. Playtomic's court-booking infrastructure across European club networks illustrates how technology reduces friction for informal scheduling.
- Professional:Elite training facilities require specialized surfaces, motion-capture systems, and sports science staff that limit addressable market to metropolitan clusters with corporate sponsorship density.
- Amateur:Entry-level programming relies on volunteer coaching and municipal facility subsidies, constraining margin expansion but building pipeline conversion to competitive tiers.
Margin concentration sits with Competitive tiers; volume scaling depends on Recreational participation.
Demographic:
Application-driven facility design separates child-safe impact surfaces from adult performance specifications, with family-oriented venues requiring multi-generational programming breadth that strains coach certification coverage.
- Children:State-level youth sports regulations in the United States mandate protective equipment upgrades and certified coach training that extend facility onboarding timelines. ASTM F1148 playground standards govern climbing structure specifications for indoor recreation centers.
- Adults:Corporate wellness procurement through third-party platform aggregators is consolidating budget authority away from direct facility contracting. Human resources departments at technology and professional services firms favor bundled wellness vendors.
- Seniors:Low-impact programming and adaptive equipment specifications address mobility constraints, with Medicare Advantage supplemental benefits increasingly covering recreational facility memberships.
- Families:Multi-pass pricing and cross-generational league formats maximize per-visit revenue but require redundant staffing across age-appropriate coaching certifications.
Corporate sponsorship anchors Adult demand; regulatory compliance shapes Children segment economics.
Equipment Type:
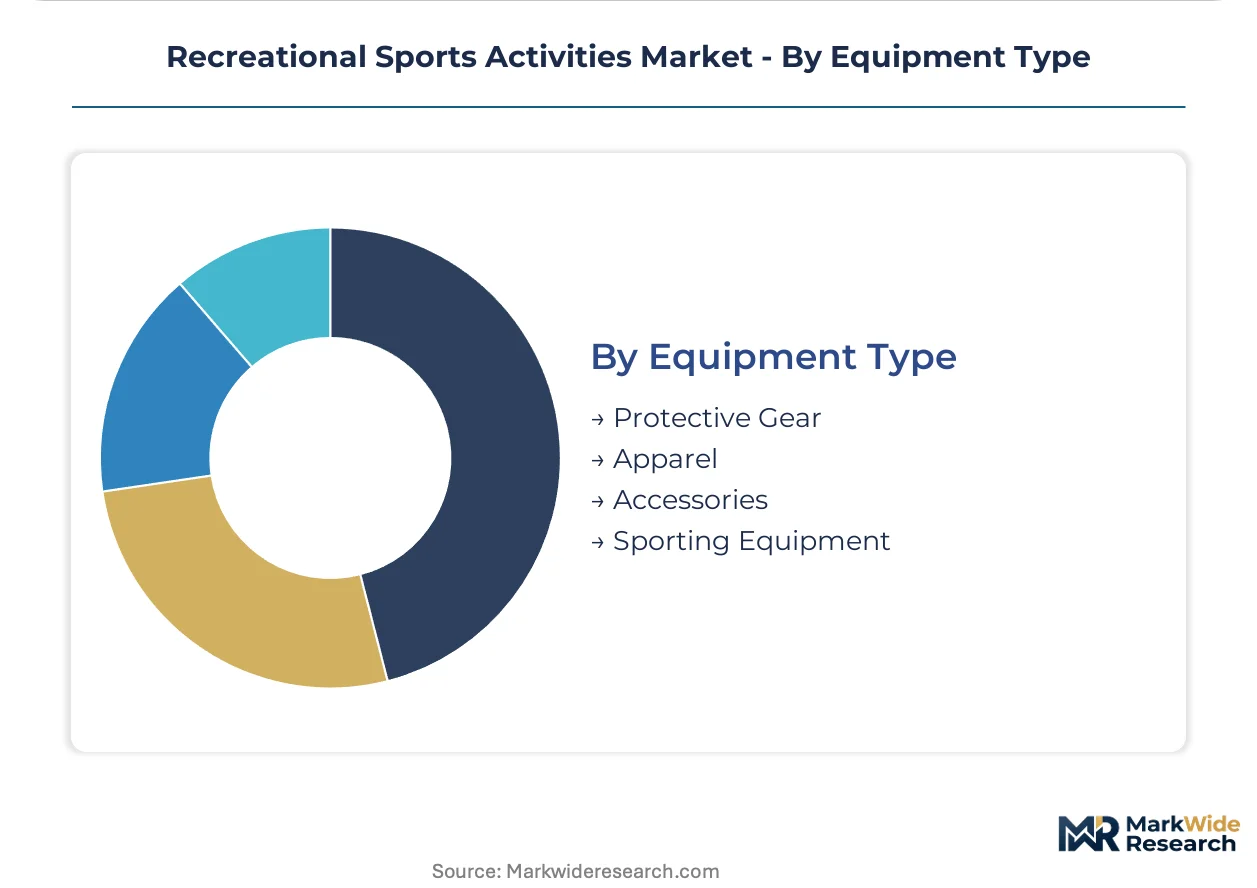
Supply concentration in protective gear manufacturing creates premium margin capture for certified headgear and joint supports, while apparel and accessories face commoditization from unbranded import competition.
- Protective Gear:Liability-conscious facilities mandate certified headgear, joint supports, and impact-absorbing surfaces that command premium margins. ISO 203 standardized safety testing reduces liability exposure and enables insurance coverage expansion.
- Sporting Equipment:Padel rackets, pickleball paddles, and indoor golf simulators require specialized manufacturing scale that Selkirk Sport and TOCA Football have captured through vertical integration and automated delivery technology.
- Apparel:Performance fabrics and team uniform contracts generate recurring replacement cycles, though direct-to-consumer e-commerce compresses wholesale channel margins.
- Accessories:Sensor-enabled performance tracking devices and wearable technology create subscription revenue streams beyond physical equipment sales, with motion-capture integration expanding in premium United States facilities.
Certification requirements concentrate margin in Protective Gear; technology integration drives Accessories expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace wellness incentives and municipal infrastructure bonds anchor United States demand, while ISO 203 and ASTM F1148 certification requirements reshape facility economics across developed markets. Urban recreational infrastructure investments concentrate in metropolitan clusters with corporate sponsorship density.
United States
Corporate wellness programs and insurance premium reductions expand facility memberships among working adults. State-level concussion protocols mandate protective equipment upgrades and certified coach training. California and Texas climbing gym operators extend equipment replacement cycles as ASTM F1148 impact-testing requirements tighten.
Spain
Padel court construction and indoor golf center development accelerate through private facility investment. Coach certification bottlenecks at accrediting bodies extend hiring timelines for certified instructors. Madrid and Barcelona anchor European recreational club network expansion through Playtomic's digital booking infrastructure.
Germany
EN 913 equipment safety standards govern protective gear procurement for climbing gyms and aerial parks. Municipal sports complex development receives federal infrastructure funding allocation. Bavaria and North Rhine-Westphalia concentrate multi-sport facility construction with integrated corporate wellness programming.
United Kingdom
Adaptive reuse of retail anchors and industrial warehouses creates lower-cost conversion opportunities for indoor sports centers. Third-party wellness platform aggregators consolidate corporate procurement budget authority. Greater London and Manchester metropolitan areas lead private facility development with sensor-enabled performance tracking integration.
Australia
Coastal water sports facilities face seasonal demand patterns and specialized corrosion standards for equipment. Medicare Advantage supplemental benefits increasingly cover recreational facility memberships for senior programming. New South Wales and Victoria climbing gym operators navigate ASTM F1148-equivalent local standards for fall-height compliance.
Recreational Sports Activities Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with equipment manufacturers and facility operators occupying distinct competitive spaces. The market structure separates vertically integrated equipment producers from technology-enabled training platforms and digital infrastructure providers. Three archetypes dominate: manufacturing-scale equipment suppliers, automated training system developers, and court-booking platform operators. Competitive moves concentrate on geographic expansion through facility franchising and technology licensing partnerships.
Among United States-based equipment specialists, Selkirk Sport and TOCA Football exemplify divergent scale strategies. Selkirk Sport occupies a position within the manufacturing-scale tier for racket sports equipment. TOCA Football anchors the automated training technology segment through ball-delivery system integration. European digital infrastructure representation includes Playtomic, which sits within the platform-operator archetype across club network aggregation.
| Leading Market Players |
|---|
| Selkirk Sport |
| TOCA Football |
| The Sports Facilities Companies |
| Splash Sports |
| Epic Padel |
| Legacy Sports Group |
| Playtomic |
| Seat Unique |
| Five Iron Golf |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day equipment certification lead times for ISO 203 and ASTM F1148 testing compress facility procurement cycles and concentrate pricing power with accredited manufacturers who maintain approved inventory buffers. This inventory constraint feeds directly into premium capture for protective gear and certified surfaces, while facilities absorbing longer lead times face compressed margins on member acquisition timelines.
Pricing Analysis
United States facility access fees run 40-60% above Spanish and German equivalents, reflecting liability insurance burdens and certified coach wage premiums. Pricing stratifies across premium automated-training tiers, standard instructor-led programming, and economy self-service access. Cost compression in economy tiers is intensifying because polyurethane feedstock volatility squeezes surface material suppliers. Corporate wellness buyers show lowest price sensitivity; amateur recreational participants exhibit highest elasticity.
Supply Chain Analysis
Strategic stockpiling of certified protective gear dominates inventory strategy given six-month recertification windows for ASTM F1148 compliance. Manufacturing concentrates in China for sporting equipment, the United States for automated training systems, and Germany for EN 913-certified protective apparatus. Supply chains draw from petrochemical derivatives for surface materials, aluminum alloys for climbing hardware, and semiconductor components for sensor-enabled accessories. Single-source vulnerability sits with automated ball-delivery system manufacturers. Distribution runs through facility-direct procurement for capital equipment and third-party wellness platform aggregators for corporate membership contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from unstructured outdoor recreation—hiking, cycling, and running—that captures price-sensitive participants without facility overhead. Defense requires differentiation through technology integration and certification moats that unstructured alternatives cannot replicate.
For Market Incumbents: Fortify automated training system deployments to extend operating hours without certified coach dependency, compressing labor cost structures that unstructured outdoor substitutes cannot match. Deepen backward integration into polyurethane surface manufacturing to hedge petrochemical feedstock volatility. Prioritize ISO 203 certification maintenance as a barrier against uncertified import competition.
For New Entrants and Emerging Players: Fast-track coach certification through Spain's expanding accrediting body partnerships offers facility staffing advantages as established markets face instructor shortages. Target adaptive reuse real estate conversions in suburban United States retail vacancies where lower-cost entry offsets competitive density. Deploy sensor-enabled performance tracking as a differentiated subscription revenue layer atop facility access fees.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified entertainment conglomerates with underoptimized recreational sports divisions lacking digital infrastructure investment. Long-term viability hinges on technology-enabled training platform ownership rather than pure facility real estate. Watch corporate wellness procurement consolidation through third-party aggregators as an inflection signal—platform-scale aggregation favors acquired technology stacks over standalone facility operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Training System Deployment | TOCA Football's ball-delivery technology extends facility operating hours without labor cost escalation. |
| Coach Certification Fast-Track Partnership | Accrediting body capacity expansion in Spain and the United States accelerates member acquisition velocity. |
| Adaptive Reuse Real Estate Conversion | Vacant retail anchors in suburban United States markets offer lower-cost entry for indoor golf and padel centers. |
| Sensor-Enabled Performance Tracking Integration | Motion-capture subscriptions create recurring revenue beyond facility access fees in premium United States markets. |
| Corporate Wellness Platform Aggregation | Third-party bundling of gym access, mental health apps, and nutrition counseling consolidates procurement budget authority. |
Methodological Framework
A spread of perspectives from facility operators, equipment procurement managers, certified coaching directors, and corporate wellness benefits administrators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through ISO certification databases, ASTM standards documentation, municipal bond issuance records for recreational infrastructure, and OSHA workplace wellness incentive filings. Bottom-up facility capacity modeling and top-down consumer expenditure analysis triangulated market sizing across the projection horizon.
Segmentation dimensions modeled include activity type, participation level, demographic cohort, and equipment category, with geographic regulatory cluster as an additional cross-cutting variable. CAGRs were derived from installed facility base expansion rates, equipment replacement cycles, and digital platform subscription attach rates. Forecast inputs incorporated coach certification pipeline constraints, petrochemical feedstock price trajectories, and corporate wellness program penetration curves.
The analysis sits within stated boundaries; outcomes outside sustained municipal infrastructure investment levels or accelerated ISO certification timelines would require recalibration. Forecasts reflect documented assumptions around facility development financing availability and employer wellness subsidy durability. Revision becomes warranted when unstructured outdoor recreation participation crosses threshold levels that materially compress facility membership growth rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Trekking Poles Market
Outdoor and Adventure Activities
Ski Gear and Equipment Market
Outdoor and Adventure Activities
Paragliding Equipment Market
Outdoor and Adventure Activities
Snowshoes Market
Outdoor and Adventure Activities
Parasailing Equipment Market
Outdoor and Adventure Activities
Global Inflatable Outdoor Leisure Product Market
Outdoor and Adventure Activities
Global Water Bikes Market
Outdoor and Adventure Activities
Global Hydration Backpack Market
Outdoor and Adventure Activities
Outdoor Living Product Market
Outdoor and Adventure Activities
Adventure Sports and Activities Market
Outdoor and Adventure Activities
Outdoor Backpack Market
Outdoor and Adventure Activities
Hunting Rangefinder Market
Outdoor and Adventure Activities
Hydration Packs Market
Outdoor and Adventure Activities
India Spectator Sports Market
Outdoor and Adventure Activities
Global Climbing Holds Market
Outdoor and Adventure Activities
Ski Vacation Market