
 Spain Sports Tourism Market | 2026-2036
Spain Sports Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Sports Tourism Market Analytics
Project finance for destination sports complexes is reconfiguring competitive entry barriers across Spain's sports tourism landscape. Kaptiva Sports Travel leverages its vertical integration into academy operations and lodging to sustain margin capture across the value chain. Agency Sports and Travel Europe anchors its position through exclusive partnerships with La Liga clubs for stadium access and player meet-and-greet programming. CN Sports Tourism differentiates via technology leadership in dynamic pricing platforms for event ticketing and hospitality bundling.
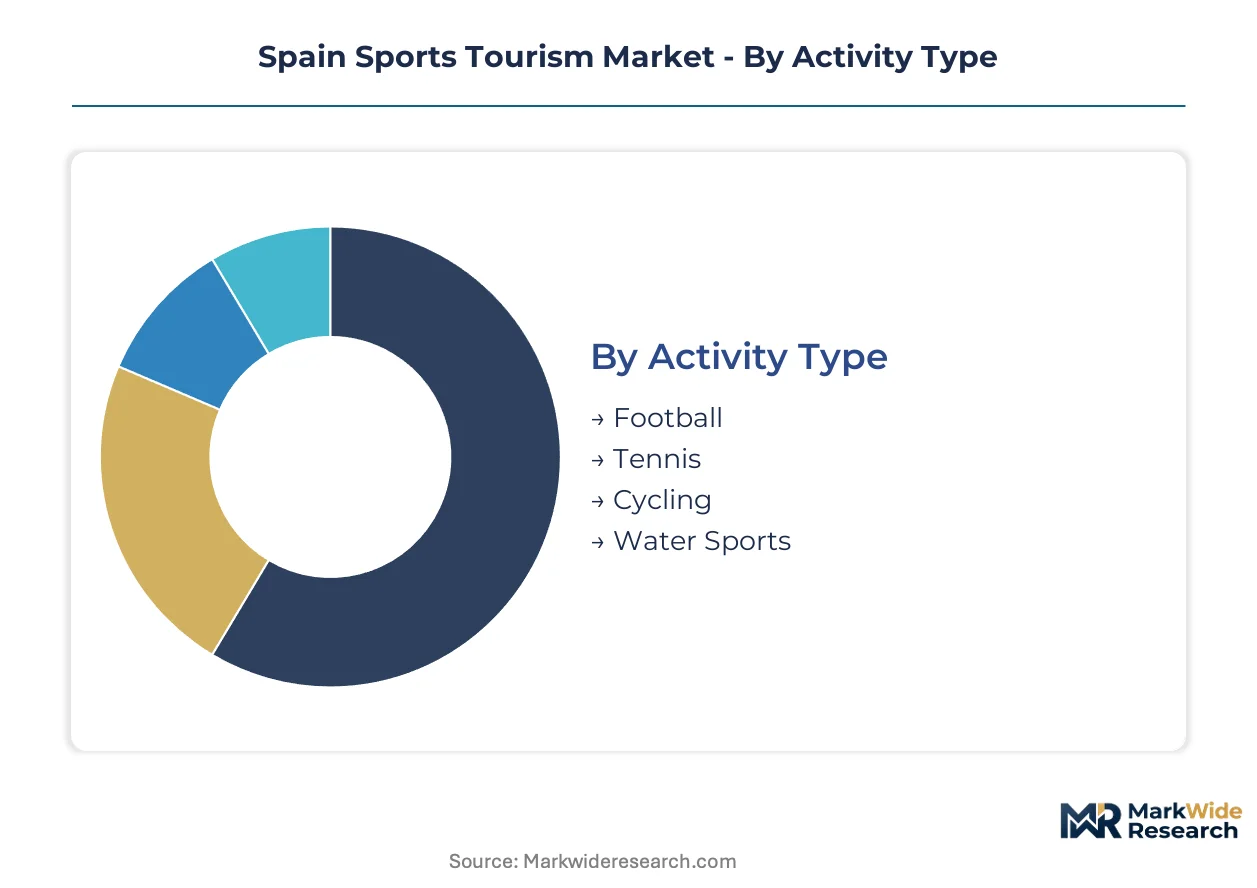
Sports tourism encompasses organized travel where participation in or attendance at sporting activities constitutes the primary purpose, typically involving specialized infrastructure such as FIFA-certified pitches, UCI-graded cycling routes, or RYA-accredited sailing centers designed to host training, competition, or spectator experiences. The sector generates economic value through accommodation, transport, food service, and ancillary retail spend tied to athletic events. Football commands the largest activity-type revenue pool given Spain's stadium inventory and club brand equity, while cycling experiences the fastest growth trajectory driven by Gran Fondo participation and pro-team training camp demand. Training camps within the travel-purpose dimension yield superior per-visitor spend compared to leisure segments, concentrating margin pools in facilities offering integrated coaching, recovery, and analytics services.
Spain's Ministry of Industry, Trade and Tourism enforces national sports tourism quality certifications that standardize facility safety, environmental management, and service protocols for operators seeking official designation. Regional governments in Andalusia, Catalonia, and the Valencian Community layer additional licensing requirements for water sports providers and cycling tour operators that shape market access conditions. The General Secretariat for Tourism coordinates with autonomous communities to align subsidy programs for infrastructure investment with EU Green Deal criteria on energy efficiency and sustainable mobility. Stakeholders must monitor how pending amendments to coastal law affect water sports concessions and whether Basque Country and Canary Islands tax incentives for sports facility development trigger competitive relocation of training camp investments.
Market Dynamics
Spain's updated national sports tourism certification framework under the Ministry of Industry, Trade and Tourism is tightening facility standards and operator accountability, forcing infrastructure upgrades across Andalusian complexes while concentrating demand in climate-advantaged zones around Málaga and Seville.
Growth Catalysts
- EU Green Deal alignment:Subsidy programs for infrastructure investment now require energy efficiency and sustainable mobility compliance, directing capital toward certified facilities.
- Amateur football academies:International youth teams seek structured training environments, driving fastest-expanding end-use demand for integrated coaching and recovery services.
- Gran Fondo participation:Pro-team training camp demand accelerates cycling infrastructure investment across Catalonia and the Valencian Community.
Market Restraints
- Coastal law uncertainty:Pending amendments to water sports concessions create investment paralysis for marina-dependent operators in the Balearic Islands.
- Labor cost escalation:Specialized coaching and sports medicine talent commands premium wages, compressing margins at mid-tier facilities.
- Regional licensing fragmentation:Andalusia, Catalonia, and the Valencian Community impose divergent requirements for cycling tour operators, multiplying compliance overhead.
Strategic Opportunities
- Basque Country tax incentives:Sports facility development subsidies threaten competitive relocation of training camp investments from saturated southern markets.
- Dynamic pricing platforms:Technology convergence between hospitality bundling and event ticketing opens margin capture in visitor spend optimization.
- Canary Islands positioning:Year-round climate advantage remains underexploited for winter training camps relative to established Mediterranean competitors.
Industry Challenges
- FIFA pitch certification timelines:Extended approval cycles for surface quality standards delay academy opening dates and revenue recognition.
- Analytics integration complexity:Legacy facility management systems resist seamless connection with player performance tracking and recovery monitoring technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Sports Tourism Market |
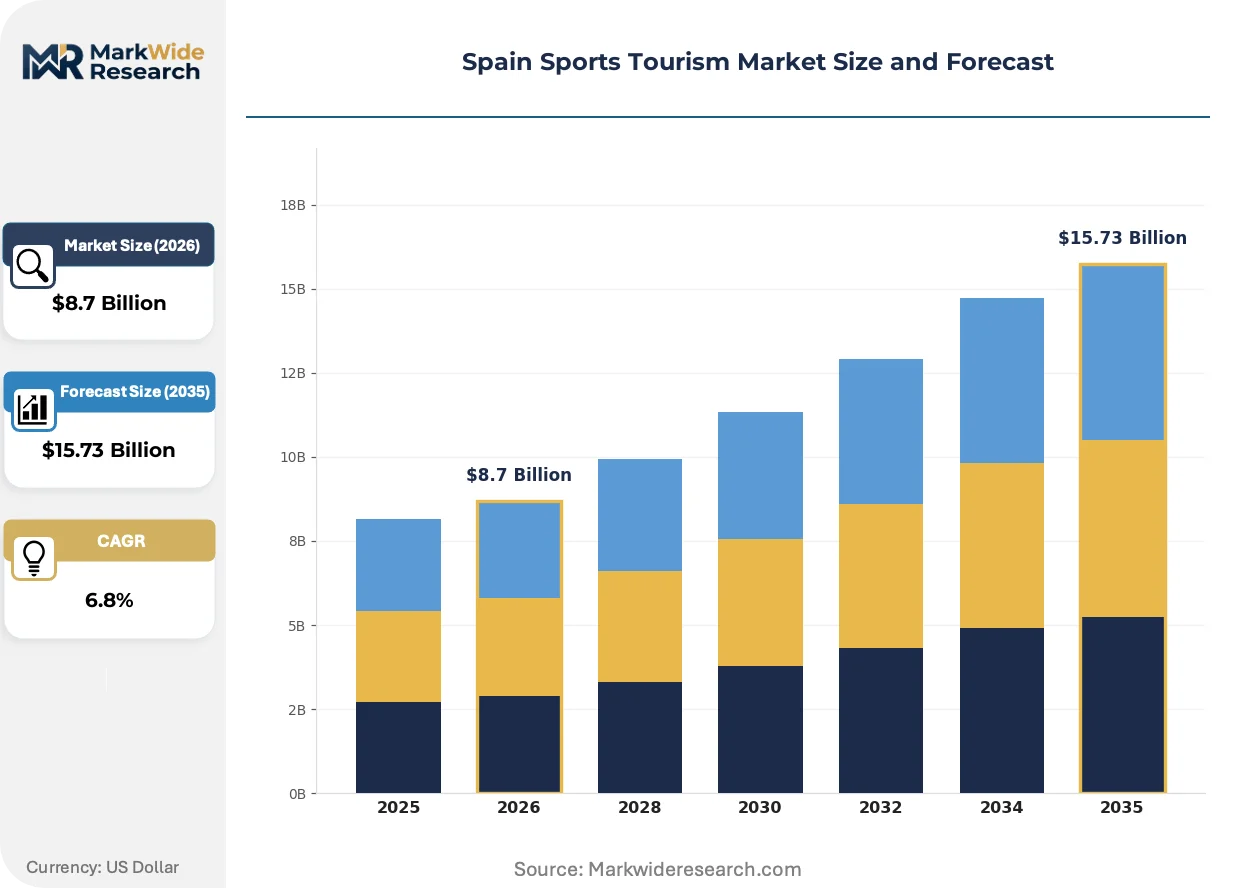
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Activity Type: Football, Tennis, Cycling, Water Sports Travel Purpose: Leisure, Competition, Training Camps, Events Customer Type: Individuals, Groups, Families, Professionals Service Type: Accommodation, Guided Tours, Ticketing, Rentals |
| Companies Covered | Oentours, Agency Sports and Travel Europe, CN Sports Tourism, Just Explore, Spain Sports Tour, Kaptiva Sports Travel, Spain Essential Travel, Costa Excursions, Jolly DMC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Sports Tourism Market Evolving Landscape
Technology integration and regulatory tightening are compressing competitive timelines across Spain's sports tourism infrastructure, with operators racing to deploy certified systems before subsidy windows close and demand concentrates in premium-tier facilities.
Biomechanical tracking systems embedded in training pitches are capturing real-time player load data for injury prevention and performance optimization. Elite football academies in Catalonia are deploying these surfaces at scale, replacing conventional turf installations. This sensor infrastructure is hybridizing facility operations by merging physical infrastructure with digital service layers, enabling per-visitor analytics upsells that training camps now bundle into premium packages.
Spain's Ministry of Industry, Trade and Tourism coordinates certification alignment with EU Green Deal criteria, mandating energy efficiency audits for official sports tourism designation. Facility operators face capital expenditure thresholds for solar integration and sustainable mobility access. Andalusian complexes around Málaga are responding fastest, leveraging existing subsidy pipelines to secure competitive certification ahead of 2025 compliance deadlines.
Buyer concentration among international youth football academies is shortening vendor selection cycles and unbundling traditional package components. Training camp procurement now separates lodging, coaching, and analytics services for competitive tender. This pattern is most visible in Seville, where academy directors negotiate directly with specialized recovery clinics and independent coaching collectives rather than accepting bundled resort offerings.
Spain Sports Tourism Market Segmentation
Segmentation in Spain's sports tourism market reveals how distinct visitor profiles and activity preferences concentrate economic value across infrastructure types. Understanding these divisions exposes where margin pools accumulate and which facility investments align with demand trajectories.
Activity Type:
Football cycles through visitor turnover fastest given academy scheduling intensity, while water sports exhibit the longest booking lead times tied to seasonal wind and wave patterns.
- Football:FIFA-certified pitches and stadium infrastructure anchor the largest revenue pool. International youth academies cluster around Málaga and Seville complexes where climate permits year-round programming, compressing facility utilization cycles.
- Cycling:UCI-graded routes and Gran Fondo participation drive the steepest expansion trajectory. Pro-team training camp demand concentrates in Catalonia and the Valencian Community where gradient variety and road quality meet professional standards.
- Tennis:Clay court traditions and ATP tournament circuits sustain steady demand from Eastern European and Middle Eastern training groups seeking surface-specific preparation.
- Water Sports:RYA-accredited sailing centers and surf camps depend on coastal concession stability, with pending amendments to Spanish coastal law creating investment uncertainty for Balearic operators.
Football dominates installed base across certified facilities. Cycling is where expansion concentrates as infrastructure investment follows pro-team relocation patterns.
Travel Purpose:
Cost tiers separate this category sharply, with training camps commanding premium pricing against standardized leisure packages.
- Training Camps:Integrated coaching, recovery, and analytics services yield superior per-visitor spend. Biomechanical tracking systems embedded in Catalonian pitches enable real-time player load data upsells bundled into premium packages.
- Events:La Liga stadium access and player meet-and-greet programming drive hospitality bundling complexity. Dynamic pricing platforms capture margin through ticket and accommodation optimization.
- Leisure:Self-directed participation with lower service integration compresses margins at mid-tier facilities unable to differentiate through certification tier.
- Competition:Tournament hosting requires compliance with national sports tourism quality certifications under Spain's Ministry of Industry, Trade and Tourism, favoring operators with completed infrastructure upgrades.
Training camps capture the highest margin per visitor. Leisure segments sustain volume throughput across secondary facilities.
Customer Type:
Volume concentration varies dramatically, with groups generating block bookings that stabilize occupancy against individual traveler volatility.
- Groups:International youth football teams and cycling clubs negotiate directly with specialized recovery clinics and independent coaching collectives, unbundling traditional resort packages.
- Professionals:Elite athletes and sports medicine tourists demand analytics integration and legacy facility management system compatibility, extending procurement cycles.
- Families:Multi-generational travel combines participant and spectator roles, concentrating demand in Andalusian complexes with adjacent non-sports amenities.
- Individuals:Solo travelers fill shoulder-season capacity at lower price points, particularly in Canary Islands facilities seeking to exploit year-round climate advantage.
Groups dominate forward booking visibility. Professionals concentrate margin capture in certified premium-tier facilities.
Service Type:
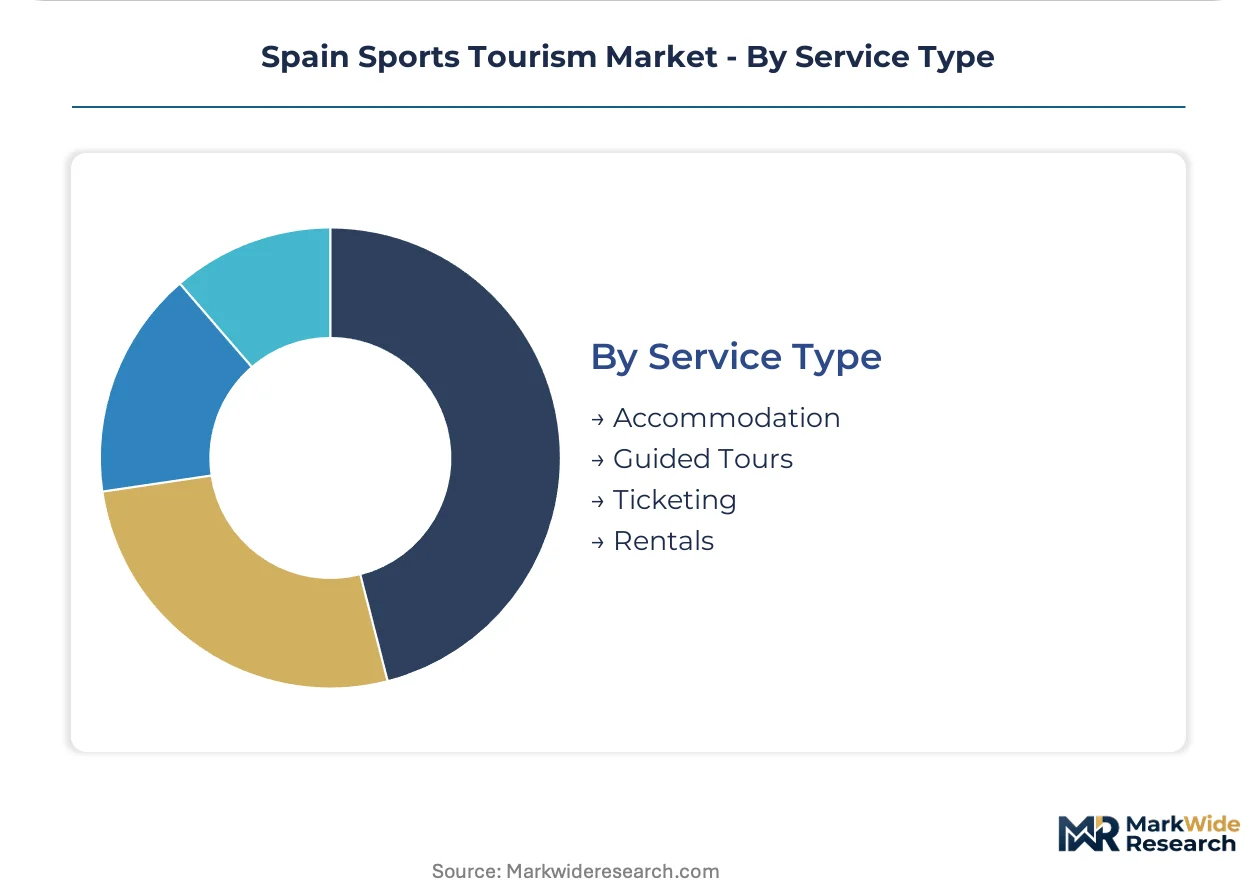
Supply concentration clusters in accommodation and ticketing, while guided tours and rentals fragment across regional operators.
- Accommodation:Vertical integration into lodging sustains margin capture across the value chain for operators controlling both pitch access and bed inventory.
- Ticketing:Technology leadership in dynamic pricing platforms differentiates operators capable of hospitality bundling and visitor spend optimization.
- Guided Tours:Cycling route expertise and local knowledge requirements create barriers for non-specialized entrants, particularly in Basque Country where terrain complexity demands certified guides.
- Rentals:Equipment provision concentrates in coastal zones and ski resorts, with EU Green Deal alignment requirements pushing fleet electrification investments.
Accommodation dominates capital deployment. Ticketing technology is where competitive differentiation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's sports tourism sector generates substantial inbound revenue with limited outbound leakage, creating a favorable trade balance concentrated in southern and eastern coastal zones where climate-advantaged infrastructure draws international training groups.
Andalusia
International youth football academies and Gran Fondo cycling camps drive demand concentration around Málaga and Seville. The regional government layers licensing requirements for cycling tour operators atop national Ministry of Industry, Trade and Tourism certification standards. Climate-permissive complexes in the Costa del Sol corridor are capturing training camp investments that seek year-round programming capability.
Catalonia
Pro-team cycling training camps and elite football academy demand concentrate in Barcelona-adjacent facilities. The Generalitat enforces additional environmental management protocols for sports tourism operators seeking regional subsidy eligibility. Biomechanical tracking systems embedded in training pitches around the province are enabling real-time player load data services bundled into premium packages.
Valencian Community
UCI-graded cycling routes and professional team relocation patterns are accelerating infrastructure investment across the region. Regional licensing requirements for water sports providers create compliance overhead distinct from Andalusian and Catalan frameworks. Castellón and Alicante provinces are developing integrated coaching and recovery service clusters to capture training camp margin pools.
Basque Country
Tax incentives for sports facility development are threatening competitive relocation of training camp investments from saturated southern markets. The regional administration coordinates subsidy programs with EU Green Deal criteria on energy efficiency and sustainable mobility. San Sebastián and Bilbao are emerging as alternative destinations for cycling terrain complexity that demands certified guide expertise.
Canary Islands
Year-round climate advantage remains underexploited for winter training camps relative to established Mediterranean competitors. The autonomous community maintains distinct concession frameworks for coastal sports facilities pending national coastal law amendments. Tenerife and Gran Canaria complexes are targeting individual travelers to fill shoulder-season capacity at lower price points.
Spain Sports Tourism Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying discrete services to unbundled procurement. The vendor base organizes around three strategic archetypes: vertically integrated academy-lodging operators, exclusive partnership brokers securing stadium access and player programming, and technology leaders deploying dynamic pricing platforms for hospitality bundling. Competitive moves concentrate on backward integration into captive accommodation supply and technology licensing for visitor spend optimization.
Among Spain-based operators, Agency Sports and Travel Europe, CN Sports Tourism, and Kaptiva Sports Travel occupy distinct positioning vectors. Agency Sports and Travel Europe exemplifies the exclusive partnership archetype through its La Liga club relationships. CN Sports Tourism represents technology leadership in ticketing and hospitality convergence. Kaptiva Sports Travel anchors the vertically integrated tier controlling both pitch access and bed inventory. Each sits within a defendable margin pool as buyer concentration among international youth academies shortens vendor selection cycles.
| Leading Market Players |
|---|
| Oentours |
| Agency Sports and Travel Europe |
| CN Sports Tourism |
| Just Explore |
| Spain Sports Tour |
| Kaptiva Sports Travel |
| Spain Essential Travel |
| Costa Excursions |
| Jolly DMC |
| Others |
Value Network & Pricing Analysis
Andalusian complexes around Málaga and Seville concentrate certified pitch capacity, translating climate advantage into pricing power for training camp operators who capture premium rates through integrated lodging and coaching bundles.
Pricing Analysis
International youth football academies anchor a three-tier pricing structure across premium, standard, and economy levels, with certification tier under Spain's Ministry of Industry, Trade and Tourism and volume scale as primary differentiation drivers. Cost compression in mid-tier facilities is intensifying because specialized coaching and sports medicine talent commands premium wages. Academy directors demonstrate highest price sensitivity when unbundling lodging from coaching services, while pro-team training camps show lowest sensitivity to analytics integration upsells.
Supply Chain Analysis
Extended payment terms from facility operators to independent coaching collectives and recovery clinics are stretching working capital cycles across the value chain. Supply concentrates in Spain, Portugal, and Morocco for climate-advantaged training infrastructure, with raw material dependencies on FIFA-certified turf systems, biomechanical sensor arrays, and sports medicine equipment. Single-source vulnerability sits with specialized pitch certification bodies whose extended approval timelines delay revenue recognition. Distribution runs through direct procurement relationships between academy directors and unbundled service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified FIFA pitch infrastructure and EU Green Deal compliance expertise represent scarce capabilities that concentrate margin capture among operators who secured subsidy windows ahead of regulatory deadlines.
For Market Incumbents: Pre-empt competitive relocation of training camp investments by securing Basque Country and Canary Islands tax incentive eligibility before facility saturation triggers subsidy exhaustion. Backward integration into captive accommodation supply defends margin pools against unbundling pressure from academy procurement teams. Certification investment ahead of 2025 compliance deadlines locks in premium-tier positioning. For New Entrants and Emerging Players: Winter training camps in the Canary Islands represent the most penetrable entry point given underexploited year-round climate advantage relative to established Mediterranean competitors. Dynamic pricing platform development for hospitality bundling offers technology-led market access without heavy pitch infrastructure commitments. Direct sales to independent academy directors bypass entrenched resort relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with embedded biomechanical tracking infrastructure and proven EU Green Deal certification pathways. Long-term viability rests on analytics service recurring revenue rather than transactional pitch rental. Watch FIFA pitch certification approval velocity as inflection indicator for facility revenue recognition timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU Green Deal Certification | Spain's Ministry of Industry, Trade and Tourism mandates energy audits for official designation eligibility. |
| Biomechanical Tracking Integration | Real-time player load data services enable premium package upsells in Catalonian facilities. |
| Backward Integration into Lodging | Kaptiva Sports Travel's model sustains margin capture across academy operations and bed inventory. |
| Dynamic Pricing Platform Deployment | CN Sports Tourism's technology leadership optimizes visitor spend through hospitality bundling convergence. |
| Exclusive La Liga Partnership | Agency Sports and Travel Europe secures stadium access and player meet-and-greet programming differentiation. |
Research Methodology
A spread of perspectives from academy directors, facility operators, regional tourism board officials, and sports medicine practitioners converged on the working assumptions driving segmentation and growth trajectory assessments. Primary interviews with these stakeholders combined with secondary validation against EU Green Deal policy documents, Spanish Ministry of Industry certification standards, and autonomous community subsidy program filings. Bottom-up facility capacity modeling and top-down inbound tourism expenditure analysis provided triangulation.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across activity type, travel purpose, customer type, and service type dimensions. CAGRs were derived from capacity utilization curves and per-visitor spend trajectories. Forecast inputs incorporated FIFA pitch certification pipeline data and pro-team training camp relocation patterns.
Practitioners should monitor coastal law amendment progress and Basque Country tax incentive utilization rates for early signals of competitive investment relocation. Forecasts reflect assumptions on subsidy program continuity and certification timeline stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Asia-Pacific Spectator Sports Market
Outdoor and Adventure Activities
Motorized Pool Tube Market
Outdoor and Adventure Activities
Hiking Backpacks Market
Outdoor and Adventure Activities
Parasailing Equipment Market
Outdoor and Adventure Activities
Outdoor Living Product Market
Outdoor and Adventure Activities
Global Climbing Holds Market
Outdoor and Adventure Activities
Hunting Rangefinder Market
Outdoor and Adventure Activities
Wakeboard Market
Outdoor and Adventure Activities
Adventure Gear Market
Outdoor and Adventure Activities
Kayak Market
Outdoor and Adventure Activities
India Spectator Sports Market
Outdoor and Adventure Activities
Global Ski Poles Market
Outdoor and Adventure Activities
Ski Vacation Market
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
Climbing Harness Market
Outdoor and Adventure Activities
Power Sports Market