
 Snowshoes Market | 2026-2036
Snowshoes Market Size, Share, and Industry Trends Forecast 2026-2036
Snowshoes Market Insights
Specialty outdoor retail and direct-to-consumer channels is reshaping how snowshoes reach end users, with seasonal pop-up stores and regional outfitters gaining ground against big-box sporting goods. MSR leverages its Seattle-based engineering hub to sustain technical leadership in backcountry bindings and flotation geometry. Atlas Snowshoe Company anchors its position through Vermont manufacturing and deep relationships with Eastern U.S. Nordic centers. Crescent Moon Snowshoes differentiates via its single-bar binding system and concentrated presence in Rocky Mountain rental fleets.
Snowshoes are load-distributing footwear devices constructed from aluminum tubing, composite decking, or polymer frames with crampon-enhanced traction systems, designed to prevent foot sinkage in snow depths exceeding 30 centimeters and enable human locomotion across untracked terrain. Recreational aluminum models dominate unit volume through rental program penetration at Nordic ski areas and state park systems, while composite backcountry variants command premium positioning among avalanche-educated users seeking reduced frame weight for steep slope travel. Racing segments occupy a narrow but technically demanding niche governed by International Snowshoe Federation specifications for frame dimensions and binding release criteria.
ASTM International maintains F2387 for snowshoe structural integrity and binding retention, while the U.S. Forest Service trail permitting process influences commercial guided operation equipment standards across Wilderness Study Areas. Health Canada and the U.S. Consumer Product Safety Commission coordinate on seasonal recall protocols for binding component failures, tightening market access for uncertified imports. Stakeholders must monitor evolving backcountry access policies on federal lands and the pace of composite recycling infrastructure development as sustainability criteria penetrate procurement specifications.
Market Dynamics
Composite material substitution is restructuring competitive economics across snowshoe manufacturing, as carbon fiber and thermoplastic decking displace traditional aluminum tubing in performance segments and force incumbent suppliers to retool fabrication lines or cede premium positioning.
Growth Catalysts
- ASTM F2387 Safety Certification:Mandatory structural integrity testing creates barrier to entry for low-cost imports while elevating consumer confidence in certified brands across US retail channels.
- Backcountry Ski Resort Expansion:Colorado, British Columbia, and Utah operators are adding snowshoe-specific terrain zones with guided avalanche education programs, embedding equipment rental into lesson packages.
- Polymer Frame Injection Molding:Advances in glass-reinforced nylon compounds enable single-piece deck construction, cutting assembly labor and allowing rapid colorway customization for regional outfitters.
Market Restraints
- Aluminum Price Volatility:6061-T6 tubing costs fluctuate with LME aluminum futures, compressing margins on recreational-grade products where material cost share exceeds 35 percent.
- Seasonal Demand Concentration:North American purchase windows compress to November through February, forcing inventory carrying costs and obsolescence risk on distributors without Southern Hemisphere counter-seasonal markets.
- Cross-Country Ski Substitution:Groomed Nordic trail systems in Minnesota, Wisconsin, and Vermont draw overlapping user base with lower equipment cost and established instruction infrastructure.
Strategic Opportunities
- Japan Winter Tourism Recovery:Nagano and Hokkaido prefectures are expanding English-language snowshoe guiding permits, creating entry path for ASTM-certified manufacturers into rental fleet procurement.
- Forest Service Special Use Permits:Commercial guiding on federal Wilderness Study Areas requires documented equipment compliance, positioning certified suppliers for B2B contract capture.
- Direct-to-Consumer Subscription:Seasonal rental-by-mail models targeting urban millennials in Seattle, Denver, and Toronto bypass retail markup while capturing usage data for product development.
Industry Challenges
- Composite Technician Scarcity:Layup and cure process expertise concentrates in aerospace supply chains, forcing snowshoe manufacturers to train in-house or accept quality variance.
- Binding Release Mechanism Certification:International Snowshoe Federation testing protocols for racing segment require third-party validation cycles exceeding 18 months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snowshoes Market |
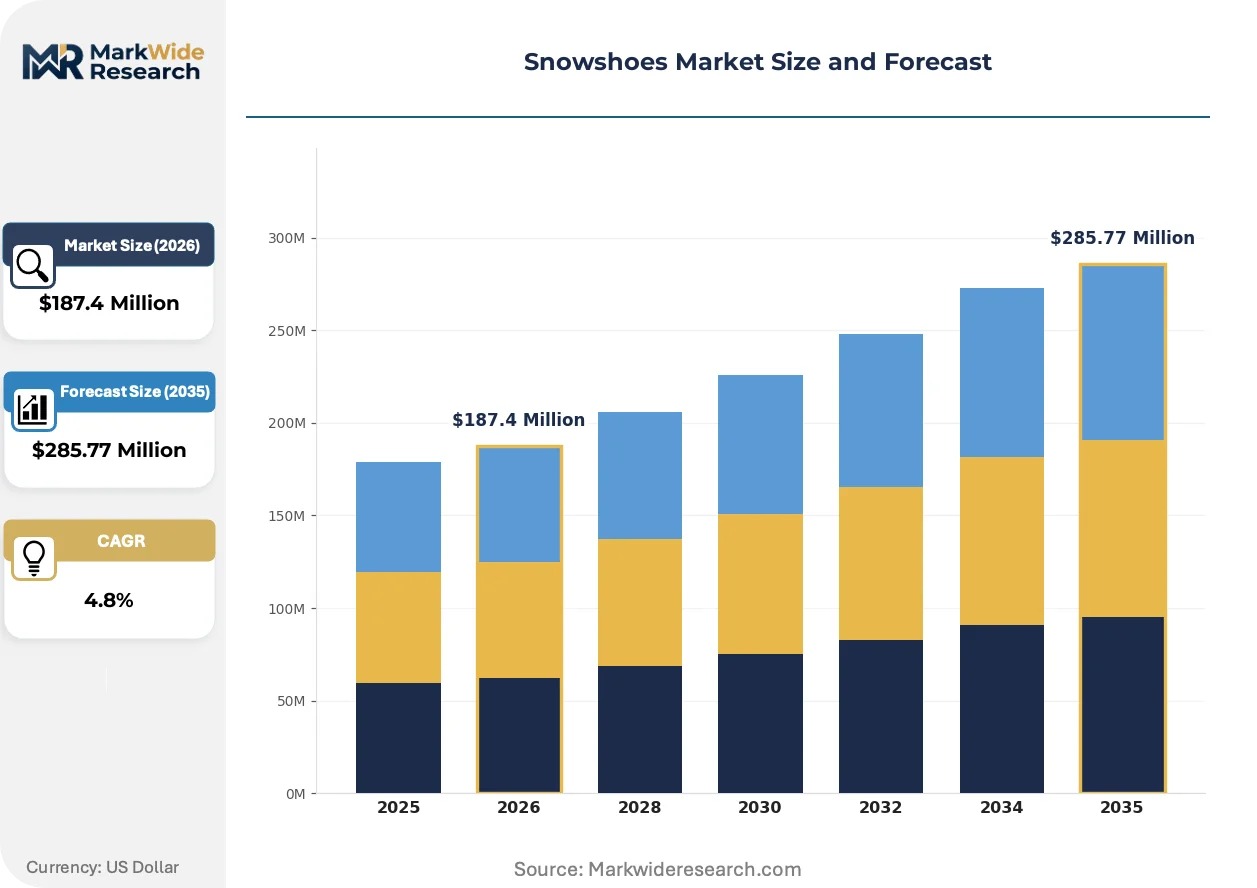
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recreational, Backcountry, Racing, Kids Material: Aluminum, Composite, Plastic, Wood Use Case: Leisure, Expeditions, Fitness, Hunting Size: Adult, Youth, Women's, Custom |
| Companies Covered | MSR, Atlas Snowshoe Company, Crescent Moon Snowshoes, Tubbs Snowshoes, GV Snowshoes, Fimbulvetr, Chinook Technical Outdoor, Garneau, L.L.Bean, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snowshoes Market Trends and Innovations
Digital design tools and predictive biomechanics are compressing product development cycles while regulatory harmonization efforts create new compliance pathways for multi-jurisdiction suppliers.
Generative design software is virtualizing frame topology optimization, enabling manufacturers to simulate load distribution across 10,000+ geometry permutations before cutting tooling. Backcountry specialists in Colorado and Alberta are adopting these digitally-optimized prototypes for field validation. This capability is virtualizing the traditional prototype-test-iterate cycle, collapsing 18-month development timelines to under 8 months.
Health Canada and the US Consumer Product Safety Commission have aligned seasonal recall protocols for binding component failures, creating synchronized compliance windows that reduce regulatory fragmentation. Manufacturers must now submit joint documentation packages for spring product launches. Racing and rental fleet segments face accelerated compliance timelines as both agencies prioritize youth-binding retention standards.
Rental program operators are unbundling equipment from instruction packages, shifting to per-hour pricing models at Nordic centers in Vermont and Quebec. This consumption-pattern shift pressures manufacturers to prioritize durability metrics over weight reduction for fleet sales. Colorado's state park system has piloted outcome-based rental agreements where suppliers bear replacement cost for frames failing before 500 rental cycles.
Snowshoes Market Segmentation
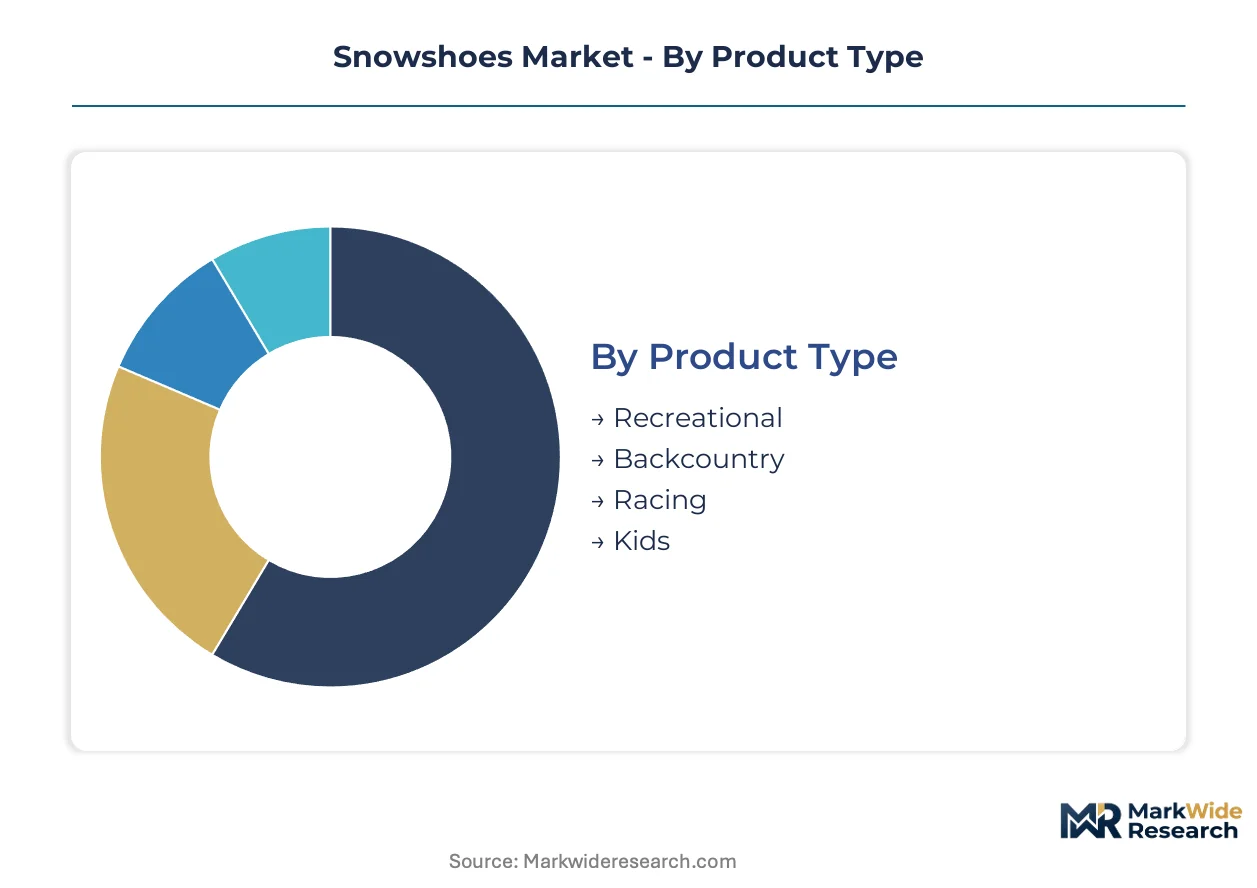
Snowshoe demand fragments across distinct performance tiers and user profiles, with material choices and terrain applications driving fundamentally different procurement criteria. Rental operators, backcountry guides, and retail consumers each impose separate specifications on frame geometry, binding systems, and durability metrics.
Product Type:
Recreational, backcountry, racing, and kids models span a use-case spectrum from flat-trail walking to technical alpine travel, with binding complexity and flotation geometry scaling to terrain demands.
- Recreational:Aluminum-tubing frames with simple strap bindings dominate rental fleets at Nordic centers and state parks. Demand concentrates in Minnesota, Wisconsin, and Quebec where groomed trail systems support novice entry.
- Backcountry:Aggressive crampon systems and heel-lift mechanisms enable steep slope travel for avalanche-educated users. Colorado's mountain resort corridors and Utah's Wasatch Range drive premium procurement as guided education programs expand.
- Racing:Ultra-lightweight composite construction governed by International Snowshoe Federation dimensional specifications. Narrow competitive niche centered on sanctioned events in New England and the Canadian Rockies.
- Kids:Scaled-down polymer frames with simplified binding interfaces for youth program enrollment. Vermont's Nordic centers and Ontario's provincial parks anchor fleet replacement cycles.
The dominant share belongs to Recreational models, while Backcountry is closing the gap fastest.
Material:
Frame composition determines weight-to-strength ratios, manufacturing capital requirements, and end-user price acceptance across the cost tier structure.
- Aluminum:6061-T6 tubing remains the baseline for rental-grade products, though LME price volatility compresses margins on entry-level SKUs. Eastern U.S. manufacturers maintain established supply relationships with domestic extruders.
- Composite:Carbon fiber and glass-reinforced layups command premium positioning in backcountry and racing segments. Layup expertise concentrates in aerospace-adjacent supply chains, forcing snowshoe specialists to train technicians in-house.
- Plastic:Injection-molded polymer decks enable single-piece construction with rapid colorway customization for regional outfitters. Glass-reinforced nylon compounds from compounders in Ohio and Michigan feed assembly lines.
- Wood:Traditional ash and hickory frames persist in artisanal production for historical reenactment and specialty collectors. Limited commercial volume centered on Vermont and Quebec craft manufacturers.
Aluminum retains volume leadership, though Composite is expanding most quickly as backcountry participation accelerates.
Use Case:
Activity-specific requirements reshape frame sizing, traction configuration, and binding release characteristics across customer types.
- Leisure:Flat-terrain walking on packed trails or golf course conversion routes. Demand clusters around retirement communities in Arizona and Florida with seasonal migration patterns.
- Expeditions:Multi-day unsupported travel requiring flotation across deep powder and variable snow bridges. Alaska's guiding operators and Yukon territorial parks set equipment standards.
- Fitness:Running and high-cadence walking with specialized racing-style frames. Minnesota's urban park systems and Calgary's pathway networks support dedicated winter programming.
- Hunting:Load-bearing capacity for pack-out scenarios with aggressive traction for off-trail bushwhacking. Montana and Idaho outfitters drive specification for military-grade binding retention.
Leisure commands installed base, while Fitness is gaining share fastest among urban millennials.
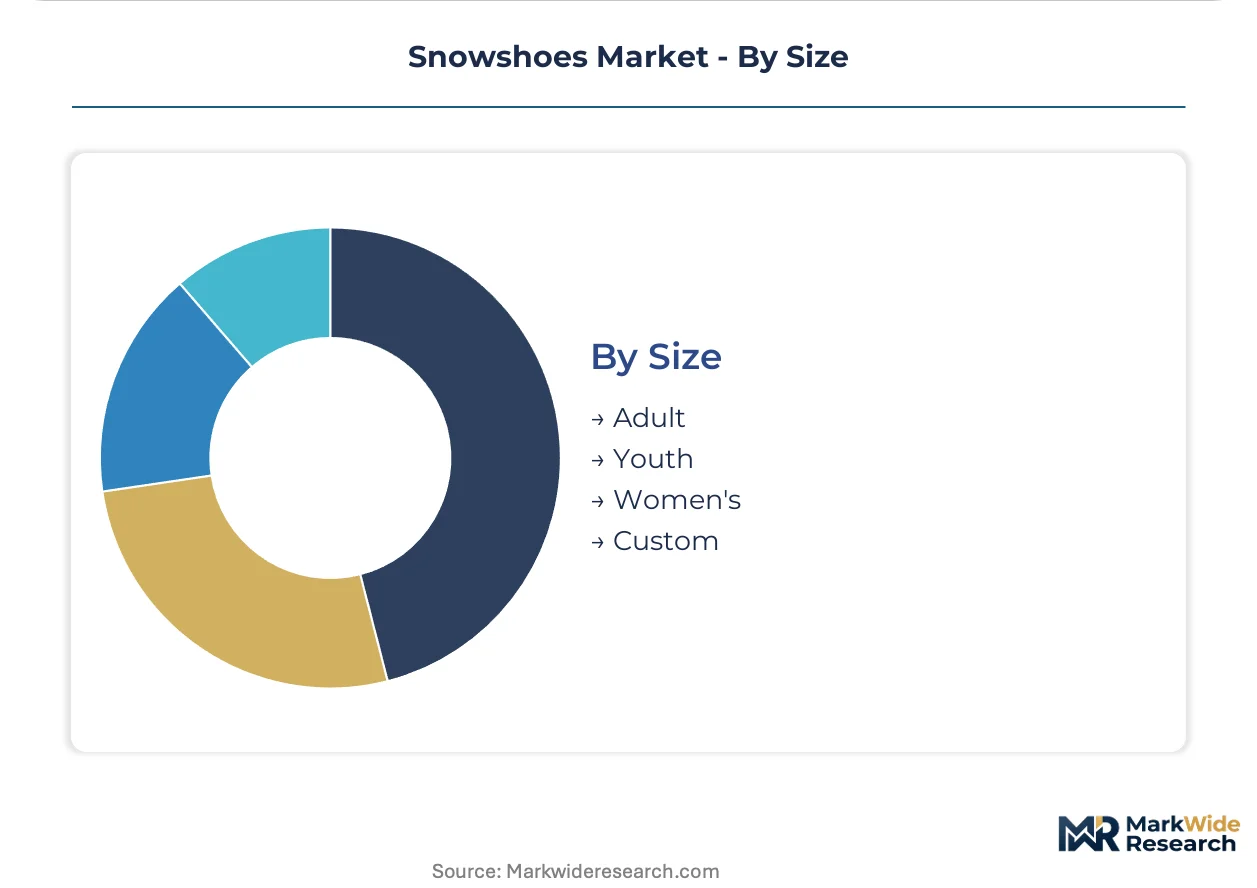
Size:
Anthropometric variation and load-bearing requirements segment the market across demographic and functional dimensions.
- Adult:Standard unisex frames accommodating 80-150 kg total load across 25-30 inch deck lengths. Rental fleet procurement defaults to this specification for inventory simplification.
- Youth:Scaled 17-22 inch decks with reduced binding complexity for ages 6-14. School program contracts in Colorado and Utah drive seasonal volume concentration.
- Women's:Narrower frame profiles and adjusted binding pivot points based on gait biomechanics studies. Direct-to-consumer channels in Seattle and Denver report higher conversion for gender-specific SKUs.
- Custom:Bespoke geometry for adaptive athletes and extreme load scenarios. Limited production runs from specialty manufacturers in Vermont and British Columbia.
Adult sizing dominates procurement volumes, while Women's is climbing the fastest as product development targets previously underserved biomechanical requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Canadian Pacific Railway's mountain corridor through British Columbia and Alberta underwrites North American backcountry access, while Japan's Hokkaido Shinkansen extension and Norway's Ofoten Line position Nordic tourism infrastructure as demand catalysts.
United States
Colorado's I-70 mountain corridor and Utah's Wasatch Front anchor domestic backcountry participation growth. ASTM F2387 certification requirements administered by the Consumer Product Safety Commission create procurement standards for federal land permits. Seattle-based engineering clusters and Vermont's manufacturing base concentrate technical and production capacity respectively.
Canada
Quebec's provincial trail networks and British Columbia's Coast Mountains drive rental fleet turnover and guided expedition demand. Health Canada coordinates seasonal recall protocols with U.S. counterparts, tightening market access for uncertified imports. Calgary and Montreal serve as distribution nodes for Prairie and Eastern Nordic center supply chains.
Japan
Nagano and Hokkaido prefectures are expanding English-language guiding permits as winter tourism recovers. METI oversees industrial standards alignment for outdoor equipment imports. The Niseko-Tomamu resort corridor concentrates rental procurement for inbound adventure tourism.
Norway
Cross-country trail infrastructure in Oppland and Trøndelag counties sustains recreational participation rates. The Norwegian Environment Agency regulates commercial guiding permits on protected lands. Oslo-based outfitters coordinate fleet procurement for Svalbard expedition operators.
Germany
Bavarian Alpine regions and Black Forest trail systems support steady leisure segment demand. KBA-equivalent equipment safety frameworks apply to imported backcountry gear through EU CE marking requirements. Munich outdoor retail clusters influence Central European distribution patterns.
Snowshoes Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers: vertically integrated manufacturers controlling composite layup processes, regional fabricators serving rental fleet contracts, and specialty designers focused on binding system innovation. Strategic archetypes include aerospace-adjacent composite specialists, Vermont-based aluminum tubing houses, and direct-to-consumer digital natives. Capacity expansion and ASTM certification acquisition represent the dominant competitive moves as barriers rise for uncertified imports.
Among Seattle-based technical developers, MSR anchors the premium backcountry tier through sustained engineering investment in flotation geometry. Atlas Snowshoe Company occupies the position of Eastern U.S. manufacturing incumbent with established Nordic center relationships. Crescent Moon Snowshoes exemplifies the binding-innovation archetype through differentiated mechanical approaches and Rocky Mountain rental penetration.
| Leading Market Players |
|---|
| MSR |
| Atlas Snowshoe Company |
| Crescent Moon Snowshoes |
| Tubbs Snowshoes |
| GV Snowshoes |
| Fimbulvetr |
| Chinook Technical Outdoor |
| Garneau |
| L.L.Bean |
| Others |
Pricing and Supply Chain Analysis
The Canadian Pacific Railway's mountain corridor through British Columbia and Alberta carries aluminum tubing and composite feedstock from Pacific port terminals to assembly facilities in Calgary and Denver, with freight cost volatility creating divergent margin structures between coastal importers and inland fabricators while rental fleet procurement concentrates negotiating leverage among state park systems and Nordic center cooperatives.
Pricing Analysis
Volume-discount tiering structures separate ASTM-certified backcountry models from uncertified recreational imports and artisanal wooden frames. Pricing stratifies across premium, standard, and economy tiers based on certification grade and binding complexity. Cost compression in recreational aluminum segments intensifies because LME futures volatility exceeds 35 percent material cost share. Rental operators at Quebec's provincial networks exhibit highest price sensitivity, while avalanche-educated backcountry users in Colorado's Wasatch corridor accept premium positioning for reduced frame weight.
Supply Chain Analysis
Upstream feedstock flows draw from 6061-T6 extruders in Ohio and Michigan, carbon fiber pre-preg suppliers in Washington state, and glass-reinforced nylon compounders feeding injection molders in Quebec. Raw material dependencies center on aluminum tubing, thermoplastic resins, and stainless steel crampon stock. Single-source vulnerability concentrates in aerospace-adjacent composite layup technicians trained for racing segment certification. Distribution runs through specialty outdoor retail clusters in Seattle, Denver, and Montreal, with direct-to-consumer subscription models bypassing traditional markup layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: ASTM F2387 certification creates 18-month validation barriers that insulate incumbents from low-cost import competition while embedding equipment standards into federal land permitting processes.
For Market Incumbents: Insulate market position by acquiring in-house composite layup capability to reduce aerospace supply chain dependency, and secure Forest Service Special Use Permit documentation workflows before competing suppliers achieve certification. Binding release mechanism validation cycles exceeding 18 months create durable barriers against emerging polymer frame entrants from Asian manufacturing clusters. For New Entrants and Emerging Players: Japan's Nagano and Hokkaido prefectures expanding English-language guiding permits represent the most penetrable entry point for ASTM-certified manufacturers seeking rental fleet procurement outside saturated North American channels. Direct-to-consumer subscription models targeting urban millennials in Toronto and Seattle bypass retail markup concentration. Partner with established avalanche education providers to embed equipment trials into guided lesson packages. For Investors and Strategic Acquirers: Carve-out targets emerge from aerospace-adjacent composite specialists with idle capacity and trained technician pools. Long-term viability rests on certification infrastructure rather than brand equity alone. Monitor Health Canada-US CPSC recall protocol synchronization as signal for accelerated compliance timelines favoring certified supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| ASTM F2387 Certification Acquisition | Unlocks Forest Service permitting access and blocks uncertified import competition across federal Wilderness Study Areas. |
| Composite Layup Capability Buildout | Reduces dependency on aerospace supply chains and enables racing segment entry under International Snowshoe Federation protocols. |
| Direct-to-Consumer Subscription Launch | Captures urban millennial demand in Seattle and Denver while generating usage data for product development cycles. |
| Japan Rental Fleet Partnership | Positions certified manufacturers for inbound tourism recovery across Nagano and Hokkaido prefecture guiding permits. |
| Polymer Frame Injection Molding Scale-Up | Enables rapid colorway customization for regional outfitters and cuts assembly labor in recreational tier production. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ASTM International certification records, U.S. Forest Service Special Use Permit databases, and Nordic center procurement contracts. Primary interviews engaged product development engineers at Seattle-based technical developers, rental program managers at Vermont and Quebec Nordic centers, composite technicians from aerospace-adjacent supply chains, and federal land permitting officers. Secondary validation drew from Health Canada recall archives, U.S. Consumer Product Safety Commission seasonal enforcement reports, and provincial trail network maintenance budgets. Bottom-up unit demand modeling triangulated against top-down market value reconstruction.
Forecast inputs incorporate product type segmentation across recreational, backcountry, racing, and kids models; material composition tiers spanning aluminum, composite, polymer, and wood; and use case distinctions between leisure, expedition, fitness, and hunting applications. CAGRs derive from regression analysis of historical rental fleet turnover rates, guided participation growth in Colorado and British Columbia, and substitution elasticity between snowshoes and groomed Nordic trail systems. Industry-specific inputs include International Snowshoe Federation dimensional specification evolution and composite recycling infrastructure development timelines.
Macroeconomic conditions sit as an overlay; deviation in aluminum futures pricing, winter tourism recovery velocity, or federal land access policy would shift the trajectory. Forecasts reflect documented assumptions regarding certification timeline stability and rental program unbundling trends. Cross-checking against state park system equipment procurement bid archives is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Kayak Market
Outdoor and Adventure Activities
Hydration Packs Market
Outdoor and Adventure Activities
Fishing Waders Market
Outdoor and Adventure Activities
Recreational Sports Activities Market
Outdoor and Adventure Activities
Recreational Use Water Chute Market
Outdoor and Adventure Activities
India Spectator Sports Market
Outdoor and Adventure Activities
Asia-Pacific Spectator Sports Market
Outdoor and Adventure Activities
Global Climbing Holds Market
Outdoor and Adventure Activities
Global Personal Watercraft Market
Outdoor and Adventure Activities
Leisure Centers Market
Outdoor and Adventure Activities
Ski Vacation Market
Outdoor and Adventure Activities
United States and Europe Horse Racing Market
Outdoor and Adventure Activities
Spain Sports Tourism Market
Outdoor and Adventure Activities
Trekking Poles Market
Outdoor and Adventure Activities
Outdoor Backpack Market
Outdoor and Adventure Activities
Power Sports Market