
 Kitesurf Kites Market | 2026-2036
Kitesurf Kites Market Size, Share, and Industry Trends Forecast 2026-2036
Kitesurf Kites Market Insights
Market Context
Aftermarket service revenue from bladder replacement, canopy repair, and line tuning is rewriting profit distribution across the kitesurf kites value chain. Ozone leverages its New Zealand manufacturing base to sustain premium positioning in high-wind performance categories. Cabrinha anchors North American distribution through dedicated school partnerships and instructor certification programs. Duotone competes across European watersports retail with a broad freeride-to-wave product hierarchy.
Technical Definition and Segment Structure
Kitesurf kites are traction kites engineered from ripstop nylon or polyester canopies with inflatable leading-edge bladders or closed-cell foil architectures, spanning five to seventeen square meters to harness wind power for board propulsion across marine and estuarine surfaces. The leading-edge inflatable configuration dominates commercial volumes due to relaunch reliability in surf impact zones, while foil kites gain share among expedition riders and snow-kite crossover users. Freeride and all-around type segments carry the volume base, whereas race and wave categories command higher unit margins through specialized aspect ratios and reinforced construction. Material selection clusters around nylon for mainstream durability and Kevlar reinforcement in high-load zones, with Mylar film applications concentrated in competition-grade foil kites where dimensional stability under cyclic loading determines performance.
Regulatory Environment and Outlook
The US Coast Guard classifies kitesurf kites as unregulated recreational equipment, though state-level waterway authorities in Florida, California, and Hawaii impose seasonal access restrictions that shape local demand patterns. REACH compliance in Europe governs chemical content in canopy coatings and bladder polymers, while CE marking requirements for flotation and rescue accessories affect bundled product configurations. Stakeholders must monitor evolving coastal access negotiations and emerging sustainability disclosure rules that could alter material sourcing decisions and end-of-life collection obligations.
Market Dynamics
Bladderless inflatable architectures and load-frame canopy construction are compressing replacement cycles while lifting performance thresholds, forcing incumbent manufacturers to retool production lines or cede share to specialized composite fabricators.
Growth Catalysts
- REACH compliance in Europe:Chemical content restrictions on canopy coatings and bladder polymers are accelerating R&D investment in bio-based alternatives, creating first-mover advantages for compliant suppliers.
- Coastal tourism procurement:Dedicated kitesurf schools in Portugal's Algarve corridor and Spain's Tarifa zone are expanding equipment fleets to capture seasonal visitor influx.
- Closed-cell foil architectures:Expedition riders and snow-kite crossover users are adopting foil kites for superior upwind performance in low-wind conditions.
Market Restraints
- Ripstop nylon price volatility:Petrochemical feedstock fluctuations directly compress margins on mainstream durability tiers.
- Leading-edge bladder supply concentration:Polyurethane bladder fabrication clusters in East Asian contract manufacturers, exposing brands to logistics disruptions.
- CE marking for flotation accessories:Rescue equipment bundling requirements add compliance costs without corresponding price recovery.
Strategic Opportunities
- Brazil's underpenetrated coastline:Ceará and Rio Grande do Norte states lack established school networks despite consistent trade winds.
- Modular canopy systems:Interchangeable leading edges and struts allow riders to reconfigure kites for varying conditions without full replacement.
- US state-level waterway access negotiations:Florida seasonal restriction reforms could unlock year-round demand in the Southeast.
Industry Challenges
- Composite fabrication skill scarcity:Load-frame construction requires specialized sewing technicians that schools cannot supply.
- ISO 21853 certification timelines:Safety standard harmonization delays product launches across export markets.
- Legacy bladder inventory obsolescence:Bladderless migration strands component stock at distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitesurf Kites Market |
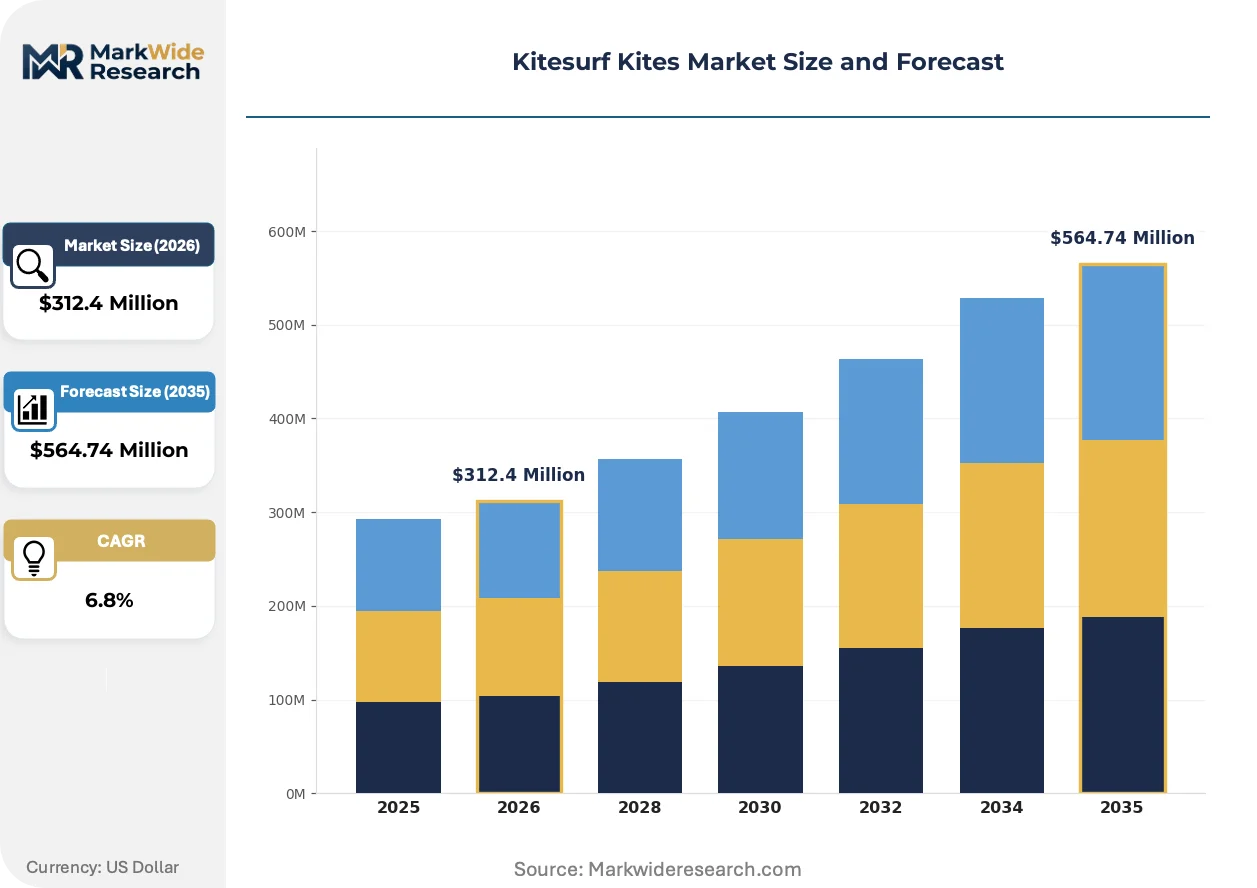
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Freeride, Race, Wave, All-around Material: Nylon, Polyester, Mylar, Kevlar Size: 5m, 7m, 9m, 12m Experience Level: Beginner, Intermediate, Advanced, Professional |
| Companies Covered | Ozone, F-One, North Kiteboarding, Eleveight, Cabrinha, Duotone, Core, Airush, Naish, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitesurf Kites Market Trends and Innovations
Material science breakthroughs and regulatory chemistry restrictions are converging to reshape how kitesurf kites are engineered, sourced, and sold across coastal markets.
Kevlar reinforcement in high-load zones is migrating from race-grade specialty kites to mid-tier freeride models. Weekend riders in Cape Town's Bloubergstrand zone now expect competition-derived durability without pro-level pricing. This migration is compressing the premium-standard gap and forcing brands to reposition flagship products.
REACH chemical content governance in Europe now governs perfluorinated compounds in canopy water-repellent coatings. Manufacturers are reformulating with silicone-based alternatives that sacrifice some hydrophobic performance for compliance. Race and wave categories face the steepest reformulation costs due to performance-critical surface treatments.
School-direct bulk purchasing is displacing traditional retail intermediaries in high-density wind sports corridors. Portuguese and Spanish coastal operators now negotiate fleet pricing directly with manufacturers, bypassing regional distributors. This channel compression is most visible in the Algarve-Tarifa corridor where school concentration exceeds retail footprint.
Kitesurf Kites Market Segmentation
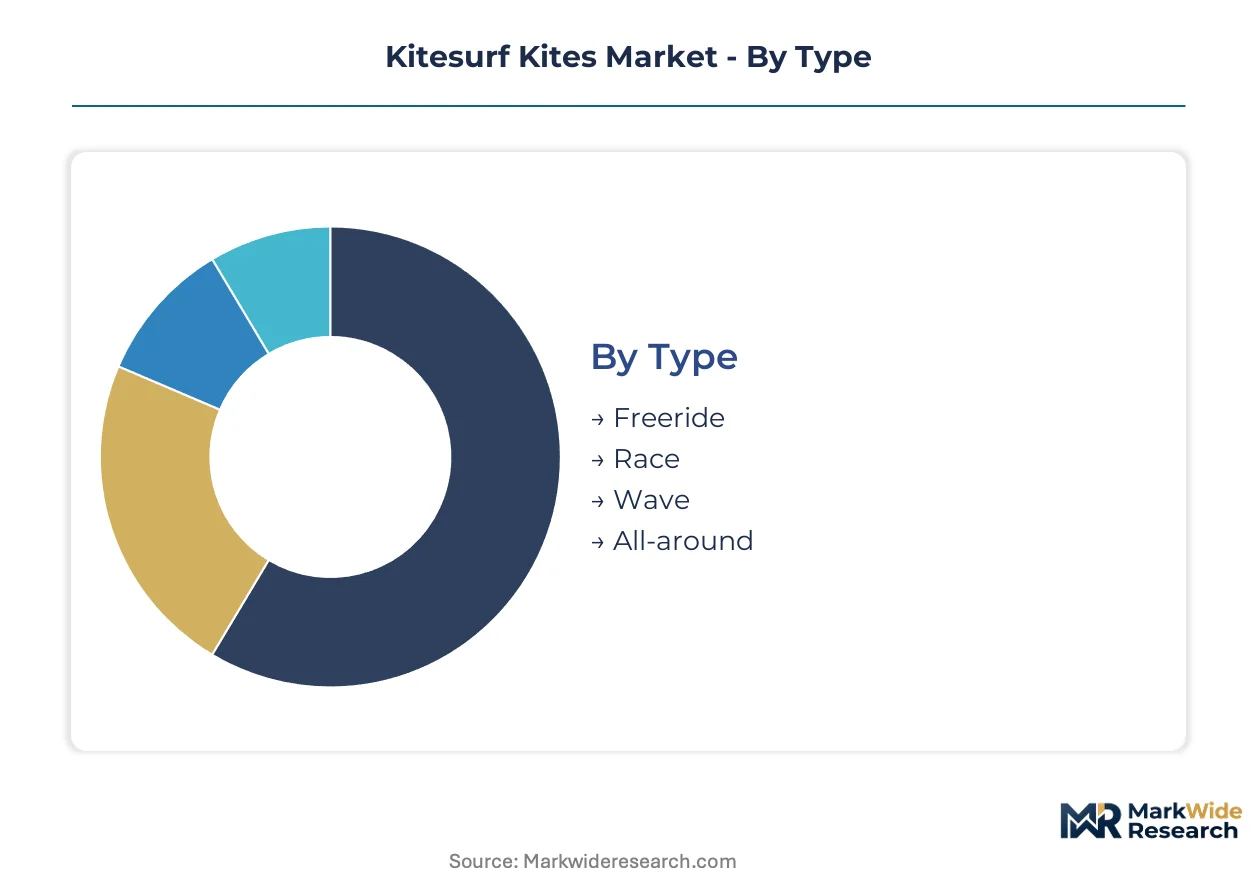
Segmentation in kitesurf kites reveals how construction choices, rider capability, and wind condition specialization carve distinct profit pools. Manufacturers configure product hierarchies around these fault lines to capture volume at entry tiers and margin at performance extremes.
Type:
Application specialization determines canopy architecture, aspect ratio, and reinforcement intensity across riding disciplines.
- Freeride:Moderate aspect ratios and balanced depower range suit variable coastal conditions from Portugal's Algarve to Cape Town's Bloubergstrand. Volume concentration here reflects the recreational rider base seeking versatility across wind strengths.
- All-around:Hybrid geometries bridge wave and flat-water performance, dominating school fleet procurement in Tarifa and Ceará where instructors need one-kite solutions for student progression.
- Race:High-aspect profiles maximize upwind velocity through rigid frame construction.
- Wave:Rapid pivot response and surf-resistant bladders handle impact zones.
Freeride commands the established base. The steepest expansion runs through Wave as surf-kite crossover participation climbs.
Material:
Cost tier and durability requirements stratify raw material selection across nylon, polyester, and composite reinforcements.
- Nylon:Ripstop weaves dominate mainstream production for tear resistance and repairability. REACH chemical restrictions on coatings are forcing reformulation investments among European suppliers serving the Algarve-Tarifa corridor.
- Kevlar:Aramid reinforcement migrates from race-grade specialty into mid-tier freeride models as weekend riders demand competition-derived durability without pro-level pricing.
- Polyester:Lower stretch coefficients suit budget-conscious entry segments.
- Mylar:Film laminates provide dimensional stability in competition foil kites.
Nylon retains the volume anchor. Kevlar-blended constructions are gaining share fastest as durability expectations rise across tiers.
Size:
Wind range coverage drives square-meter selection, with geographic wind patterns shaping regional demand concentration.
- 9m:The utility standard for 15-20 knot conditions covers most coastal tourism operations in Portugal and Spain. School-direct bulk purchasing clusters here for fleet standardization.
- 12m:Light-wind specialization captures Cape Town summer sessions and Brazilian trade wind lulls. Foil kite compatibility expands addressable conditions.
- 5m:Storm-range handling for high-wind zones.
- 7m:Transition sizing for gusty coastal microclimates.
9m configurations hold the core position. The 12m segment is climbing the fastest as light-wind accessibility broadens participation windows.
Experience Level:
Customer type determines safety system complexity, relaunch assistance features, and price positioning across the rider journey.
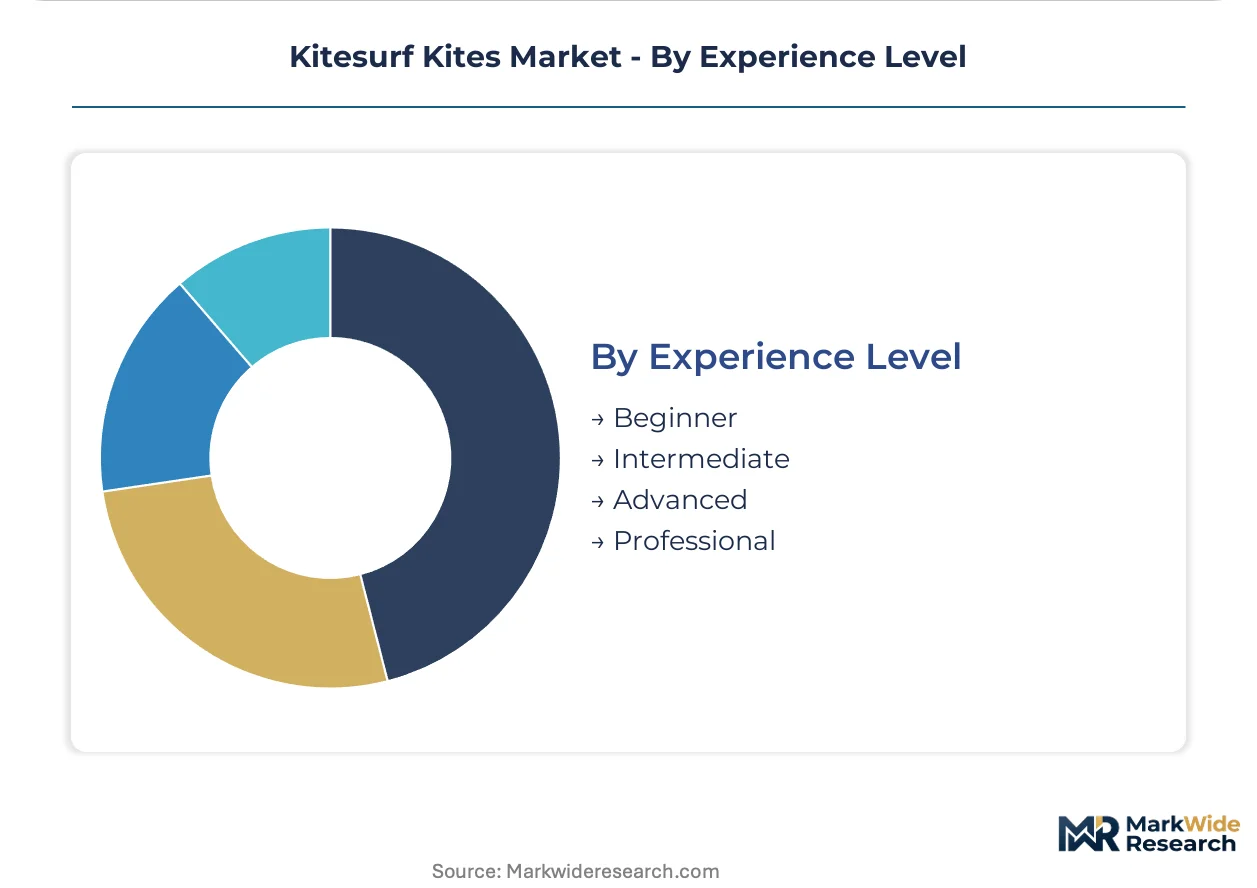
- Beginner:Automated relaunch systems and reduced bar pressure dominate school procurement in Brazil's underpenetrated Ceará coastline. Equipment durability under repeated crashes shapes material specifications.
- Intermediate:Progression-oriented models with adjustable depower range capture the largest upgrade cycle volume as first-kit replacement demand concentrates in European watersports retail.
- Advanced:Performance-tuned response characteristics for unhooked maneuvers.
- Professional:Custom prototypes and competition-grade construction.
Intermediate riders represent the replacement engine. Beginner segment expansion is accelerating most quickly as coastal tourism operators scale school infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across coastal markets. Brazilian operators negotiate aggressively on school fleet orders while Cape Town buyers absorb premium pricing for high-wind durability. This elasticity divide shapes how manufacturers configure regional distribution.
United States
Florida seasonal waterway restrictions compress demand windows in the Southeast, pushing rental operators toward multi-use equipment configurations. The US Coast Guard maintains unregulated recreational classification, though state-level authorities in California and Hawaii impose access limitations. Miami-Dade and Fort Lauderdale clusters concentrate school procurement, with operators negotiating direct manufacturer contracts to bypass traditional retail margins.
Portugal
Algarve corridor tourism operators drive the densest school-fleet procurement in Europe, with Lagos-to-Faro concentrations exceeding retail footprint. REACH compliance through ECHA governs chemical content in canopy coatings, accelerating bio-based formulation investments among suppliers serving Portuguese distributors. Sagres and Alvor sub-clusters anchor equipment staging for Atlantic wind seasonality.
Spain
Tarifa's year-round trade winds sustain the highest school-per-capita density globally, with fleet standardization favoring 9m utility configurations. CE marking requirements for flotation and rescue accessories add compliance costs to bundled product configurations. The Strait of Gibraltar microclimate supports extended operating seasons that justify premium equipment depreciation schedules.
South Africa
Cape Town's Bloubergstrand zone commands premium positioning for high-wind performance categories, with weekend riders demanding competition-derived durability. Limited local manufacturing capacity forces reliance on import channels through Durban and Cape Town ports. Summer light-wind sessions expand 12m segment demand as foil kite compatibility broadens participation windows.
Brazil
Ceará and Rio Grande do Norte states present underpenetrated coastline despite consistent trade winds, with school network gaps constraining equipment procurement. ANVISA governs product safety standards for imported recreational equipment, though kitesurf-specific certification remains underdeveloped. Jericoacoara and Preá clusters show early operator concentration as coastal tourism infrastructure scales.
Kitesurf Kites Market Competitive Landscape
Capability concentration sits with specialized composite fabricators mastering load-frame construction; scale advantage sits with established brands commanding school-direct procurement relationships. The vendor base stratifies across three tiers: premium performance specialists, volume-driven freeride suppliers, and regional school-fleet providers. Dominant competitive moves include geographic expansion into underpenetrated wind corridors and portfolio diversification across inflatable and foil architectures.
Within the premium-tier vector, Ozone anchors high-wind performance positioning through its New Zealand manufacturing base. Cabrinha and Duotone occupy scale-advantaged positions, with the former anchoring North American distribution and the latter competing across European watersports retail hierarchies. These three exemplify how geographic specialization and channel control separate market tiers.
| Leading Market Players |
|---|
| Ozone |
| F-One |
| North Kiteboarding |
| Eleveight |
| Cabrinha |
| Duotone |
| Core |
| Airush |
| Naish |
| Others |
Pricing and Supply Chain Analysis
Shanghai-to-Rotterdam container freight corridors transmit petrochemical feedstock volatility directly into ripstop nylon landed costs, concentrating margin pressure on mid-tier manufacturers while enabling premium brands to widen price differentiation through captive bladder fabrication.
Pricing Analysis
Aftermarket service revenue from bladder replacement, canopy repair, and line tuning now drives lifetime value capture across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates Ozone's New Zealand-manufactured high-wind performance kites from Duotone's European freeride volume plays and budget polyester entry models. Cost compression in standard-tier nylon canopies is intensifying because REACH-compliant silicone-based coating reformulations add production overhead without commensurate price recovery. Brazilian school-fleet buyers exhibit highest price sensitivity, while Cape Town's weekend riders absorb premium positioning for Kevlar-reinforced durability.
Supply Chain Analysis
Extended payment terms from East Asian polyurethane bladder fabricators now anchor working capital structures for European and North American kite brands. Component sourcing concentrates in China, Taiwan, and Vietnam for ripstop weaving and bladder extrusion, while New Zealand retains specialized load-frame composite fabrication. Raw material dependencies rest on petrochemical-derived nylon polymers, aramid fiber shipments from Teijin's Japanese facilities, and silicone coating precursors. Single-source vulnerability in leading-edge bladder supply exposes brands to logistics disruptions through the Strait of Malacca. Distribution runs through school-direct procurement in Portugal and Spain, bypassing traditional retail intermediaries in high-density wind corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Load-frame canopy construction expertise has emerged as the critical bottleneck, with fewer than a dozen sewing technicians globally capable of executing composite fabrication at race-grade tolerances.
For Market Incumbents: Build certification moats around ISO 21853 safety standard harmonization to delay competitor product launches across export markets. Deepen backward integration into Kevlar-reinforced canopy production to capture margin migrating from race-grade specialty into mid-tier freeride models. Anchor school-direct procurement relationships in Brazil's underpenetrated Ceará corridor before regional distributors establish footholds. For New Entrants and Emerging Players: Pursue modular canopy system architecture as the most penetrable white-space opportunity, allowing riders to reconfigure kites for varying conditions without full replacement. Target expedition rider segments adopting closed-cell foil architectures for superior upwind performance in low-wind conditions. Enter through instructor certification partnerships rather than retail channel builds to bypass incumbent distribution control. For Investors and Strategic Acquirers: Specialized composite fabricators mastering bladderless inflatable architectures represent the highest-conviction acquisition archetype for capability integration. Long-term viability hinges on bio-based coating formulation pipelines achieving REACH compliance without hydrophobic performance sacrifice. Watch for Florida state-level waterway access negotiation outcomes as the inflection signal that would unlock year-round Southeast demand and justify premium equipment depreciation schedules.| Strategic Initiative | Industry Significance |
|---|---|
| Bladderless Architecture Migration | Retooling production lines captures share from legacy bladder-dependent competitors. |
| School-Direct Procurement Partnership | Portuguese and Spanish coastal operators now negotiate fleet pricing bypassing distributors. |
| REACH-Compliant Coating Reformulation | Silicone-based alternatives sacrifice hydrophobic performance for ECHA chemical content compliance. |
| Modular Canopy System Development | Interchangeable leading edges and struts expand rider condition coverage without full replacement. |
| Brazilian Coastal Infrastructure Expansion | Jericoacoara and Preá clusters show early operator concentration as tourism infrastructure scales. |
Research Methodology
A standing panel of kite school operators, watersports retail buyers, composite fabrication technicians, and coastal tourism procurement managers provided ongoing calibration against secondary validation from trade customs records, ECHA REACH substance databases, and manufacturer technical documentation. Primary fieldwork combined structured interviews with equipment fleet managers in Portugal's Algarve corridor and Tarifa's school-dense zone with technical assessments of bladderless architecture migration timelines. Bottom-up unit economics triangulated against top-down coastal tourism expenditure estimates.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling rider progression segments, canopy architecture types, material grade tiers, and regional wind pattern clusters. CAGRs derived from equipment replacement cycle compression and school-fleet expansion rates in underpenetrated corridors. Industry-specific inputs included polyurethane bladder supply lead times and REACH compliance cost pass-through elasticity.
Sensitivities concentrate around petrochemical feedstock price trajectories, coastal access regulatory negotiations, and composite fabrication skill pipeline development. Forecasts reflect documented assumptions regarding trade wind seasonality stability and school network penetration rates. Macroeconomic deviation in coastal tourism expenditure, regulatory acceleration in sustainability disclosure rules, or breakthrough advances in bio-based polymer performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
United States and Europe Horse Racing Market
Outdoor and Adventure Activities
India Spectator Sports Market
Outdoor and Adventure Activities
Asia-Pacific Spectator Sports Market
Outdoor and Adventure Activities
Fat Bike Market
Outdoor and Adventure Activities
Global Climbing Shoes Market
Outdoor and Adventure Activities
Recreational Use Water Chute Market
Outdoor and Adventure Activities
Hydration Packs Market
Outdoor and Adventure Activities
Recreational Sports Activities Market
Outdoor and Adventure Activities
Mountain Bike Market
Outdoor and Adventure Activities
Hiking Cleats Market
Outdoor and Adventure Activities
Power Sports Market
Outdoor and Adventure Activities
Leisure Centers Market
Outdoor and Adventure Activities
Adventure Sports and Activities Market
Outdoor and Adventure Activities
US Spectator Sports Market
Outdoor and Adventure Activities
Global Ski Poles Market
Outdoor and Adventure Activities
Ski Vacation Market