
 Hiking Cleats Market | 2026-2036
Hiking Cleats Market Size, Share, and Industry Trends Forecast 2026-2036
Hiking Cleats Market Analytics
Trail running adoption is restructuring demand patterns across outdoor retail channels, pulling volume from traditional mountaineering categories toward lighter, multi-terrain systems. Kahtoola leverages its ice-traction heritage to compete in this expanding segment, while Hillsound anchors its position through specialized approach-shoe compatibility. Yaktrax differentiates via mass-market accessibility and broad retail distribution.
Hiking cleats are traction devices that attach to footwear soles via elastomer harnesses, metal coils, or carbide spikes to prevent slippage on ice, packed snow, and loose rock surfaces, typically rated for specific slope angles and temperature ranges. Mountaineering cleats with full stainless-steel spike configurations command the highest margin pools due to technical certification requirements, while trail running variants using lightweight aluminum and synthetic composites represent the fastest-expanding segment. Leather materials retain dominance in serious backpacking applications where durability and mold-to-foot properties justify premium positioning, though Gore-Tex membranes are displacing conventional treatments in wet-climate markets.
The EU Green Deal and REACH chemical frameworks constrain solvent-based adhesives and certain chromium-tanned leathers, redirecting R&D toward bio-based synthetics and water-based bonding processes. The US Consumer Product Safety Commission and ASTM International maintain traction-performance testing protocols that gate market access for import-dependent brands. Stakeholders must monitor evolving biodegradability standards and regional recycling infrastructure gaps as these factors will determine which material platforms sustain commercial viability.
Market Dynamics
Trail running adoption is restructuring demand patterns across outdoor retail channels, pulling volume from traditional mountaineering categories toward lighter, multi-terrain systems. This shift compresses product lifecycles and rewards brands with rapid prototyping capabilities.
Growth Catalysts
- EU Green Deal mandates:REACH chemical frameworks constrain solvent-based adhesives and chromium-tanned leathers, redirecting R&D toward bio-based synthetics and water-based bonding processes that open premium positioning.
- Technical mountaineering certification:Stainless-steel spike configurations with slope-angle ratings command institutional procurement in Alpine rescue and professional guiding sectors.
- Gore-Tex membrane displacement:Wet-climate markets in Norway and Scotland are replacing conventional leather treatments with waterproof-breathable laminates, expanding addressable seasons.
Market Restraints
- Carbide spike input volatility:Tungsten supply concentration in Chinese mining regions creates margin pressure for technical cleat manufacturers.
- ASTM traction-testing compliance costs:US Consumer Product Safety Commission protocols gate market access for import-dependent brands, extending certification timelines.
- Microspike substitution threat:Coil-based traction systems from mass-market competitors capture casual winter walkers unwilling to pay premium for full spike configurations.
Strategic Opportunities
- Approach-shoe compatibility white space:Specialized harness systems for hybrid footwear categories remain underdeveloped in North American retail.
- Biodegradability standard anticipation:Early alignment with emerging EU end-of-life regulations positions brands for circular economy procurement preferences.
- Direct-to-consumer channel expansion:Technical fitting requirements for mountaineering cleats favor virtual try-on tools and subscription replacement models.
Industry Challenges
- Composite bonding technician scarcity:Water-based adhesive processes require retraining of legacy footwear manufacturing workforces.
- Multi-terrain certification complexity:Products spanning trail running, mountaineering, and ice-climbing use cases face conflicting performance standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hiking Cleats Market |
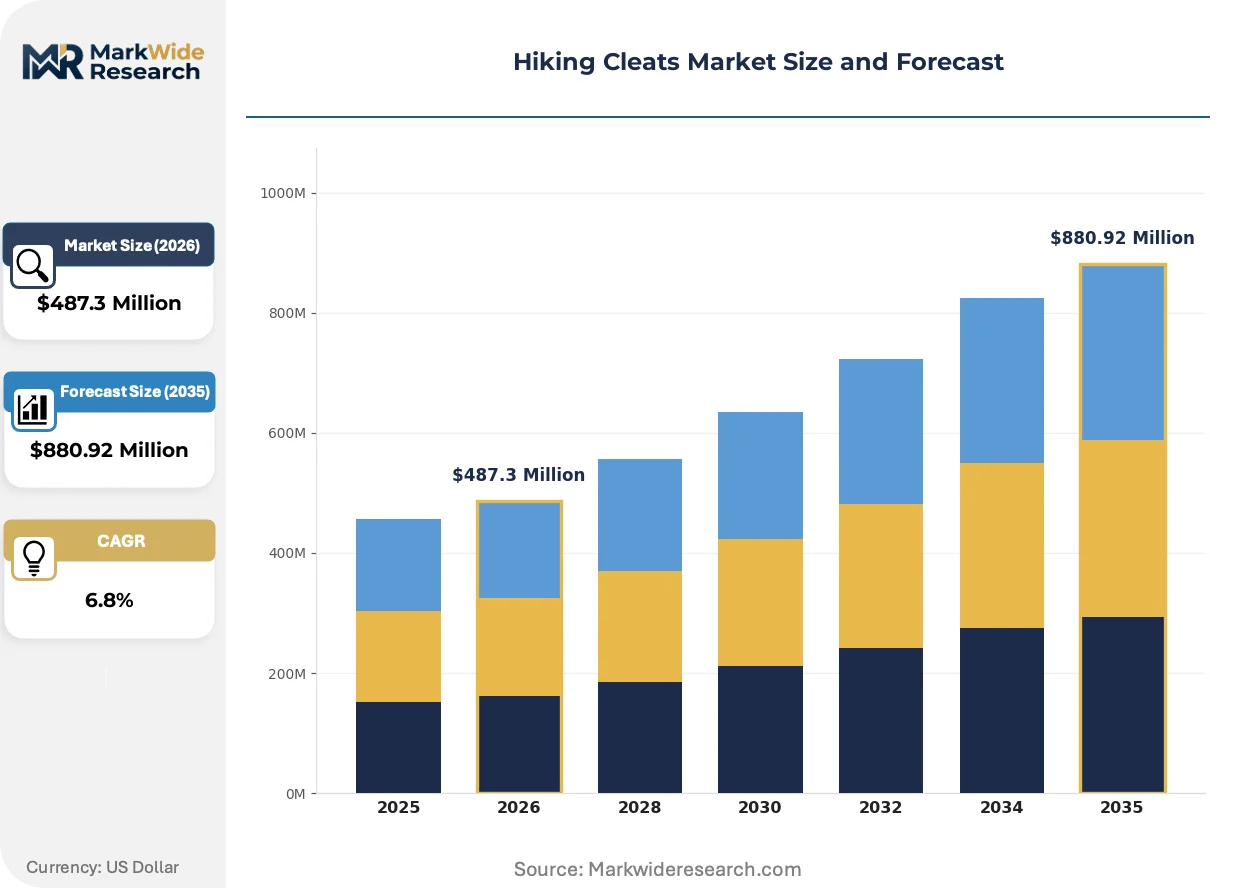
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trail Running, Mountaineering, Approach Shoes, Backpacking Material: Leather, Synthetic, Gore-Tex, Mesh Size: Small, Medium, Large, Extra Large End User: Recreational Hikers, Serious Backpackers, Trail Runners, Outdoor Enthusiasts |
| Companies Covered | Fusigo, Kahtoola, Hillsound, Yaktrax, Icetrax, Wowobjects, Boxoon, Astyer, Teamland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hiking Cleats Market Evolving Landscape
Material science convergence with digital fitting tools is compressing development cycles and enabling mass customization previously reserved for bespoke mountaineering equipment.
Carbide-reinforced elastomer compounds are integrating into hybrid spike configurations that bridge trail running and technical ice travel. Alpine athletes and ski mountaineers are adopting these systems at accelerating rates. This convergence is integrating previously separate product categories into unified traction platforms.
REACH chemical frameworks are phasing out per- and polyfluoroalkyl substances in water-repellent treatments. Manufacturers must reformulate membrane bonding agents and surface coatings. Wet-climate product lines in Germany and Austria are responding fastest, with several brands already certifying PFAS-free alternatives.
Specialty retailers are unbundling fitting services from product sales, charging separately for biomechanical assessment and cleat-attachment optimization. This model displaces traditional full-price retail in Scandinavia and the Pacific Northwest. Backcountry guides and avalanche professionals are driving adoption where performance guarantees outweigh upfront cost sensitivity.
Hiking Cleats Market Segmentation
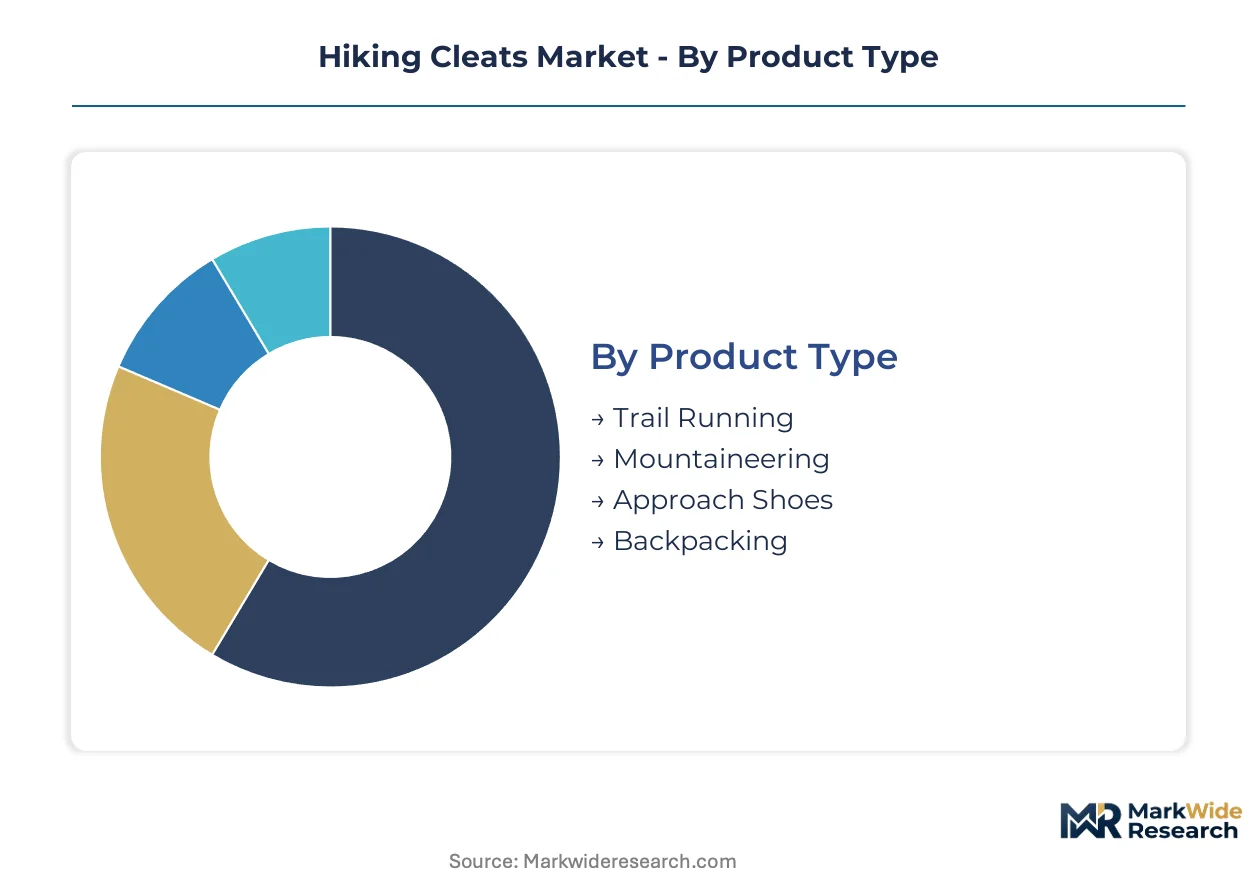
Segmentation in hiking cleats determines capital allocation across fundamentally different manufacturing footprints. Spike fabrication, membrane lamination, and harness molding each demand specialized equipment that cannot be redeployed across categories without significant retooling costs.
Product Type:
Capital intensity peaks in segments requiring certified metalworking infrastructure and multi-terrain testing facilities.
- Mountaineering:Full stainless-steel spike configurations rated for vertical ice demand CNC machining centers and slope-angle certification laboratories. Alpine rescue services in Germany and Austria specify these systems for institutional procurement, locking in premium margin pools through technical compliance requirements.
- Trail Running:Lightweight aluminum and synthetic composite platforms utilize rapid-prototyping workflows and additive manufacturing for iterative spike geometry refinement. Demand concentrates in Pacific Northwest retail channels where year-round muddy conditions extend the addressable season beyond traditional winter boundaries.
- Approach Shoes:Hybrid harness systems bridge scrambling and technical climbing with modular attachment points.
- Backpacking:Durable elastomer compounds prioritize multi-day comfort over pure traction metrics.
Most installed capacity flows through Mountaineering. Expansion is steepest in Trail Running.
Material:
Raw material sourcing geography and regulatory exposure vary sharply across this dimension, determining working capital requirements and compliance overhead.
- Gore-Tex:Waterproof-breathable laminates command the highest material cost per unit but displace conventional treatments in wet-climate markets. Norwegian and Scottish retailers now stock predominantly membrane-equipped lines, driven by consumer expectations of all-weather reliability.
- Leather:Chromium-tanned hides face REACH chemical framework constraints, redirecting procurement toward vegetable-tanned alternatives with longer curing cycles. Serious backpacking applications in Germany's Alpine regions retain leather dominance where mold-to-foot durability justifies premium positioning.
- Synthetic:Recycled PET and bio-based polymers align with EU Green Deal mandates but require dedicated compounding equipment.
- Mesh:Open-weave constructions prioritize breathability for high-exertion trail running use cases.
Revenue concentration sits with Gore-Tex. Reformulation pressure is most intense on Leather.
Size:
Inventory carrying costs scale non-linearly with SKU proliferation, favoring brands with demand-forecasting sophistication.
- Medium:The modal foot dimension in North American and European populations supports highest production volumes and leanest unit economics. Trail running adoption concentrates here due to demographic alignment with the sport's core participant base.
- Large:Mountaineering and backpacking categories over-index in this bracket, reflecting male-skewed participation in technical outdoor activities. German Alpine clubs report fitting distributions that favor Large for institutional procurement.
- Small:Growing female participation in trail running expands addressable volume.
- Extra Large:Niche sizing with limited retail shelf allocation.
Production scheduling optimizes around Medium. Forecast error costs bite hardest in Extra Large.
End User:
Customer lifetime value and replacement frequency diverge substantially, shaping channel strategy and warranty provisioning.
- Trail Runners:High-frequency users replace cleats seasonally, creating recurring revenue streams that justify direct-to-consumer subscription models. Scandinavian specialty retailers unbundle fitting services for this segment, charging separately for biomechanical assessment.
- Serious Backpackers:Extended trip planning cycles and equipment research intensity favor editorial content and guide recommendations over impulse purchases. Germany's Alpine regions concentrate this cohort where technical mountaineering standards drive premium procurement.
- Recreational Hikers:Price-sensitive occasional users dominate mass-market retail.
- Outdoor Enthusiasts:Multi-activity participants seek cross-compatible systems.
Service attach rates peak with Trail Runners. Margin stability rests with Serious Backpackers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Alpine manufacturing corridor anchors hiking cleats production through specialized metalworking clusters in Bavaria and Baden-Württemberg. Technical certification requirements from Alpine rescue services sustain premium procurement channels across European markets. Regional demand patterns diverge sharply between institutional buyers and recreational trail runners.
United States
Pacific Northwest retail channels drive trail running cleat volume through year-round muddy conditions extending addressable seasons. ASTM International traction-testing protocols gate market access for import-dependent brands, extending certification timelines. Seattle and Portland specialty retailers unbundle fitting services from product sales, charging separately for biomechanical assessment.
Germany
Alpine rescue and professional guiding sectors command institutional procurement of stainless-steel spike configurations with slope-angle ratings. EU Green Deal REACH chemical frameworks constrain solvent-based adhesives and chromium-tanned leathers, redirecting R&D toward bio-based synthetics. Bavarian manufacturing clusters around Munich specialize in CNC machining centers for technical mountaineering certification.
Norway
Wet-climate consumer expectations displace conventional leather treatments with Gore-Tex waterproof-breathable laminates across retail channels. The country's national environmental regulator enforces strict biodegradability standards for outdoor equipment end-of-life disposal. Oslo and Bergen outdoor retailers now stock predominantly membrane-equipped product lines.
United Kingdom
Scottish Highlands mountaineering standards drive premium procurement for technical ice-traction systems among serious backpackers. Health and Safety Executive workplace regulations influence professional outdoor guide equipment specifications. Glasgow and Edinburgh specialty retailers concentrate distribution for hybrid approach-shoe compatible systems.
China
Tungsten mining concentration in Chinese regions creates supply-side pressure for carbide spike input costs affecting technical cleat manufacturers. The Ministry of Ecology and Environment enforces dual carbon goals constraining heavy metal processing facilities. Yangtze River Delta manufacturing hubs specialize in rapid-prototyping workflows for trail running aluminum composite platforms.
Hiking Cleats Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers bridge previously separate product categories into unified traction platforms. The vendor base organizes around three tiers: mass-market coil-system suppliers, technical mountaineering specialists with certification infrastructure, and rapid-prototyping trail running innovators. Strategic archetypes include heritage metalworking firms leveraging Alpine manufacturing legacies, synthetic material specialists pursuing EU Green Deal compliance premiums, and direct-to-consumer disruptors unbundling fitting services. Capacity expansion and technology licensing represent the dominant competitive moves, particularly for water-based adhesive processes and carbide-reinforced elastomer compounds.
Within the heritage metalworking tier, Kahtoola and Hillsound occupy positions exemplifying ice-traction heritage and specialized approach-shoe compatibility respectively. Yaktrax anchors the mass-market accessibility archetype through broad retail distribution channels. These three companies represent the competitive spectrum from technical certification-dependent premium positioning to volume-driven coil-system accessibility, with each archetype responding differently to trail running adoption restructuring demand patterns across outdoor retail channels.
| Leading Market Players |
|---|
| Fusigo |
| Kahtoola |
| Hillsound |
| Yaktrax |
| Icetrax |
| Wowobjects |
| Boxoon |
| Astyer |
| Teamland |
| Others |
Value Network & Pricing Analysis
Alpine rescue procurement standards mandating slope-angle certification for stainless-steel spike configurations force manufacturers toward CNC machining centers in Bavaria and Baden-Württemberg, concentrating supply-side capability and sustaining premium pricing tiers for institutional buyers.
Pricing Analysis
Carbide and tungsten input-cost pass-through from Chinese mining regions compresses margins for technical mountaineering cleats while coil-based mass-market alternatives absorb less volatility. Three-tier pricing structure across premium, standard, and economy levels separates certified Alpine rescue systems from trail running composites and entry-level elastomer harnesses. Price differentiation hinges on ASTM traction-testing compliance and Gore-Tex membrane integration. Casual winter walkers in mass retail show highest price sensitivity; professional guides and avalanche specialists demonstrate lowest sensitivity where performance guarantees dominate procurement criteria.
Supply Chain Analysis
Reverse-logistics flows for end-of-life cleat disposal face emerging EU biodegradability mandates, requiring manufacturers to design for material recovery and remanufacturing. Production concentrates in Germany, China, and the United States, with Bavarian clusters specializing in certified metalworking and Yangtze River Delta hubs driving rapid-prototyping workflows. Raw material dependencies center on tungsten carbide, stainless steel feedstock, and Gore-Tex membrane laminates. Single-source vulnerability in Chinese tungsten supply creates structural risk for spike fabrication. Distribution runs through specialty outdoor retailers in the Pacific Northwest and Scandinavian markets, with direct-to-consumer channels expanding for trail running subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as trail running adoption pulls demand toward lighter, multi-terrain systems with premium material specifications displacing conventional treatments.
For Market Incumbents: Anticipate coil-based microspike substitution threats from mass-market competitors by deepening certification moats around Alpine rescue procurement and accelerating water-based adhesive R&D to satisfy REACH framework evolution. Vertical integration into Bavarian CNC machining capacity defends margin position against import-dependent brands facing extended ASTM compliance timelines. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting trail runner replacement cycles in the Pacific Northwest, where year-round muddy conditions extend addressable seasons. Approach-shoe compatibility white space in North American retail offers lowest competitive density. Biomechanical assessment unbundling in Scandinavian markets provides service-attach revenue streams distinct from product margin competition. For Investors and Strategic Acquirers: Asymmetric upside sits with rapid-prototyping trail running innovators possessing bio-based synthetic material pipelines aligned with EU Green Deal mandates. Long-term viability over the next decade favors brands with circular economy positioning and PFAS-free certification ahead of regulatory phase-outs. Monitor tungsten supply disruption indicators and REACH chemical framework expansion timelines as inflection signals for margin compression versus premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Adhesive Transition | REACH compliance opens premium positioning in German Alpine procurement channels. |
| Direct-to-Consumer Channel Expansion | Virtual try-on tools capture trail runner replacement cycles in Pacific Northwest markets. |
| Carbide-Reinforced Elastomer Integration | Hybrid spike configurations bridge trail running and technical ice travel categories. |
| PFAS-Free Membrane Certification | Norwegian and Scottish wet-climate retailers now demand PFAS-free alternatives. |
| Approach-Shoe Compatibility Development | Modular harness systems address underdeveloped white space in North American retail. |
Research Methodology
Multiple input streams — primary interviews with product development directors at mountaineering equipment manufacturers, procurement leads from Alpine rescue services, specialty retail buyers in Seattle and Oslo, and secondary validation against ASTM International testing protocols, EU REACH chemical framework filings, and customs trade data for tungsten carbide imports — were reconciled through bottom-up segment enumeration and top-down market sizing triangulation.
Historical shipment data from CNC machining centers and rapid-prototyping facilities were cross-referenced against panel input from Bavarian manufacturing clusters and Yangtze River Delta composite specialists across the analysis window. Segmentation dimensions modeled include product type, material platform, size distribution, and end-user archetype. CAGRs were derived from slope-angle certification adoption curves and trail running participation rates. Forecast inputs incorporated EU Green Deal implementation timelines and biodegradability standard evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tungsten supply disruption or accelerated PFAS phase-out scenarios. Practitioners should monitor REACH chemical framework expansion, Alpine rescue procurement specification changes, and direct-to-consumer channel penetration rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Hiking Backpacks Market
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
Mountain Bike Market
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
India Spectator Sports Market
Outdoor and Adventure Activities
Wakeboard Market
Outdoor and Adventure Activities
Outdoor Backpack Market
Outdoor and Adventure Activities
Motorized Pool Tube Market
Outdoor and Adventure Activities
Snowshoes Market
Outdoor and Adventure Activities
Hiking Accessories Market
Outdoor and Adventure Activities
Global Water Bikes Market
Outdoor and Adventure Activities
Snorkeling Market
Outdoor and Adventure Activities
Hiking Gear and Equipment Market
Outdoor and Adventure Activities
Ski Vacation Market
Outdoor and Adventure Activities
Paragliding Equipment Market
Outdoor and Adventure Activities
Kayak Market