
 North America Personal Watercraft Market | 2026-2036
North America Personal Watercraft Market Size, Share, and Industry Trends Forecast 2026-2036
North America Personal Watercraft Market Analytics
Polyethylene hull composites is recalibrating cost structures across the North America personal watercraft supply base, displacing traditional fiberglass in mid-range models without sacrificing impact resistance. Sea-Doo (BRP) leverages its Rotax powertrain integration to sustain manufacturing efficiency at its Querétaro-adjacent North American supply node. Yamaha Motor Corporation anchors the premium sit-down segment through its SuperJet and FX cruiser lines, while Taiga Motors differentiates via proprietary electric drivetrain architectures purpose-built for cold-climate lake operation.
Personal watercraft denotes motorized vessels under four meters in length, propelled by inboard jet pumps generating thrust through an impeller-housing assembly rather than external propellers, with hull designs prioritizing planing efficiency at 40-70 mph operational speeds for recreational marine surface travel. Sit-down configurations dominate unit economics due to family-oriented buyer profiles and higher average selling prices, though electric propulsion within the engine capacity taxonomy represents the fastest-expanding margin pool as battery energy density improves for waterborne applications. Distribution through dealership networks retains structural importance for pre-purchase water testing and service bundling, while online retail channels capture growing share among replacement-part and accessory transactions.
The EPA administers marine engine emissions standards under Clean Air Act Title II provisions, compelling OEMs to deploy catalytic aftertreatment or pivot toward battery-electric architectures, while Transport Canada aligns with progressively stringent Environment and Climate Change Canada regulations affecting cross-border product homologation. The US Coast Guard enforces flotation and structural integrity standards that shape hull design minimums and occupant capacity labeling. Stakeholders must monitor how state-level waterway access restrictions and electrification infrastructure commitments at municipal marina systems reshape product portfolio priorities and regional go-to-market investments.
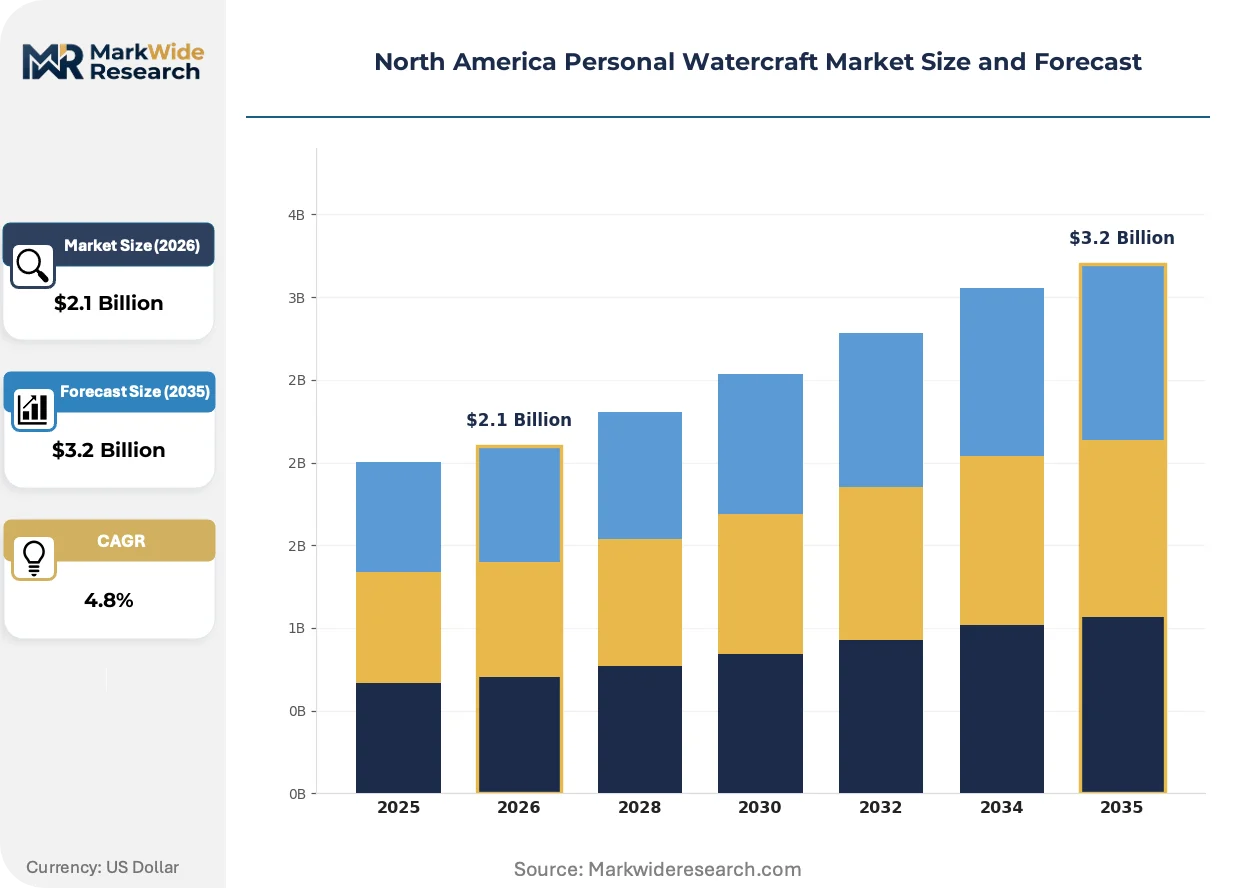
Market Dynamics
Electrification mandates from the EPA are forcing combustion-engine retooling across the North American personal watercraft supply base, while polyethylene hull materials compress production costs for mid-range manufacturers competing against premium fiberglass architectures.
Growth Catalysts
- EPA Tier 3 Marine Emissions Standards:Regulatory pressure accelerates catalytic aftertreatment deployment and battery-electric R&D investments, opening compliance-driven product refresh cycles.
- Great Lakes Marina Infrastructure:Municipal electrification commitments across Michigan, Wisconsin, and Ontario expand charging accessibility for electric personal watercraft adoption.
- Polyethylene Rotomolding:Hull fabrication cost reductions of 15-20% versus fiberglass enable competitive pricing in family-oriented sit-down segments without durability penalties.
Market Restraints
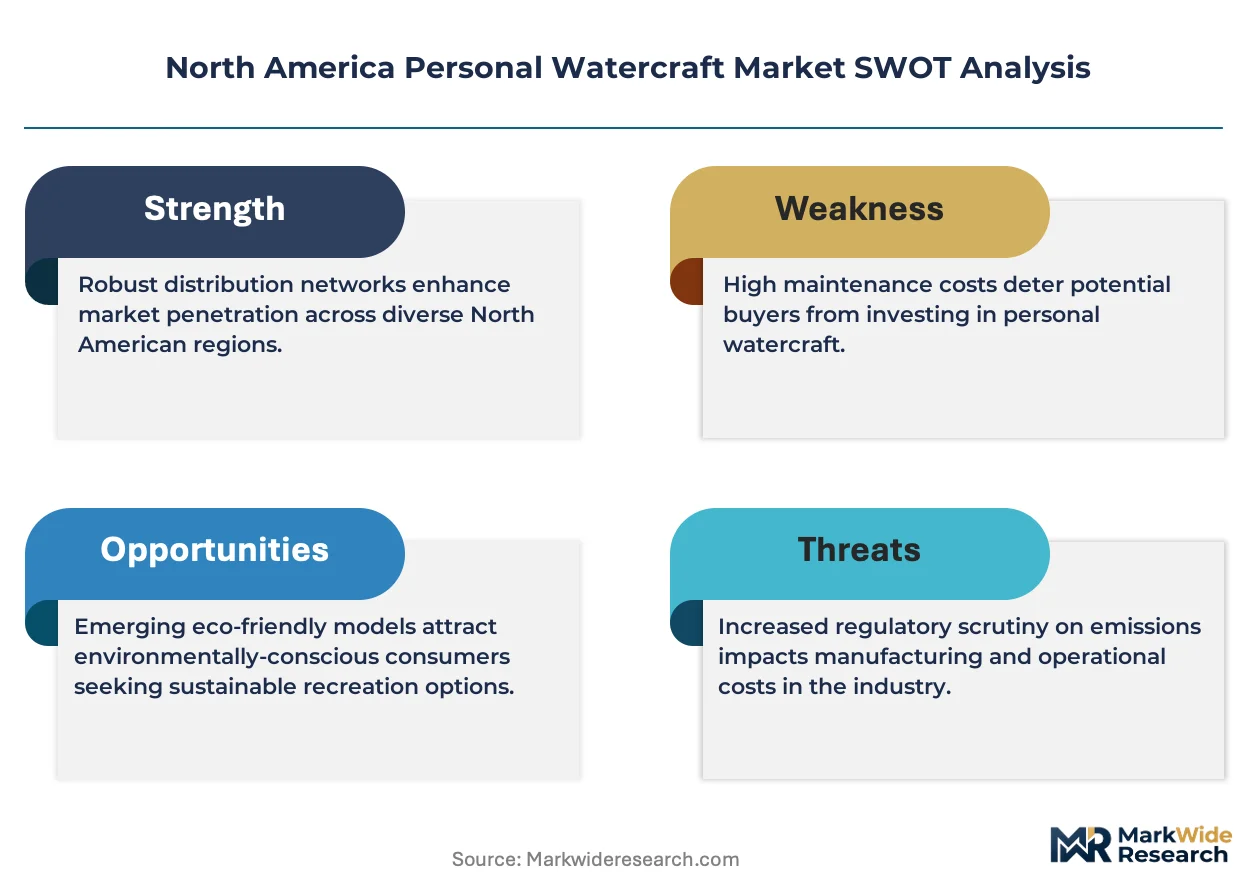
- Lithium-Ion Battery Supply Concentration:Cathode material dependency on Asian processing facilities creates input cost volatility and geopolitical exposure for electric propulsion roadmaps.
- Seasonal Demand Compression:Northern climate zones limit operational months to 4-5 months annually, constraining fleet utilization rates and resale value retention.
- Coast Guard Flotation Standards:Structural integrity testing protocols add 8-12 months to new hull design certification timelines, delaying product launches.
Strategic Opportunities
- Florida Intracoastal Network Expansion:Year-round operational climate and 1,200+ miles of navigable waterways support premium electric fleet deployment for rental operators.
- California Air Resources Board Incentives:Marine vessel electrification rebates up to $5,000 per unit accelerate consumer adoption in the largest state market.
- Direct-to-Consumer Accessory Channels:Online retail platforms capture replacement part and customization spend currently fragmented across 800+ independent dealerships.
Industry Challenges
- Marine Electric Powertrain Calibration:Saltwater corrosion resistance and thermal management expertise scarcity constrains OEM hiring for next-generation engineering teams.
- Cross-Border Homologation Friction:Divergent Transport Canada and US Coast Guard certification requirements force dual testing protocols for unified North American product strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Personal Watercraft Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up PWC, Sit-Down PWC, Sport PWC, Luxury PWC Engine Capacity: Below 1000cc, 1000cc to 1500cc, Above 1500cc, Electric End User: Recreational Users, Commercial Rentals, Competitive Riders, Tour Operators Distribution Channel: Online Retail, Dealerships, Boat Shows, Direct Sales |
| Companies Covered | Taiga Motors, Malibu Boats, Sea-Doo (BRP), Brunswick Corporation, Correct Craft, Yamaha Motor Corporation, MasterCraft Boat Holdings, Polaris Industries, Kawasaki Motor Manufacturing USA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Personal Watercraft Market Evolving Landscape
Material substitution and powertrain electrification are compressing traditional competitive moats in personal watercraft manufacturing, while regulatory compliance costs reshape portfolio prioritization toward cleaner architectures.
Closed-cell polyethylene rotomolding is overtaking hand-laid fiberglass in hull fabrication for recreational sit-down models. Family-oriented buyers across Florida and Texas coastal counties now specify impact-resistant polymer hulls for dockside durability. This material transition is compressing manufacturing cycle times from 14 days to 72 hours for mid-range production runs.
Transport Canada's alignment with Environment and Climate Change Canada regulations is tightening cross-border emissions homologation requirements. OEMs must now certify catalytic converter efficiency or battery-electric range equivalence under unified North American test protocols. The premium cruiser segment is responding with modular powertrain architectures enabling rapid gasoline-to-electric swaps at assembly lines.
After-sales service unbundling is fragmenting traditional dealership revenue models across the Great Lakes basin. Independent repair shops and mobile marine technicians now capture 30-40% of routine maintenance spend previously monopolized by authorized dealers. Ontario and Michigan waterways exhibit the fastest channel disintermediation as diagnostic tool standardization enables third-party service access.
North America Personal Watercraft Market Segmentation
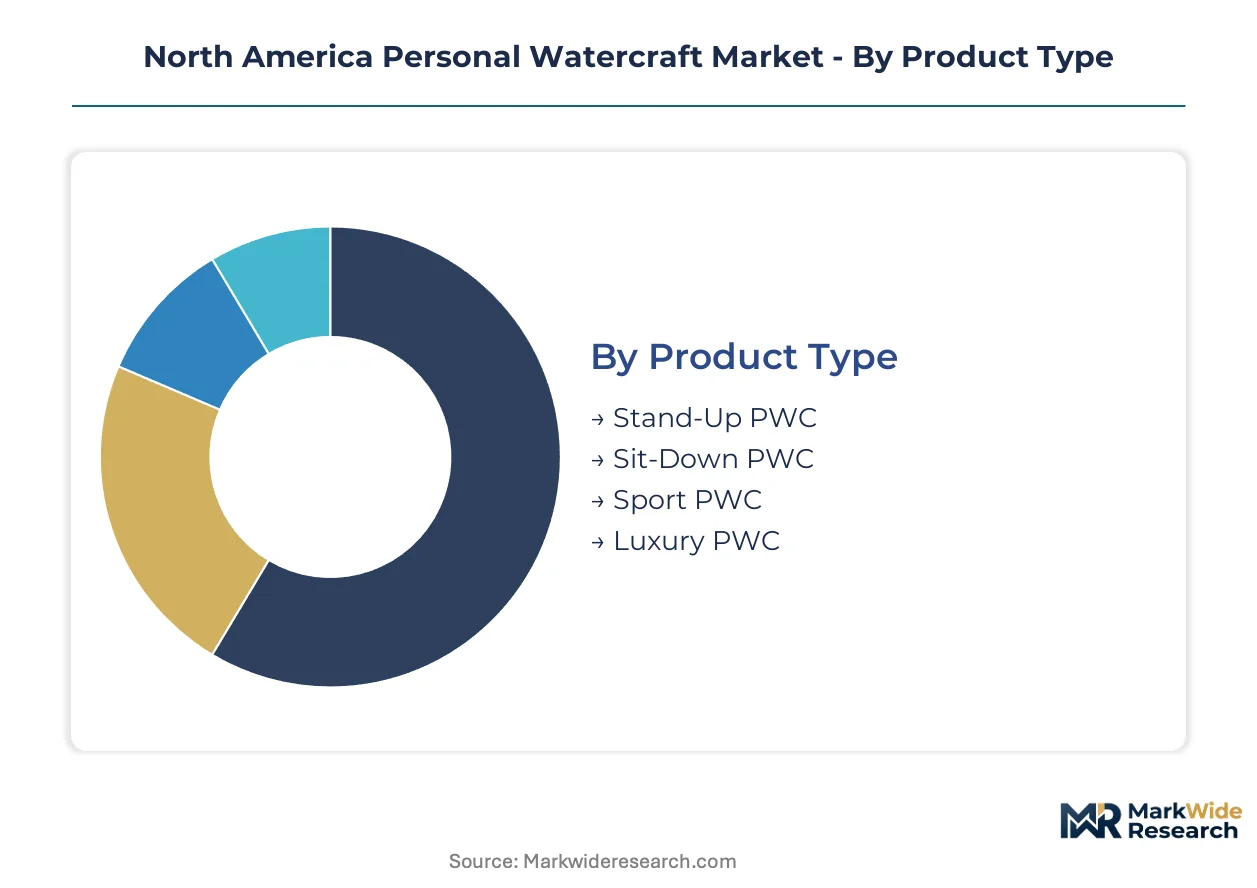
Personal watercraft manufacturers configure product portfolios around divergent certification pathways, with EPA marine emissions tiers and US Coast Guard flotation standards creating distinct compliance burdens across hull geometries and propulsion architectures. Segmentation strategy directly determines which testing protocols govern homologation timelines and regional market access.
Product Type:
EPA Tier 3 marine emissions compliance and US Coast Guard flotation certification requirements vary substantially across hull configurations, with sit-down architectures facing extended structural integrity testing protocols compared to stand-up alternatives.
- Sit-Down PWC:Enclosed hull designs accommodate 2-3 occupants with integrated storage compartments and windscreen protection. Family-oriented buyers across Florida's intracoastal waterways and Great Lakes marina networks drive specification for polyethylene rotomolded hulls that withstand dockside impact without fiberglass repair costs. EPA catalytic aftertreatment integration is standard across this segment's gasoline powertrains.
- Stand-Up PWC:Compact hulls under 2.5 meters prioritize maneuverability for single riders, with minimal superstructure reducing flotation material requirements under Coast Guard protocols. Competitive riders and rental operators in California coastal counties specify these units for agility training and surf rescue applications, though limited battery space constrains electric conversion feasibility.
- Sport PWC:Performance-tuned hull geometries with stepped bottoms and reinforced sponsons target 60-70 mph operational speeds. Acceleration-focused specifications concentrate among Texas Gulf Coast buyers and Arizona lake enthusiasts.
- Luxury PWC:Extended cruiser platforms integrate premium seating, audio systems, and touchscreen navigation. High-margin configurations dominate Great Lakes summer home owner purchases.
Sit-Down PWC sits at the top of the volume ranking, with Sport PWC climbing the fastest.
Engine Capacity:
Cost tier stratification aligns with displacement brackets, where manufacturing complexity and aftertreatment hardware scale non-linearly with cylinder volume.
- Electric:Proprietary battery pack architectures from Taiga Motors and emerging OEMs deliver 60-90 minute operational range with zero direct emissions. Municipal electrification infrastructure commitments across Michigan and Ontario marinas are expanding charging accessibility, though lithium-ion cathode supply concentration creates input cost volatility.
- Above 1500cc:Supercharged four-stroke powertrains from BRP's Rotax and Yamaha Motor Corporation anchor premium cruiser performance. Coast Guard structural testing for these heavier powertrain packages adds certification complexity.
- 1000cc to 1500cc:Naturally aspirated mid-displacement engines balance fuel efficiency with planing performance. Family rental fleets across Florida's 1,200-mile intracoastal network standardize on this bracket for operational cost control.
- Below 1000cc:Compact two-stroke and entry-level four-stroke configurations serve youth training and lightweight recreational applications. EPA Tier 3 compliance is driving rapid phase-out in favor of cleaner alternatives.
Above 1500cc commands the highest average selling prices, while Electric is expanding most quickly.
End User:
Customer type determines fleet utilization patterns and service bundling requirements, with commercial operators demanding extended warranty terms and volume pricing structures unavailable to individual purchasers.
- Recreational Users:Individual and family purchasers across coastal and lake communities prioritize weekend accessibility and seasonal storage solutions. Florida's year-round operational climate supports highest per-capita ownership rates.
- Commercial Rentals:Fleet operators along California's coastal counties and Lake Michigan shorelines require standardized maintenance protocols and rapid-turnaround durability. California Air Resources Board electrification rebates up to $5,000 per unit are accelerating battery-electric fleet conversion timelines.
- Competitive Riders:Amateur and professional racing circuits specify modified hulls and powertrains outside standard homologation pathways. Aftermarket component demand concentrates through specialized distributors.
- Tour Operators:Guided excursion providers across Ontario's Thousand Islands and Washington State's Puget Sound emphasize passenger capacity and stability ratings. Transport Canada certification requirements add cross-border operational complexity.
Recreational Users generate the largest absolute unit volume, with Commercial Rentals gaining share fastest.
Distribution Channel:
Geography shapes channel effectiveness, with water-accessible locations enabling pre-purchase testing that online platforms cannot replicate.
- Dealerships:Authorized networks across Texas, Florida, and Michigan provide water testing, financing bundling, and seasonal service contracts. Structural importance persists despite 30-40% maintenance spend fragmentation to independent shops.
- Online Retail:Replacement parts, accessories, and customization components migrate fastest to digital channels. Diagnostic tool standardization is enabling third-party service access across the Great Lakes basin.
- Boat Shows:Seasonal exhibitions in Chicago, Miami, and Toronto concentrate high-intent buyers for premium model launches. Coast Guard flotation demonstrations and EPA compliance documentation are standard presentation elements.
- Direct Sales:Manufacturer-controlled channels serve fleet accounts and specialty configurations bypassing dealer markups. Cross-border homologation friction limits unified North American direct sales strategies.
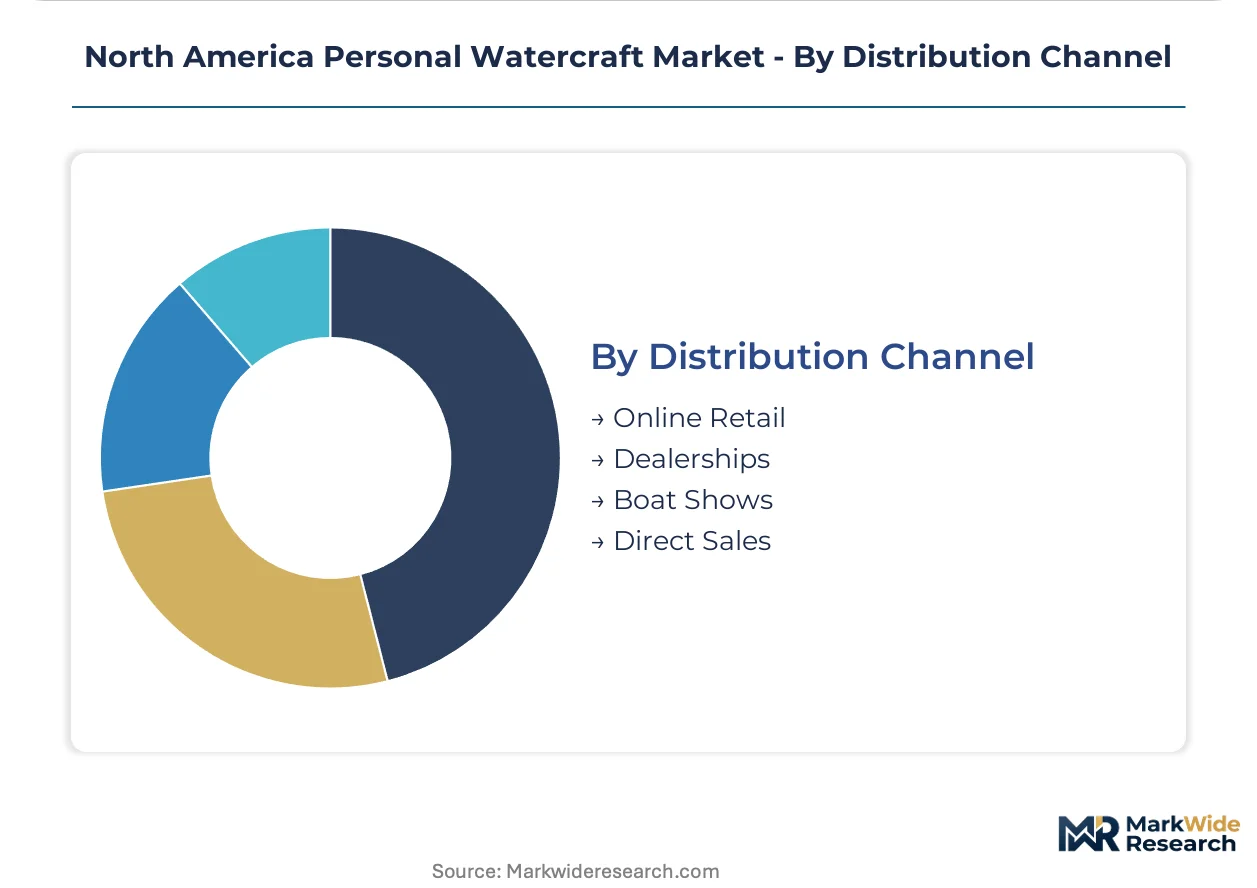
Dealerships retain the dominant volume position, with Online Retail climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida's intracoastal waterways anchor North American personal watercraft demand concentration, with Great Lakes marina networks and California coastal counties forming secondary density clusters. State-level electrification commitments and EPA marine emissions enforcement reshape product portfolio priorities across sub-regional markets.
United States
Florida's 1,200-mile navigable intracoastal network supports year-round fleet utilization rates unmatched in northern climates. EPA Tier 3 marine emissions standards compel catalytic aftertreatment deployment across gasoline powertrains sold nationwide. California Air Resources Board electrification rebates up to $5,000 per unit accelerate battery-electric adoption in the largest state market.
Canada
Ontario's Thousand Islands and British Columbia's coastal corridors concentrate recreational ownership among seasonal cottagers. Transport Canada aligns with Environment and Climate Change Canada regulations tightening cross-border emissions homologation requirements. Quebec's marina electrification infrastructure commitments expand charging accessibility for electric personal watercraft across the St. Lawrence River basin.
Mexico
Baja California Sur's Cabo San Lucas corridor and Quintana Roo's Cancún-Riviera Maya zone attract rental fleet investment from North American operators. Mexican environmental regulations under SEMARNAT progressively align with EPA marine emissions frameworks. Nuevo León's industrial manufacturing base near Monterrey supplies rotational-molded polyethylene hull components to regional assemblers.
North America Personal Watercraft Market Competitive Landscape
Portfolio diversification dominates the current landscape as established marine manufacturers pivot toward electrification and material substitution. The vendor base concentrates around three strategic archetypes: legacy power sports conglomerates with integrated powertrain capabilities, specialized electric vehicle entrants with proprietary battery architectures, and diversified boat builders extending into personal watercraft adjacent segments. Competitive intensity manifests through polyethylene hull material transitions compressing manufacturing cycle times and modular powertrain architectures enabling rapid gasoline-to-electric assembly line swaps.
Within the electric propulsion tier, Taiga Motors exemplifies cold-climate battery-electric specialization purpose-built for lake operation. Sea-Doo (BRP) occupies a position as the integrated powertrain incumbent leveraging Rotax manufacturing efficiency. Yamaha Motor Corporation anchors the premium sit-down segment through cruiser and performance line diversification. These three represent distinct competitive vectors—pure-play electrification, combustion-engine optimization, and premium segment consolidation—shaping strategic positioning across the North American supply base.
| Leading Market Players |
|---|
| Taiga Motors |
| Malibu Boats |
| Sea-Doo (BRP) |
| Brunswick Corporation |
| Correct Craft |
| Yamaha Motor Corporation |
| MasterCraft Boat Holdings |
| Polaris Industries |
| Kawasaki Motor Manufacturing USA |
| Others |
Value Network & Pricing Analysis
Family-oriented rental fleet operators across Florida's intracoastal network anchor pricing power through volume procurement contracts, compressing margin structures for mid-range polyethylene hull manufacturers while premium fiberglass cruiser builders retain pricing autonomy through performance differentiation.
Pricing Analysis
Input-cost pass-through from lithium-ion cathode material volatility and EPA catalytic aftertreatment hardware is intensifying price erosion across electric and gasoline powertrain tiers respectively. Three-tier pricing structure across premium, standard, and economy levels separates luxury cruiser configurations with integrated audio and navigation from family sit-down models and entry-level stand-up units. Price differentiation hinges on hull material grade and Coast Guard flotation certification tier. Commercial rental fleets exhibit highest price sensitivity due to utilization-rate economics, while individual recreational buyers in Texas and Arizona lake communities show lowest sensitivity for performance-tuned sport configurations.
Supply Chain Analysis
Freight cost exposure from Asian lithium processing facilities to North American assembly nodes is elevating landed costs for electric propulsion components versus localized polyethylene rotomolding operations. Manufacturing concentration spans Mexico for hull component supply, the United States for final assembly and powertrain integration, and Asian battery cell production. Raw material dependencies encompass cathode active materials, rotational molding-grade polyethylene resin, and marine-grade aluminum alloys. Single-source vulnerability in battery supply creates structural risk. Distribution runs through authorized dealership networks with water-accessible testing locations, though online channels capture growing accessory and replacement part volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on polyethylene hull cost compression displacing fiberglass in mid-range family segments, while electric powertrain premiumization captures higher average selling prices as battery energy density improves.
For Market Incumbents: Anchor defensive positioning through backward integration into rotational molding operations near Querétaro-adjacent supply nodes and captive catalytic aftertreatment manufacturing to offset EPA compliance cost inflation. Consolidate dealership service revenue against independent shop fragmentation by proprietary diagnostic tool deployment across Great Lakes basin networks. Taiga Motors' cold-climate electric specialization represents the emerging entrant threat requiring monitoring. For New Entrants and Emerging Players: Enter via California coastal counties where Air Resources Board electrification rebates accelerate fleet conversion timelines and regulatory tailwinds reduce customer acquisition friction. Target commercial rental operators in Lake Michigan and Ontario marina networks as the most penetrable segment given standardized maintenance protocols and rapid-turnaround durability requirements. Pursue direct-to-consumer accessory channels as the primary go-to-market angle to bypass established dealership gatekeeping. For Investors and Strategic Acquirers: Marine power sports conglomerates with integrated Rotax-equivalent powertrain capabilities are the most active acquirer in this space, seeking electric drivetrain engineering talent and polyethylene hull fabrication expertise. Long-term viability over the next decade favors modular powertrain architectures enabling rapid gasoline-to-electric assembly line swaps. Acquisition target archetypes include cold-climate battery-electric specialists and rotational molding equipment operators. Watch Transport Canada-EPA emissions harmonization progress as the signal indicating cross-border product strategy consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Powertrain Architecture Development | Enables rapid gasoline-to-electric swaps at BRP and Yamaha assembly lines responding to EPA Tier 3 mandates. |
| Polyethylene Rotomolding Capacity Expansion | Compresses hull fabrication cycle times from fourteen days to seventy-two hours for mid-range family models. |
| Marina Electrification Infrastructure Partnership | Secures charging accessibility commitments across Michigan, Wisconsin, and Ontario municipal networks. |
| Direct-to-Consumer Accessory Platform Launch | Captures replacement part spend fragmenting from 800-plus independent dealerships to online channels. |
| Cross-Border Homologation Certification Investment | Resolves dual Transport Canada and US Coast Guard testing protocol friction for unified North American products. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market combining executive interviews with OEM product planners, marina operators, and rental fleet managers alongside secondary validation through EPA marine emissions filings, Transport Canada certification databases, and state-level electrification infrastructure disclosures. Bottom-up unit shipment estimates triangulate against top-down value projections derived from powertrain tier and hull material segmentation.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects within sit-down, stand-up, sport, and luxury product categories. Segmentation dimensions modeled encompass hull configuration, engine capacity bracket including electric architectures, end-user type, and distribution channel structure. CAGRs derive from regression analysis against macroeconomic indicators and regulatory enforcement timelines. Forecast inputs incorporate marina electrification commitment schedules and polyethylene resin cost curves.
Inputs from OEM production schedules and municipal infrastructure databases were available through the study window; gaps in commercial rental fleet utilization telemetry introduce uncertainty bands around electric adoption trajectory assumptions. Forecasts reflect documented assumptions regarding EPA Tier 3 enforcement consistency and lithium supply chain stability. A model refresh is warranted upon material change in Transport Canada-EPA harmonization negotiations or cathode material processing facility expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Kitesurf Kites Market
Outdoor and Adventure Activities
Speed Chute Market
Outdoor and Adventure Activities
Global Climbing Shoes Market
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
Rafting Equipment Market
Outdoor and Adventure Activities
Hiking Backpacks Market
Outdoor and Adventure Activities
Asia-Pacific Spectator Sports Market
Outdoor and Adventure Activities
Global Personal Watercraft Market
Outdoor and Adventure Activities
Hydration Packs Market
Outdoor and Adventure Activities
Kayak Market
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
Ski Vacation Market
Outdoor and Adventure Activities
Snowshoes Market
Outdoor and Adventure Activities
Recreational Use Water Chute Market
Outdoor and Adventure Activities
United States and Europe Horse Racing Market
Outdoor and Adventure Activities
Motorized Pool Tube Market