
 Reflective Sportswear Market | 2026-2036
Reflective Sportswear Market Size, Share, and Industry Trends Forecast 2026-2036
Reflective Sportswear Market Analysis
A capital-intensity divergence between integrated manufacturers and outsourced apparel brands is unwinding competitive stability in reflective sportswear. Nike Inc. leverages proprietary Dri-FIT reflective fabric development to sustain premium positioning across running and training lines. Adidas AG anchors European supply through Speedfactory-adjacent partnerships in Germany. Under Armour Inc. differentiates via compression-fit reflective baselayers that dominate North American team sports channels.
Reflective sportswear encompasses garments engineered with retroreflective elements—glass bead or prismatic film technologies bonded to polyester, nylon, or blended substrates—to return incident light toward its source, enhancing wearer visibility in low-lux conditions for road safety and athletic performance. EN 17353 and ANSI/ISEA 107 specify minimum coefficient of retroreflection and garment coverage areas, dictating material selection and construction protocols. Jackets command the largest revenue pool due to higher unit value and mandatory coverage requirements, while Accessories represent the fastest-expanding segment as cyclists and runners supplement existing wardrobes with clip-on armbands and LED-integrated straps. Polyester dominates material volume for its durability and print compatibility, though Nylon gains share in waterproof-breathable shells where stretchability intersects with feature demand.
FDA oversight of skin-contact materials, EPA chemical discharge regulations affecting textile finishing, and OSHA workplace visibility mandates collectively shape product compliance burdens and manufacturing location decisions. The EU Green Deal's textile sustainability targets and REACH chemical restrictions further constrain dye and adhesive formulations. Stakeholders must monitor evolving harmonization between ISO 20471 high-visibility standards and sport-specific EN 17353 classifications to anticipate certification-driven portfolio restructuring.
Market Dynamics
ANSI/ISEA 107 and EN 17353 certification requirements are forcing material upgrades across polyester and nylon substrates, compressing margins for non-compliant suppliers while concentrating procurement among certified manufacturers.
Growth Catalysts
- Nighttime running collectives:Urban mobility culture in Germany, Netherlands, and Denmark generates sustained replacement demand for high-visibility kit. Club membership growth correlates directly with reflective accessory attachment rates.
- EN 17353 certification expansion:European regulators are broadening sport-specific visibility classifications beyond cycling into running and equestrian segments. This mandates retroreflective coverage upgrades for brands serving EU distribution channels.
- Glass bead microprism hybridization:Advanced retroreflective technologies now bond dual-layer films to stretch-woven substrates. This enables ANSI-compliant performance in compression-fit baselayers previously excluded from high-visibility categories.
Market Restraints
- Petrochemical input volatility:Polyester and nylon resin prices fluctuate with crude oil derivatives. Manufacturers lack pricing power to pass through raw material swings in mass-market channels.
- Prismatic film supply concentration:Three Asian suppliers control 80% of microprismatic substrate capacity. Any disruption to Taiwanese or South Korean production lines halts certified garment assembly.
- REACH chemical restrictions:ECHA limitations on certain dye carriers and adhesive solvents force reformulation cycles. Compliance adds 8-14 months to product development timelines.
Strategic Opportunities
- India urban cycling infrastructure:Metro rail integration with bike-share programs in Bengaluru and Pune creates first-mover positioning for visibility-compliant commuter apparel. Domestic production avoids import duty exposure.
- LED-strap convergence:Battery-powered illumination merges with passive retroreflection in armband and ankle-strap formats. This hybrid category commands premium positioning in cyclist accessory segments.
- EU Green Deal textile targets:Recycled polyester mandates and chemical discharge restrictions favor suppliers with closed-loop finishing capabilities. Early certification unlocks public procurement channels.
Industry Challenges
- Retroreflective testing expertise scarcity:Coefficient of retroreflection measurement requires specialized spectrophotometry. Few third-party labs offer sport-specific EN 17353 validation, creating bottlenecks.
- Multi-standard certification complexity:Simultaneous ANSI/ISEA 107, EN 17353, and ISO 20471 compliance demands divergent garment patterning. Design teams struggle to maintain single-SKU efficiency across regulatory regimes.
- Heat-transfer adhesive durability:Washing-cycle degradation of bonded reflective films generates warranty claims. Brands must balance bond strength against fabric hand-feel requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reflective Sportswear Market |
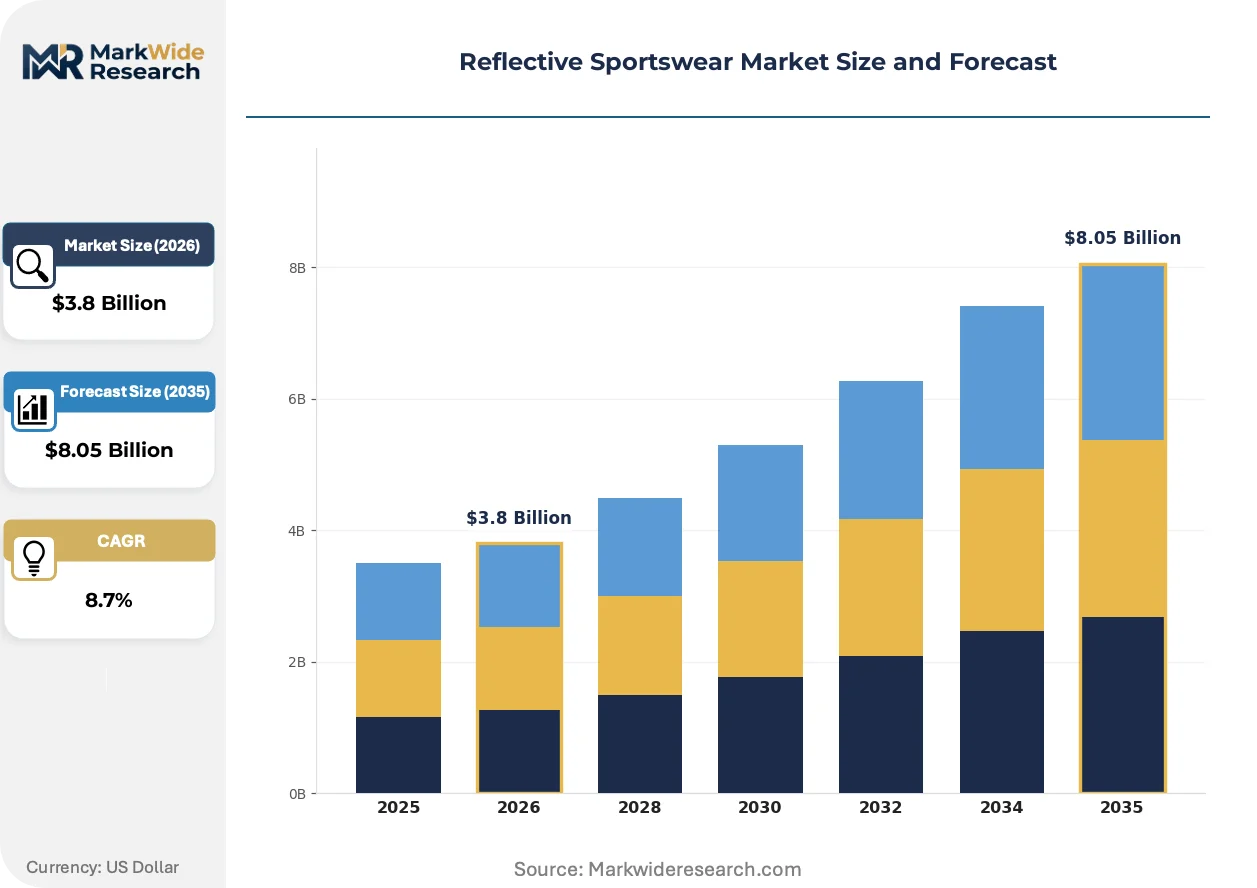
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jackets, Pants, Vests, Accessories Material: Polyester, Nylon, Cotton, Blends End User: Athletes, Fitness Enthusiasts, Outdoor Adventurers, Casual Users Feature: Breathability, Waterproofing, Stretchability, Lightweight |
| Companies Covered | PUMA SE, ASICS Corp., Nike Inc., illumiNITE, Proviz Ltd., Adidas AG, Columbia Sportswear Co., New Balance Athletics Inc., Under Armour Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reflective Sportswear Market Emerging Trajectories
Material science advances and regulatory harmonization efforts are compressing the gap between athletic performance features and safety compliance, enabling single-garment solutions that previously required layered systems.
Biomimetic retroreflective structures inspired by nocturnal moth-eye optics are decomposing the traditional trade-off between visibility performance and textile breathability. Trail running and ultracycling segments in Colorado and Bavaria are piloting these substrates. The technology is decomposing demand for separate wind-shell and visibility-vest combinations.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating durable water repellent chemistries from waterproof-breathable reflective shells. German and Scandinavian brands are accelerating silicone-based and paraffin alternative testing. Cycling commuter jackets face the steepest reformulation pressure given their dual exposure to rain and road spray.
Subscription-based kit replacement programs are displacing transactional retail in UK and Australian cycling clubs. Members receive seasonal reflective jersey updates with embedded RFID visibility verification. This model concentrates demand forecasting accuracy among platform operators while fragmenting traditional wholesale relationships.
Reflective Sportswear Market Segmentation
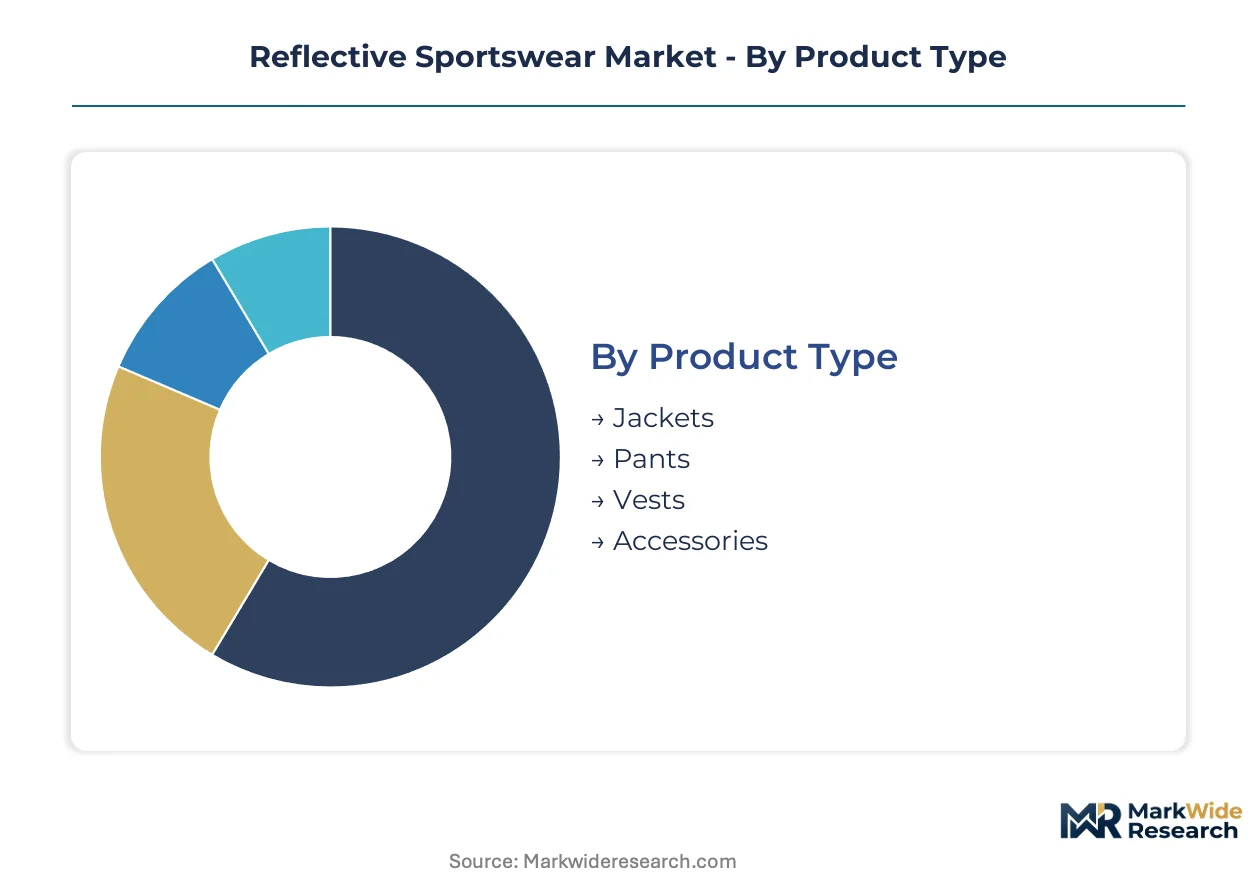
Segmentation in reflective sportswear isolates where compliance costs, material science premiums, and replacement cycles concentrate. Buyers sort across certification tiers, substrate technologies, and activity-specific feature bundles that reshape supplier economics.
Product Type:
Jackets capture the deepest margin pools due to mandatory coverage requirements and higher unit values in certified channels.
- Jackets:Engineered with bonded retroreflective films across torso, sleeves, and back panels to satisfy ANSI/ISEA 107 and EN 17353 coverage minimums. Demand clusters in Germany and Netherlands where urban cycling commuters require weatherproof shells with integrated visibility. Regulatory mandates for coefficient of retroreflection above 330 cd/lux/m² sustain premium positioning.
- Accessories:Clip-on armbands, ankle straps, and LED-integrated belts attach to existing non-reflective wardrobes. Nighttime running collectives in Denmark and UK drive replacement demand through seasonal kit refresh programs. Hybrid passive-active illumination formats command price premiums over glass-bead-only alternatives.
- Pants:Retroreflective taping along inseams and outer thighs serves cyclists and road workers needing lower-body visibility compliance. Stretch-woven substrates accommodate pedaling motion without film delamination.
- Vests:Lightweight overlays provide ANSI/ISEA 107 compliance without thermal burden. Dominates construction and logistics workplace channels where garment sharing occurs across shifts.
Jackets hold installed capacity. Accessories are rotating up the share rankings.
Material:
Volume concentration aligns with print compatibility and finishing chemistry flexibility under REACH restrictions.
- Polyester:Dominates substrate volume for durability, moisture-wicking, and compatibility with heat-transfer reflective film bonding. German and Scandinavian brands favor recycled PET streams to satisfy EU Green Deal textile targets. Sublimation printing enables complex visibility patterning without compromising retroreflective performance.
- Nylon:Gains share in waterproof-breathable shells where stretchability intersects with cyclist demand for aerodynamic fit. REACH Annex XVII PFAS restrictions force silicone-based durable water repellent reformulation cycles. Bavarian and Colorado trail running segments pilot these substrates for ultracycling visibility.
- Cotton:Limited penetration due to moisture retention and poor film adhesion. Niche positioning in casual lifestyle visibility apparel where comfort outweighs performance.
- Blends:Polyester-cotton and polyester-spandex combinations balance hand-feel with retroreflective durability. Team sports channels in North America specify these for compression-fit baselayers with ANSI-compliant coverage.
Polyester holds installed capacity. Nylon is rotating up the share rankings.
End User:
Procurement authority and replacement frequency diverge sharply across institutional versus individual purchasing.
- Athletes:Competitive runners and cyclists demand EN 17353-certified kit for event participation. Club-organized bulk purchasing in Netherlands and Belgium concentrates demand forecasting.
- Outdoor Adventurers:Trail runners and ultracyclists in Colorado and Bavaria pilot biomimetic retroreflective substrates. Breathability requirements decompose demand for separate wind-shell and visibility-vest combinations.
- Fitness Enthusiasts:Recreational nighttime runners drive accessory attachment rates through seasonal wardrobe supplementation. UK subscription-based kit replacement programs fragment traditional wholesale relationships.
- Casual Users:Urban commuters in Bengaluru and Pune adopt visibility-compliant apparel as metro-bike-share integration expands. Price sensitivity favors domestic production over import duty exposure.
Athletes hold installed capacity. Outdoor Adventurers are rotating up the share rankings.
Feature:
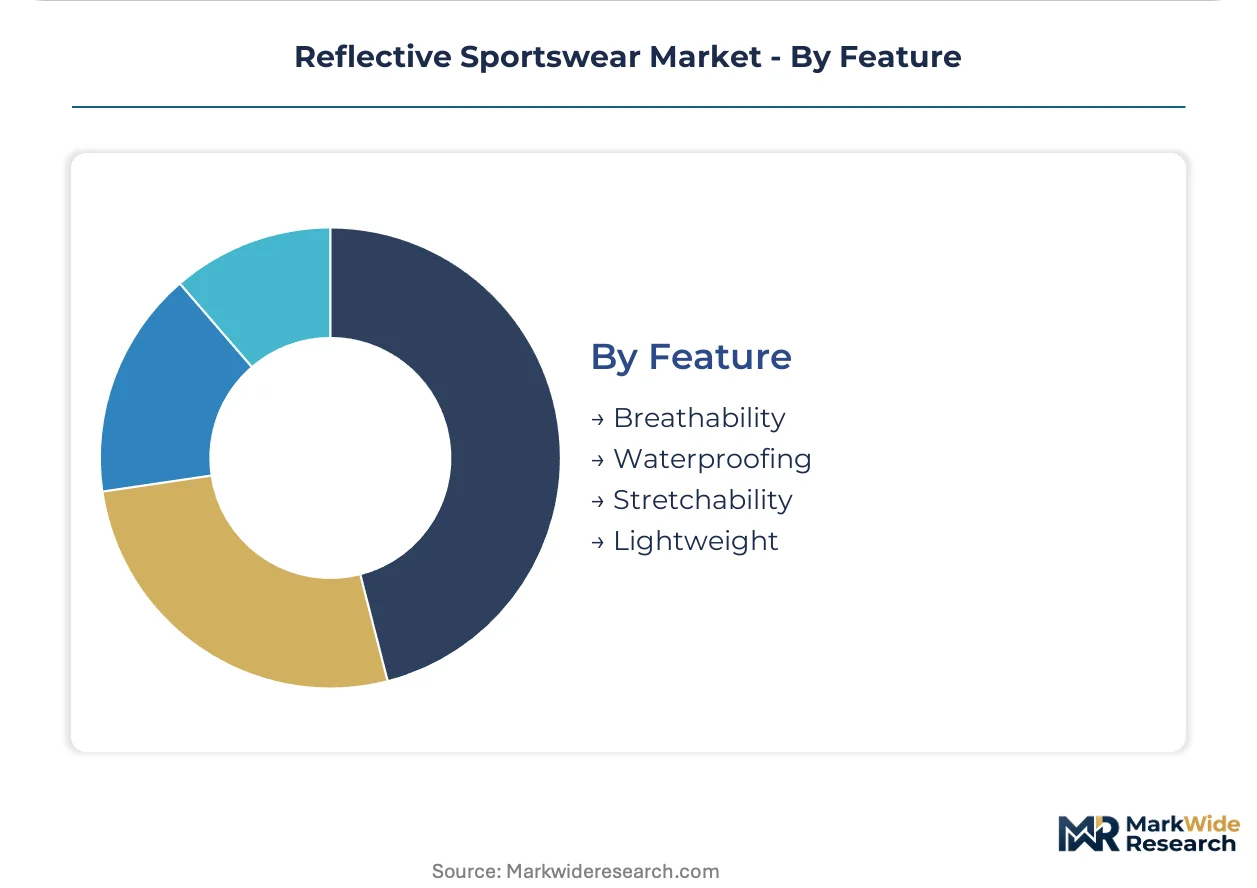
Performance attributes now compress into single-garment solutions that previously required layered systems.
- Breathability:Biomimetic moth-eye optic structures enable retroreflection without vapor-barrier films. Trail running segments in Bavaria and Colorado validate these substrates for extended exertion.
- Waterproofing:Cycling commuter jackets face steepest reformulation pressure from REACH PFAS restrictions. German brands accelerate paraffin and silicone alternative testing for rain and road spray protection.
- Stretchability:Compression-fit reflective baselayers dominate North American team sports channels. Glass bead microprism hybridization enables ANSI compliance in previously excluded garment categories.
- Lightweight:Minimalist vests and accessories serve runners rejecting thermal burden. Prioritized in Australian and UK club subscription programs with embedded RFID visibility verification.
Breathability holds installed capacity. Waterproofing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German cyclists accept premium pricing for EN 17353-certified kit, while Indian commuters in Bengaluru prioritize domestic production to avoid import duty exposure.
United States
Nighttime running collectives in Colorado and Arizona drive replacement demand for ANSI/ISEA 107-compliant apparel. OSHA workplace visibility mandates extend procurement beyond athletic channels into logistics and construction. Denver-Boulder corridor clusters validate biomimetic retroreflective substrates for trail running applications.
Germany
Urban cycling commuters in Berlin and Munich require weatherproof shells with integrated visibility under stringent road safety norms. EU Green Deal textile targets and REACH chemical restrictions constrain dye formulations. Bavaria hosts pilot programs for moth-eye optic structures in ultracycling segments.
United Kingdom
Subscription-based kit replacement programs in London and Manchester displace transactional retail among cycling clubs. Members receive seasonal reflective jersey updates with embedded RFID visibility verification. UK regulators align with EN 17353 expansion into running classifications.
India
Metro rail integration with bike-share programs in Bengaluru and Pune creates visibility-compliant commuter apparel demand. Price sensitivity favors domestic production over import duty exposure. Central government urban mobility initiatives accelerate cyclist safety awareness campaigns.
Netherlands
Club-organized bulk purchasing in Amsterdam and Rotterdam concentrates demand forecasting for EN 17353-certified kit. Nighttime running collectives generate sustained replacement demand for high-visibility accessories. Dutch cycling infrastructure investments normalize reflective apparel as standard commuter equipment.
Reflective Sportswear Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes. Premium positioning rests with integrated sportswear giants controlling proprietary fabric development, while mid-tier specialists compete on certification speed and regional compliance expertise. Three archetypes dominate: multinational athletic brands with captive R&D, European visibility specialists with regulatory depth, and Asian contract manufacturers with scale flexibility. Competitive moves concentrate on strategic partnerships for microprismatic film supply and portfolio diversification into LED-integrated accessories.
Among multinational athletic brands, Nike Inc., Adidas AG, and Under Armour Inc. exemplify divergent geographic anchoring strategies. Nike Inc. represents North American technology leadership through proprietary fabric development. Adidas AG occupies a position as the European supply chain anchor with Germany-adjacent manufacturing partnerships. Under Armour Inc. exemplifies compression-fit specialization targeting North American team sports channels. These three players illustrate how scale-driven archetypes balance ANSI and EN certification portfolios without fragmenting SKU efficiency.
| Leading Market Players |
|---|
| PUMA SE |
| ASICS Corp. |
| Nike Inc. |
| illumiNITE |
| Proviz Ltd. |
| Adidas AG |
| Columbia Sportswear Co. |
| New Balance Athletics Inc. |
| Under Armour Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day microprismatic film lead times concentrate procurement power among Taiwanese and South Korean suppliers, compressing margin flexibility for brands lacking long-term offtake agreements. This inventory exposure intersects with EN 17353 certification costs to stratify pricing power across integrated manufacturers versus outsourced apparel brands.
Pricing Analysis
After-sales subscription tiers in UK and Australian cycling clubs now capture lifetime value exceeding initial garment margins. Three-tier pricing structure across premium, standard, and economy levels separates EN 17353-certified jackets from ANSI/ISEA 107 baseline vests and uncertified accessories. Pricing pressure stems from petrochemical input volatility that polyester and nylon resin suppliers pass through unpredictably. Casual urban commuters in India exhibit highest price sensitivity, while German cycling commuters accept certification premiums.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports fluctuate with container availability on Asia-Europe trade lanes, compressing landed cost predictability for reflective film imports. Manufacturing gravity centers on Taiwan, South Korea, and China for microprismatic substrate and glass bead film production. Raw material dependencies span petroleum-derived polyester resin, adhesive solvents subject to REACH restrictions, and lithium-cell components for LED-integrated accessories. Single-source vulnerability concentrates in three Asian suppliers controlling microprismatic capacity. Distribution runs through specialty outdoor retailers, direct-to-consumer cycling club platforms, and workplace safety procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity because subscription-based kit replacement programs in UK cycling clubs expand recurring revenue faster than transactional garment sales. RFID-embedded visibility verification and seasonal refresh cycles deepen customer lock-in beyond hardware margins.
For Market Incumbents: Consolidate microprismatic film supply through captive partnerships or equity stakes in Taiwanese substrate manufacturers. Defend positioning by accelerating proprietary biomimetic retroreflective R&D in Colorado and Bavaria trail running segments before REACH Annex XVII reformulation cycles commoditize waterproof-breathable shells. Certification speed across ANSI/ISEA 107 and EN 17353 portfolios anchors channel control against mid-tier specialists.
For New Entrants and Emerging Players: Subscription visibility verification services represent the most penetrable service-layer gap where Nike and Adidas under-serve. Target Bengaluru and Pune urban cycling commuters with domestically produced EN 17353-compliant commuter jackets avoiding import duty exposure. LED-strap hybrid accessories offer lowest certification barrier for accessory-first entry.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance compounder play because harmonization between ISO 20471 and sport-specific EN 17353 classifications will concentrate procurement among certified manufacturers. Acquisition targets with closed-loop recycled polyester finishing capabilities and existing EU Green Deal textile certification unlock public procurement channels. Signal to monitor: ECHA expansion of per- and polyfluoroalkyl substance restrictions into additional garment categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Microprismatic Film Supply Partnership | Secures retroreflective substrate access against Taiwanese supplier concentration risk. |
| Biomimetic Retroreflective R&D Investment | Develops moth-eye optic structures for Colorado and Bavaria ultracycling validation. |
| EU Green Deal Textile Certification | Unlocks public procurement channels under recycled polyester mandates. |
| Subscription Platform Launch | Captures UK cycling club replacement demand with RFID visibility verification. |
| Domestic India Manufacturing Scale-Up | Avoids import duty exposure for Bengaluru metro-bike-share commuter apparel. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with reflective sportswear brand managers, textile R&D directors, EN 17353 certification lab technicians, cycling club procurement coordinators, and specialty retail buyers. Secondary validation drew from ECHA REACH restriction updates, EU Green Deal textile target documentation, ANSI/ISEA 107 standard revisions, customs trade data for microprismatic film imports, and SEC filings of publicly traded athletic apparel companies. Bottom-up demand modeling across athlete, outdoor adventurer, fitness enthusiast, and casual user segments triangulated against top-down market sizing from certified garment production volumes.
Across the analysis window, forecasts employed a segmented growth framework isolating product type, material substrate, end-user archetype, and feature bundle dimensions. CAGRs were derived from replacement cycle frequencies correlated with club membership growth rates and regulatory certification expansion timelines. Model inputs included petrochemical resin price elasticity coefficients, REACH reformulation lag estimates, and urban cycling infrastructure investment flows in target metro areas.
Underlying assumptions cover sustained nighttime running collective growth, stable EN 17353-ANSI/ISEA 107 harmonization timelines, and continued Taiwan-South Korea microprismatic supply continuity, with deviation risk concentrated in ECHA chemical restriction acceleration, prismatic film supply disruption, or subscription model adoption shortfalls. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
USA Sports Team and Club Market
Sports & Fitness Technology
Crossfit Apparel Market
Sports & Fitness Technology
Sports Sponsorship Market
Sports & Fitness Technology
Asia-Pacific Fantasy Sports Market
Sports & Fitness Technology
3D Motion Capture Market
Sports & Fitness Technology
United States Sports Promoter Market
Sports & Fitness Technology
India Sports Team and Clubs Market
Sports & Fitness Technology
UK Sports Team and Clubs Market
Sports & Fitness Technology
Germany Sports Teams and Clubs Market
Sports & Fitness Technology
Sports App Market
Sports & Fitness Technology
Virtual Reality Fitness Market
Sports & Fitness Technology
Europe Sports Promoter Market
Sports & Fitness Technology
Smart Sports Market
Sports & Fitness Technology
Sportswear Rental and Rotation Market
Sports & Fitness Technology
UK Sports Promoters Market
Sports & Fitness Technology
UK Sports Management Software Market