
 High-Speed Busbar Transfer Devices Market | 2026-2036
High-Speed Busbar Transfer Devices Market Size, Share, and Industry Trends Forecast 2026-2036
High-Speed Busbar Transfer Devices Market Insights
Direct sales channels for high-speed busbar transfer devices is tilting toward systems integrators and EPC firms serving mission-critical infrastructure. ABB Ltd. leverages its electrification portfolio to anchor premium positions in data center and utility verticals. Siemens AG sustains engineering-intensive relationships with European power utilities through localized manufacturing scale. Schneider Electric SE differentiates via digital control integration across its transfer switch lines.
High-speed busbar transfer devices are electromechanical or solid-state apparatus engineered to execute sub-cycle load transfers between independent busbar sources, typically achieving transfer times below 100 milliseconds to prevent voltage sag-induced equipment trips. These systems employ hybrid contactor-thyristor architectures or microprocessor-based synchronism-check relays to maintain power continuity for semiconductor fabrication lines, hospital operating suites, and hyperscale computing halls. Automatic transfer switches command the largest installed base across commercial buildings and government facilities, though solid-state variants capture expanding share in telecommunication and data center applications where zero-transfer tolerance applies. Digital control technology is deepening penetration in manufacturing plants, while electromechanical platforms retain cost advantage in educational institutions and standard commercial deployments.
FERC Order 2222 and IEEE 1547-2018 in the United States compel grid-interactive transfer equipment to support distributed energy resource integration, elevating technical specifications for utility-facing products. IEC 61439 low-voltage switchgear assemblies standards and EU Green Deal efficiency mandates in Europe enforce thermal performance and materials compliance that filter market access for non-certified suppliers. Stakeholders must weigh hybrid system development against electromechanical cost floors as grid modernization programs and hyperscale facility buildouts redefine procurement criteria across end-use verticals.
Market Dynamics
Sub-100 millisecond transfer tolerance requirements from hyperscale data centers and semiconductor fabs are compressing procurement cycles and forcing hybrid electromechanical-solid-state architectures into standard specifications.
Growth Catalysts
- FERC Order 2222:Distributed energy resource integration mandates in the United States are compelling grid-interactive transfer equipment upgrades across utility-facing product lines.
- Hyperscale computing halls:Zero-transfer tolerance specifications from cloud infrastructure operators are accelerating solid-state variant adoption over electromechanical platforms.
- IEC 61439 thermal compliance:Low-voltage switchgear assembly standards in Europe are filtering market access and consolidating supplier bases around certified manufacturers.
Market Restraints
- Copper and silver price volatility:Input cost swings for conductor materials are compressing margins on electromechanical contactor assemblies.
- Thyristor supply concentration:Power semiconductor sourcing dependencies in East Asian foundries create vulnerability for solid-state transfer device production.
- Legacy synchronization protocols:IEEE 1547-2003 interoperability requirements in existing utility infrastructure limit rapid solid-state retrofit deployment.
Strategic Opportunities
- India data center buildout:PLI scheme incentives for critical power infrastructure are opening procurement channels for certified transfer device suppliers.
- Digital twin integration:Convergence of microprocessor-based relay control with predictive maintenance software is creating premium service attach revenue streams.
- EU Green Deal efficiency mandates:Thermal performance benchmarking requirements are advantaging suppliers with advanced heat dissipation architectures.
Industry Challenges
- Power electronics engineering scarcity:Specialized talent for thyristor gate control and harmonic filtering design commands premium compensation and extends hiring timelines.
- Multi-standard certification complexity:Simultaneous UL 891, IEC 61439, and IEEE 1547-2018 compliance testing extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Speed Busbar Transfer Devices Market |
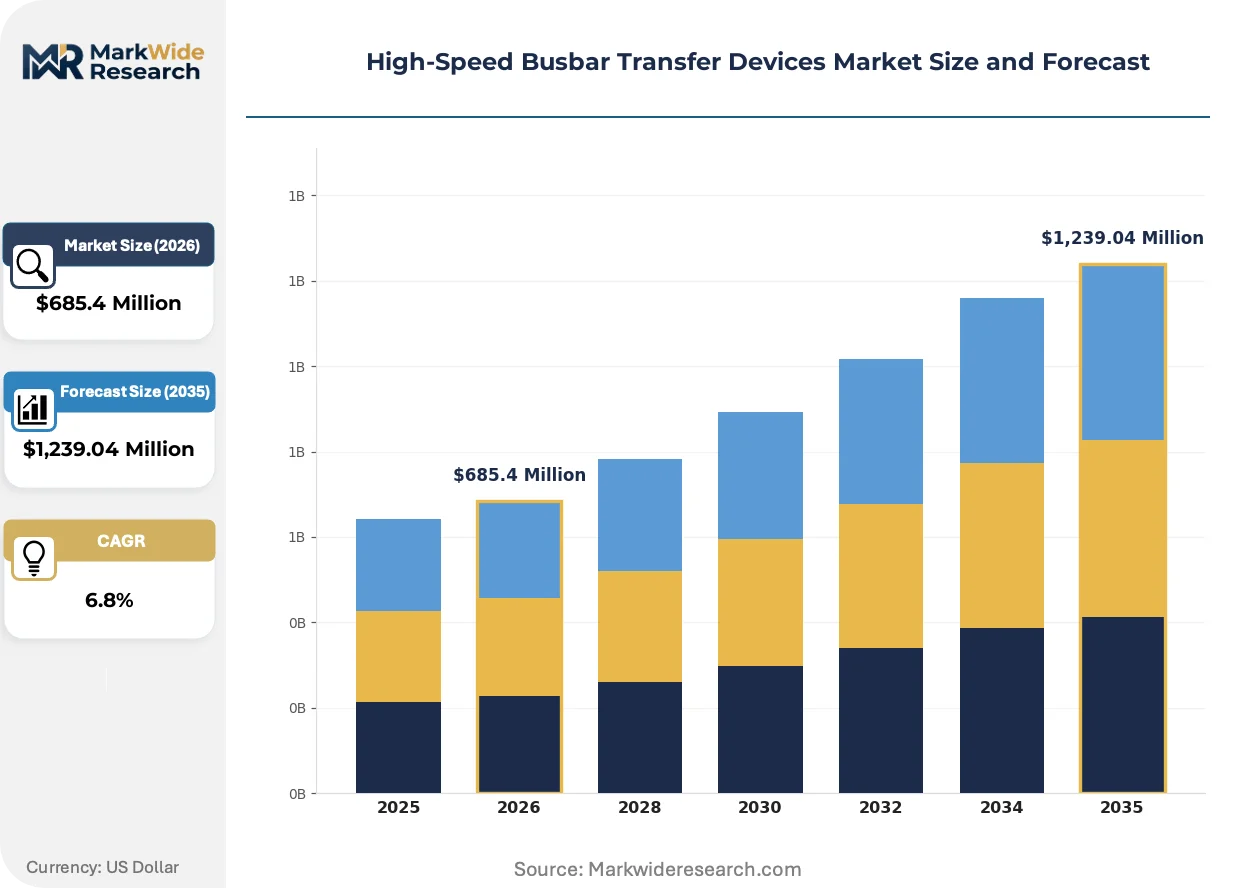
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Transfer Switches, Manual Transfer Switches, Motorized Transfer Switches, Isolator Switches Technology: Electromechanical, Solid-State, Digital Control, Hybrid Systems Application: Data Centers, Telecommunication, Power Utilities, Industrial Automation End User: Commercial Buildings, Government Facilities, Manufacturing Plants, Educational Institutions |
| Companies Covered | ABB Ltd., Siemens AG, Schneider Electric SE, Eaton Corporation plc, Mitsubishi Electric Corporation, Rockwell Automation, Inc., Parker Hannifin Corporation, Festo AG & Co. KG, Hitachi, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Speed Busbar Transfer Devices Market Trends and Innovations
Control intelligence migration from standalone relay logic to embedded microprocessor platforms is redefining competitive differentiation across transfer device categories. Three developments are compressing traditional engineering cycles.
Microprocessor-based synchronism-check relay systems are digitizing fault detection and transfer sequencing functions that previously required discrete electromechanical components. Semiconductor fabrication facilities in Germany and Taiwan are specifying these platforms for sub-50 millisecond transfer requirements. The technology is digitizing vendor competitive positioning around software-configurable protection curves rather than fixed hardware architectures.
EU Green Deal efficiency mandates are enforcing thermal performance disclosure and materials compliance documentation for low-voltage switchgear assemblies. Manufacturers must now submit lifecycle carbon footprint data alongside traditional safety certifications. European power utilities are responding by consolidating procurement around suppliers with verified circular economy credentials and localized manufacturing footprints.
Systems integrators and EPC firms are displacing traditional distributor networks as the primary specification channel for mission-critical infrastructure projects. Direct engineering relationships now govern procurement for data center and healthcare verticals where uptime guarantees carry contractual penalties. This channel compression is most visible in the United States and Germany where hyperscale facility buildouts concentrate buying power among a handful of national contractors.
High-Speed Busbar Transfer Devices Market Segmentation
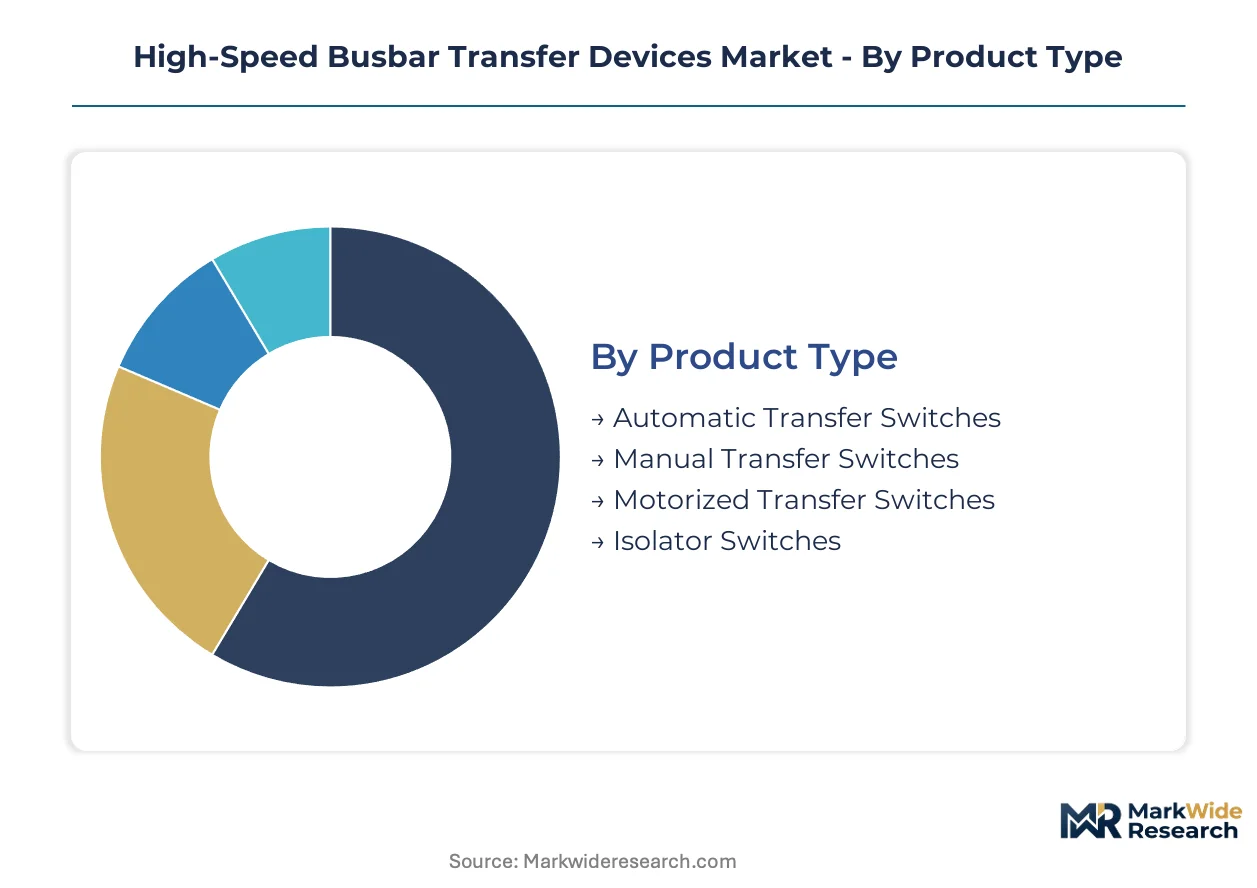
Segmentation in high-speed busbar transfer devices reveals divergent procurement cycles across electromechanical and solid-state platforms. Cycle times compress from 18-24 months for utility-scale electromechanical systems to 6-9 months for data center solid-state deployments. Understanding these velocity differences shapes inventory positioning and R&D resource allocation.
Product Type:
Replacement cycles vary dramatically across product categories, with automatic platforms turning over fastest due to continuous duty wear patterns while isolator switches persist for decades in static configurations.
- Automatic Transfer Switches:Microprocessor-controlled contactor assemblies execute sub-cycle transfers without operator intervention. Hyperscale data centers in the United States specify these for zero-downtime guarantees under SLA penalties. Procurement concentrates among systems integrators serving cloud infrastructure operators with 99.999% uptime contracts.
- Manual Transfer Switches:Hand-operated mechanical interlocks provide basic source selection for non-critical loads. Educational institutions and small commercial buildings in Germany deploy these where operator presence is guaranteed and capital constraints limit automation investment.
- Motorized Transfer Switches:Electrically operated mechanisms enable remote switching through SCADA integration. Power utilities in China specify these for substation automation retrofits requiring centralized control.
- Isolator Switches:Visible-break disconnectors provide maintenance isolation without load-breaking capability. Industrial automation facilities deploy these upstream of transfer devices for lockout-tagout compliance.
Automatic transfer switches anchor the volume base while solid-state variants gain share at the steepest rate.
Technology:
Cost tiers stratify sharply across technology architectures, with electromechanical platforms occupying the economy tier and hybrid systems commanding premium positioning through thyristor-contact redundancy.
- Electromechanical:Contactor-based architectures achieve 50-100 millisecond transfer times through mechanical interlocking. Commercial buildings and government facilities in the United States standardize on these for cost-sensitive applications where brief voltage sags are tolerable.
- Solid-State:Thyristor-based static switches eliminate moving parts and achieve sub-cycle transfers below 16 milliseconds. Semiconductor fabrication lines in Taiwan specify these for voltage sag immunity in photolithography processes.
- Digital Control:Embedded microprocessor platforms replace discrete relay logic with software-configurable protection curves. European power utilities adopt these for IEC 61850 substation communication integration.
- Hybrid Systems:Combined electromechanical-solid-state architectures parallel thyristors with mechanical contacts for redundancy. Data centers in Germany deploy these to balance zero-transfer tolerance with maintenance accessibility.
Electromechanical technology dominates installed base while hybrid systems expand most quickly in mission-critical verticals.
Application:
Customer type concentration varies by application, with data centers consolidating procurement among hyperscale operators while industrial automation fragments across discrete manufacturing sites.
- Data Centers:Hyperscale computing halls demand sub-50 millisecond transfers with zero voltage interruption. Cloud infrastructure operators in the United States and Germany specify solid-state or hybrid architectures under contractual uptime penalties.
- Telecommunication:Central office and cell tower applications prioritize compact footprint and remote monitoring capability. 5G network rollouts in China drive procurement of digital control platforms with SNMP integration.
- Power Utilities:Grid-interactive transfer equipment requires IEEE 1547-2018 compliance for distributed energy resource integration. FERC Order 2222 mandates in the United States compel utility-facing product upgrades.
- Industrial Automation:Manufacturing plants specify transfer devices for continuous process protection. Automotive assembly lines in Germany deploy these to prevent robotic cell resets during source transfers.
Power utilities anchor the volume base while data center applications climb the fastest.
End User:
Margin structures diverge across end-user categories, with manufacturing plants accepting premium pricing for customized engineering while educational institutions drive standardization toward economy tiers.
- Commercial Buildings:Office complexes and retail centers prioritize first-cost minimization for code-compliant backup power. Automatic electromechanical switches dominate these specifications in the United States.
- Government Facilities:Military and civilian installations mandate MIL-STD or equivalent ruggedization standards. Procurement runs through approved vendor lists with extended qualification cycles.
- Manufacturing Plants:Continuous process industries specify transfer devices with synchronized closing to prevent motor reacceleration transients. Semiconductor fabs in Taiwan and Germany drive demand for sub-50 millisecond hybrid systems.
- Educational Institutions:Universities and K-12 facilities deploy basic automatic transfer switches for life safety loads. Budget constraints limit penetration of digital control features.
Commercial buildings anchor the volume base while manufacturing plants drive the steepest technology upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC Order 2222 and India's PLI scheme for critical power infrastructure are redirecting procurement flows toward certified suppliers in the United States and South Asia. Data center buildouts in Germany and semiconductor expansion in Taiwan are tightening transfer tolerance specifications to sub-50 milliseconds.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth are specifying hybrid electromechanical-solid-state architectures under contractual uptime penalties. FERC Order 2222 compels grid-interactive transfer equipment upgrades across utility-facing product lines. The PJM Interconnection territory concentrates procurement among systems integrators serving 99.999% SLA contracts.
Germany
Automotive robotic assembly lines in Bavaria and Baden-Württemberg deploy synchronized closing transfer devices to prevent cell resets during source transfers. EU Green Deal efficiency mandates enforce thermal performance disclosure and lifecycle carbon footprint documentation. Industrial clusters around Stuttgart and Munich are consolidating procurement around suppliers with verified circular economy credentials.
China
5G network rollouts and substation automation retrofits in the Yangtze River Delta and Pearl River Delta are driving procurement of digital control platforms with SCADA integration. The country's national energy regulator mandates distributed energy resource compatibility for grid-interactive equipment. Manufacturing concentration in Shenzhen and Shanghai is compressing procurement cycles for solid-state variants.
India
PLI scheme incentives for critical power infrastructure are opening procurement channels for certified transfer device suppliers serving data center buildouts in Maharashtra and Karnataka. The Central Electricity Authority enforces technical standards for grid connectivity that filter market access. Mumbai and Bangalore clusters are specifying automatic transfer switches for hyperscale facility construction.
Taiwan
Semiconductor fabrication facilities in Hsinchu Science Park and Tainan Science Park specify thyristor-based static switches for voltage sag immunity in photolithography processes. The country's national standards body aligns with IEC 61439 for low-voltage switchgear assembly certification. Wafer foundry expansion is accelerating solid-state variant adoption over electromechanical platforms.
High-Speed Busbar Transfer Devices Market Competitive Landscape
On the supply side, the industry is consolidating around electrification portfolios with certified manufacturing footprints across multiple geographies. European and Japanese industrial conglomerates anchor premium positioning through localized engineering relationships. Three archetypes dominate: diversified electrification groups with transfer device divisions, automation specialists with power distribution portfolios, and regional electrical equipment fabricators with cost-optimized platforms. Competitive moves center on hybrid system development and digital control integration to capture data center procurement.
Among diversified electrification groups, ABB Ltd., Siemens AG, and Schneider Electric SE exemplify the engineering-intensive tier. ABB Ltd. anchors premium positions through its electrification portfolio breadth. Siemens AG occupies a position sustained by European utility relationships and manufacturing scale. Schneider Electric SE represents the digital integration archetype with microprocessor-based control platforms across transfer switch lines.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Schneider Electric SE |
| Eaton Corporation plc |
| Mitsubishi Electric Corporation |
| Rockwell Automation, Inc. |
| Parker Hannifin Corporation |
| Festo AG & Co. KG |
| Hitachi, Ltd. |
| Others |
Pricing and Supply Chain Analysis
East Asian thyristor foundry concentration in Taiwan and South Korea anchors margin capture upstream, while downstream pricing power fragments across hyperscale data center operators, European power utilities, and Indian EPC firms bidding PLI-subsidized infrastructure projects.
Pricing Analysis
Volume-discount tiering structures stratify procurement across three performance levels: hybrid systems with sub-50 millisecond transfer capability command premium positioning from semiconductor fabs and hyperscale computing halls, standard electromechanical platforms serve commercial buildings with 99.9% uptime tolerance, and economy-tier manual switches address educational institutions with capital constraints. Price differentiation hinges on IEC 61439 certification grade and after-sales service bundling with predictive maintenance software. Cost compression in the standard tier intensifies because copper and silver conductor price volatility squeezes contactor assembly margins. Educational institutions exhibit the highest price sensitivity, while semiconductor fabrication facilities accept premium pricing for zero-transfer tolerance guarantees.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for power semiconductor sourcing. Thyristor production concentrates in Taiwan, South Korea, and Japan, while electromechanical contactor fabrication centers on Germany, China, and the United States. Raw material dependencies span copper conductors, silver plating for contact surfaces, and silicon carbide substrates for next-generation static switches. Single-source vulnerability in East Asian foundries creates procurement contingency requirements for solid-state transfer device manufacturers. Distribution runs through systems integrators and EPC firms serving mission-critical infrastructure verticals, displacing traditional distributor networks in data center and healthcare procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hyperscale cloud operators and national EPC contractors, compressing supplier margins and forcing certification investments as table stakes for contract eligibility.
For Market Incumbents: Pre-empt margin erosion in electromechanical platforms by accelerating hybrid system development and securing captive thyristor supply agreements with Taiwanese foundries. Channel control through direct engineering relationships with systems integrators represents the priority defensive lever against emerging automation specialists with power distribution portfolios. For New Entrants and Emerging Players: Pursue white-space opportunities in India's PLI-subsidized data center buildout and Southeast Asian 5G network infrastructure where incumbent certification footprints remain underdeveloped. The most penetrable segment is motorized transfer switches for Chinese substation automation retrofits, accessible through SCADA integration partnerships with local systems integrators. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state and hybrid system manufacturing due to thyristor inventory carrying costs and multi-standard certification testing requirements. Acquisition targets should display verified IEC 61439 and UL 891 compliance with established relationships in hyperscale data center procurement. The signal to watch is FERC Order 2222 implementation pace as a demand inflection indicator for grid-interactive transfer equipment upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Development | Combines thyristor speed with mechanical contact redundancy for data center zero-transfer requirements. |
| Digital Control Integration | Enables IEC 61850 substation communication and predictive maintenance software attach revenue. |
| Multi-Standard Certification Investment | UL 891, IEC 61439, and IEEE 1547-2018 compliance filters market access and consolidates supplier bases. |
| Thyristor Supply Security | Captive agreements with Taiwanese foundries reduce single-source vulnerability for solid-state production. |
| Systems Integrator Channel Control | Direct engineering relationships govern procurement for 99.999% uptime SLA contracts in hyperscale facilities. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with data center infrastructure directors, utility substation engineers, EPC procurement managers, semiconductor fab facilities managers, and power systems integrators; and secondary validation through FERC filings, IEC standards documentation, SEC 10-K electrification segment disclosures, and hyperscaler capex announcements. Bottom-up equipment shipment data triangulated against top-down infrastructure investment forecasts across the projection horizon.
Forecast inputs considered technology architecture, application vertical, transfer speed requirement tier, end-user category, and regional regulatory framework across the modeling period. CAGRs derived from segment-level growth rate reconciliation against macro infrastructure spending trajectories. Industry-specific forecast inputs included data center construction pipeline tracking and semiconductor fab equipment capex cycles.
Sensitivities concentrate around copper and silver commodity price trajectories, thyristor foundry capacity allocation shifts, and FERC Order 2222 implementation timing. Forecasts reflect documented assumptions about hyperscale facility buildout pace and distributed energy resource integration mandates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
DC Contactor Market
Electrical Equipment
Europe Electric Insulator Market
Electrical Equipment
Medium Voltage Transformer Market
Electrical Equipment
Electric Enclosure Market
Electrical Equipment
South America High Voltage Switchgear Market
Electrical Equipment
High Efficiency Low Voltage Aluminum Motors Market
Electrical Equipment
Heat Shrink Terminations Market
Electrical Equipment
Global Busbar Market
Electrical Equipment
Global Digital Panel Meter Market
Electrical Equipment
Circuit Breaker and Fuses Market
Electrical Equipment
Asia-Pacific Vacuum Circuit Breakers Market
Electrical Equipment
Global Capacitor Bank Controllers Market
Electrical Equipment
Motor Protection Devices Market
Electrical Equipment
GCC Ceiling Fan Market
Electrical Equipment
Electrical Isolator Market
Electrical Equipment
Axial Fans Market