
 High Voltage Diodes Market | 2026-2036
High Voltage Diodes Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Diodes Market Analytics
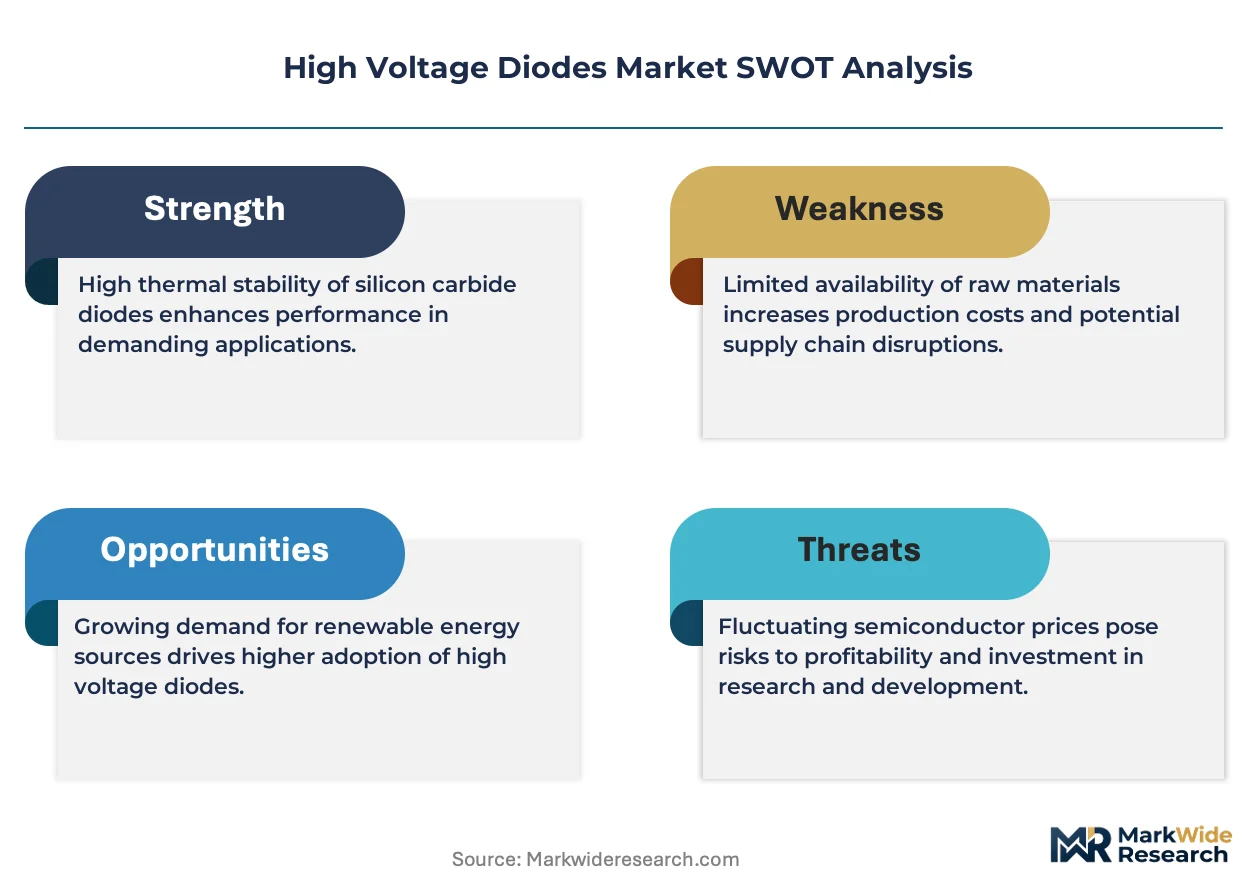
REACH substance restrictions is rebalancing the cost-of-entry calculus for European suppliers of high voltage diodes, forcing reformulation of passivation materials and metallization chemistries. Infineon Technologies AG leverages its captive SiC substrate capacity to control wafer supply for automotive-grade rectifiers. Vishay Intertechnology anchors the industrial equipment segment through thick-film expertise and JEDEC-qualified packaging lines.
High voltage diodes are semiconductor devices engineered to withstand reverse breakdown voltages exceeding one kilovolt, typically fabricated from silicon or wide-bandgap materials with precise doping profiles and edge termination structures to manage electric field distribution; they function as unidirectional current switches in power conversion, protection, and rectification systems across energy infrastructure and transportation. Rectifier diodes command the largest revenue share due to ubiquity in AC-DC power supplies and grid-scale inverters, while SiC technology captures the fastest expansion trajectory as thermal performance requirements intensify in electric vehicle onboard chargers. GaN hybrid configurations occupy a niche but growing margin pool in telecommunications base station power amplifiers where switching frequency demands exceed silicon capabilities.
The EU Green Deal's embodied carbon rules and the EPA's semiconductor fabrication emissions standards are tightening lifecycle accountability for high voltage diode production, compelling foundries to disclose scope-three emissions and water usage. China's MEE enforces discharge limits on gallium and arsenic process effluents that constrain wet-chemical throughput at packaging facilities. Stakeholders must monitor how F-Gas Regulation phase-downs affect dielectric gas selection in high voltage testing equipment used for end-of-line validation.
Market Dynamics
Silicon carbide substrate shortages are forcing power semiconductor manufacturers to reallocate wafer supply toward automotive traction inverters, compressing availability for industrial rectifier applications and reshaping procurement hierarchies across the value chain.
Growth Catalysts
- EU Green Deal embodied carbon rules:Lifecycle disclosure mandates for scope-three emissions are accelerating foundry investments in low-carbon metallization processes for high voltage diode production.
- Electric vehicle onboard chargers:SiC rectifier demand from automotive OEMs is pulling wafer capacity away from legacy industrial applications toward 800-volt traction architectures.
- China's dual carbon goals:Domestic power device clusters in the Yangtze River Delta are receiving preferential grid access and capital subsidies for wide-bandgap semiconductor expansion.
Market Restraints
- Substrate cost volatility:150mm SiC boule supply concentrates among three merchant vendors, exposing diode manufacturers to price spikes during automotive procurement surges.
- REACH substance restrictions:Reformulation of passivation materials containing hexavalent chromium is extending qualification timelines for European-sourced rectifiers by 8-14 months.
- Silicon device substitution limits:Thermal performance ceilings in silicon junction rectifiers block their deployment in EV fast-charging modules above 22kW.
Strategic Opportunities
- Grid-scale energy storage inverters:Utility-scale battery installations in Germany and China require high-reliability blocking diodes for fault protection, opening volume contracts outside automotive allocation queues.
- GaN hybrid integration:Telecom base station power amplifiers are adopting GaN-on-SiC Schottky configurations for frequencies above 3GHz where pure silicon fails.
- F-Gas Regulation phase-down:Dielectric gas restrictions in high voltage testing equipment are creating demand for SF6-free validation chambers that semiconductor foundries must procure.
Industry Challenges
- Edge termination engineering expertise:Bevel and junction termination extension design for 3.3kV+ ratings requires specialized ion implantation physicists concentrated in Japan and Germany.
- JEDEC qualification timelines:Automotive-grade AEC-Q101 testing for wide temperature cycling extends product release cycles by 18-24 months versus industrial equivalents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Diodes Market |
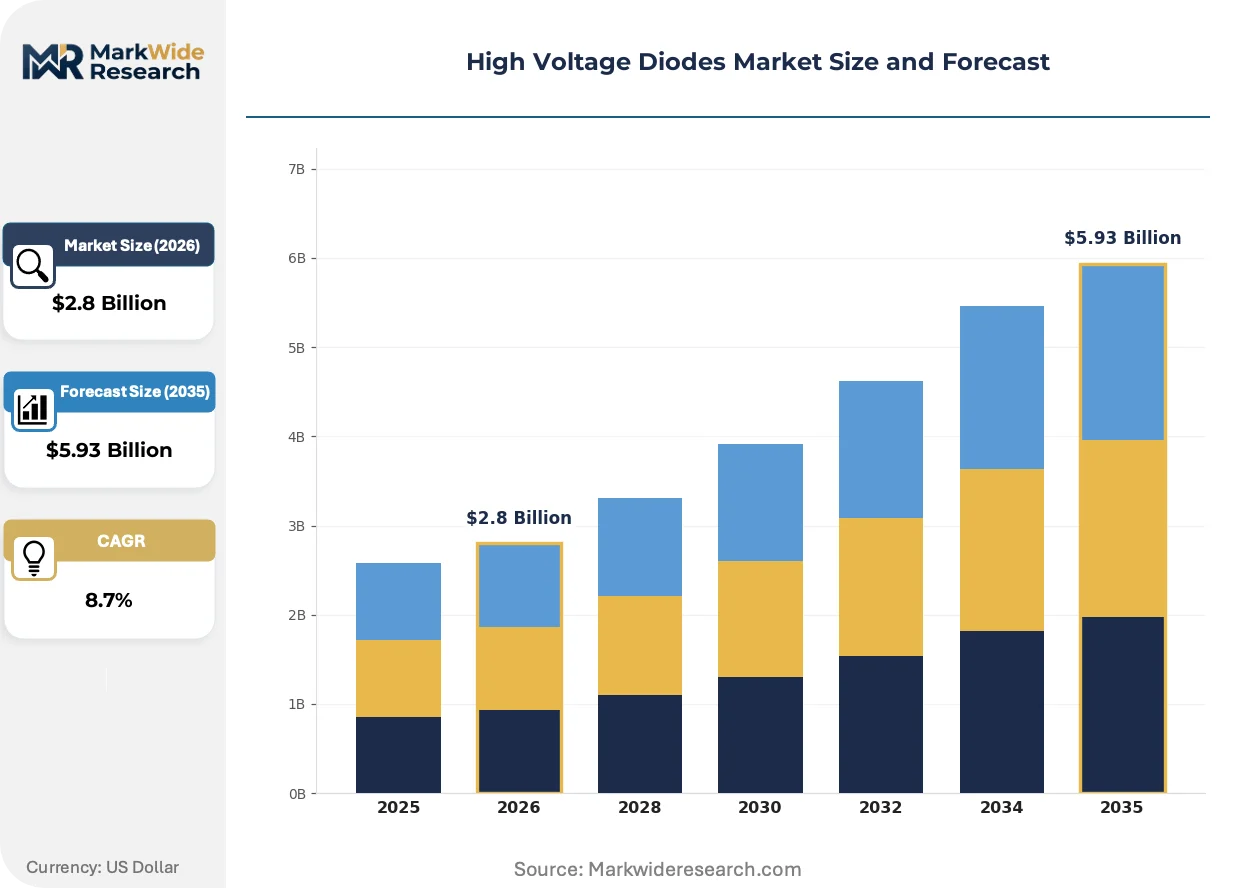
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Schottky, Zener, Avalanche, Rectifier Application: Power Electronics, Telecommunications, Automotive, Industrial Equipment End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Utilities Technology: Silicon, SiC, GaN, Hybrid |
| Companies Covered | Infineon Technologies AG, STMicroelectronics, Vishay Intertechnology, onsemi, Nexperia, ROHM, Littelfuse, Mitsubishi Electric Corporation, Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Diodes Market Evolving Landscape
Material science breakthroughs and regulatory disclosure mandates are simultaneously accelerating wide-bandgap adoption and compressing traditional silicon rectifier margins across power conversion applications.
Silicon carbide Schottky barrier diodes eliminate reverse recovery charge in high-frequency switching applications. EV powertrain engineers at OEMs in Germany, China, and Japan are specifying SiC rectifiers for 800-volt architectures launching between 2025 and 2027. This technology is expanding into industrial motor drives and renewable energy inverters as thermal management constraints intensify.
REACH substance restrictions on hexavalent chromium and cadmium compounds are forcing reformulation of metallization and passivation chemistries. European suppliers must redesign edge termination structures and resubmit qualification data to maintain CE marking eligibility. Automotive-grade diode manufacturers with captive plating facilities face the steepest compliance cost escalations.
Direct procurement contracts between automotive OEMs and SiC substrate growers are bypassing traditional distributor channels for high-reliability rectifiers. Tier-one power module assemblers in China's Yangtze River Delta and Germany's automotive corridor are negotiating multi-year wafer supply agreements that lock out smaller industrial diode purchasers. This channel consolidation is most visible in 650V-1200V ratings where automotive allocation consumes over 70% of merchant substrate output.
High Voltage Diodes Market Segmentation
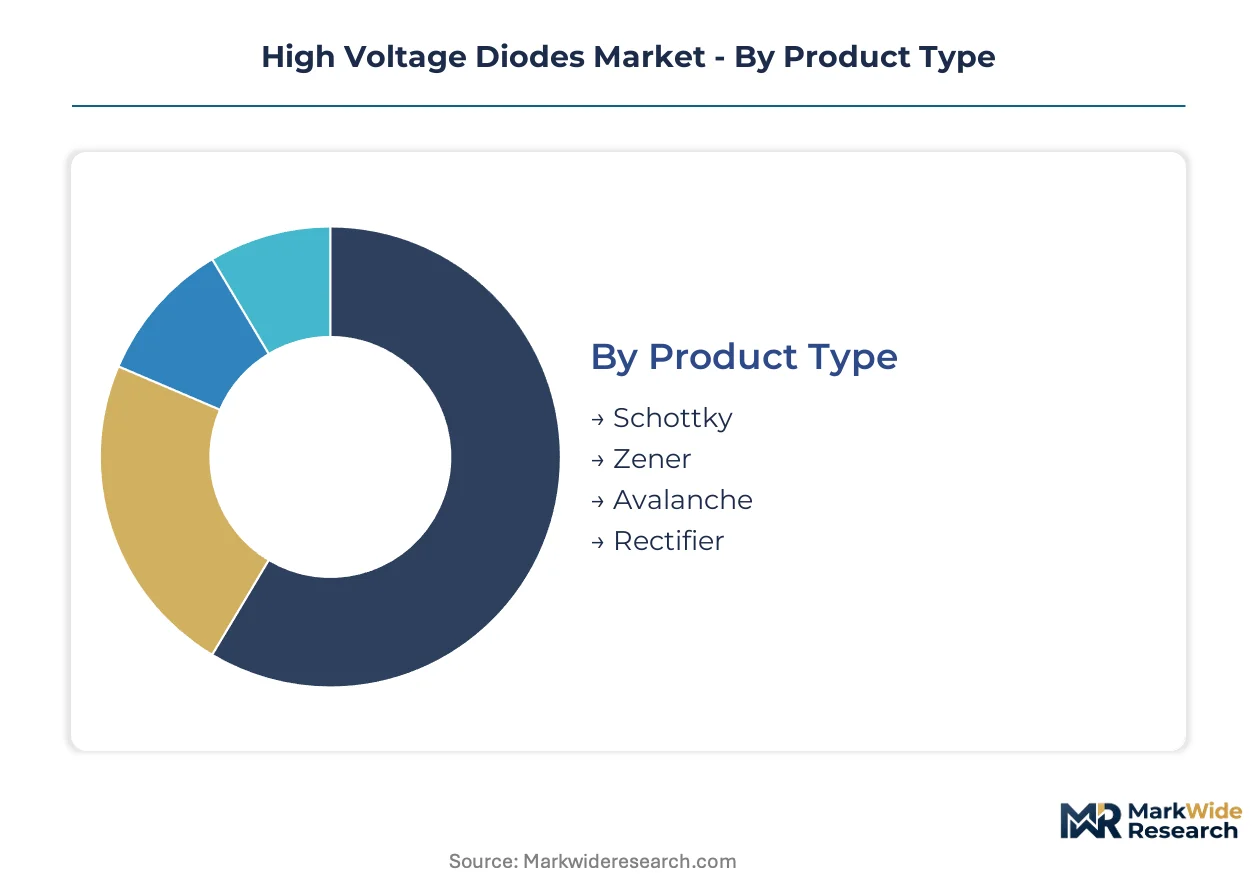
High voltage diode procurement patterns diverge sharply across product architectures, end-use thermal requirements, and supply chain integration levels. Buyers prioritize junction termination reliability in grid applications, switching speed in telecom infrastructure, and temperature cycling endurance in automotive powertrains.
Product Type:
Cost tiers separate commodity rectifiers from precision-engineered protection diodes requiring specialized edge termination physics.
- Rectifier:Silicon and SiC junction designs dominate AC-DC conversion in grid-tied inverters and EV onboard chargers. Demand concentrates in Germany's automotive semiconductor corridor where 800-volt traction architectures pull wafer allocation away from industrial applications.
- Schottky:Metal-semiconductor junctions eliminate reverse recovery losses in high-frequency switch-mode power supplies. China's Yangtze River Delta power device cluster sources these for server rack power distribution where efficiency benchmarks tighten.
- Zener:Precision voltage reference devices protect sensitive control circuitry in industrial motor drives.
- Avalanche:Ruggedized structures absorb transient energy in traction inverter protection circuits.
Rectifier diodes lead volumes today; SiC-based Schottky configurations are gaining share fastest.
Application:
Volume concentration tracks electrification intensity across transportation and energy infrastructure buildouts.
- Automotive:Traction inverters and onboard chargers specify 650V-1200V SiC rectifiers with AEC-Q101 qualification. Procurement surges from OEMs in Germany, China, and Japan compress substrate availability for other segments.
- Power Electronics:Grid-scale inverters and energy storage systems require 3.3kV+ blocking diodes with field-proven reliability. Germany's utility procurement favors European-sourced devices meeting EU Green Deal embodied carbon disclosure rules.
- Industrial Equipment:Motor drives and welding power supplies sustain silicon rectifier demand through thick-film packaging expertise.
- Telecommunications:Base station power amplifiers above 3GHz drive GaN-on-SiC Schottky adoption for switching frequency performance.
Automotive applications lead volumes today; power electronics for grid storage is expanding most quickly.
End User:
Integration depth separates captive semiconductor producers from merchant market purchasers facing allocation constraints.
- OEMs:Automotive and energy equipment manufacturers negotiate direct SiC substrate supply agreements, bypassing distribution channels. China's dual carbon goals accelerate preferential grid access for domestic power device clusters securing these contracts.
- Tier-1 Suppliers:Power module assemblers in Japan's precision electronics manufacturing belt engineer custom diode packages for traction inverter integration.
- Utilities:Grid operators in Germany specify high-reliability blocking diodes for fault protection in battery storage installations.
- Aftermarket Providers:Industrial maintenance distributors source JEDEC-qualified replacements for legacy rectifier fleets.
OEMs lead volumes today; Tier-1 suppliers are climbing the fastest as channel consolidation accelerates.
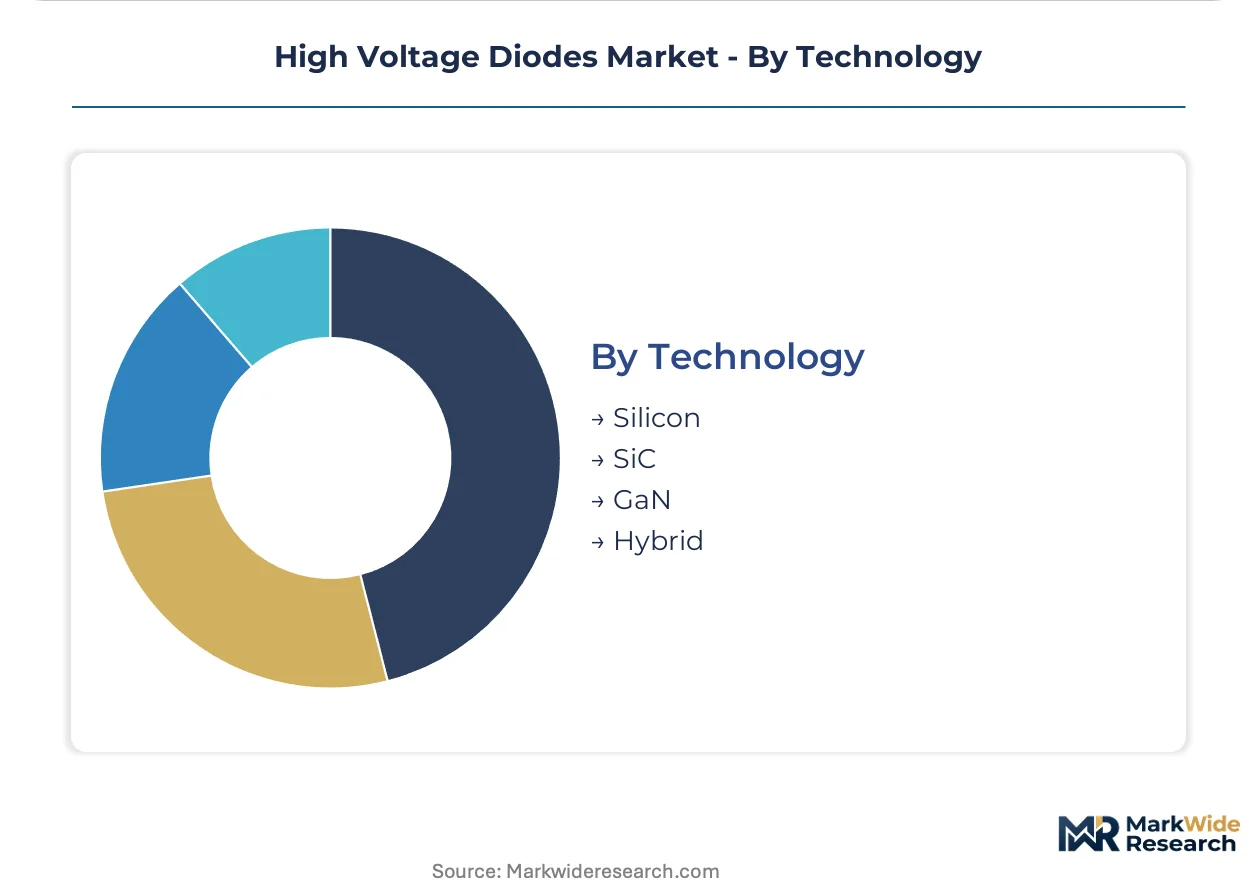
Technology:
Material bandgap determines thermal ceiling and switching frequency tradeoffs across power conversion architectures.
- SiC:Wide-bandgap substrates enable 175°C+ junction temperatures in EV fast-charging modules above 22kW. REACH substance restrictions on hexavalent chromium extend European supplier qualification timelines.
- Silicon:Mature junction rectifiers retain cost advantage in industrial motor drives below 10kW thermal thresholds.
- GaN:Heterostructure devices target telecom base station amplifiers where frequency demands exceed silicon capabilities.
- Hybrid:GaN-on-SiC configurations balance switching speed with thermal conductivity in specialized RF power applications.
Silicon leads volumes today; SiC shows the steepest expansion trajectory as automotive procurement intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized ion implantation physicists concentrate in Germany and Japan, anchoring edge termination engineering for 3.3kV+ ratings. These talent clusters attract automotive OEMs and power module assemblers seeking qualified high voltage diode suppliers.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify 800-volt traction architectures requiring SiC rectifiers with AEC-Q101 qualification. REACH substance restrictions on hexavalent chromium extend supplier qualification timelines by 8-14 months. The automotive semiconductor corridor stretching from Munich to Stuttgart hosts captive plating facilities facing steep compliance cost escalations.
China
Domestic EV manufacturers and grid-scale battery installers pull wafer capacity toward 650V-1200V rectifiers for onboard chargers. The Ministry of Ecology and Environment enforces discharge limits on gallium and arsenic process effluents at packaging facilities. The Yangtze River Delta power device cluster receives preferential grid access and capital subsidies for wide-bandgap semiconductor expansion.
Japan
Precision electronics manufacturers engineer custom diode packages for traction inverter integration. METI industrial policy supports domestic substrate development to reduce import dependence for wide-bandgap materials. The manufacturing belt spanning Tokyo through Nagoya to Osaka concentrates JEDEC-qualified packaging expertise.
United States
EPA semiconductor fabrication emissions standards compel foundries to disclose scope-three emissions and water usage for lifecycle accountability. Industrial equipment OEMs sustain silicon rectifier demand through thick-film packaging expertise. The Southwest and Pacific Northwest host power electronics design centers specifying high-reliability blocking diodes for utility-scale installations.
South Korea
Memory and display semiconductor producers leverage existing cleanroom infrastructure to diversify into power device packaging. The Seoul Capital Area anchors R&D for next-generation edge termination structures. Busan-Ulsan industrial complexes supply metallization chemistries reformulated to meet evolving substance restrictions.
High Voltage Diodes Market Competitive Landscape
The competitive structure tilts toward integrated device manufacturers with captive substrate capacity and JEDEC-qualified packaging lines. Merchant vendors without upstream wafer supply face allocation compression during automotive procurement surges. Three archetypes dominate: European automotive-grade specialists with REACH-compliant metallization, Asian diversified electronics conglomerates with vertical silicon carbide control, and American industrial-focused suppliers with thick-film expertise. Capacity expansion and direct OEM substrate agreements represent the dominant competitive moves reshaping procurement hierarchies.
Among the named participants, Infineon Technologies AG exemplifies the European integrated archetype with captive SiC substrate production. Vishay Intertechnology occupies a position within the industrial-specialist tier, while STMicroelectronics represents diversified electronics conglomerate positioning. These anchors illustrate how geographic origin and corporate structure map to strategic positioning without prescribing specific product portfolios or market shares.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| STMicroelectronics |
| Vishay Intertechnology |
| onsemi |
| Nexperia |
| ROHM |
| Littelfuse |
| Mitsubishi Electric Corporation |
| Toshiba Corporation |
| Others |
Value Network & Pricing Analysis
Automotive OEMs in Germany and China concentrate procurement volume for 650V-1200V SiC rectifiers, forcing a contract-based long-term offtake pricing model that locks out spot-market participants during substrate allocation crunches.
Pricing Analysis
Unbundled wafer supply commands premium positioning against packaged diode deliveries, with three-tier pricing structure across premium, standard, and economy levels separating AEC-Q101 automotive grades from industrial JEDEC equivalents and unqualified merchant devices. Certification tier and volume scale drive price differentiation, with automotive qualification extending supplier lead positions. Cost compression in industrial silicon rectifiers intensifies because substrate reallocation toward EV traction inverters narrows merchant availability. Tier-1 power module assemblers show least price sensitivity; aftermarket maintenance distributors face acute margin pressure.
Supply Chain Analysis
150mm SiC boule supply rests on Japanese, American, and German specialty crystal growers, with epitaxial wafer processing anchored in Taiwan and South Korea. High-purity graphite crucibles, specialty gases for ion implantation, and precision photoresists constitute critical input dependencies. Single-source vulnerability concentrates in merchant substrate vendors exposed to automotive procurement surges. Distribution runs through direct OEM-substrate grower agreements that bypass traditional component distributors for high-reliability ratings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European suppliers face 8-14 month qualification timeline extensions under REACH substance restrictions, while China's Yangtze River Delta cluster receives preferential grid access and capital subsidies, creating a geographic-arbitrage window for cost-sensitive capacity placement.
For Market Incumbents: Acquire captive SiC substrate production capacity to secure wafer allocation outside automotive procurement queues. Infineon Technologies AG's backward integration into SiC boule growth exemplifies defensive positioning against merchant supply compression. Invest in REACH-compliant metallization chemistries to maintain CE marking eligibility as hexavalent chromium restrictions tighten. Channel control through direct OEM agreements locks out distributor-dependent competitors during allocation crunches. For New Entrants and Emerging Players: Industrial equipment distributors represent the most accessible channel partner type for JEDEC-qualified silicon rectifier sourcing. Grid-scale energy storage inverter manufacturers in Germany offer white-space volume contracts outside automotive allocation queues. Target GaN-on-SiC Schottky configurations for telecom base station amplifiers above 3GHz where switching frequency demands exceed incumbent silicon capabilities. Technical service bundling with edge termination engineering support differentiates against commodity merchants. For Investors and Strategic Acquirers: Automotive OEMs are the most active acquirer in this space, pursuing direct substrate supply agreements that reshape procurement hierarchies. Long-term viability hinges on wide-bandgap material control positions with demonstrated AEC-Q101 qualification pathways. Acquisition target archetype: mid-cap European diode specialists with captive plating facilities and pending REACH compliance certifications. Watch SiC substrate utilization rates at merchant vendors as the inflection indicator for industrial allocation availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Production | Captive wafer supply insulates Infineon Technologies AG from automotive allocation crunches. |
| REACH-Compliant Metallization Reformulation | European suppliers redesign passivation chemistries to maintain CE marking eligibility under ECHA restrictions. |
| Direct OEM Substrate Supply Agreements | Tier-1 assemblers in Germany's automotive corridor lock multi-year wafer contracts bypassing distribution channels. |
| GaN-on-SiC Schottky Development | Telecom base station power amplifiers above 3GHz adopt hybrid configurations where silicon junctions fail. |
| SF6-Free High Voltage Testing Chambers | F-Gas Regulation phase-downs compel foundries to procure alternative dielectric gas validation equipment. |
Research Methodology
Direct dialogue with power semiconductor procurement managers, automotive Tier-1 supplier engineers, foundry operations directors, and grid-scale inverter system architects grounded qualitative assessment. Secondary validation drew from SEC 10-K filings, ECHA REACH substance restriction updates, MIIT wide-bandgap semiconductor policy circulars, and customs trade data for SiC substrate movements. Bottom-up segment sizing triangulated against top-down energy infrastructure investment flows.
Market size and growth trajectory outputs calibrated across the analysis window through multi-dimensional segmentation by product architecture, thermal performance tier, end-use electrification intensity, and supply chain integration depth. CAGRs derived from substrate capacity expansion announcements, automotive platform electrification roadmaps, and utility-scale battery installation pipelines. Forecast inputs incorporated REACH compliance timeline delays and China's dual carbon subsidy disbursement rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SiC substrate capacity buildout execution and F-Gas Regulation enforcement timing. Projections reflect assumptions about automotive 800-volt architecture adoption curves and grid storage inverter deployment schedules. Material deviation in merchant substrate utilization rates or REACH substance restriction expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Monocrystalline Half-Chip Module Market
Semiconductor Devices
N-Topcon Solar Cells Market
Semiconductor Devices
Solar Cell Paste Market
Semiconductor Devices
China Semiconductor Diode Market
Semiconductor Devices
Laneth-16 Market
Semiconductor Devices
Voltage Controlled Oscillators Market
Semiconductor Devices
Advanced IC Substrates Market
Semiconductor Devices
Europe Printed Circuit Board (PCB) Market
Semiconductor Devices
Taiwan Discrete Semiconductor Market
Semiconductor Devices
Gan on Silicon Technology Market
Semiconductor Devices
Americas Semiconductor Device Market
Semiconductor Devices
Amorphous-Semiconductor Devices Market
Semiconductor Devices
Pcie Switches Market
Semiconductor Devices
United Arab Emirates (UAE) CEP Market
Semiconductor Devices
Ultra Low Power Microcontroller Market
Semiconductor Devices
Wttx Market