
 Solar Cell Paste Market | 2026-2036
Solar Cell Paste Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Cell Paste Market Outlook
Chinese metallization paste producers are expanding domestic silver paste capacity to serve the country's vertically integrated solar cell manufacturers. DuPont de Nemours leverages its historical intellectual property in glass frit chemistry to sustain premium positioning in n-type TOPCon cell metallization. Heraeus Holding anchors European supply through its German R&D centers, while Samsung SDI competes in the Asia-Pacific region with specialized low-temperature curing formulations for heterojunction architectures.
Solar cell paste comprises conductive formulations—typically silver, aluminum, or copper particles suspended in organic vehicles and glass frit systems—that form ohmic contacts on crystalline silicon wafers through high-temperature firing at 700–850°C. Screen-printed silver paste dominates front-side metallization due to its established line-width control and contact resistivity below 2 mΩ·cm², though inkjet printing is gaining traction for finer finger geometries below 20 micrometers. Aluminum paste retains structural importance in p-type PERC back-surface fields where thick-film coverage exceeds 90% of wafer area, while barrier layer formulations command margin premiums in shingle and tandem cell architectures requiring edge isolation. Photovoltaic module applications absorb the majority of paste volumes, yet building-integrated photovoltaics (BIPV) represents the fastest-growing demand pool as aesthetic and transparency requirements drive specialized paste development.
The US EPA regulates volatile organic compound emissions from paste manufacturing facilities, while China's MIIT enforces GB/T 9535 reliability standards that directly specify metallization adhesion and solderability criteria. REACH compliance in Europe constrains lead and cadmium content in paste formulations, pushing reformulation investments toward lead-free glass systems. Stakeholders must monitor silver price volatility and the pace of copper paste qualification, as these variables will determine capital allocation between incumbent silver-dominant processes and emerging plated-copper metallization routes.
Market Dynamics
The transition from p-type PERC to n-type TOPCon and heterojunction architectures is compressing silver consumption per watt while demanding higher-performance paste formulations with specialized glass chemistry and finer particle distributions.
Growth Catalysts
- Utility-scale deployment:Developers in India and Saudi Arabia are commissioning multi-gigawatt projects requiring high-efficiency cells with advanced metallization. Paste suppliers qualify formulations specifically for these arid-climate installations.
- China's GB/T 9535 reliability standards:Updated adhesion and solderability criteria are redirecting procurement toward certified domestic producers. Jiangsu and Zhejiang manufacturing clusters consume the majority of compliant paste volumes.
- Copper plating qualification:Equipment makers and cell manufacturers are co-developing plated-copper processes that reduce silver dependency. Pilot lines in Germany and South Korea are validating seed-layer pastes for this transition.
Market Restraints
- Silver price volatility:The London Bullion Market Association daily fixing directly impacts paste raw material costs. Formulators cannot fully pass through spikes to contract-bound module makers.
- Chinese supply concentration:Over seventy percent of silver paste manufacturing capacity sits in Jiangsu, Zhejiang, and Guangdong provinces. Geopolitical friction or logistics disruption would constrain global availability.
- Lead-free glass reformulation lag:REACH compliance deadlines in Europe are forcing substitution of traditional lead-oxide glass frit systems. Alternative formulations still exhibit higher contact resistance on certain silicon textures.
Strategic Opportunities
- BIPV aesthetic requirements:Building-integrated photovoltaics in Germany and the Netherlands demand neutral-colored and transparent conductive films. Specialized paste development for frameless glass-glass modules commands margin premiums.
- Shingle cell architectures:Interdigitated back-contact and shingle designs require edge-isolation barrier layers with precise viscosity control. Paste suppliers with screen-printing and inkjet compatibility capture this niche.
- US IRA domestic content credits:The Inflation Reduction Act incentives are stimulating North American cell manufacturing investment. Qualifying paste production within USMCA trade zones satisfies origin requirements for module assembly.
Industry Challenges
- Glass frit chemistry expertise scarcity:Formulation scientists capable of optimizing lead-free systems for n-type contact resistance are concentrated at a handful of R&D centers. Recruitment competition intensifies as Chinese and Korean producers expand technical teams.
- Copper paste oxidation control:Developing stable copper particle dispersions that resist degradation during storage and printing remains technically demanding. Shelf-life specifications lag silver-based alternatives by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Cell Paste Market |
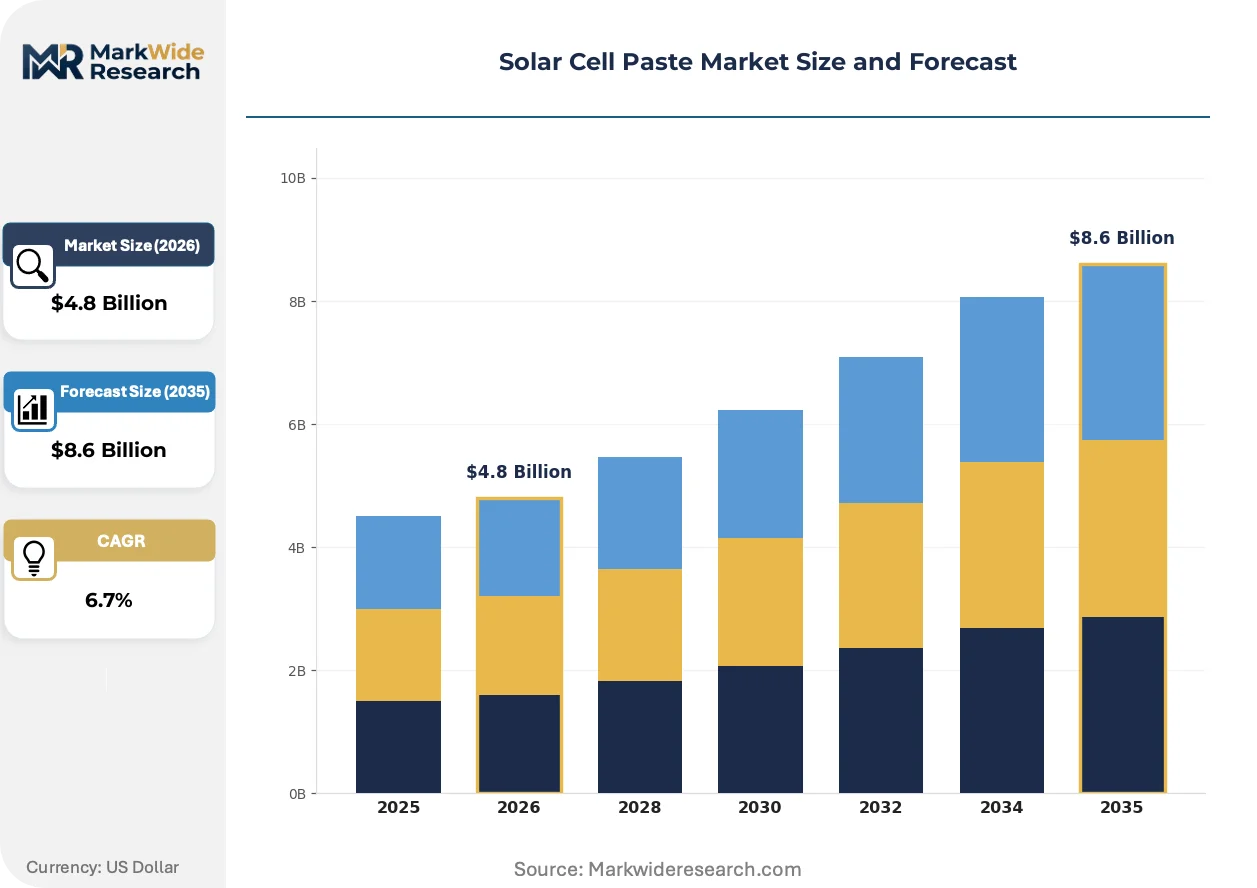
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver Paste, Aluminum Paste, Conductive Adhesives, Barrier Layer Technology: Screen Printing, Inkjet Printing, Laser Scribing, Roll-to-Roll End User: Manufacturers, Research Institutions, Renewable Energy Firms, Distributors Application: Photovoltaic Modules, BIPV, Residential Systems, Utility-Scale Projects |
| Companies Covered | Shanghai Aiko Solar Energy, TDK Corporation, DuPont de Nemours, Samsung SDI, Toyo Aluminium, Heraeus Holding, Sumitomo Metal Mining, Soleras Advanced Materials, Johnson Matthey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Cell Paste Market Strategic Shifts
Metallization technology is fragmenting across multiple competing pathways as cell efficiency roadmaps diverge. Paste suppliers must maintain parallel qualification tracks for screen printing, inkjet deposition, and plating-based architectures.
Inkjet-printed silver paste is decentralizing front-side metallization equipment ownership. Cell makers in Taiwan and Malaysia are adopting non-contact deposition systems that eliminate screen wear and enable sub-20-micrometer finger geometries. This printing modality is decentralizing capital requirements from centralized screen shops to individual production lines.
REACH Annex XVII restrictions on lead compounds are compelling reformulation of glass frit systems across European paste production. Manufacturers are qualifying bismuth-zinc-boron alternatives that maintain adhesion on textured silicon. Heterojunction cell architectures with their lower firing temperatures are most affected, as these formulations require entirely new organic vehicle chemistries.
Long-term supply agreements with silver refiners are displacing spot-market purchasing among tier-one module makers. Korean and Indian cell manufacturers are locking in multi-year offtake contracts to hedge against London Metal Exchange volatility. This contractual shift is most visible in the utility-scale procurement segment where project financing requires input cost predictability across decade-long asset lifetimes.
Solar Cell Paste Market Segmentation
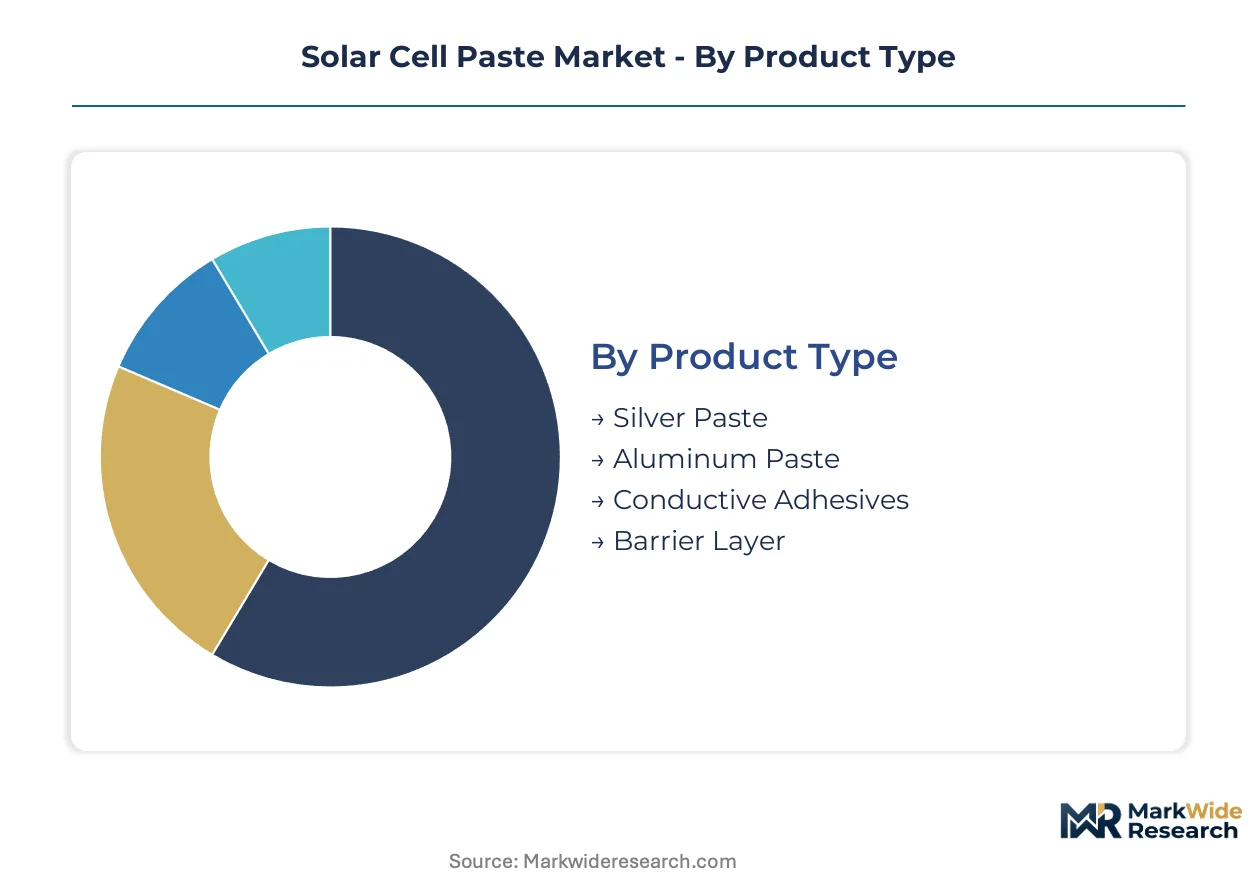
Solar cell paste segmentation reveals how formulation chemistry, deposition physics, and end-use requirements fragment procurement patterns across the value chain. Each dimension carries distinct margin structures and technical qualification barriers that reshape supplier-customer relationships.
Product Type:
Silver paste manufacturing concentrates in Jiangsu and Zhejiang provinces where integrated cell makers enforce stringent glass frit specifications.
- Silver Paste:Suspensions of silver flakes and spherical particles in organic vehicles with lead-free or bismuth-based glass frit systems. Front-side metallization for n-type TOPCon cells demands sub-2 mΩ·cm² contact resistivity. Jiangsu province consumes the majority of high-volume shipments as vertically integrated manufacturers qualify formulations for multi-gigawatt production lines.
- Aluminum Paste:Thick-film formulations containing aluminum powder, glass frit, and organic binders fired at 700–850°C to form p+ back-surface fields. Demand clusters in p-type PERC cell production where coverage exceeds 90% of wafer area. Zhejiang manufacturing bases source standard-grade material through annual contracts with domestic formulators.
- Conductive Adhesives:Isotropic and anisotropic formulations for shingled cell interconnection and temperature-sensitive heterojunction architectures.
- Barrier Layer:Dielectric pastes providing edge isolation and electrical insulation in interdigitated back-contact and tandem cell designs.
Today's leader: Silver Paste. Tomorrow's challenger: Barrier Layer.
Technology:
Deposition modality determines capital intensity, line-width capability, and paste rheology requirements with divergent equipment ownership models.
- Screen Printing:Mesh-based stencil deposition with squeegee-driven paste transfer enabling 20–40 micrometer finger widths. The dominant installed base across crystalline silicon manufacturing. Taiwanese and Malaysian cell makers maintain centralized screen shops with dedicated paste inventory management.
- Inkjet Printing:Non-contact piezoelectric deposition of low-viscosity formulations achieving sub-20-micrometer geometries without mechanical wear. Pilot adoption in Taiwan and Malaysia is decentralizing capital requirements from shared screen facilities to individual production lines.
- Laser Scribing:Selective ablation and metallization patterning for advanced cell architectures requiring localized contact formation.
- Roll-to-Roll:Continuous coating processes for flexible and lightweight photovoltaic applications outside conventional wafer-based manufacturing.
Screen Printing commands current volume. Inkjet Printing is gaining share fastest among new capacity investments.
End User:
Customer type dictates contract structure, technical service intensity, and qualification timeline with sharp differences between commercial production and developmental applications.
- Manufacturers:Tier-one and tier-two cell and module producers purchasing paste through multi-year supply agreements with silver price hedging mechanisms. Korean and Indian producers are locking in long-term offtake contracts to secure input cost predictability for project financing.
- Research Institutions:Universities and national laboratories sourcing small-batch experimental formulations for next-generation cell architecture development.
- Renewable Energy Firms:Project developers and independent power producers influencing paste selection through module procurement specifications for utility-scale installations.
- Distributors:Regional chemical and electronics material wholesalers serving fragmented aftermarket and maintenance requirements.
Manufacturers drive absolute volume. Research Institutions shape formulation roadmaps for next-generation architectures.
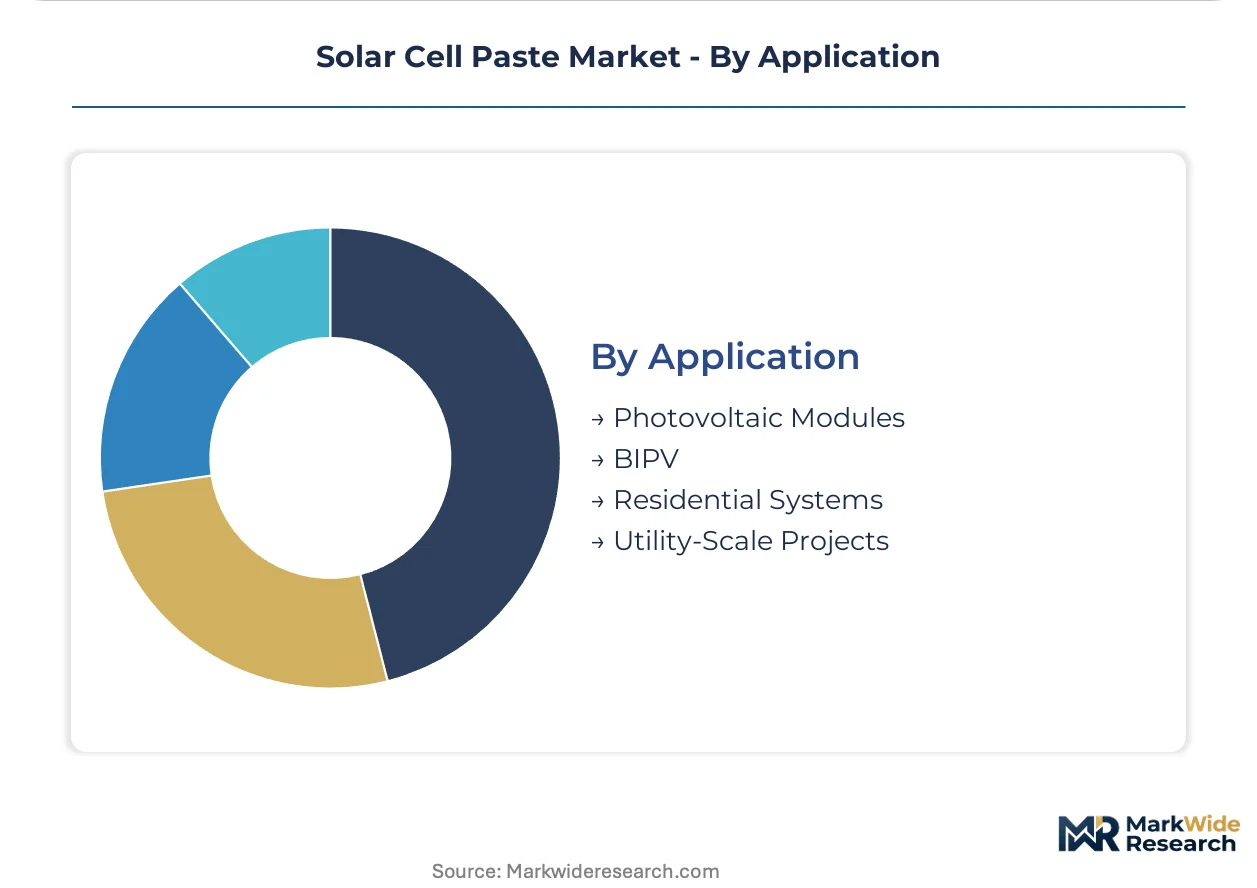
Application:
End-use segment determines reliability standards, aesthetic requirements, and thermal cycling specifications with diverging paste performance thresholds.
- Photovoltaic Modules:Standard framed glass-backsheet and glass-glass configurations absorbing the majority of metallization paste volumes. China's GB/T 9535 reliability standards enforce adhesion and solderability criteria that redirect procurement toward certified domestic suppliers.
- BIPV:Building-integrated photovoltaics requiring neutral-colored, transparent, or patterned conductive films for architectural integration. German and Dutch projects command margin premiums for specialized aesthetic formulations in frameless glass-glass modules.
- Residential Systems:Distributed rooftop installations with moderate efficiency requirements and standard metallization specifications.
- Utility-Scale Projects:Multi-gigawatt ground-mount developments in India and Saudi Arabia requiring high-efficiency cells with climate-qualified paste formulations for arid-environment performance.
Photovoltaic Modules anchor current demand. BIPV offers the steepest expansion trajectory as aesthetic requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting solar cell paste manufacturing toward jurisdictions with streamlined chemical compliance regimes and integrated photovoltaic supply chains. Cost-of-compliance gaps between REACH-regulated Europe and Asia-Pacific production zones are accelerating capacity relocation.
China
MIIT's updated GB/T 9535 reliability standards enforce metallization adhesion and solderability criteria that redirect procurement toward certified domestic producers. The country's dual carbon goals tighten product specifications across the value chain. Jiangsu and Zhejiang provinces concentrate vertically integrated cell and module manufacturing clusters that consume the majority of compliant paste volumes.
Germany
REACH Annex XVII restrictions on lead compounds compel reformulation of traditional glass frit systems toward bismuth-zinc-boron alternatives. ECHA compliance deadlines force substitution investments despite higher contact resistance on certain silicon textures. Heraeus Holding anchors European supply through German R&D centers specializing in lead-free metallization chemistry.
United States
EPA volatile organic compound regulations govern paste manufacturing facility emissions, while IRA domestic content credits stimulate North American cell manufacturing investment. Project developers in Texas and California commission multi-gigawatt utility-scale installations requiring climate-qualified formulations. Qualifying paste production within USMCA trade zones satisfies origin requirements for module assembly.
South Korea
MFDS chemical safety assessments and KOSHA industrial standards regulate manufacturing workplace exposure limits for silver nanoparticle handling. Samsung SDI competes regionally with specialized low-temperature curing formulations for heterojunction architectures. Pilot lines in Gyeonggi and Chungcheong provinces validate seed-layer pastes for copper plating transitions.
India
BIS certification requirements and CEA grid interconnection standards influence module reliability specifications that cascade to metallization paste procurement. PLI scheme incentives attract cell manufacturing investment in Gujarat and Tamil Nadu. Developers in Rajasthan and Karnataka commission multi-gigawatt projects requiring high-efficiency cells with arid-climate qualified paste formulations.
Solar Cell Paste Market Competitive Environment
Chinese producers anchor the volume tier; European specialists hold premium positioning in n-type metallization chemistry. The market exhibits tiered concentration with three to five dominant formulators controlling high-volume silver paste supply while regional specialists capture niche barrier-layer and conductive adhesive segments. Two strategic archetypes predominate: vertically integrated chemical conglomerates with captive glass frit capabilities, and focused metallization houses with dedicated photovoltaic R&D programs. Capacity expansion and lead-free reformulation partnerships represent the dominant competitive moves as suppliers qualify formulations for TOPCon and heterojunction transitions.
Within the premium-tier vector, DuPont de Nemours and Heraeus Holding occupy positions defined by historical intellectual property in glass frit chemistry and European regulatory compliance leadership. Samsung SDI exemplifies the Asia-Pacific specialist archetype with regional formulation capabilities. Shanghai Aiko Solar Energy represents Chinese vertical integration into cell manufacturing with captive paste development.
| Leading Market Players |
|---|
| Shanghai Aiko Solar Energy |
| TDK Corporation |
| DuPont de Nemours |
| Samsung SDI |
| Toyo Aluminium |
| Heraeus Holding |
| Sumitomo Metal Mining |
| Soleras Advanced Materials |
| Johnson Matthey |
| Others |
Value Chain & Pricing Dynamics
The transition from screen-printed silver paste to inkjet-deposited and plated-copper metallization simultaneously compresses per-watt material costs and redistributes pricing power toward formulators with lead-free glass frit expertise. China's MIIT certification requirements and REACH Annex XVII compliance deadlines in Europe are bifurcating procurement into premium-qualified and commodity-grade tiers with divergent margin structures.
Pricing Analysis
Distributor margins for silver paste formulations typically range 8-15% above direct OEM contracts, with volume-tiered discounts locking in multi-gigawatt cell manufacturers at the lowest price points. Pricing stratifies across premium, standard, and economy tiers based on GB/T 9535 certification status and lead-free glass chemistry sophistication. Cost compression in standard-grade aluminum paste is intensifying because Jiangsu and Zhejiang producers are expanding captive capacity. Tier-two module makers exhibit highest price sensitivity, while n-type TOPCon specialists prioritize contact resistivity specifications over unit economics.
Supply Chain Analysis
Reverse-logistics flows for expired paste inventory and screen recycling are minimal, though German and South Korean pilot lines are validating reclamation processes for silver-containing waste streams. Raw material sourcing draws from silver refiners in China, South Korea, and Germany, with organic vehicle chemistries resting on petrochemical feedstocks from Singapore and the Netherlands. Single-source vulnerability concentrates in high-purity silver flake supply from Jiangsu-based processors. Distribution runs through regional chemical distributors serving cell manufacturing clusters in Zhejiang, Gujarat, and Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where the cost differential between REACH-compliant European production and MIIT-certified Chinese supply exceeds 20% on equivalent specifications. Formulators can exploit this spread by qualifying dual-source production across regulatory jurisdictions.
For Market Incumbents: Anticipate copper plating qualification timelines by securing seed-layer paste partnerships with equipment makers in Germany and South Korea. Defensive consolidation should emphasize backward integration into glass frit production to protect margin structures against silver price volatility. Incumbents must also monitor emerging Chinese producers expanding TOPCon-specific formulation capacity as a direct competitive threat. For New Entrants and Emerging Players: The US IRA domestic content credits open a window for USMCA-zone paste production serving Texas and California module assembly. New entrants should prioritize barrier-layer formulations for shingle cell architectures in the Netherlands and Germany, where aesthetic BIPV requirements outpace qualified supply. A direct technical sales model to tier-two cell makers in India bypasses established distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap formulators with captive glass frit capabilities but limited n-type qualification track records. Long-term viability hinges on copper paste shelf-life breakthroughs and lead-free reformulation completion before ECHA enforcement hardens. The signal to watch is silver offtake contract renegotiation frequency, which indicates buyer confidence in plated-copper transition timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Lead-Free Glass Frit Reformulation | REACH Annex XVII compliance in Germany and the Netherlands mandates substitution investments despite higher contact resistance trade-offs. |
| Copper Plating Partnership | Equipment co-development with South Korean and German pilot lines validates seed-layer pastes for silver-reduction roadmaps. |
| USMCA Production Qualification | IRA domestic content credits stimulate paste manufacturing investment in Texas to serve module assembly origin requirements. |
| BIPV Specialized Formulation Development | German and Dutch architectural projects command margin premiums for neutral-colored conductive films in frameless glass-glass modules. |
| Long-Term Silver Offtake Contracting | Korean and Indian cell manufacturers hedge London Bullion Market Association volatility through multi-year procurement agreements. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cell manufacturing procurement directors, glass frit R&D leads, module reliability engineers, and metallization equipment specialists with secondary validation. Trade data from Chinese customs authorities, MIIT certification registries, ECHA substance restriction notifications, and SEC filings from publicly traded chemical conglomerates anchored supply-side estimates. Bottom-up paste consumption models triangulated against top-down module production forecasts across the analysis window.
Historical reference periods spanning pre-PERC, PERC-dominant, and n-type transition phases anchored the forecast framework across the projection horizon. The analytical model segmented by paste chemistry, deposition technology, cell architecture, and end-use application with regional regulatory clusters. CAGRs derived from logistic diffusion curves for technology transitions, with silver price scenarios and copper plating adoption curves as key sensitivity inputs.
Revisions become necessary when copper paste oxidation stability breakthroughs, sudden silver price spikes, or geopolitical logistics disruptions in Jiangsu and Zhejiang materialize. Practitioners should monitor ECHA enforcement timelines and Chinese dual carbon policy implementation for early signals of regulatory-driven procurement shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Rad-Hard Mosfets Market
Semiconductor Devices
Monocrystalline Half-Chip Module Market
Semiconductor Devices
Silicon-Based Anode Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Leap Engine Market
Semiconductor Devices
Global Switched Capacitor Filter Market
Semiconductor Devices
Ferroelectric FET Market
Semiconductor Devices
Global Layer Pads Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
Global ASIC Bitcoin Mining Hardware Market
Semiconductor Devices
AIN DBC Ceramic Substrate Market
Semiconductor Devices
5G Automotive Grade Product Market
Semiconductor Devices
Gan Transistor Market
Semiconductor Devices
ATX Motherboards Market
Semiconductor Devices
Smart Gate Driver Market
Semiconductor Devices
India MLCC Market