
 Sudan Power EPC Market | 2026-2036
Sudan Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Sudan Power EPC Market Analytics
Sudan's renewable energy procurement guidelines is consolidating project pipelines around engineering-procurement-construction contracts that bundle solar, storage, and transmission. Sinohydro Corporation leverages its dam-building heritage to dominate hydroelectric rehabilitation tenders along the Blue Nile. Larsen & Toubro anchors its position through modular solar EPC execution for industrial zone developers. PowerChina competes on turnkey pricing for transmission infrastructure tied to generation assets.
Sudan Power EPC denotes the full-scope contracting discipline covering design, equipment procurement, civil works construction, and commissioning of electricity generation and delivery infrastructure, typically executed under lump-sum turnkey arrangements with performance guarantees on output and schedule. The primary purpose centers on reducing execution risk for capital-constrained utilities and independent power producers through single-point accountability. Solar EPC services command expanding margin pools as distributed photovoltaic installations outpace centralized thermal additions in the project pipeline. Hydroelectric technology sustains its structural lead in total contracted value given the scale of Nile basin rehabilitation programs. Government end-user contracts concentrate procurement attention due to sovereign-backed payment security and multi-year implementation horizons.
Sudan's national electricity regulator and the country's central planning authority shape contractor qualification requirements and local content mandates for foreign EPC firms. The country's environmental impact assessment procedures and grid code standards determine technology selection and interconnection timelines for project sponsors. Stakeholders must monitor how foreign currency access protocols and sovereign payment mechanisms evolve to decide whether to advance engineering commitments or stage construction mobilization.
Market Dynamics
Solar-hybrid configurations are displacing thermal-only procurement along the Nile River basin, forcing EPC contractors to restructure engineering teams around photovoltaic integration and battery storage co-design.
Growth Catalysts
- Feed-in Tariff Framework:Sudan's national renewable energy feed-in mechanism guarantees long-term offtake pricing for solar-hybrid developers. Industrial mining corridors are accelerating grid-connected captive capacity additions under this structure.
- Hydroelectric Rehabilitation:Dam infrastructure along the Blue Nile requires comprehensive EPC overhaul. Aging turbine and civil works assets create immediate procurement demand for turnkey rehabilitation contracts.
- Manufacturing Zone Expansion:New industrial clusters in Khartoum State and River Nile State require dedicated substations and medium-voltage distribution. Zone developers prefer single-point EPC accountability for speed-to-operations.
Market Restraints
- Foreign Currency Access:Sudan's central bank rationing of hard currency delays equipment import timelines. Chinese turbine manufacturers and European inverter suppliers face payment settlement friction.
- Transmission Bottlenecks:The national grid's 220kV backbone suffers from conductor thermal limits and substation transformer aging. Generation assets cannot achieve commercial operation without parallel transmission EPC.
- Local Content Mandates:Contractor qualification requirements impose escalating Sudanese labor and material sourcing thresholds. Foreign EPC firms struggle to identify certified local civil works subcontractors.
Strategic Opportunities
- Darfur Solar Mini-Grids:Underpenetrated western states lack grid extension feasibility. Solar-diesel hybrid mini-grids with village-scale distribution represent untapped EPC demand for humanitarian-energy convergence.
- Red Sea Port Electrification:Port Sudan container terminal expansion requires shore power and cold chain infrastructure. Maritime logistics operators seek EPC partners for integrated power and cargo handling systems.
- Agricultural Pumping Modernization:Gezira Scheme irrigation districts are converting diesel pumping to solar-powered boreholes. EPC contractors can bundle PV generation with variable-frequency drive motor retrofits.
Industry Challenges
- Commissioning Engineer Scarcity:Sudan produces insufficient electrical engineers with hybrid plant startup experience. EPC firms must import commissioning specialists from Egypt and the Gulf, inflating mobilization costs.
- Grid Code Compliance Delays:The national electricity regulator's interconnection standards for inverter-based generation lack technical clarity. Project sponsors face repeated design review cycles before energization approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sudan Power EPC Market |
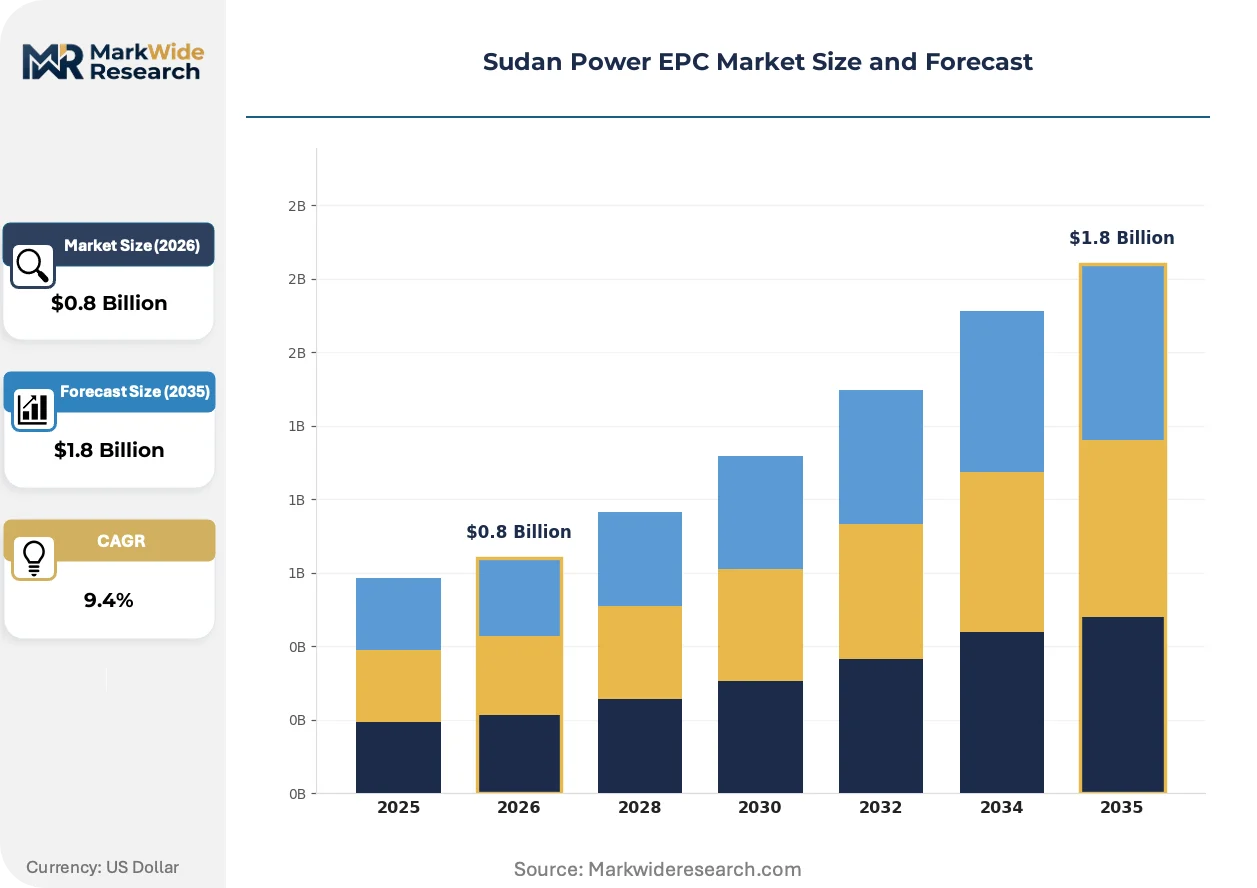
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.8 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Procurement, Construction, Commissioning Technology: Solar, Wind, Hydroelectric, Biomass End User: Residential, Commercial, Industrial, Government Project Size: Small Scale, Medium Scale, Large Scale, Utility Scale |
| Companies Covered | Dal Group, Sinohydro Corporation, Sudanese Thermal Power Generating Company, Larsen & Toubro, PowerChina, Siemens AG, Bharat Heavy Electricals Limited (BHEL), General Electric, Ram Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sudan Power EPC Market Evolving Landscape
Battery energy storage systems are becoming mandatory design elements rather than optional add-ons, compressing EPC contract scopes around DC-coupled architectures that unify solar, storage, and power conversion hardware under single procurement packages.
Containerized lithium-ion battery systems are integrating directly into solar park substation designs, eliminating separate civil works for battery buildings. Industrial offtakers in the mining sector are specifying 4-hour duration storage as standard in tender documents. This integration is compressing balance-of-plant costs and accelerating construction schedules by enabling factory-tested skid delivery.
Sudan's environmental impact assessment procedures now mandate cumulative impact studies for sequential dam rehabilitation along shared river reaches. The country's central planning authority requires climate resilience documentation for all new transmission corridor routing. Hydropower rehabilitation EPC contracts are absorbing 15-20% additional engineering scope for sediment management and fish passage retrofitting.
Engineering-procurement-construction contracts are consolidating previously fragmented procurement stages into single competitive tenders. State utilities are abandoning split-package contracting that separated civil works from electromechanical supply. Sudan's Ministry of Energy is piloting integrated tenders for generation, transmission, and distribution in the Kassala region, compressing vendor management overhead for capital-constrained offtakers.
Sudan Power EPC Market Segmentation
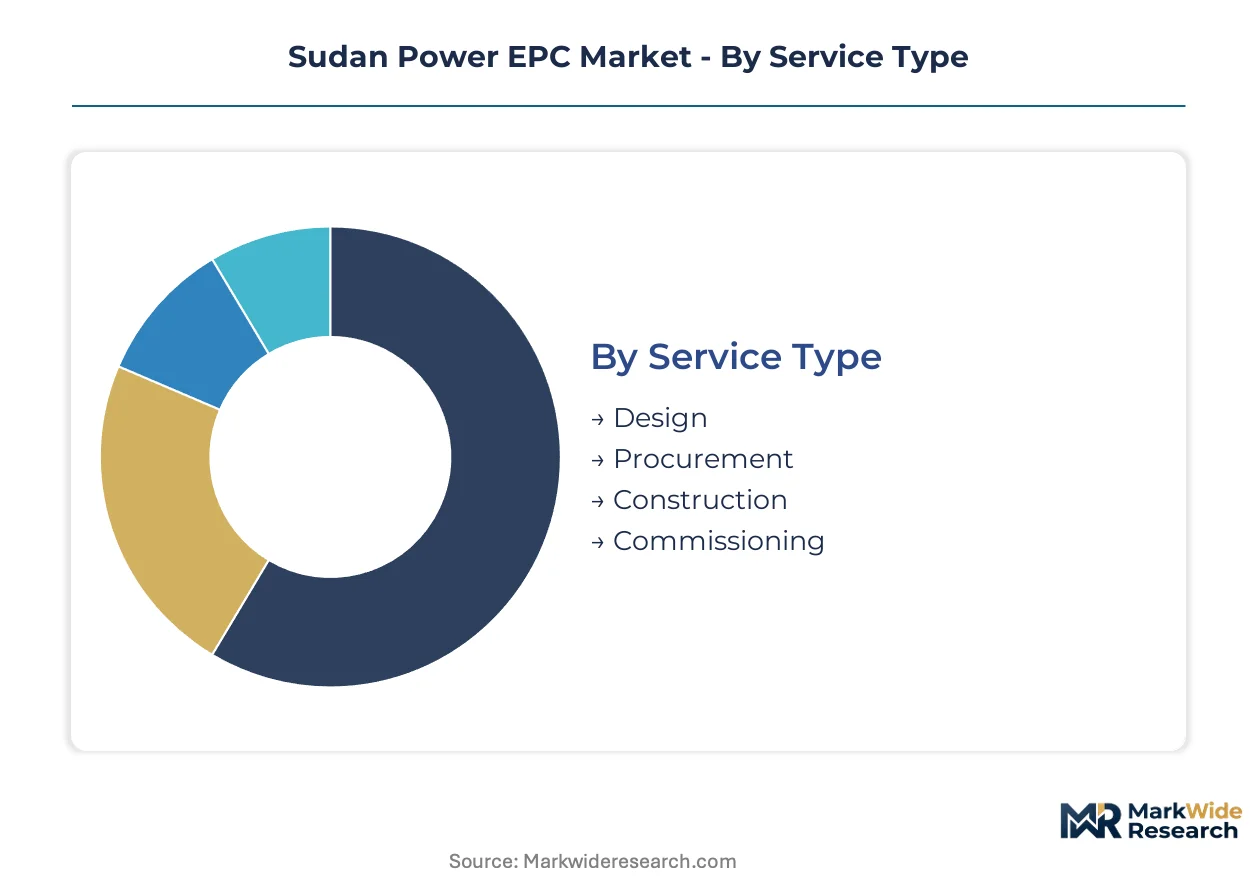
Sudan Power EPC contractors structure bidding strategies around service bundling depth and technology specialization. Segment boundaries determine which firms qualify for sovereign-backed tenders versus private industrial offtake.
Service Type:
Capital intensity peaks where engineering liability and equipment procurement overlap under single-point accountability.
- Design:Front-end engineering packages for solar-hybrid and hydroelectric rehabilitation define contractor qualification tiers. River Nile State utilities demand dam-specific civil engineering credentials that exclude generalist firms.
- Procurement:Equipment sourcing concentrates on Chinese turbine manufacturers and European inverter suppliers facing Sudan's foreign currency rationing protocols. Procurement-only contracts attract trading houses lacking construction capability.
- Construction:Civil works execution absorbs the largest labor mobilization and local content compliance burden. Khartoum State manufacturing zones drive demand for substation foundation and switchyard construction.
- Commissioning:Plant startup and grid synchronization services command premium pricing due to engineer scarcity. Hybrid solar-storage facilities require inverter commissioning specialists imported from Egypt and the Gulf.
Most installed capacity flows through Construction. Expansion is steepest in Commissioning.
Technology:
Application-specific engineering requirements separate utility-scale tenders from distributed generation opportunities.
- Solar:Photovoltaic EPC dominates new capacity additions with DC-coupled architectures bundling generation and battery storage. Industrial mining corridors in Red Sea State specify 4-hour duration storage as standard procurement.
- Wind:Onshore wind development remains nascent due to measurement campaign gaps and grid interconnection uncertainty. Darfur plateau wind resource assessments are pending feasibility completion.
- Hydroelectric:Dam rehabilitation along the Blue Nile sustains the highest contract values through turbine replacement and sediment management. Sinohydro Corporation leverages legacy relationships for turnkey overhaul tenders.
- Biomass:Agricultural residue-to-energy projects cluster around Gezira Scheme irrigation districts with established feedstock logistics. Bagasse cogeneration attracts sugar estate captive power investment.
Procurement volume concentrates in Hydroelectric. Solar is gaining share fastest.
End User:
Payment security and offtake duration determine EPC contract pricing and performance guarantee structures.
- Residential:Distributed rooftop solar installations rely on micro-finance arrangements and donor-funded rural electrification programs. Mini-grid developers in western Sudan target village-scale demand aggregation.
- Commercial:Office and retail load centers in Khartoum prioritize diesel displacement through behind-the-meter solar. Bankability constraints limit project scale to equipment supplier financing.
- Industrial:Mining and manufacturing offtakers command the largest grid-connected captive capacity additions. Sovereign mining concessions in Red Sea State offer hard-currency revenue streams that de-risk EPC investment.
- Government:State utility contracts provide sovereign-backed payment security across multi-year implementation horizons. The Ministry of Energy pilots integrated generation-transmission-distribution tenders in Kassala region.
Contract value aggregates in Government. Industrial is expanding most quickly.
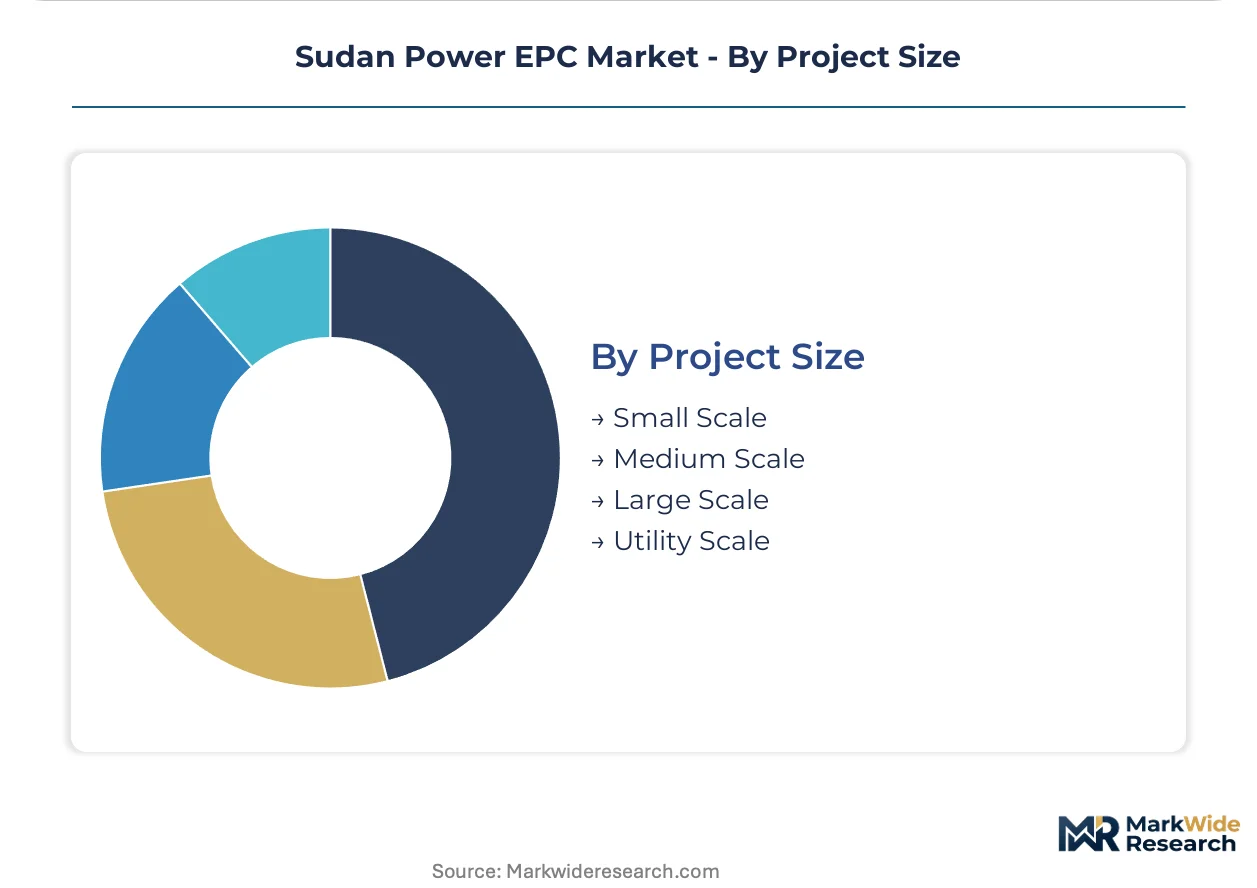
Project Size:
Economies of scale and vendor qualification thresholds fragment the contractor landscape across capacity bands.
- Small Scale:Sub-5MW installations serve isolated commercial loads and rural mini-grids. Containerized solar-diesel hybrid systems enable rapid deployment without transmission interconnection.
- Medium Scale:5-50MW projects target industrial zone embedded generation and distribution utility feed-in supply. Engineering-procurement-construction contracts consolidate previously fragmented procurement stages.
- Large Scale:50-200MW developments require parallel transmission EPC to resolve grid backbone constraints. Blue Nile hydroelectric rehabilitation falls within this band.
- Utility Scale:Above-200MW solar parks and dam complexes demand multi-year construction timelines and political risk insurance. Only Chinese state-owned contractors currently qualify for this tier.
Execution risk concentrates in Utility Scale. Medium Scale offers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Khartoum and Port Sudan anchor Sudan's EPC execution capacity, with Chinese expatriate technicians supplementing local civil works crews along the Nile corridor.
Khartoum State
Industrial zone developers in Khartoum North and Jabal Awlia are procuring embedded generation substations under single-point EPC contracts. Sudan's Ministry of Energy mandates local content thresholds of 30 percent Sudanese labor for qualifying tenders. Manufacturing clusters around the Giad Industrial Complex are driving captive solar-hybrid capacity additions to displace diesel baseload.
River Nile State
Atbara cement works and sugar processing estates are expanding grid-connected captive power under the national feed-in framework. The country's environmental impact assessment procedures require cumulative hydrological studies for sequential dam projects. Dam rehabilitation contracts at Sennar and Roseires concentrate procurement attention along the Blue Nile basin.
Red Sea State
Port Sudan container terminal expansion requires integrated shore power and cold chain electrification. Maritime logistics operators seek EPC partners bundling cargo handling systems with dedicated substations. Mining concessions in the Haya gold belt offer hard-currency revenue streams that de-risk contractor investment in remote transmission infrastructure.
Darfur Region
Humanitarian-energy convergence programs are deploying solar-diesel hybrid mini-grids across underpenetrated western states. The national electricity regulator exempts village-scale systems from grid code compliance to accelerate rural energization. El Fasher and Nyala serve as logistics hubs for containerized PV-diesel systems serving displaced population centers.
Sudan Power EPC Market Competitive Landscape
Capital-heavy dam builders compete with modular solar specialists for procurement share along divergent technology vectors. Chinese state-owned contractors dominate hydroelectric rehabilitation through legacy financing relationships and equipment supply integration. Three archetypes define competitive positioning: turnkey dam rehabilitators, distributed solar integrators, and transmission infrastructure bundlers. Consolidation pressure intensifies as utilities abandon split-package contracting for consolidated generation-transmission tenders.
Among Chinese state-owned enterprises, Sinohydro Corporation and PowerChina exemplify the capital-intensive dam rehabilitation archetype, leveraging equipment import financing to secure multi-year implementation contracts. Larsen & Toubro represents the modular execution tier, anchoring industrial zone solar deployments through standardized EPC packages. These three firms occupy distinct competitive positions without direct overlap in tender qualification tiers.
| Leading Market Players |
|---|
| Dal Group |
| Sinohydro Corporation |
| Sudanese Thermal Power Generating Company |
| Larsen & Toubro |
| PowerChina |
| Siemens AG |
| Bharat Heavy Electricals Limited (BHEL) |
| General Electric |
| Ram Energy |
| Others |
Value Network & Pricing Analysis
DC-coupled solar-storage architectures are compressing balance-of-plant costs while concentrating procurement leverage among Chinese turbine manufacturers and European inverter suppliers who control critical power conversion hardware. This technology transition simultaneously reduces civil works expenditure and amplifies foreign currency exposure for Sudanese offtakers locked into hard-currency equipment contracts.
Pricing Analysis
Turnkey lump-sum contracting with performance guarantees dominates Sudan Power EPC pricing, separating sovereign-backed utility tenders from private industrial offtake on payment security terms. Price differentiation hinges on contractor qualification tier and local content compliance burden rather than technology specification alone. Cost compression in solar-hybrid segments is intensifying because Chinese state-owned competitors are absorbing currency risk to secure multi-year rehabilitation contracts. Industrial mining offtakers in Red Sea State demonstrate lowest price sensitivity due to hard-currency revenue streams, while rural mini-grid developers face acute budget constraints under donor-funded procurement ceilings.
Supply Chain Analysis
Freight costs from Chinese manufacturing hubs to Port Sudan absorb 8-12% of total equipment landed value, with Red Sea shipping lane congestion amplifying delivery uncertainty for turbine and generator sets. Equipment sourcing concentrates in China for hydroelectric machinery, Germany and Austria for grid automation systems, and the UAE for logistics consolidation and spare parts staging. Raw material dependencies span high-grade steel castings for turbine runners, lithium iron phosphate cells for storage integration, and copper conductor for 220kV transmission builds. Single-source vulnerability runs through Sinohydro Corporation's dam equipment supply chain where proprietary turbine designs lock in decades-long parts dependency. Distribution runs through Port Sudan container terminals with inland haulage via Nile River barge networks to Khartoum and Blue Nile construction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
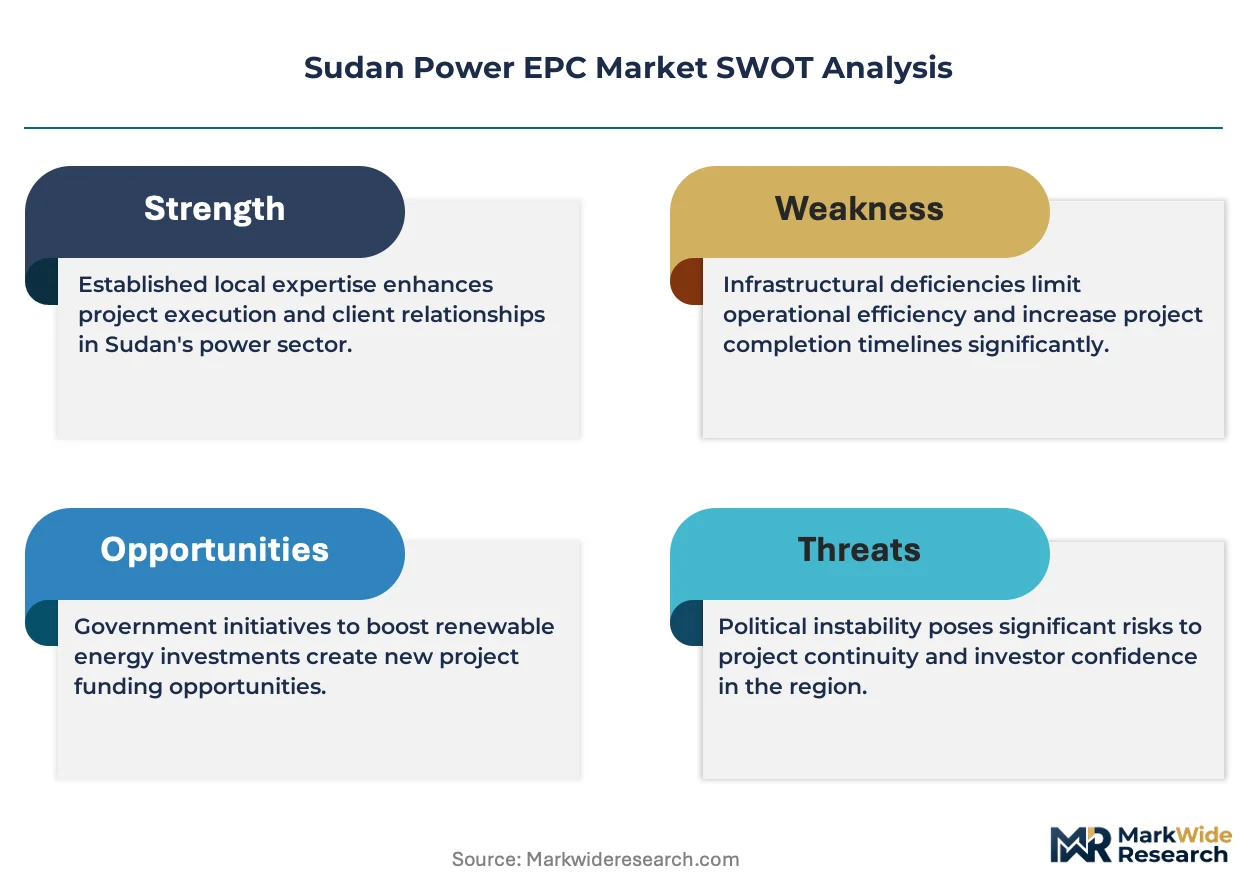
Sudan's national renewable energy feed-in tariff framework operates as a regulatory compounder, mandating long-term offtake pricing that transforms project finance structures and EPC contractor risk allocation.
For Market Incumbents: Acquire commissioning engineering capabilities through specialist recruitment from Egypt and Gulf markets to address hybrid plant startup scarcity. Consolidate position in Blue Nile hydroelectric rehabilitation by securing sediment management engineering credentials before environmental impact assessment scope expansions harden qualification barriers. Solar-hybrid technology displacement from industrial offtakers threatens thermal-only contractors who lack photovoltaic integration expertise.
For New Entrants and Emerging Players: Capture Darfur solar-diesel hybrid mini-grid deployment through humanitarian-energy convergence programs exempt from grid code compliance requirements. Target agricultural pumping modernization in Gezira Scheme irrigation districts where solar-powered borehole conversions bundle PV generation with motor retrofit EPC scope. Partner with Sudanese civil works subcontractors holding certified labor credentials to satisfy local content mandates without direct workforce mobilization.
For Investors and Strategic Acquirers: Valuations sit cheapest among medium-scale solar EPC specialists with modular execution capabilities but limited transmission infrastructure bundling experience. Long-term viability framing centers on contractors who can pivot from generation-only contracts to integrated generation-transmission-distribution tenders as the Ministry of Energy consolidates procurement stages. Watch for foreign currency access protocol liberalization as the inflection signal triggering accelerated equipment import and construction mobilization.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Generation-Transmission Tendering | Ministry of Energy pilots in Kassala compress vendor management overhead for capital-constrained state utilities. |
| Local Content Compliance Certification | Sudanese labor thresholds of 30% separate qualified bidders from foreign firms lacking subcontractor relationships. |
| Battery Storage System Integration | 4-hour duration lithium-ion specifications in mining corridor tenders mandate DC-coupled architecture engineering. |
| Hydroelectric Rehabilitation Credentialing | Sennar and Roseires dam contracts require cumulative hydrological study capabilities under environmental procedures. |
| Humanitarian-Energy Convergence Positioning | Darfur mini-grid deployments leverage regulatory exemption from grid code compliance to accelerate rural energization. |
Research Methodology
Coverage spans Khartoum State, River Nile State, Red Sea State, and Darfur Region, with primary inputs from each sub-region's project development pipeline. Utility planning officers, independent power project developers, EPC contractors, and grid operators provided structured interviews on procurement timelines and qualification requirements. Secondary validation drew from Sudan's Ministry of Energy tender announcements, central bank foreign currency protocols, national electricity regulator grid code standards, and environmental impact assessment procedures. Bottom-up project aggregation triangulates against top-down macroeconomic capacity planning frameworks.
Rate-of-change decomposition separates volume growth from pricing dynamics across the analysis window, with segmentation modeled by technology type, service bundling depth, end-user payment security tier, and project capacity scale. CAGRs derive from installed capacity buildout trajectories applied to EPC contract value per megabyte benchmarks. Forecast inputs incorporate feed-in tariff framework stability assumptions, hydroelectric rehabilitation program sequencing, and industrial zone expansion pipelines in Khartoum North and Jabal Awlia.
Foreign currency access rationing, sovereign payment mechanism reliability, and grid backbone interconnection bottlenecks are the dominant revision risks to modeled EPC contract flow. Forecasts reflect documented assumptions on equipment import financing availability and contractor qualification threshold evolution. A model refresh is warranted upon material change in central bank hard currency allocation protocols or Ministry of Energy tender consolidation policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
HVDC Capacitor Market
Power
Solar Plants Controllers Market
Power
Direct Current Power System Market
Power
Germany Solar Inverter Market
Power
Italy Power Market
Power
India Power Market
Power
Residential Portable Inverter Generator Market
Power
Europe Submarine Power Cables Market
Power
Residential Micro Inverter Market
Power
Statcom Market
Power
Green UPS Market
Power
North America CHP Market
Power
Asia-Pacific Turbomachinery Control Systems Market
Power
Combined Heat and Power (CHP) Systems Market
Power
Smart Power Market
Power
Single-Phase Microinverter Market