
 Battery Electronic Control Unit Market | 2026-2036
Battery Electronic Control Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Electronic Control Unit Market Outlook
The EU Battery Regulation is decoupling legacy ECU designs from next-generation battery management requirements, forcing suppliers to embed state-of-charge algorithms with carbon traceability. Robert Bosch GmbH leverages its semiconductor foundry partnerships to secure silicon carbide supply for power modules. Infineon Technologies AG dominates automotive-grade microcontroller supply through its AURIX platform. Panasonic Corporation anchors cylindrical cell integration expertise into ECU firmware development for thermal runaway prevention.
A Battery Electronic Control Unit is an embedded electronic system comprising voltage sensing circuits, temperature acquisition channels, and balancing FET arrays that execute cell monitoring, state estimation, and fault isolation across lithium-ion battery packs. The device operates at sampling frequencies exceeding 100 Hz to maintain electrochemical stability during charge and discharge cycles. Advanced ECU variants command margin premiums due to ASIL-D functional safety certification requirements and predictive diagnostic capabilities. CAN Bus technology leads automotive installations, though Ethernet adoption is accelerating in 800-volt architectures where data throughput demands exceed legacy protocol limits. OEMs represent the dominant procurement channel, with direct sourcing contracts locking in multi-year firmware customization agreements.
FDA oversight applies to battery ECUs deployed in medical mobility devices, while EPA tailpipe rules indirectly shape automotive battery management specifications through range optimization mandates. NHTSA defect investigation protocols force ECU suppliers to maintain traceable calibration records across production lots. Stakeholders must monitor how ISO 26262 functional safety revisions and emerging wireless battery management standards alter hardware architecture roadmaps.
Market Dynamics
Automotive OEMs are forcing a fundamental redesign of ECU architectures as 800-volt battery platforms demand real-time data throughput that legacy CAN Bus protocols cannot deliver. This voltage transition is concentrating procurement power among vehicle assemblers capable of multi-year firmware customization contracts.
Growth Catalysts
- EU Battery Regulation:Mandates for digital battery passports and carbon footprint disclosure are compelling ECU suppliers to embed traceability algorithms directly into state-of-charge estimation firmware.
- Silicon carbide semiconductors:Power module efficiency gains from wide-bandgap materials are reducing thermal management overhead in high-voltage architectures, enabling faster cell balancing cycles.
- Stuttgart-Wolfsburg corridor:Geographic co-location of Tier-1 suppliers with German vehicle assemblers is compressing development feedback loops and accelerating validation timelines.
Market Restraints
- Automotive-grade microcontroller concentration:Dominant supply positions in AURIX-class chips create single-source vulnerability for ASIL-D certified ECU production.
- Functional safety certification costs:ISO 26262 compliance timelines and third-party validation expenses impose six-figure barriers on new market entrants.
- Lithium-ion cell chemistry lock-in:Established voltage sensing and balancing algorithms optimized for cylindrical formats resist adaptation to prismatic and solid-state architectures.
Strategic Opportunities
- Ethernet backbone migration:800-volt platforms are creating white space for ECU suppliers capable of delivering deterministic networking protocols that exceed legacy CAN bandwidth limits.
- Wireless battery management standards:Elimination of wiring harnesses between cell monitoring units and central controllers enables pack architecture redesigns with reduced assembly labor.
- Medical mobility devices:FDA-regulated powerchair and prosthetic applications represent an adjacent vertical with lower automotive-style certification barriers and higher margin profiles.
Industry Challenges
- Functional safety engineering talent:ASIL-D firmware development requires specialized expertise in failure mode analysis that outstrips current semiconductor industry training pipelines.
- Legacy vehicle platform integration:Retrofitting Ethernet-capable ECUs into existing 400-volt architectures demands backward-compatible gateway designs that increase hardware complexity.
- Calibration record retention:NHTSA defect investigation protocols require traceable production lot documentation spanning decade-long vehicle lifecycles, straining data infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Electronic Control Unit Market |
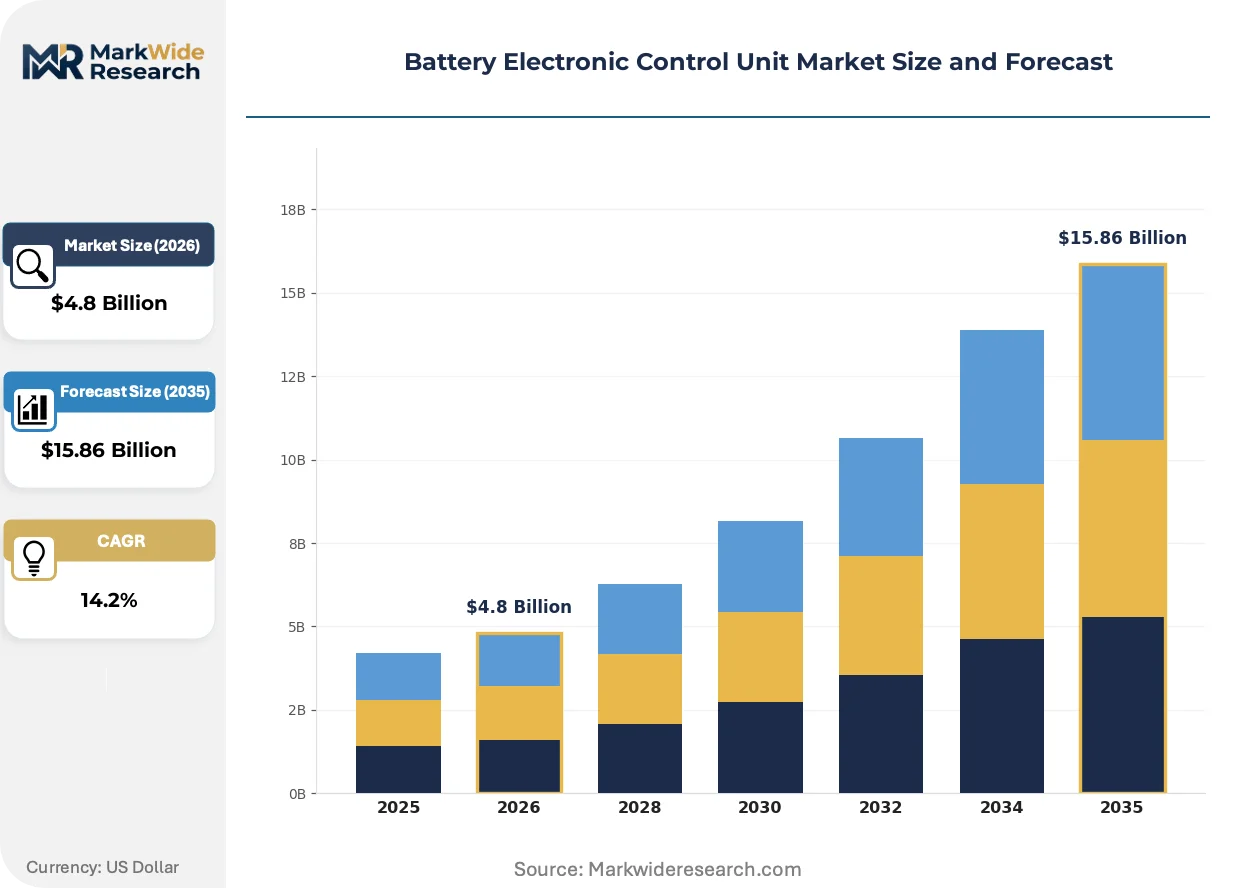
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard ECU, Advanced ECU, Hybrid ECU, Custom ECU Technology: Pulse Width Modulation, CAN Bus, LIN Bus, Ethernet End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Electric Vehicles, Hybrid Vehicles, Energy Storage Systems, Power Tools |
| Companies Covered | Infineon Technologies AG, Aptiv, Robert Bosch GmbH, Hitachi Automotive Systems, ZF Friedrichshafen AG, Continental AG, NXP Semiconductors, Panasonic Corporation, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Electronic Control Unit Market Strategic Shifts
Electrification architectures are compressing the boundary between power electronics and battery management, forcing ECU designs to absorb functions previously handled by discrete controllers. This integration pressure is reshaping supplier competitive positions and procurement specifications simultaneously.
Wireless battery management systems are unifying cell monitoring, balancing control, and thermal sensing onto single-chip architectures that eliminate isolation transformers and wiring harnesses. Premium EV platforms in Germany and South Korea are piloting these topologies for 2025 model year introductions. The technology is unifying previously separate hardware tiers into consolidated ECU designs that reduce pack assembly cost structures.
REACH substance restrictions and RoHS compliance deadlines are forcing ECU manufacturers to eliminate lead-based solder and specific flame retardants from printed circuit board assemblies. Industrial consequence includes qualification delays for alternative metallurgy in high-vibration automotive environments. German Tier-1 suppliers are responding fastest, leveraging existing materials science partnerships with semiconductor foundries to maintain qualification schedules.
Direct OEM contracting is displacing traditional Tier-1 distribution channels as vehicle assemblers seek exclusive firmware customization rights and dedicated engineering support. Battery management system procurement now flows through centralized EV platform teams rather than decentralized commodity purchasing. This concentration is most visible in California and Shanghai, where vertical integration between vehicle brands and cell producers has collapsed the traditional supplier hierarchy.
Battery Electronic Control Unit Market Segmentation
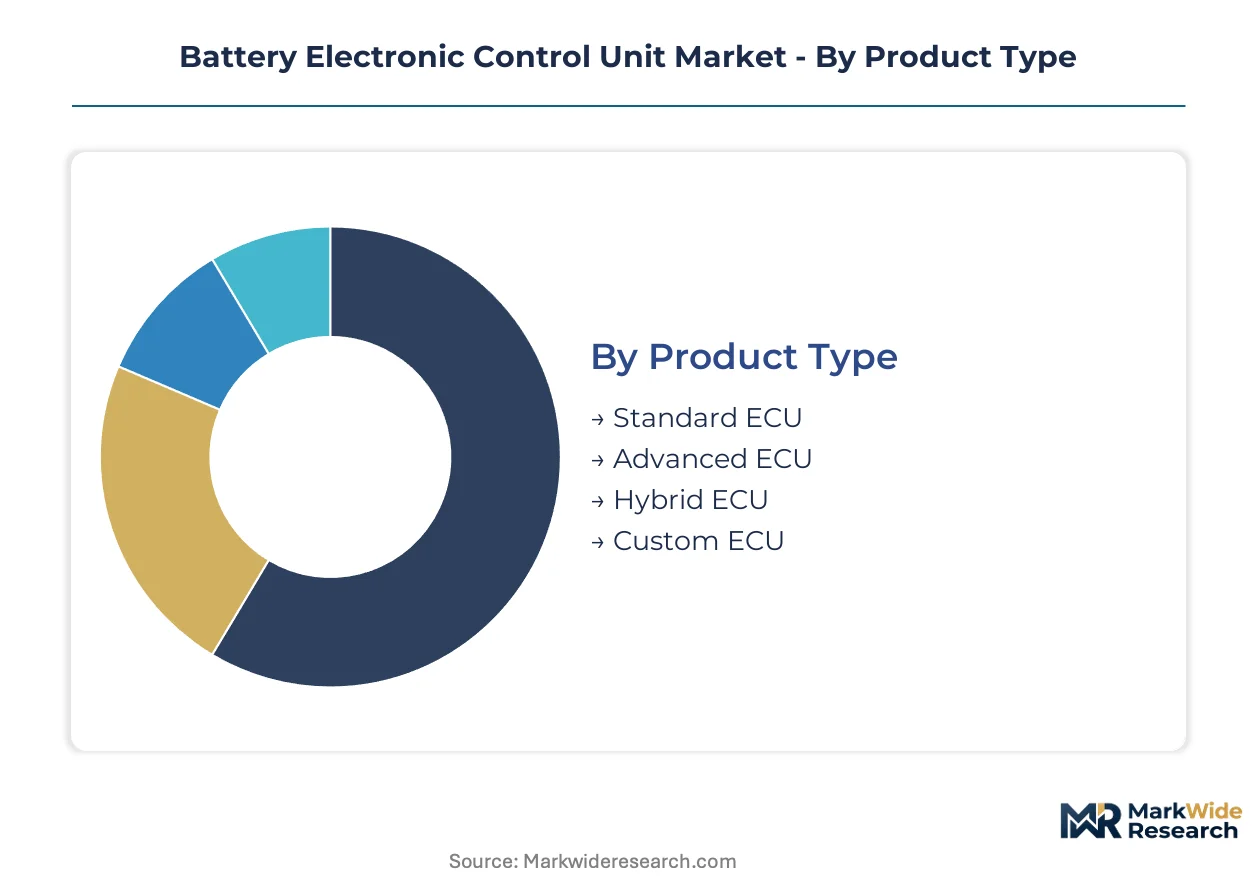
ECU segmentation tracks how integration depth varies across voltage architectures and functional safety requirements. Product tiers diverge sharply between standalone modules for aftermarket replacement and embedded systems co-designed with vehicle platforms.
Product Type:
Integration depth separates standalone replacement units from embedded platform-native designs, with firmware customization rights determining procurement channel access.
- Standard ECU:Fixed-parameter designs using off-the-shelf voltage sensing ICs and passive balancing topologies. Demand concentrates in aftermarket channels serving legacy 400-volt vehicle fleets across Germany and China, constrained by limited firmware update capability and ASIL-B certification ceilings.
- Advanced ECU:ASIL-D certified architectures with predictive diagnostic algorithms and silicon carbide power stages. Procurement concentrates with premium EV OEMs in Stuttgart and Wolfsburg corridors where multi-year firmware customization contracts lock engineering resources.
- Hybrid ECU:Dual-protocol designs bridging CAN Bus legacy networks with Ethernet backbone migration paths.
- Custom ECU:Application-specific designs with dedicated thermal runaway prevention firmware for cylindrical cell formats.
Standard ECU leads volumes today; Advanced ECU is gaining share fastest.
Technology:
Communication protocols stratify by data throughput requirements, with legacy bus architectures facing displacement in high-voltage platforms.
- Pulse Width Modulation:Analog control methodology for cell balancing FET arrays using fixed-frequency switching with variable duty cycles. Demand persists in cost-optimized power tool and energy storage applications across Chinese manufacturing clusters, though automotive migration to digital protocols limits expansion.
- CAN Bus:Differential serial protocol dominating 400-volt architectures with 1 Mbps throughput and deterministic latency. Procurement concentrates with established Tier-1 suppliers serving legacy vehicle platforms in Wolfsburg and Detroit, constrained by bandwidth ceilings in 800-volt battery management.
- LIN Bus:Low-cost single-wire protocol for auxiliary sensing nodes in door and seat battery applications.
- Ethernet:Deterministic networking with 100 Mbps throughput enabling real-time thermal imaging and predictive state estimation.
CAN Bus leads volumes today; Ethernet is climbing the fastest.
End User:
Procurement authority is consolidating toward vehicle platform teams with exclusive firmware rights, collapsing traditional distribution hierarchies.
- OEMs:Direct contracting entities with centralized EV platform teams controlling multi-year firmware customization agreements. Demand concentrates with vertically integrated assemblers in California and Shanghai where cell-to-pack architectures eliminate Tier-1 intermediary roles.
- Aftermarket Providers:Independent distributors serving vehicle service networks with replacement ECUs calibrated to legacy platform specifications.
- Tier-1 Suppliers:Traditional system integrators with co-location advantages in German automotive corridors.
- Vehicle Assemblers:Contract manufacturers without captive design engineering seeking standardized ECU specifications.
OEMs lead volumes today; Tier-1 Suppliers face share erosion fastest.
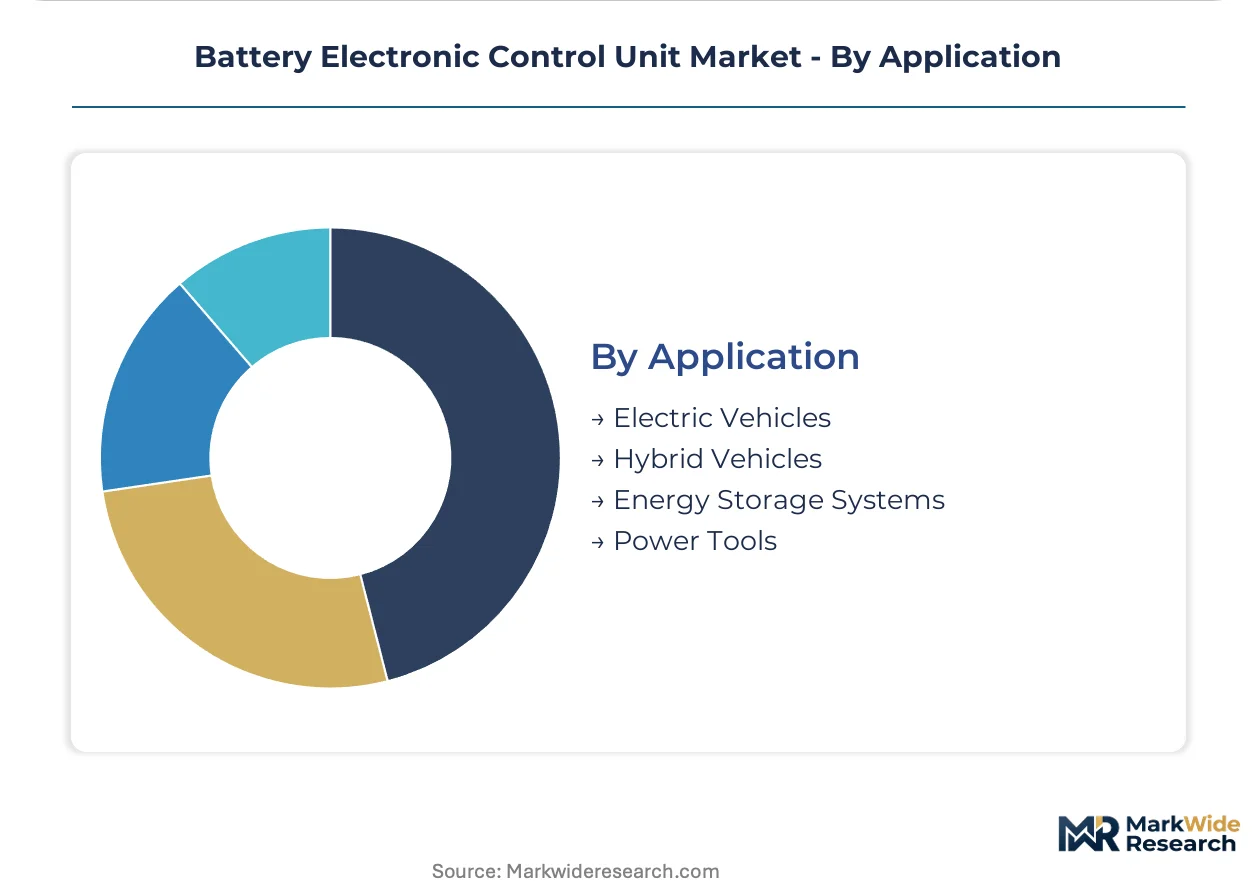
Application:
Cell chemistry and pack architecture requirements fragment ECU specifications across mobility and stationary energy verticals.
- Electric Vehicles:High-voltage platforms demanding ASIL-D functional safety with real-time thermal runaway prevention. Procurement concentrates with 800-volt architectures in South Korea and Germany where silicon carbide integration enables faster balancing cycles.
- Hybrid Vehicles:Dual-voltage designs managing both high-voltage traction packs and 12-volt auxiliary systems.
- Energy Storage Systems:Grid-scale installations with modular rack architectures and centralized monitoring requirements.
- Power Tools:Compact cylindrical cell packs with simplified balancing and no functional safety certification requirements.
Electric Vehicles lead volumes today; Energy Storage Systems show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive engineering established the foundational architectures for battery management systems during the 1990s hybrid vehicle programs, creating the technical lineage that now dominates high-voltage ECU design standards worldwide.
Germany
Stuttgart and Wolfsburg anchor European demand for ASIL-D certified ECUs as Mercedes-Benz Group and Volkswagen AG consolidate battery platform engineering. The EU Battery Regulation mandates digital passports and carbon footprint disclosure, forcing firmware redesigns. Baden-Württemberg's semiconductor corridor concentrates silicon carbide supply partnerships between Robert Bosch GmbH and foundry operators.
China
CATL and BYD procurement of battery management systems is reshaping global ECU specifications through volume-driven customization requirements. MIIT dual carbon goals accelerate 800-volt platform adoption across NEV manufacturers. The Yangtze River Delta cluster around Shanghai hosts the densest concentration of cell-to-pack ECU co-development programs with European Tier-1 suppliers.
United States
Tesla and Rivian direct contracting models are collapsing traditional Tier-1 intermediary roles in battery management procurement. NHTSA defect investigation protocols force traceable calibration record retention across decade-long vehicle lifecycles. California's EV platform teams in Palo Alto and Irvine lock multi-year firmware exclusivity agreements with semiconductor vendors.
South Korea
Hyundai Motor Group and LG Energy Solution joint ventures are driving Ethernet-backbone ECU adoption in 800-volt architectures. MFDS medical device regulations create adjacent demand channels for powerchair battery management systems. The Busan-Ulsan corridor concentrates thermal runaway prevention firmware development for cylindrical cell formats.
Japan
Toyota and Panasonic vertical partnerships sustain proprietary ECU architectures optimized for prismatic cell monitoring. METI battery supply chain security initiatives prioritize domestic microcontroller sourcing for critical automotive applications. The Nagoya-Tokyo corridor maintains legacy CAN Bus expertise while piloting deterministic networking migration paths.
Battery Electronic Control Unit Market Competitive Environment
Capital-heavy semiconductor foundries compete with asset-light fabless designers for architectural control in battery ECU supply chains. Market structure concentrates around three tiers: integrated device manufacturers with captive fabrication, automotive Tier-1 system integrators with firmware customization rights, and specialized microcontroller vendors licensing core IP. Dominant competitive moves include strategic foundry partnerships securing silicon carbide supply and exclusive multi-year firmware development agreements locking engineering resources.
Among German-based industrial conglomerates, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify the Tier-1 system integrator archetype with co-location advantages in Stuttgart automotive corridors. Infineon Technologies AG anchors the semiconductor vendor tier through automotive-grade microcontroller supply. These three entities represent divergent strategic positions: foundry-linked manufacturing scale, vehicle platform firmware integration, and chip-level functional safety certification.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Aptiv |
| Robert Bosch GmbH |
| Hitachi Automotive Systems |
| ZF Friedrichshafen AG |
| Continental AG |
| NXP Semiconductors |
| Panasonic Corporation |
| Denso Corporation |
| Others |
Value Chain & Pricing Dynamics
ASIL-D certification premiums against standard ECU commodity pricing create a bifurcation that simultaneously concentrates procurement power with German premium OEMs and fragments supply chain tiers between silicon carbide-integrated foundry partnerships and off-the-shelf microcontroller distributors. This divergence forces Tier-1 suppliers to maintain dual sourcing strategies while automotive platform teams in Stuttgart and Wolfsburg extract firmware exclusivity through multi-year engineering contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with ASIL-D certification grade and silicon carbide power module integration serving as primary price differentiation drivers. Cost compression in standard ECU tiers is intensifying because Chinese cell-to-pack architectures eliminate intermediary margins, while premium EV OEMs in Germany show least price sensitivity due to firmware customization requirements locking engineering resources.
Supply Chain Analysis
Single-source vulnerability sits with Infineon's AURIX microcontroller dominance and Taiwan's semiconductor foundry concentration for silicon carbide substrates. The supply chain draws from Germany for automotive-grade firmware engineering, China for cell-to-pack integration manufacturing, and South Korea for cylindrical cell thermal management IP. Tariff exposure on wide-bandgap semiconductors threatens cost structures, while distribution runs through direct OEM contracting channels that bypass traditional Tier-1 intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Battery Regulation functions as a regulatory compounder, with digital passport mandates and carbon footprint disclosure requirements forcing architectural redesigns that expand addressable demand for traceability-embedded ECU firmware.
For Market Incumbents: Lock in silicon carbide foundry partnerships before capacity constraints harden, and deepen backward integration into automotive-grade microcontroller design to offset single-source vulnerability from Infineon's AURIX dominance. Firmware exclusivity contracts with Stuttgart-Wolfsburg OEMs represent the critical defensive lever against emerging fabless competitors. For New Entrants and Emerging Players: FDA medical device regulations in the United States open a window for powerchair and prosthetic battery management applications where ASIL-D certification barriers fall below automotive thresholds. Target medical mobility OEMs in California and Massachusetts with wireless battery management topologies that eliminate wiring harness assembly costs. For Investors and Strategic Acquirers: Consolidation pressure builds where functional safety engineering talent scarcity intersects with ISO 26262 validation infrastructure requirements. The acquisition target archetype is fabless ECU designers with deterministic Ethernet protocol IP and existing medical device regulatory filings. Watch for inflection when wireless battery management standards achieve IEEE ratification.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Partnership | Secures wide-bandgap substrate supply for 800-volt power modules ahead of capacity constraints. |
| Firmware Exclusivity Contract | Locks multi-year engineering resources with Mercedes-Benz and Volkswagen platform teams. |
| Wireless Battery Management Development | Eliminates isolation transformers and wiring harnesses for pack architecture cost reduction. |
| Medical Mobility Regulatory Filing | Opens FDA-cleared demand channel with higher margins and lower certification barriers. |
| Ethernet Backbone Migration | Captures 800-volt platform data throughput requirements exceeding CAN Bus bandwidth limits. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, semiconductor foundry account managers, and medical device regulatory consultants. Secondary validation drew from NHTSA defect investigation databases, EU Battery Regulation implementation notices, MIIT new energy vehicle production statistics, and SEC semiconductor vendor filings. Bottom-up cell monitoring unit shipment estimates and top-down EV platform production forecasts were cross-referenced for triangulation.
Segment-weighting approaches applied voltage architecture tiers, functional safety certification levels, and communication protocol types across the analysis window. CAGRs were derived from modeled adoption curves for 800-volt platforms and wireless battery management penetration rates. Industry-specific inputs included silicon carbide power module cost decline trajectories and ISO 26262 revision timelines affecting hardware architecture roadmaps.
Forecast precision tightens around the base case; tail outcomes carry wider variance under raw material export restriction scenarios and foundry capacity allocation shifts. Forecasts reflect assumptions regarding EU Battery Regulation enforcement timing and NEV subsidy continuity in China. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Switching Regulators Power Management IC Market
Power Systems
Global Frequency Converter Market
Power Systems
Embedded Power Generation Market
Power Systems
Central Battery Systems Market
Power Systems
Grid Forming Inverters Market
Power Systems
Battery Equalizer Market
Power Systems
Bypass Thyristor Market
Power Systems
Linear Voltage Regulators Market
Power Systems
Global Telecom Tower Power System Market
Power Systems
North America Variable Frequency Drive Market
Power Systems
Low Voltage Drives Market
Power Systems
South America Battery Management System Market
Power Systems
Generator Circuit Breaker Market
Power Systems
Asia-Pacific DC Distribution Networks Market
Power Systems
Asia-Pacific Electric Vehicle Power Inverter Market
Power Systems
DC-DC Converter Market