
 Switching Regulators Power Management IC Market | 2026-2036
Switching Regulators Power Management IC Market Size, Share, and Industry Trends Forecast 2026-2036
Switching Regulators Power Management IC Market Analytics
Market Dynamics
Multi-source procurement for switching regulator die is shifting toward captive wafer supply and long-term foundry partnerships. Texas Instruments Incorporated anchors North American supply through its internal 300mm fabrication. Infineon Technologies AG competes via vertical integration into gallium nitride process technology. STMicroelectronics extends its position through European automotive qualification programs.
Technology and Segmentation
Switching regulators power management ICs are voltage conversion circuits employing pulse-width modulation to achieve efficiencies exceeding ninety percent, primarily serving battery-powered and mains-isolated systems. Step-down architectures dominate unit shipments due to their ubiquity in consumer and automotive voltage rails, while buck-boost configurations capture premium margin pools in hybrid electric vehicle drivetrains. Digital control technology leads R&D investment as OEMs demand programmable loop compensation and telemetry for predictive maintenance.
Regulatory Environment
The EU Ecodesign Directive and REACH substance restrictions constrain material choices and mandate minimum efficiency thresholds for external power supplies. The EPA ENERGY STAR program and California CEC Title 20 standards enforce comparable efficiency floors in the United States. Stakeholders must monitor evolving carbon-border adjustment mechanisms and semiconductor subsidy conditions that alter cost competitiveness between regional supply bases.
Market Dynamics
Gallium nitride process technology is compressing incumbent silicon MOSFET architectures across automotive and data center power stages. This displacement is forcing legacy suppliers to requalify entire product portfolios while opening margin pools for early movers with captive GaN fabrication.
Growth Catalysts
- EU Ecodesign efficiency mandates:Tightened minimum performance standards for external power supplies are mandating active-mode efficiency above 89 percent, forcing adapter OEMs to abandon linear regulators entirely.
- EV powertrain electrification:Battery electric vehicle production in China is consuming high-current buck-boost regulators for 800V architectures at volumes unmatched by other end-use verticals.
- Digital control telemetry:Programmable loop compensation with predictive maintenance data streams is consolidating design wins in server power and telecom infrastructure.
Market Restraints
- 300mm silicon wafer concentration:Captive foundry capacity at Texas Instruments and limited merchant supply from TSMC create allocation risk during demand spikes.
- REACH substance restrictions:ECHA constraints on leadframe plating chemistries and molding compounds are extending qualification timelines by 8-14 months for automotive-grade products.
- Linear regulator residual demand:Ultra-low noise applications in precision instrumentation and medical imaging retain incumbent LDO architectures that resist full substitution.
Strategic Opportunities
- India PLI scheme for semiconductors:Production-linked incentives for domestic fab and ATMP capacity are attracting switching regulator assembly and test investments.
- AI server power density:GPU rack power budgets exceeding 120kW are creating white space for multi-phase controllers with transient response below 100 nanoseconds.
- Wireless charging integration:Qi2 and magnetic resonance standards are embedding resonant converter ICs into consumer device ecosystems previously served by discrete solutions.
Industry Challenges
- Automotive AEC-Q100 qualification:Zero-defect requirements and temperature cycling to 150°C are compressing time-to-revenue for new product introductions.
- GaN e-mode driver integration:Cascode and direct-drive architectures demand mixed-signal design capabilities scarce in legacy analog power teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switching Regulators Power Management IC Market |
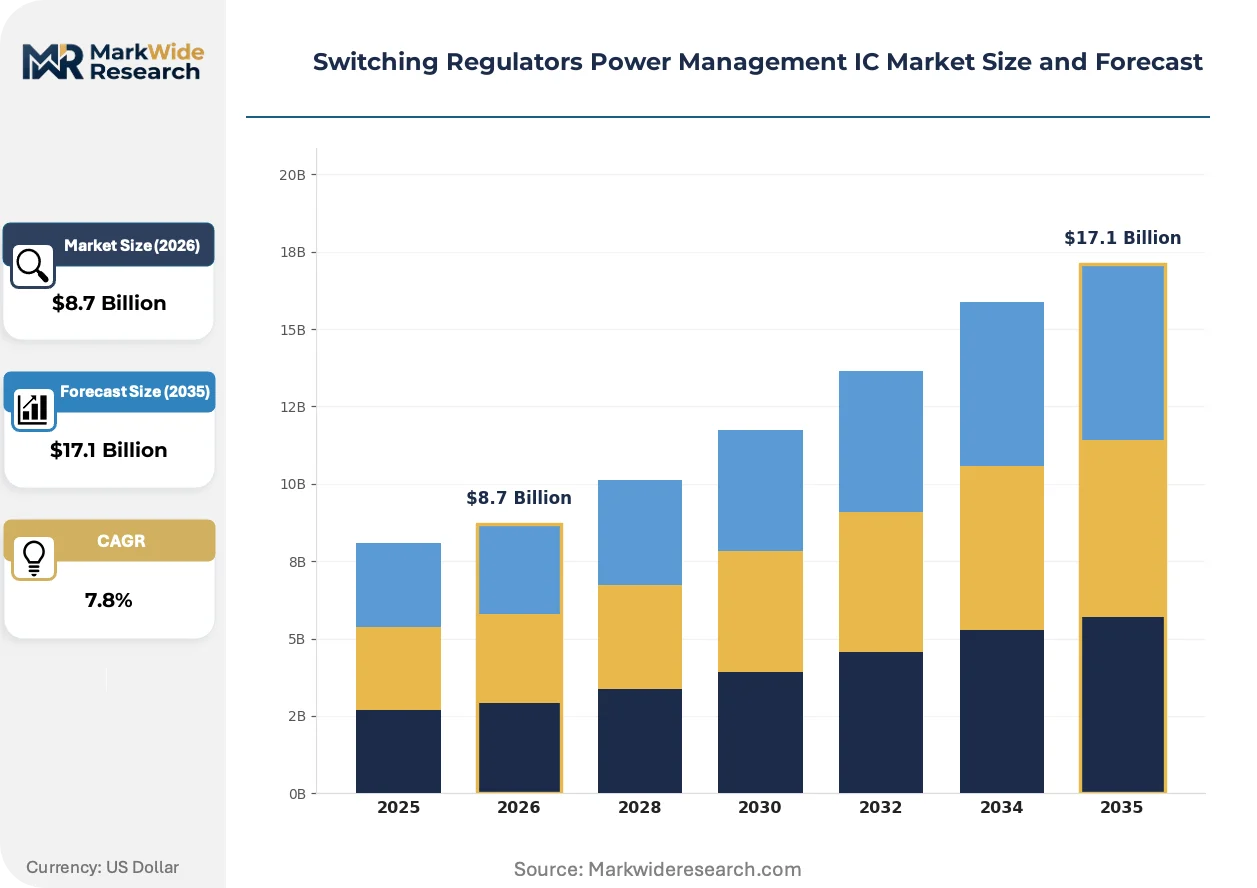
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Step-Down, Step-Up, Buck-Boost, Integrated Technology: Linear, Digital, Analog, Hybrid Application: Consumer Electronics, Automotive Systems, Industrial Equipment, Telecommunications End User: OEMs, Aftermarket Suppliers, System Integrators, Developers |
| Companies Covered | STMicroelectronics, Maxim Integrated, Texas Instruments Incorporated, Microchip Technology Inc, NXP Semiconductors, Infineon Technologies AG, Analog Devices, Renesas Electronics Corporation, ROHM Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switching Regulators Power Management IC Market Evolving Landscape
Silicon carbide and gallium nitride wide-bandgap semiconductors are redefining efficiency benchmarks across voltage classes. This transition is compressing the viable window for superjunction MOSFETs while creating new subsystem integration opportunities.
GaN power ICs with monolithic gate drivers and protection logic are consolidating discrete component counts in 48V intermediate bus converters. Data center operators at hyperscale facilities in Virginia and Frankfurt are qualifying these solutions for 98.5 percent peak efficiency targets. The technology is consolidating board area and thermal management costs that previously constrained power density roadmaps.
EPA ENERGY STAR Version 8.0 and California CEC Title 20 Tier 2 standards are mandating no-load power consumption below 100 milliwatts for external adapters. Adapter OEMs serving North American retail channels are redesigning flyback controllers with burst-mode operation and active X-capacitor discharge. The regulations are compressing margins for non-compliant inventory while rewarding architectural transitions to quasi-resonant and active clamp topologies.
Direct procurement from foundry partners is displacing traditional distribution for high-volume automotive and computing OEMs. Tier-1 suppliers in Germany and Japan are negotiating wafer starts and die bank agreements that bypass authorized distributors entirely. This channel compression is most visible in 12V and 48V multiphase controllers where single-customer programs absorb dedicated fab capacity.
Switching Regulators Power Management IC Market Segmentation
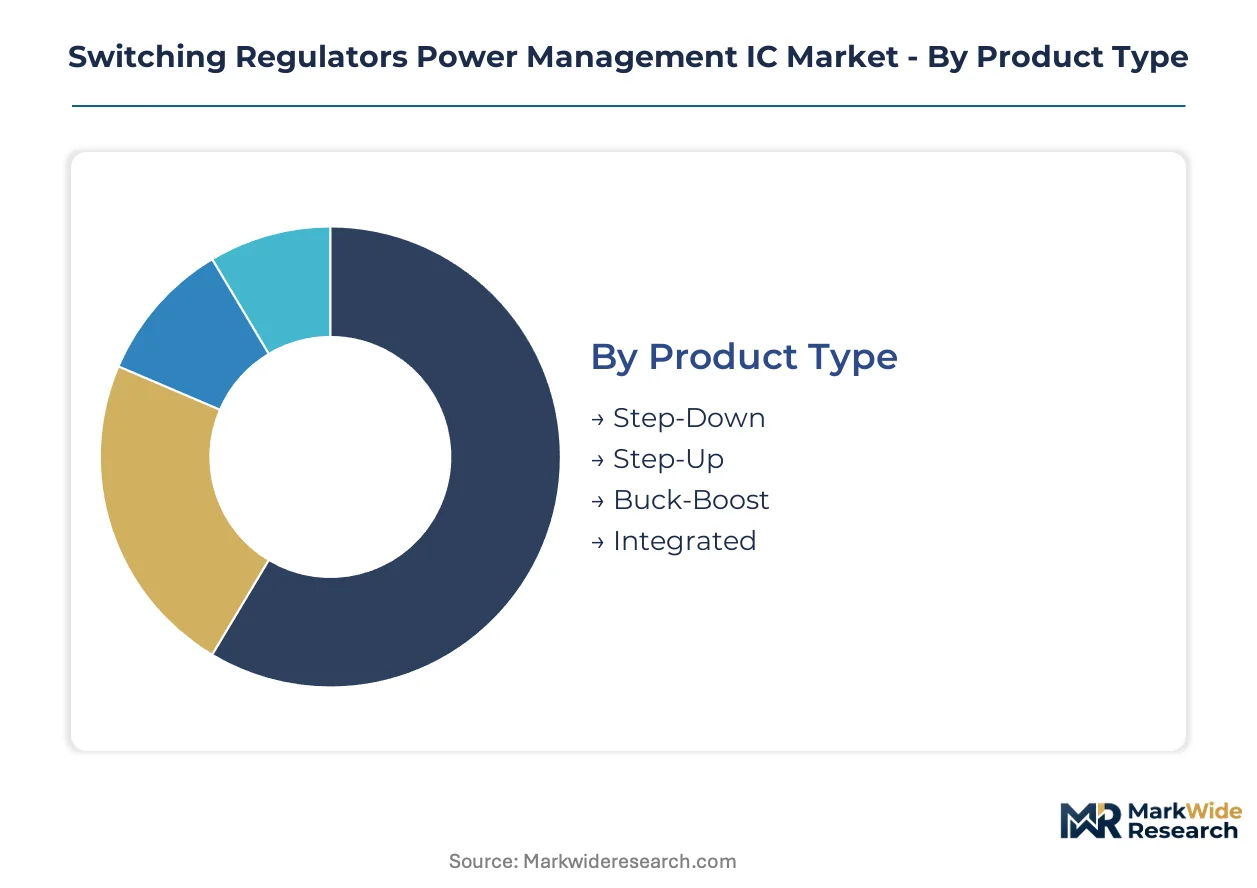
Switching regulator architectures fragment across voltage conversion topologies, control methodologies, and end-use qualification tiers. Each segment carries distinct margin profiles, automotive qualification timelines, and foundry capacity requirements that shape supplier portfolio decisions.
Product Type:
Step-down architectures dominate unit volumes while buck-boost configurations command premium pricing in high-voltage automotive rails.
- Step-Down:Pulse-width modulation circuits reduce input voltage through inductive energy storage with synchronous rectification. Consumer electronics OEMs in China consume the highest volumes for smartphone and laptop voltage rails, driven by EU Ecodesign efficiency mandates above 89 percent.
- Buck-Boost:H-bridge configurations enable seamless voltage transition across battery discharge curves. Battery electric vehicle powertrains in China deploy these for 800V architectures where cell voltage sag demands bidirectional conversion capability.
- Step-Up:Boost inductor topologies serve LED driver and USB power delivery applications requiring voltage elevation from single-cell lithium sources.
- Integrated:Monolithic solutions combining controller, driver, and power stage reduce board area for space-constrained wearables and IoT endpoints.
Today's leader: Step-Down. Tomorrow's challenger: Buck-Boost.
Technology:
Control methodology determines loop response speed, programmability, and silicon area trade-offs across foundry nodes.
- Analog:Continuous-time comparators and error amplifiers deliver sub-microsecond transient response without digital overhead. Server power designers at hyperscale facilities in Virginia and Frankfurt specify these for 98.5 percent peak efficiency targets in 48V intermediate bus converters.
- Digital:Programmable state machines enable adaptive loop compensation and telemetry streaming for predictive maintenance. Telecom infrastructure OEMs consolidate design wins here as remote monitoring becomes mandatory for SLAs.
- Hybrid:Mixed-signal architectures partition fast analog feedback from slow digital supervision, balancing response speed against configurability.
- Linear:Residual demand persists in precision instrumentation and medical imaging where sub-millivolt noise floors resist switching substitution.
Analog anchors current revenue. Digital is climbing the fastest.
Application:
Automotive qualification requirements create the steepest barriers to entry, while consumer electronics drives pure volume scale.
- Automotive Systems:AEC-Q100 Grade 0 qualification demands zero-defect performance across -40°C to 150°C temperature cycling. German Tier-1 suppliers negotiate wafer starts and die bank agreements that bypass distribution channels entirely for 12V and 48V multiphase controllers.
- Consumer Electronics:External adapter OEMs redesign flyback controllers with burst-mode operation to meet EPA ENERGY STAR Version 8.0 no-load limits below 100 milliwatts.
- Industrial Equipment:Extended temperature ranges and isolation requirements serve factory automation motor drives and programmable logic controllers.
- Telecommunications:Base station power supplies and optical module POL converters demand high reliability with multi-decade field life.
Automotive commands margin expansion. Consumer electronics absorbs volume scale.
End User:
Direct procurement patterns diverge sharply between captive design teams and merchant market channels.
- OEMs:Vertical integration into power design accelerates as automotive and computing giants qualify proprietary regulator architectures. Texas Instruments serves this channel through internal 300mm fabrication with dedicated capacity allocation.
- System Integrators:Server and storage subsystem assemblers specify multiphase controllers with transient response below 100 nanoseconds for AI rack power budgets exceeding 120kW.
- Aftermarket Suppliers:Replacement adapter and repair markets face compressed margins as efficiency regulations obsolete non-compliant inventory.
- Developers:Evaluation module demand from research institutions and startup hardware teams seeds future design wins through early ecosystem engagement.
OEMs control premium access. System integrators drive architectural specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta anchors switching regulator demand through battery electric vehicle production clusters and renewable energy infrastructure deployment. Regional procurement concentrates around Shanghai, Suzhou, and Ningbo manufacturing corridors.
China
Domestic EV powertrain electrification and 800V architecture adoption consume the highest volumes of high-efficiency buck-boost regulators. MIIT efficiency mandates under dual carbon goals reshape procurement criteria for automotive OEMs. The Pearl River Delta manufacturing belt around Shenzhen and Guangzhou hosts the densest concentration of adapter OEMs redesigning flyback controllers for export markets.
United States
Hyperscale data center operators in Virginia and Frankfurt-adjacent US facilities specify GaN-based 48V intermediate bus converters for AI server racks exceeding 120kW. EPA ENERGY STAR Version 8.0 and California CEC Title 20 Tier 2 standards enforce no-load consumption below 100 milliwatts. Austin, Texas anchors North American supply through captive 300mm fabrication serving automotive and computing OEMs directly.
Germany
Tier-1 automotive suppliers negotiate wafer starts and die bank agreements for 12V and 48V multiphase controllers under AEC-Q100 Grade 0 requirements. The EU Green Deal and tightened Ecodesign regulations mandate active-mode efficiency above 89 percent for external power supplies. Baden-Württemberg's Stuttgart-Karlsruhe corridor concentrates automotive qualification programs and power electronics R&D.
Japan
Precision instrumentation and medical imaging retain demand for ultra-low noise linear regulators that resist full switching substitution. METI industrial efficiency programs and JIS standards guide domestic procurement specifications. The Kanto region around Tokyo hosts mixed-signal design capabilities for GaN e-mode driver integration.
India
Production-linked incentives for domestic fab and ATMP capacity attract switching regulator assembly and test investments from multinational suppliers. BIS certification requirements and CEA power quality standards shape local procurement. Karnataka's Bangalore-Chennai electronics corridor emerges as the primary concentration for outsourced semiconductor assembly.
Switching Regulators Power Management IC Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue wide-bandgap process technology and digital control integration. The supplier base concentrates around vertically integrated analog power specialists and foundry-dependent fabless designers. Three archetypes dominate: captive fabrication owners with dedicated capacity allocation, GaN process technology pioneers with upstream material control, and automotive-qualified European suppliers with zero-defect track records. Competitive moves center on backward integration into wafer supply and long-term foundry partnerships that bypass distribution channels.
Among European automotive-qualified suppliers, STMicroelectronics, Infineon Technologies AG, and NXP Semiconductors exemplify the zero-defect archetype through AEC-Q100 program participation. Texas Instruments Incorporated represents captive fabrication ownership with internal 300mm supply serving direct OEM procurement. Analog Devices and Maxim Integrated occupy positions within the precision-signal conditioning tier that bridges linear and switching architectures. Renesas Electronics Corporation and ROHM Co Ltd anchor Asia-Pacific supply positions through mixed-signal heritage and automotive customer relationships.
| Leading Market Players |
|---|
| STMicroelectronics |
| Maxim Integrated |
| Texas Instruments Incorporated |
| Microchip Technology Inc |
| NXP Semiconductors |
| Infineon Technologies AG |
| Analog Devices |
| Renesas Electronics Corporation |
| ROHM Co Ltd |
| Others |
Value Network & Pricing Analysis
Captive wafer supply anchors both cost predictability and margin defense for switching regulator suppliers. Texas Instruments' internal 300mm fabrication in Austin insulates its automotive and computing OEM customers from foundry allocation shocks while preserving pricing power through dedicated capacity. This integration choice separates premium-tier suppliers from fabless competitors exposed to TSMC spot-market volatility.
Pricing Analysis
Input-cost pass-through from silicon wafer and gallium nitride substrate prices stratifies supplier margins across three performance tiers. Automotive AEC-Q100 Grade 0 qualification commands premium positioning against consumer-grade alternatives, while volume-scale buyers in China's EV clusters extract standard-tier discounts through multi-year die bank agreements. Pricing pressure stems from EU Ecodesign efficiency mandates compressing margins for non-compliant legacy inventory. Consumer electronics adapter OEMs exhibit highest price sensitivity, whereas German Tier-1 automotive suppliers prioritize supply assurance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for automotive-grade switching regulators remain underdeveloped, with end-of-life recovery concentrated in industrial equipment refurbishment rather than consumer electronics. Manufacturing concentrates in Taiwan, South Korea, and the United States, with GaN epitaxy drawing from Japanese substrate suppliers and European MOCVD equipment makers. Single-source vulnerability sits with 300mm silicon wafer supply from Texas Instruments and limited merchant alternatives. Distribution runs through direct procurement channels for high-volume automotive and computing OEMs, bypassing traditional authorized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between China's MIIT efficiency mandates and India's PLI semiconductor subsidies, with assembly cost differentials exceeding qualification timeline premiums.
For Market Incumbents: Lock in long-term foundry partnerships that bypass distribution channels entirely, mirroring German Tier-1 supplier procurement patterns. Secure captive gallium nitride process technology to defend against silicon MOSFET displacement. Prioritize AEC-Q100 Grade 0 qualification investment as zero-defect requirements compress time-to-revenue windows.
For New Entrants and Emerging Players: Direct-to-OEM digital sales channels bypass entrenched distribution relationships and open design-win opportunities in India's emerging ATMP corridor. Target buck-boost regulator white space in China's 800V EV architectures where incumbent capacity is allocated to established programs. Lead with programmable digital control telemetry to differentiate against analog legacy portfolios.
For Investors and Strategic Acquirers: Roll-up economics work for automotive-qualified European suppliers because AEC-Q100 program participation creates durable customer captivity through zero-defect track records. Five-to-ten year viability hinges on wide-bandgap process technology migration. Monitor GaN e-mode driver integration capabilities as the inflection signal separating acquisition targets from stranded analog assets.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Process Technology Migration | Captive gallium nitride fabrication secures margin pools as silicon MOSFET architectures face displacement. |
| AEC-Q100 Grade 0 Qualification | Zero-defect automotive certification compresses competitor entry timelines by 8-14 months under REACH constraints. |
| Direct OEM Procurement Channels | Wafer start agreements with German Tier-1 suppliers bypass distribution and lock dedicated fab capacity. |
| Digital Control Telemetry Integration | Programmable loop compensation captures server power and telecom infrastructure design wins at hyperscale facilities. |
| India PLI Assembly Investment | Production-linked incentives attract ATMP capacity for switching regulator test and packaging operations. |
Research Methodology
Coverage spans China, the United States, Germany, Japan, and India, with primary inputs from each regional cluster. Semiconductor procurement executives at automotive Tier-1 suppliers, power design engineers at hyperscale data center operators, and analog power team leads provided structured interviews. Secondary validation drew from MIIT efficiency filings, EPA ENERGY STAR certification databases, SEC 10-K disclosures, and EU Ecodesign regulatory impact assessments. Bottom-up unit demand modeling triangulated against top-down semiconductor consumption estimates.
Granularity extended to voltage conversion topology, control methodology, and end-use qualification tier across the projection horizon. Step-down, buck-boost, step-up, and integrated architectures were modeled separately with distinct foundry capacity assumptions. Analog, digital, hybrid, and linear control segments incorporated divergent R&D investment trajectories. CAGRs derived from regression analysis against EV production forecasts and data center power density roadmaps, with GaN penetration curves as a primary sensitivity input.
The model assumes a particular technology adoption path; alternative pathways for silicon carbide in 800V automotive rails would alter the outlook. Forecasts reflect assumptions about REACH substance restriction timelines and MIIT dual carbon enforcement intensity. Practitioners should monitor GaN e-mode driver integration capabilities and carbon-border adjustment mechanism proposals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
HVDC Converters Market
Power Systems
Battery Equalizer Market
Power Systems
AC Voltage Transducer Market
Power Systems
High Current Power Supply for Electrophoresis Market
Power Systems
Global Battery Thermal Management System Market
Power Systems
High Voltage Ceramic Zinc Oxide Surge Arrester Market
Power Systems
Power Amplifier Modules Market
Power Systems
Global Fault Current Limiter Market
Power Systems
Converter Modules Market
Power Systems
Three-Phase String Inverter Market
Power Systems
Bypass Thyristor Market
Power Systems
Organic Fixed Power Capacitors Sales Market
Power Systems
Global Gan Power Device Market
Power Systems
AC DC Power Adapter Market
Power Systems
Central Battery Systems Market
Power Systems
Low Voltage AC Drive Market