
 Europe SLI Battery Market | 2026-2036
Europe SLI Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe SLI Battery Market Insights
Skilled battery technician shortages across Central Europe is redrawing competitive dynamics for aftermarket service networks. Clarios International Inc leverages its pan-European collection infrastructure to sustain closed-loop recycling economics. Exide Technologies anchors volume production through manufacturing scale in Portugal and Spain. GS Yuasa International Ltd differentiates via technology leadership in AGM formulations for premium automotive platforms.
An SLI battery is a rechargeable lead-acid or lithium-ion unit engineered for starting, lighting, and ignition functions in internal combustion and mild-hybrid vehicles, typically delivering cold cranking amperage between 300A and 1000A at sub-zero temperatures. Flooded lead acid dominates installed base across price-sensitive vehicle segments, though AGM absorbs share in start-stop configurations where cycling durability commands premium positioning. Lithium-ion represents the fastest-growing product type, penetrating power sports and select marine applications where weight reduction justifies cost premiums over conventional chemistries.
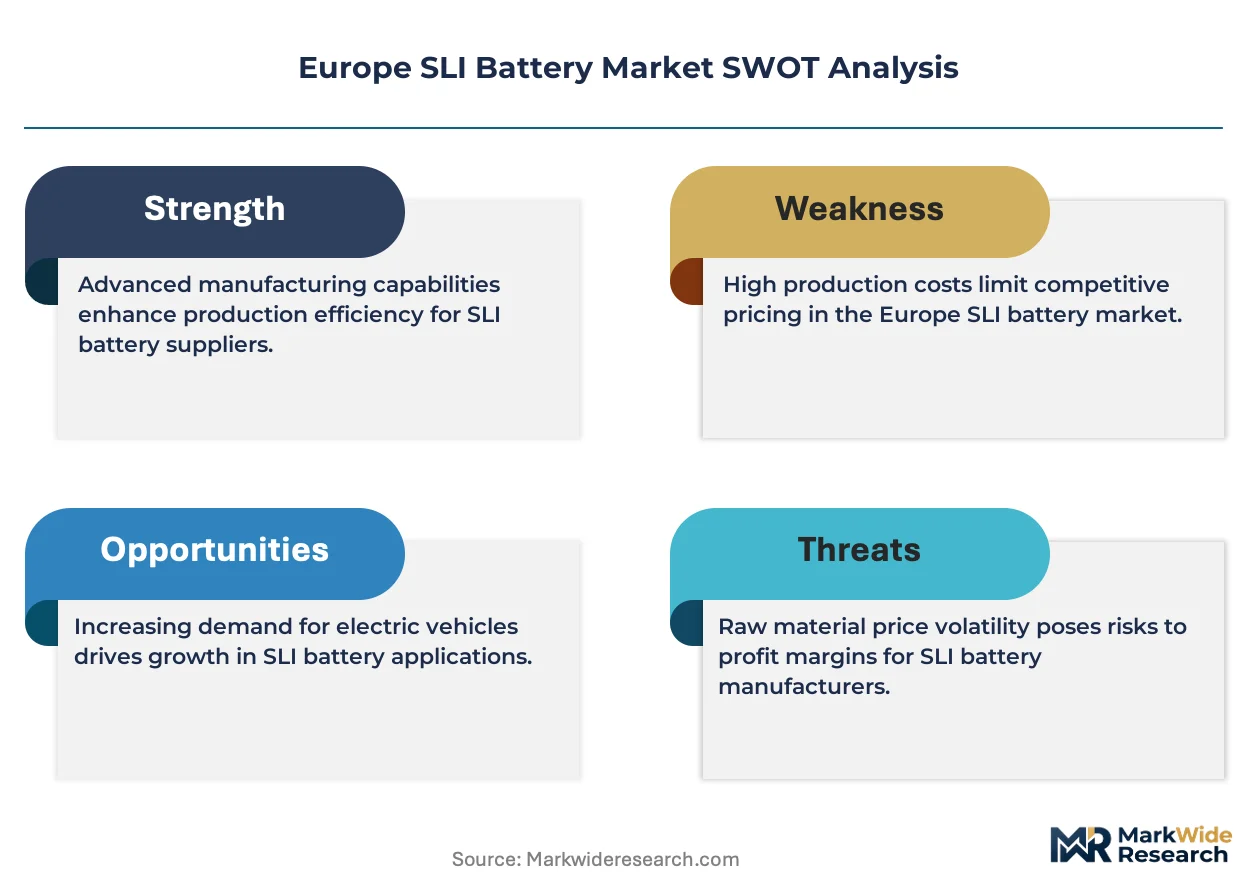
REACH compliance and the EU Battery Regulation mandate recycled content thresholds and supply chain due diligence, elevating compliance costs for importers while favoring producers with established European metallurgical partnerships. ECHA substance restrictions on lead exposure in manufacturing are accelerating automation investments at assembly plants. Stakeholders must monitor how carbon border adjustments and evolving extended producer responsibility frameworks reshape sourcing economics for raw lead and separator materials.
Market Dynamics
Vehicle electrification is bifurcating the SLI battery value chain, as mild-hybrid architectures demand enhanced cycling endurance while pure electric platforms eliminate starting functions entirely. This tension is redirecting R&D investment toward AGM optimization and lithium-ion weight reduction for residual internal combustion segments.
Growth Catalysts
- EU Green Deal decarbonization mandates:Binding emissions targets for battery production are accelerating facility upgrades and metallurgical process improvements across European manufacturing corridors.
- Start-stop system proliferation:Automotive OEMs in Germany and France are specifying deep-cycle AGM configurations to support engine-off coasting in congested urban driving profiles.
- Closed-loop recycling economics:Established collection infrastructure in Benelux and Nordic regions is lowering raw lead procurement costs for producers with integrated smelter partnerships.
Market Restraints
- Lead price volatility:London Metal Exchange pricing fluctuations for refined lead ingot compress margin stability for producers without captive mining or long-term offtake agreements.
- Substitution by high-voltage architectures:Full hybrid and battery electric vehicles are eliminating dedicated SLI units, shrinking addressable volume in premium passenger segments.
- ECHA occupational exposure limits:Tightening workplace lead concentration thresholds are forcing capital-intensive automation retrofits at aging assembly plants in Eastern Europe.
Strategic Opportunities
- Marine and power sports lithium conversion:Italian and Scandinavian OEMs are specifying lithium-ion SLI units for weight-critical applications where cold cranking performance justifies cost premiums.
- Extended producer responsibility frameworks:The EU Battery Regulation's recycling content mandates are creating first-mover advantages for producers with pre-existing European metallurgical joint ventures.
- Remanufacturing service networks:Independent aftermarket operators in Poland and Czechia are building regional refurbishment capacity to capture value from end-of-first-life batteries.
Industry Challenges
- Certified battery technician scarcity:Vocational training pipelines across Central Europe are failing to produce sufficient skilled labor for diagnostic and replacement service expansion.
- REACH compliance documentation burden:Supply chain due diligence requirements for separator materials and electrolyte additives are extending procurement qualification timelines for importers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe SLI Battery Market |
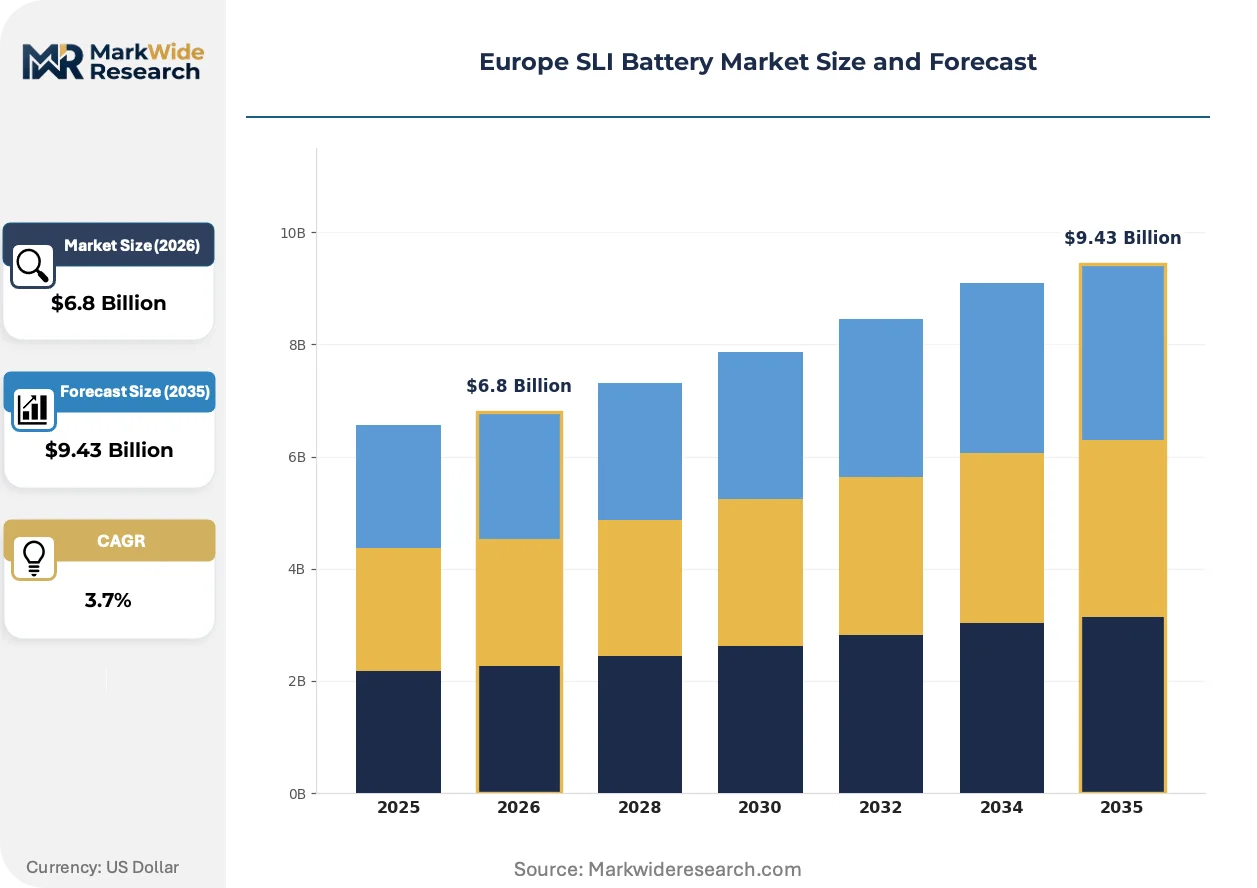
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.43 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flooded Lead Acid, AGM, Gel, Lithium-ion Application: Automotive, Marine, Power Sports, Industrial Capacity: 50Ah, 60Ah, 70Ah, 80Ah Installation: Original Equipment Manufacturer, Aftermarket, DIY, Professional Service |
| Companies Covered | EnerSys, Clarios International Inc, GS Yuasa International Ltd, C&D Technologies Inc, Leoch International Technology Limited Inc, Exide Technologies, East Penn Manufacturing Company, Trojan Battery Company, Johnson Controls, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe SLI Battery Market Trends and Innovations
Electrification is fragmenting technical roadmaps across the European supplier base, with divergent bets on lead-acid refinement versus lithium-ion substitution reshaping competitive positioning. Three developments are commanding strategic attention.
Thin-plate pure lead technology is miniaturizing cell dimensions while preserving cold cranking output, enabling packaging flexibility in congested mild-hybrid engine bays. Tier 1 suppliers are qualifying these configurations for premium German platforms where space optimization competes with thermal management demands. The technology is miniaturizing physical footprints without sacrificing amperage density, compressing traditional form factor standards.
REACH substance restrictions are forcing reformulation of separator materials and electrolyte additives, elevating compliance costs for non-European suppliers without established chemical registration portfolios. ECHA's evolving candidate list for substances of very high concern is particularly impacting flame retardant selection in battery casings. Southern European producers with integrated polymer compounding capabilities are internalizing these adjustments faster than import-dependent competitors.
Fleet operators are consolidating aftermarket purchasing through integrated service contracts that bundle battery replacement with telematics-enabled predictive maintenance. This procurement compression is disintermediating traditional distributor networks in France and Spain where independent garages previously dominated replacement demand. German commercial vehicle lessors are piloting these arrangements most aggressively, pressuring price transparency across national borders.
Europe SLI Battery Market Segmentation
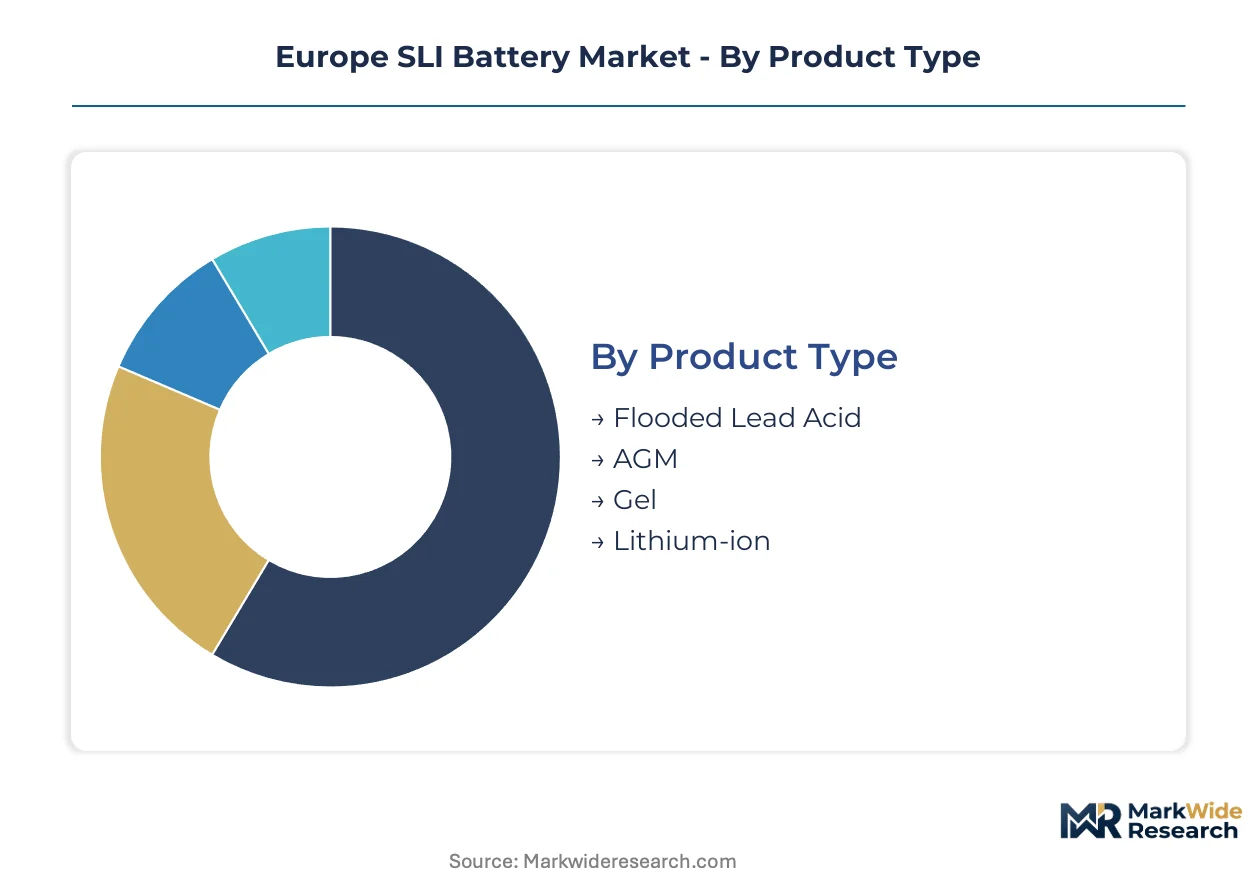
Segmentation in the Europe SLI Battery Market reveals how electrification pressures and regulatory frameworks are fragmenting demand across chemistry types and service channels. Each dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning for producers and distributors.
Product Type:
Flooded lead acid and AGM units flow primarily through automotive OEM contracts and national distributor networks, while lithium-ion penetrates specialized retail and direct marine channels where weight specifications command premium positioning.
- Flooded Lead Acid:Conventional lead-acid chemistry with liquid electrolyte requiring upright installation and periodic maintenance. Demand concentrates in Eastern European price-sensitive vehicle segments and legacy fleet operators in Poland and Romania where total cost of ownership outweighs cycling performance requirements.
- AGM:Absorbent glass mat construction immobilizes electrolyte in fiberglass separators, enabling deep-cycle durability for start-stop systems. German and French OEMs specify AGM configurations for mild-hybrid platforms where engine-off coasting in urban traffic patterns demands enhanced charge acceptance.
- Gel:Silica-thickened electrolyte eliminates stratification risks for tilted or vibration-prone installations. Marine applications in Scandinavian waters and Mediterranean charter fleets specify gel units for spill-proof reliability.
- Lithium-ion:Lithium iron phosphate or lithium manganese oxide cathodes deliver 60-70% weight reduction over lead-acid equivalents. Italian power sports manufacturers and Nordic marine OEMs are specifying these units where cold cranking performance justifies procurement cost premiums.
Flooded lead acid dominates installed base across Europe's volume vehicle parc. Lithium-ion is where expansion concentrates in premium marine and power sports niches.
Application:
Cost tier stratification separates automotive volume production from industrial and marine segments where performance specifications justify chemistry premiums and specialized distribution.
- Automotive:Passenger vehicles and light commercial fleets requiring 300-1000A cold cranking amperage for internal combustion and mild-hybrid starting systems. German OEM integration clusters around Stuttgart and Wolfsburg manufacturing corridors, while aftermarket demand strengthens from fleet operators managing electrification transition risks.
- Marine:Recreational and commercial vessels requiring vibration resistance and deep-cycle reserve capacity for auxiliary loads. Scandinavian Baltic Sea operators and Mediterranean charter fleets in Italy and Spain specify gel and lithium-ion configurations for weight-critical sailing yachts and high-performance motorcraft.
- Power Sports:Motorcycles, ATVs, and snowmobiles demanding compact form factors and reliable sub-zero starting. Alpine regions in Austria and Switzerland drive seasonal replacement cycles for lithium-ion conversions in high-end touring motorcycles.
- Industrial:Forklifts, stationary backup power, and material handling equipment requiring extended cycle life. Warehouse logistics operators in Benelux and Northern Germany specify heavy-duty flooded and AGM configurations for multi-shift operations.
Automotive absorbs the majority of unit volume. Marine and power sports are climbing the fastest as lithium-ion substitution accelerates.
Capacity:
Volume distribution tracks vehicle engine displacement and electrical load profiles, with mid-range capacities capturing the largest share of European passenger vehicle fitments.
- 50Ah:Compact car and urban runabout specifications for sub-1.4L engines with minimal auxiliary electrical demand. City car segments in Italy and France specify these capacities for weight and packaging optimization.
- 60Ah:Standard C-segment passenger vehicle fitment balancing cold cranking performance with engine bay space constraints. This capacity tier captures the largest unit volume across German and French OEM production lines.
- 70Ah:Mid-size sedans and SUVs with start-stop systems requiring enhanced cycling reserve. AGM configurations in this capacity range command premium positioning for mild-hybrid platforms.
- 80Ah:Light commercial vehicles and premium SUVs with high electrical load demands from infotainment and driver assistance systems. Fleet operators in Germany and the Netherlands specify these capacities for delivery vans and executive transport.
60Ah and 70Ah capacities dominate current European vehicle production specifications. 80Ah is gaining share fastest as electrical system complexity escalates.
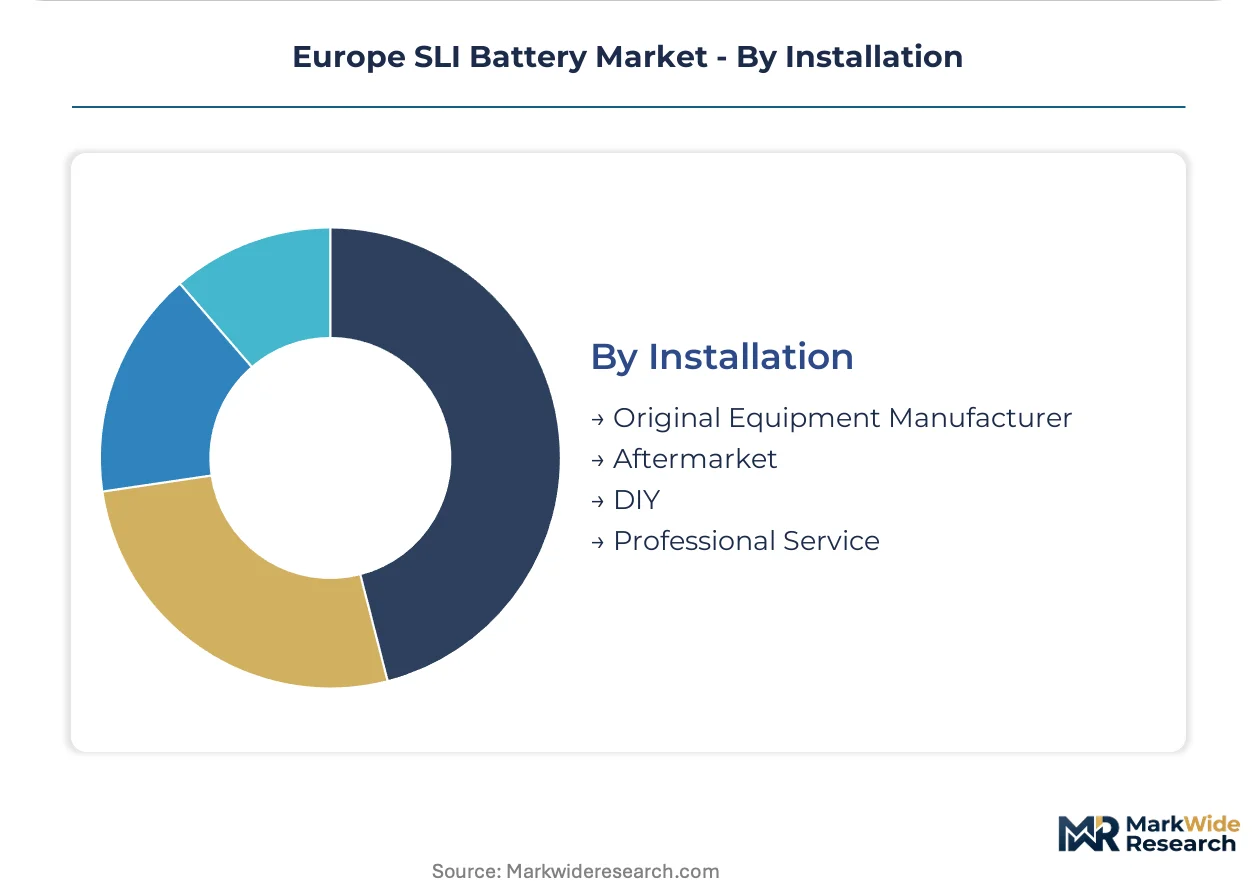
Installation:
Customer type and margin structure diverge sharply between integrated OEM supply chains and fragmented aftermarket channels with distinct service intensity requirements.
- Original Equipment Manufacturer:Tier 1 supplier integration with vehicle assembly plants requiring just-in-sequence delivery and zero-defect quality protocols. German OEMs in Stuttgart and Wolfsburg anchor this channel with multi-year supply agreements.
- Aftermarket:Independent distributors and garage networks serving replacement demand from aging vehicle parc. Fleet operators in France and Spain are consolidating purchasing through integrated service contracts that bundle battery replacement with predictive maintenance.
- DIY:Direct consumer purchase through retail auto parts chains for simple replacement procedures. Price transparency pressures compress margins in this channel across Central European markets.
- Professional Service:Certified technician installation required for start-stop system recalibration and battery management system integration. Skilled technician shortages across Poland and Czechia are constraining expansion of this high-margin service tier.
Aftermarket channels handle the majority of replacement volume. Professional service is where margin expansion concentrates as system complexity demands diagnostic capability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fleet operators deploy AGM configurations for start-stop systems at higher rates than Southern European counterparts, who favor flooded lead-acid for cost-sensitive vehicle parc maintenance. This consumption-mix differential shapes supplier investment priorities across the region.
Germany
OEM integration with premium automotive platforms drives AGM specification for mild-hybrid architectures. The EU Green Deal mandates facility decarbonization for battery production corridors. Stuttgart and Wolfsburg manufacturing clusters anchor just-in-sequence supply agreements with Tier 1 producers.
France
Commercial vehicle lessors consolidate aftermarket purchasing through bundled service contracts with predictive maintenance. REACH compliance documentation burdens extend procurement timelines for separator material imports. Lyon and Paris basin distribution networks face margin compression from fleet procurement centralization.
Italy
Power sports manufacturers specify lithium-ion SLI units for weight-critical touring motorcycles and marine applications. ECHA substance restrictions on flame retardant formulations impact casing material selection. Northern Italian industrial districts around Milan and Turin concentrate lithium conversion R&D for premium two-wheeler platforms.
Spain
Mediterranean charter fleets generate seasonal demand for gel battery configurations in sailing yachts and motorcraft. The F-Gas Regulation tightens emissions benchmarks for metallurgical processing at recycling facilities. Barcelona and Valencia port clusters sustain marine battery distribution networks serving leisure vessel operators.
Poland
Independent aftermarket operators build regional refurbishment capacity to capture end-of-first-life battery value. ECHA occupational exposure limits force automation investments at aging Eastern European assembly plants. Warsaw and Silesian industrial zones develop technician training pipelines to address certified installer scarcity.
Europe SLI Battery Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with closed-loop recycling capabilities and OEM supply relationships separating the upper tier from price-pressured distributors. Market structure reflects consolidation around metallurgical partnerships and start-stop system qualifications. Three archetypes dominate: pan-European collection infrastructure operators, AGM technology specialists, and volume-scale flooded lead-acid producers. Competitive moves concentrate on strategic partnerships for recycling joint ventures and geographic expansion into Central European aftermarket channels.
Among integrated recycling infrastructure operators, Clarios International Inc exemplifies the closed-loop archetype through its established collection networks. GS Yuasa International Ltd occupies a position within the technology-focused tier for premium AGM formulations. Exide Technologies anchors the scale-driven segment with manufacturing concentration in Southern Europe. These three represent distinct strategic postures without implying specific market share or operational claims.
| Leading Market Players |
|---|
| EnerSys |
| Clarios International Inc |
| GS Yuasa International Ltd |
| C&D Technologies Inc |
| Leoch International Technology Limited Inc |
| Exide Technologies |
| East Penn Manufacturing Company |
| Trojan Battery Company |
| Johnson Controls |
| Others |
Pricing and Supply Chain Analysis
Lithium-ion substitution in marine and power sports applications is redrawing raw material procurement geography while compressing lead-acid pricing power in traditional automotive tiers. This chemistry shift simultaneously elevates cobalt and lithium hydroxide sourcing from Nordic and Australian concentrate markets and intensifies margin pressure on flooded lead-acid producers without integrated smelter partnerships.
Pricing Analysis
Contract structures stratify between multi-year OEM offtake agreements for AGM volumes and spot-market transactions for flooded lead-acid replacement units. Price differentiation rests on cycling certification tiers for start-stop compatibility and geographic proximity to Benelux recycling infrastructure. Cost compression in the flooded tier is intensifying because Polish and Czech distributors are consolidating purchasing through fleet service contracts. Fleet operators in France and Spain exhibit highest price sensitivity, while German premium OEMs prioritize charge acceptance specifications over unit economics.
Supply Chain Analysis
Inventory buffers at Portuguese and Spanish assembly plants have compressed to six-week cycles for separator materials and electrolyte additives. Raw lead feedstock draws from German and Polish secondary smelters, while lithium carbonate hinges on Chilean and Australian mining concentrate. Single-source vulnerability concentrates in Chinese-manufactured battery management system components for lithium-ion configurations. Distribution runs through Stuttgart-anchored OEM supply chains and fragmented independent garage networks across Central Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe SLI Battery Market represents a defensive-moat opportunity anchored in regulatory entrenchment, where REACH compliance documentation and ECHA substance registration create irreversible switching costs for established European metallurgical partnerships.
For Market Incumbents: Fortify closed-loop recycling economics by deepening backward integration into Portuguese and Spanish smelter capacity before EU Battery Regulation mandates tighten. Extend OEM qualification pipelines for thin-plate pure lead configurations to defend margin position against lithium-ion substitution in premium start-stop platforms. Prioritize automation investments at Eastern European assembly plants to preempt ECHA occupational exposure limit enforcement. For New Entrants and Emerging Players: Certified technician scarcity in Poland and Czechia presents a service-layer gap where independent remanufacturing networks can capture end-of-first-life battery value. Target marine lithium conversion in Scandinavian Baltic Sea operations and Italian Mediterranean charter fleets where weight specifications justify procurement premiums. Deploy direct technical training partnerships with Warsaw and Silesian vocational institutes to secure installer capacity before incumbent distributors consolidate. For Investors and Strategic Acquirers: Capital is best deployed toward integrated recycling infrastructure operators with pre-existing Benelux collection networks and German OEM supply relationships, as these assets compound regulatory compliance advantages across the projection horizon. Monitor ECHA candidate list expansions for separator material restrictions as the inflection signal that will accelerate chemical registration portfolio valuations among Southern European polymer compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Recycling Joint Venture Formation | EU Battery Regulation mandates create first-mover advantage for producers with integrated metallurgical partnerships in Benelux corridors. |
| AGM Technology Qualification | German OEM start-stop specifications in Stuttgart and Wolfsburg anchor premium pricing for deep-cycle configurations. |
| Technician Training Pipeline Investment | Warsaw and Silesian vocational capacity addresses certified installer scarcity constraining professional service expansion. |
| Lithium-Ion Marine Conversion | Italian and Scandinavian OEM weight specifications justify cost premiums in Baltic Sea and Mediterranean charter applications. |
| Automation Retrofit Program | ECHA occupational exposure limits force capital deployment at aging Eastern European assembly plants. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings across this study. Conversations with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors in France and Spain, and recycling facility operators in Portugal and Poland were synthesized with REACH registration databases, ECHA substance restriction notices, and EU Battery Regulation implementation guidance. Bottom-up unit economics from individual chemistry configurations were triangulated against top-down production volume estimates from German and French vehicle registration data.
Sensitivity analysis around lead price volatility and lithium-ion penetration rates tests forecast robustness across the projection horizon. The analytical framework models segmentation by chemistry type, application tier, capacity band, and installation channel, with propulsion architecture and regional production cluster as cross-cutting dimensions. CAGRs were derived from regression against vehicle parc aging curves and electrification transition timelines, incorporating OEM platform standardization roadmaps and fleet operator consolidation patterns as industry-specific inputs.
Underlying assumptions cover steady-state EU Green Deal enforcement and REACH compliance trajectories, with deviation risk concentrated in ECHA substance restriction timing and carbon border adjustment implementation scope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Smart Diagnostic Battery Charger Market
Batteries
Hybrid Flow Battery Market
Batteries
Absorbent Glass Mat (AGM) Battery Market
Batteries
Primary Battery Market
Batteries
Primary Lithium Battery for Industrial Market
Batteries
India Electric Vehicle Battery Electrolyte Market
Batteries
Wide Temperature Battery Market
Batteries
Potassium-Ion Battery Market
Batteries
Asia Pacific Electric Vehicle Battery Electrolyte Market
Batteries
United States SLI Battery Market
Batteries
Printable Battery Market
Batteries
Automotive Start-Stop Battery Market
Batteries
Asia-Pacific NMC Battery Pack Market
Batteries
48 Volt Battery System Market
Batteries
Bangladesh Lead Acid Battery Market
Batteries
East Africa Battery Market