
 Portable Battery Market | 2026-2036
Portable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Battery Market Analysis
Modular battery packs with swappable cell configurations is decoupling power capacity from device form factor, letting buyers customize runtime without replacing entire units. Samsung Electronics leverages vertical integration across cell production and consumer electronics to sustain cost advantages in high-density formats. Anker Innovations specializes in compact, travel-certified designs that dominate premium direct-to-consumer channels. BYD Company Limited anchors industrial-grade portable systems with proprietary lithium iron phosphate chemistry.
Portable batteries are electrochemical energy storage devices, typically 1,000–50,000 mAh, engineered for transportable DC power supply using lithium-ion, nickel-metal hydride, or emerging solid-state architectures. These units buffer intermittent grid access and extend operational runtime for mobile equipment across consumer, commercial, and industrial settings. Lithium-ion chemistry leads unit economics and energy density, though solid-state formats are attracting R&D investment for their thermal stability and cycle life advantages. Consumer electronics remains the volume anchor, while industrial equipment and renewable energy integration represent faster-growing margin pools where OEM and utility procurement standards command premium pricing.
The EU Battery Regulation and REACH compliance frameworks in Europe, alongside China's GB/T standards administered by SAMR and the US FAA lithium cargo restrictions, are reshaping cell certification, recycling mandates, and cross-border shipment protocols. These rules elevate compliance costs for smaller exporters while favoring manufacturers with in-house testing laboratories and established regulatory affairs teams. Stakeholders must monitor solid-state commercialization timelines and regional recycling infrastructure buildouts to calibrate capacity investments and partnership strategies.
Market Dynamics
Energy density improvements in lithium-ion cells are compressing form factors while extending runtime, forcing manufacturers to recalibrate capacity-to-weight ratios across consumer and industrial product lines simultaneously.
Growth Catalysts
- EU Battery Regulation:Mandatory recycling targets and carbon footprint declarations are accelerating closed-loop supply chain investments among cell producers seeking passport compliance.
- Outdoor recreation equipment:Camping and overlanding gear manufacturers are integrating higher-capacity portable batteries into electric coolers, lighting systems, and cooking appliances.
- Solid-state electrolyte R&D:Laboratory-scale production of sulfide-based architectures is yielding prototypes with 40% higher volumetric energy density than conventional liquid electrolyte cells.
Market Restraints
- Cobalt supply concentration:Democratic Republic of Congo dominance in mined cobalt creates price volatility and ethical sourcing verification burdens for cathode material procurement.
- FAA lithium cargo restrictions:Air freight limitations on standalone battery shipments above 100 Wh constrain direct-to-consumer fulfillment speed and elevate last-mile logistics costs.
- Thermal runaway physics:Inherent exothermic decomposition risk in high-nickel cathode chemistries necessitates redundant protection circuitry that adds mass and cost.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting gigafactory investments targeting domestic electronics and automotive demand.
- Vehicle-to-load integration:Bidirectional charging ports in electric pickups and SUVs are creating aftermarket demand for high-wattage portable units capable of appliance power delivery.
- SAMR GB/T standard harmonization:China's streamlined safety certification process for cross-border e-commerce is reducing time-to-market for compliant exporters.
Industry Challenges
- Electrochemical engineering talent:Shortage of specialists with expertise in solid-electrolyte interphase optimization and cell aging modeling is slowing product development cycles.
- UN38.3 certification timelines:Extended testing queues at accredited laboratories are delaying new product introductions by four to six months.
- Legacy inventory amortization:Existing stock of cylindrical 18650 and 21700 format cells must clear channels before prismatic and pouch architectures achieve volume economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Battery Market |
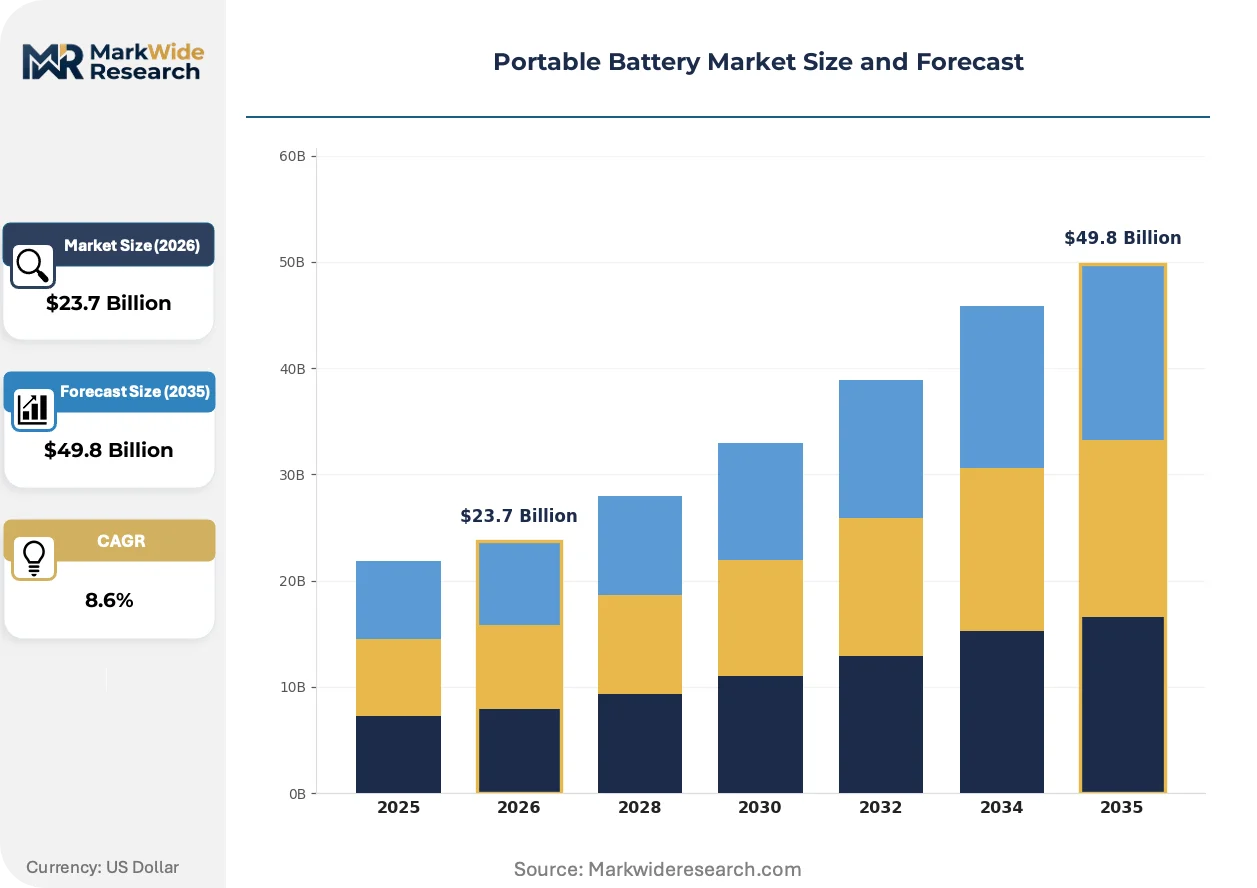
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, NiMH, Lead Acid, Solid State Application: Consumer Electronics, Electric Vehicles, Renewable Energy, Industrial Equipment End User: Retail Consumers, OEMs, Utilities, Businesses Technology: Fast Charging, Wireless Charging, Energy Storage, Power Management |
| Companies Covered | Samsung Electronics, Anker Innovations, Xiaomi Corporation, BYD Company Limited, Sony Group Corporation, Panasonic Holdings Corporation, LG Chem Ltd., Energizer Holdings Inc., Belkin International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Battery Market Emerging Trajectories
Solid-state battery architectures are transitioning from laboratory curiosity to pilot production, with implications for thermal management, cycle life, and manufacturing equipment requirements across the portable power sector.
Sulfide-based solid-state electrolyte technology is electrifying the premium portable segment by enabling lithium-metal anodes that eliminate graphite capacity constraints. Medical device and professional photography equipment manufacturers are qualifying these units for field deployment where charging access is intermittent. The technology is compressing the performance gap between portable units and stationary energy storage systems.
China's SAMR has tightened GB 31241 enforcement for lithium-ion cells sold through cross-border e-commerce platforms, mandating third-party testing documentation for all listings. This regulatory friction is elevating compliance costs for smaller sellers while consolidating marketplace presence among manufacturers with in-house certification capabilities. The consumer electronics accessory segment is experiencing the most pronounced seller attrition.
Direct-to-consumer subscription models for battery leasing are displacing outright purchase patterns among professional content creators and field service technicians. Equipment rental platforms and manufacturer-owned service programs are capturing recurring revenue streams previously lost to aftermarket replacement sales. This behavioral shift is most visible in North American and Western European urban markets where equipment utilization rates justify operational expenditure treatment.
Portable Battery Market Segmentation
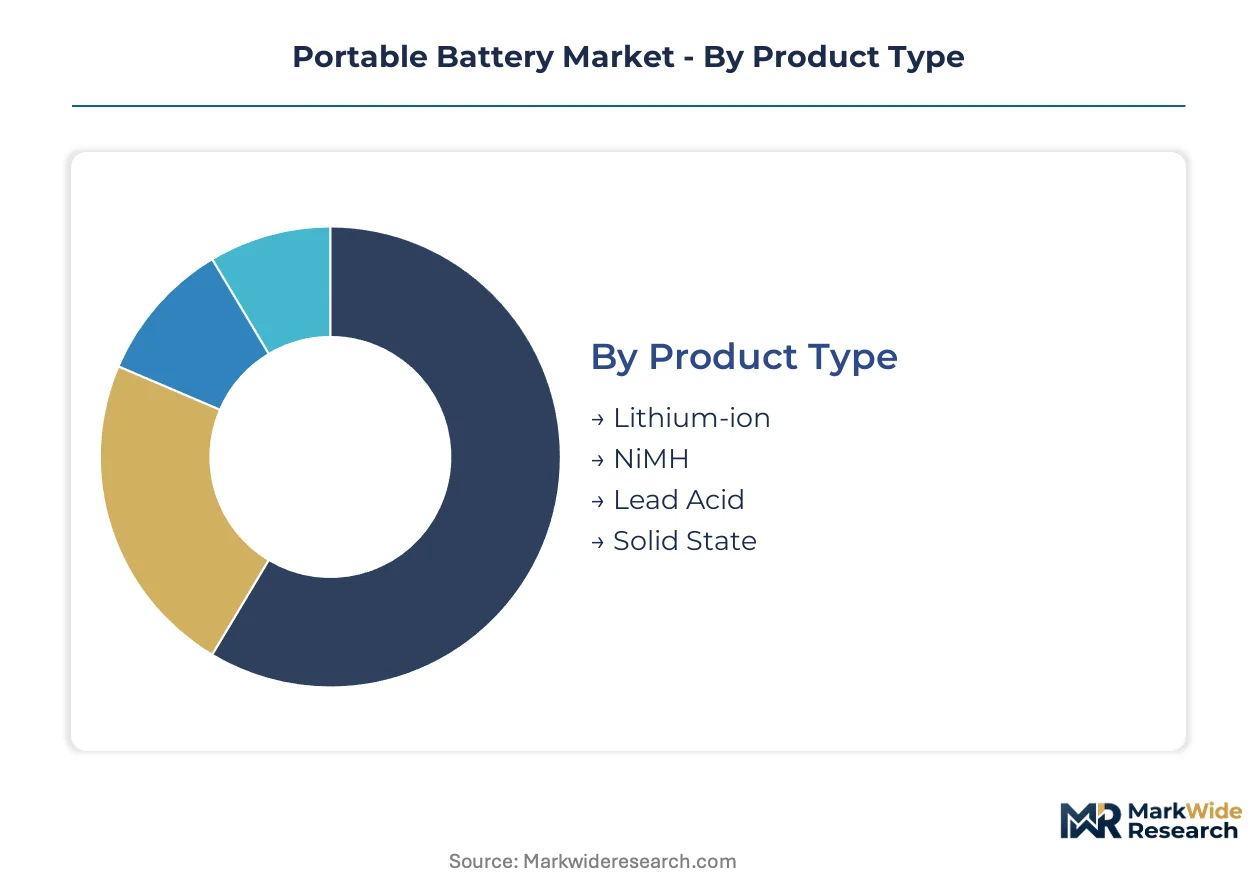
Portable battery buyers exhibit sharply divergent priorities across chemistry selection, application intensity, and procurement scale. Segmentation reveals how cell format, end-use durability requirements, and charging infrastructure availability reshape vendor go-to-market strategies.
Product Type:
Cost tier separates commodity buyers from performance-seeking segments willing to absorb chemistry premiums.
- Lithium-ion:Cobalt-nickel-manganese cathode formulations dominate energy density metrics above 250 Wh/kg. Demand concentrates in smartphone accessory channels and laptop power banks where Shenzhen manufacturing clusters exploit mature cylindrical cell supply chains.
- Solid State:Sulfide electrolyte architectures with lithium-metal anodes eliminate thermal runaway risks while pushing volumetric density past 400 Wh/L. Medical device manufacturers and professional cinematography equipment vendors in Germany and Japan are qualifying these units for field deployment where charging access is intermittent.
- NiMH:Nickel-metal hydride cells retain niche positioning in cordless power tools requiring cold-weather discharge tolerance.
- Lead Acid:Flooded and AGM formats persist in backup power for telecom base stations and rural solar installations where weight constraints are secondary to capital cost minimization.
Lithium-ion leads volumes today; solid state is gaining share fastest.
Application:
Volume scale distinguishes mass-market consumer flows from industrial procurement governed by qualification timelines.
- Consumer Electronics:Power banks, laptop battery packs, and wearable charging cases constitute the volume anchor. Amazon and direct-to-consumer channels in the United States and United Kingdom absorb the majority of 10,000-30,000 mAh units.
- Industrial Equipment:Remote monitoring systems, portable medical devices, and field robotics command 3-5x unit premiums over consumer equivalents. Oilfield services contractors and agricultural drone operators in Australia and Canada prioritize IP67 ingress protection and -20°C operational floors.
- Electric Vehicles:Aftermarket range extenders and emergency jump-start units serve EV owners in charging infrastructure gaps.
- Renewable Energy:Portable solar generators and off-grid storage buffers target cabin owners and disaster preparedness buyers.
Consumer electronics anchors shipment volumes; industrial equipment commands the steepest expansion trajectory.
End User:
Customer type determines whether procurement flows through retail markup or direct OEM negotiation.
- OEMs:Original equipment manufacturers integrate custom battery packs into finished goods during assembly. Laptop and power tool brands in Taiwan and South Korea specify cell suppliers 12-18 months ahead of product launches.
- Retail Consumers:Individual purchasers select from branded power banks through e-commerce marketplaces and electronics retailers. Travel restrictions on lithium cargo above 100 Wh constrain cross-border fulfillment options.
- Utilities:Grid operators deploy portable units for substation maintenance and emergency response vehicle fleets.
- Businesses:Field service fleets and event production companies negotiate volume contracts with rental and lease provisions.
OEMs dominate procurement value; retail consumers generate the highest transaction frequency.
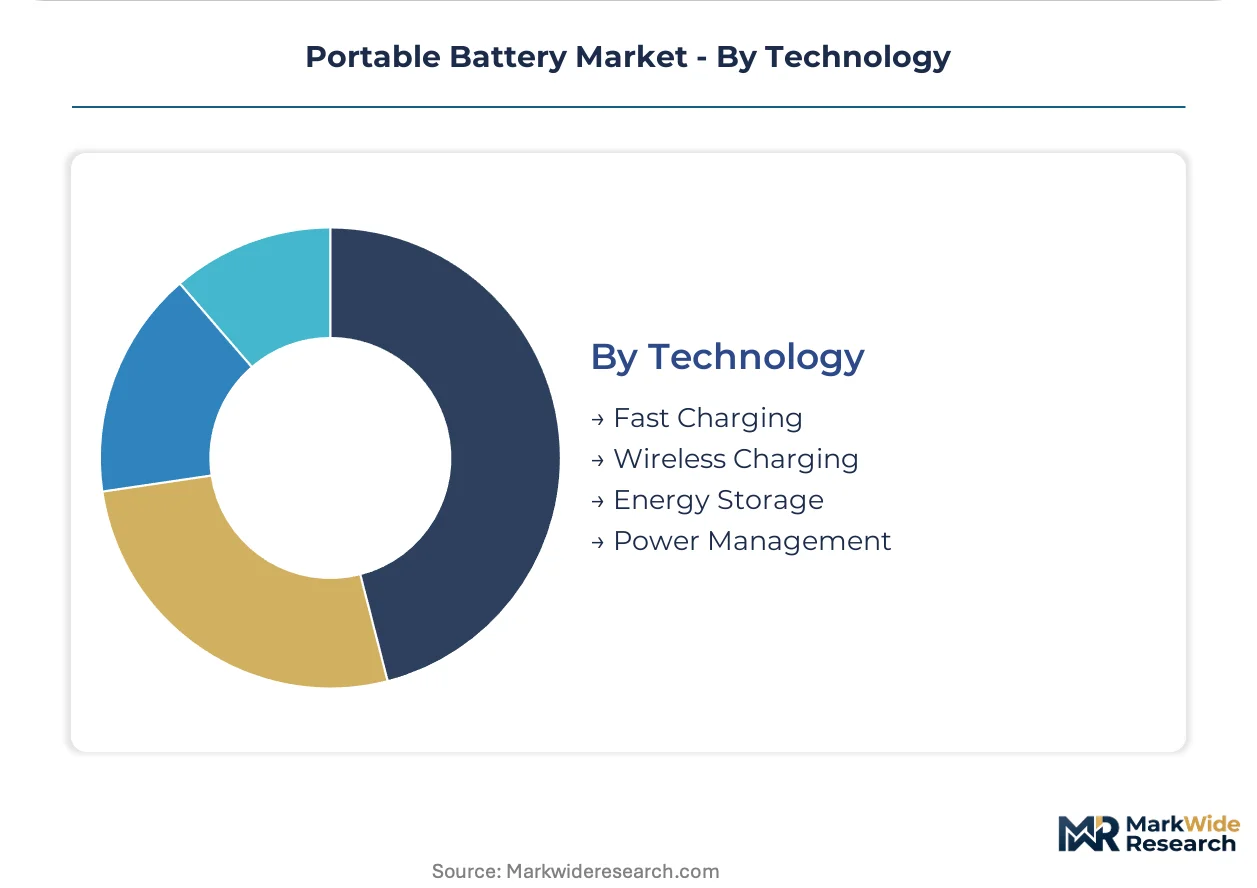
Technology:
Maturity gaps separate proven charging protocols from emerging power management architectures.
- Fast Charging:USB Power Delivery and proprietary protocols above 65W compress recharge cycles for high-capacity units. Gaming laptop manufacturers and mobile workstation vendors in the United States specify 100W+ input capability as standard.
- Power Management:Bidirectional DC-DC converters and adaptive load balancing extend cycle life through intelligent discharge curves. Industrial drone fleet operators in Norway and Switzerland prioritize these features to maximize airframe utilization rates.
- Wireless Charging:Qi and proprietary magnetic alignment systems serve smartphone and earbud accessory markets.
- Energy Storage:Cell balancing and thermal regulation electronics protect against degradation in multi-cell packs.
Fast charging leads adoption breadth; power management is climbing the fastest among enterprise buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's consumer electronics industry pioneered lithium-ion commercialization during the 1990s, establishing manufacturing protocols that East Asian clusters later scaled. Today's portable battery geography reflects this lineage through concentrated production corridors and diverging regulatory frameworks.
China
Cross-border e-commerce platforms drive consumer-grade power bank volumes through Shenzhen manufacturing clusters. SAMR's tightened GB 31241 enforcement mandates third-party testing documentation, elevating compliance costs for smaller marketplace sellers. Shenzhen and Dongguan anchor cylindrical cell production for smartphone accessory channels.
South Korea
High-density format demand from domestic electronics OEMs sustains specialized cell production around Seoul and Gyeonggi Province. MFDS alignment with international safety standards streamlines medical device battery exports. Samsung Electronics and LG Chem anchor vertical integration across cathode material and pack assembly operations.
United States
FAA lithium cargo restrictions above 100 Wh constrain direct-to-consumer fulfillment velocity, elevating last-mile logistics costs for standalone battery shipments. EPA and OSHA frameworks govern industrial-grade portable system deployments in oilfield services and agricultural drone operations. Texas and California concentrate utility procurement for emergency response vehicle fleets.
Germany
Professional cinematography and medical device manufacturers in Bavaria and Baden-Württemberg qualify solid-state units for intermittent charging environments. REACH compliance and EU Battery Regulation recycling mandates accelerate closed-loop supply chain investments. Stuttgart and Munich host qualification laboratories for sulfide electrolyte architectures.
India
PLI scheme incentives for advanced chemistry cell manufacturing attract gigafactory investments targeting domestic electronics and automotive demand. BIS certification requirements for lithium-ion imports create friction for unbranded marketplace sellers. Tamil Nadu and Gujarat emerge as preferred locations for cell-to-pack integration facilities.
Portable Battery Market Vendor Landscape
Premium-margin players sit above commodity-margin players across energy density and certification-grade dimensions, with three distinct tiers visible in procurement patterns. Consolidation pressure operates selectively: cylindrical cell formats commoditize rapidly while solid-state architectures sustain differentiation windows. Three strategic archetypes dominate—vertically integrated electronics conglomerates, specialist direct-to-consumer brands, and industrial-grade chemistry developers. Capacity expansion and regulatory certification capabilities constitute the dominant competitive moves, with in-house testing laboratories becoming table stakes for cross-border marketplace presence.
Within the electronics conglomerate tier, Samsung Electronics and LG Chem Ltd. represent backward-integrated models with captive cathode and cell production. Anker Innovations exemplifies the specialist archetype through compact, travel-certified designs that dominate premium direct-to-consumer channels. BYD Company Limited anchors the industrial-grade segment with proprietary lithium iron phosphate chemistry for heavy-duty portable systems. These three patterns—captive supply chains, certification-forward branding, and chemistry specialization—capture the structural variation across competitive positioning.
| Leading Market Players |
|---|
| Samsung Electronics |
| Anker Innovations |
| Xiaomi Corporation |
| BYD Company Limited |
| Sony Group Corporation |
| Panasonic Holdings Corporation |
| LG Chem Ltd. |
| Energizer Holdings Inc. |
| Belkin International Inc. |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in China and South Korea anchor cathode material supply, compressing procurement costs for integrated pack assemblers while forcing independent brands to absorb spot-market volatility or surrender margin to long-term offtake premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies portable battery procurement, with UN38.3 certification grade and cylindrical versus prismatic cell format serving as the primary price differentiation drivers. Pricing pressure stems from cobalt price volatility and FAA cargo restrictions elevating last-mile logistics costs. Retail consumers exhibit highest price sensitivity, while industrial OEMs prioritize cycle life and thermal stability over unit cost.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Seoul, and Los Angeles orchestrate hub-and-spoke fulfillment patterns for lithium-ion cells and finished packs. Manufacturing concentrates in China, South Korea, and Japan, with raw material dependencies on Chilean lithium, Indonesian nickel, and DRC cobalt. Single-source vulnerability in cathode precursor supply creates structural risk. Distribution runs through cross-border e-commerce platforms and OEM direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play, with India's PLI scheme offering cost advantages against EU Battery Regulation compliance burdens that inflate landed costs for non-certified exporters.
For Market Incumbents: Deepen backward integration into cathode material production to insulate margins from cobalt price volatility and DRC supply concentration risks. Expand in-house UN38.3 testing laboratories to compress certification timelines and defend marketplace presence against SAMR enforcement attrition. Solid-state R&D partnerships represent the critical capability lever for premium segment retention. For New Entrants and Emerging Players: Enter via India's PLI-subsidized gigafactory corridor to exploit domestic electronics demand and avoid EU carbon footprint declaration requirements. Professional cinematography equipment and medical device battery qualification in Germany and Japan offer the most penetrable premium segments. Direct-to-consumer subscription leasing models provide the optimal go-to-market angle for recurring revenue capture. For Investors and Strategic Acquirers: Electronics conglomerates with captive cell production are the most active acquirer in this space, seeking solid-state technology access and certification infrastructure. Long-term viability hinges on chemistry transition timing and recycling mandate compliance capability. Solid-state pilot production scale-up serves as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| GB 31241 Certification Investment | SAMR compliance separates marketplace survivors from seller attrition in cross-border channels. |
| Solid-State Pilot Production Scale-Up | Sulfide electrolyte manufacturing capability unlocks medical device and cinematography premium segments. |
| India PLI Gigafactory Construction | Domestic cell production captures electronics OEM demand while avoiding import duty friction. |
| Closed-Loop Recycling Partnership | EU Battery Regulation passport compliance secures OEM qualification for European industrial buyers. |
| Vehicle-to-Load Product Line Extension | Bidirectional charging compatibility addresses aftermarket demand from electric pickup owners. |
Methodological Framework
Direct dialogue with cell manufacturing executives, regulatory affairs specialists at certification laboratories, procurement managers at industrial drone operators, and cross-border e-commerce platform category managers grounded qualitative findings. Secondary validation drew from SAMR GB standard filings, FAA lithium cargo restriction updates, EU Battery Regulation implementing acts, and UN38.3 testing queue data. Bottom-up cell production capacity estimates and top-down portable power demand aggregation were triangulated to constrain forecast variance.
Segment-level outputs across chemistry type, application intensity, and end-user procurement mode were generated through the projection horizon. CAGRs were derived from installed base replacement cycles, outdoor recreation equipment integration rates, and solid-state commercialization trajectory assumptions. Regional regulatory enforcement timelines and recycling infrastructure buildouts served as scenario-weighting inputs.
Inputs from primary field contacts and published regulatory filings were available through the study window; gaps in solid-state manufacturing yield data and India PLI disbursement schedules introduce uncertainty bands around capacity expansion assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Zinc-Manganese Oxide Batteries Market
Batteries
N-Type Battery Market
Batteries
Battery Diagnostics and Repair Market
Batteries
FORTELION Battery Module Market
Batteries
Floor Scrubber Battery Market
Batteries
Asia-Pacific Industrial Battery Market
Batteries
Grid-Scale Flow Battery Stack Endurance Test Benches Market
Batteries
Stationary Lead-Acid Battery Market
Batteries
United States Household Battery Market
Batteries
Power Battery Sealant Market
Batteries
High Voltage Battery Market
Batteries
Silicon Battery Market
Batteries
Tubular GEL Battery Market
Batteries
Military Battery Packs Market
Batteries
South America Micro Battery Market
Batteries
North America Battery Market