
 Nickel-Metal Hydride (Ni-MH) Battery Market | 2026-2036
Nickel-Metal Hydride (Ni-MH) Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Nickel-Metal Hydride (Ni-MH) Battery Market Insights
Modular battery pack configurations is repositioning procurement patterns across the Ni-MH value chain. Panasonic Holdings Corporation leverages its integrated cell-to-pack manufacturing footprint in Japan to secure long-term hybrid vehicle contracts. Primearth EV Energy Co., Ltd. anchors the Toyota supply ecosystem with dedicated production lines for nickel-metal hydride traction batteries. FDK Corporation specializes in cylindrical cell formats for industrial and medical backup applications, competing outside the automotive mainstream.
A nickel-metal hydride battery stores electrical energy through reversible electrochemical reactions between a hydrogen-absorbing negative electrode, typically a rare-earth alloy such as lanthanum nickel hydride, and a nickel hydroxide positive electrode, with an aqueous potassium hydroxide electrolyte enabling proton transfer during charge and discharge cycles. Rechargeable Cells dominate unit volume due to their ubiquity in consumer electronics and cordless appliances, while Industrial Batteries command stronger margin pools from telecom backup and grid stabilization contracts. Low Self-Discharge technology leads consumer replacement demand, whereas High-Temperature formulations sustain growth in automotive under-hood environments where thermal tolerance determines cell longevity.
Japan's METI enforces battery recycling quotas and carbon footprint disclosure rules that elevate compliance costs for imported cells. The EU Green Deal and REACH chemical restrictions constrain nickel and cobalt sourcing transparency across European supply chains. China's SAMR implements national GB standards for cell safety testing that govern market access for domestic and foreign producers alike. Stakeholders must track regulatory divergence between Asian manufacturing hubs and European end-markets to align certification strategies with diverging compliance timelines.
Market Dynamics
Hybrid powertrain manufacturers face intensifying chemistry selection pressure as lithium-ion cost curves flatten against nickel-metal hydride's established recycling infrastructure and thermal stability advantages in high-temperature automotive environments.
Growth Catalysts
- EU Green Deal battery sustainability mandates:Carbon footprint disclosure rules favor Ni-MH's mature recycling pathways over newer chemistries with opaque supply chains.
- Japan's full hybrid vehicle production:Toyota-affiliated supply chains maintain dedicated Ni-MH capacity for powertrains where cost sensitivity outweighs energy density requirements.
- LaNi5H hydrogen storage alloys:Advanced rare-earth negative electrode formulations extend cycle life in telecom backup applications.
Market Restraints
- Lithium iron phosphate substitution:LFP cells encroach on Ni-MH's cost-sensitive automotive niche with superior energy density metrics.
- Rare-earth supply concentration:Lanthanum and cerium processing capacity clusters in China's Inner Mongolia refining corridor.
- REACH chemical transparency:ECHA nickel compound registration requirements inflate compliance documentation costs for European assemblers.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Domestic manufacturing incentives could localize Ni-MH production for two-wheeler electrification.
- Medical device backup power:Cylindrical cell formats penetrate implantable equipment and portable diagnostic platforms.
- Grid stabilization contracts:Utility-scale frequency regulation applications leverage Ni-MH's rapid charge acceptance and calendar life.
Industry Challenges
- Electrochemical engineering talent scarcity:Experienced KOH electrolyte formulation specialists command premium compensation in Japan's Kansai manufacturing belt.
- GB standard certification timelines:SAMR safety testing protocols delay market entry for imported cell designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nickel-Metal Hydride (Ni-MH) Battery Market |
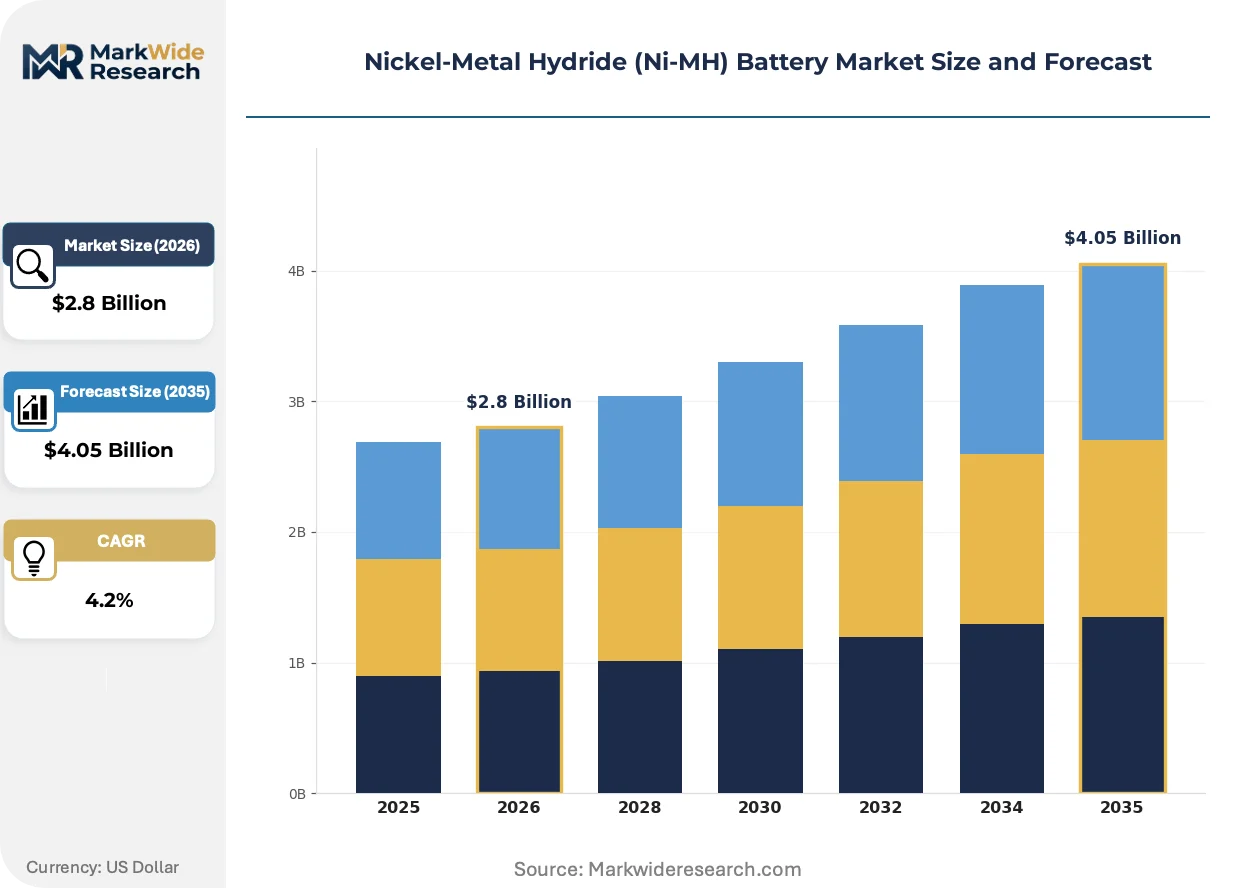
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.05 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rechargeable Cells, Industrial Batteries, Consumer Electronics, Power Tools Application: Electric Vehicles, Renewable Energy Storage, Telecommunication Equipment, Medical Devices End User: Automotive Manufacturers, Electronics Producers, Energy Providers, Healthcare Institutions Technology: Nano-Structured, High-Temperature, Low Self-Discharge, High Capacity |
| Companies Covered | Panasonic Holdings Corporation, Primearth EV Energy Co., Ltd., FDK Corporation, GS Yuasa Corporation, Energizer Holdings, Inc., Duracell Inc., VARTA AG, GP Batteries International Limited, Saft Groupe S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nickel-Metal Hydride (Ni-MH) Battery Market Trends and Innovations
Cell chemistry innovation now prioritizes thermal tolerance and recycling economics over raw energy density, redirecting R&D expenditure toward aqueous electrolyte stability and closed-loop rare-earth recovery systems.
Low self-discharge electrode formulations is electrifying consumer replacement markets by extending shelf life in cordless appliances and emergency lighting systems. Retail distributors in Germany's electronics channels now stock reformulated cells with annual capacity retention above 85 percent. This chemistry is electrifying premium positioning against alkaline disposables in professional tool segments.
Japan's METI battery recycling quotas impose mass-based collection targets on automotive OEMs, forcing reverse logistics investments for end-of-life hybrid packs. Domestic smelters in Akita Prefecture now operate dedicated hydrometallurgical lines for rare-earth recovery. European importers face parallel obligations under EU Green Deal circular economy provisions, compressing margin structures for non-integrated suppliers.
Automotive procurement departments now specify cell-to-pack integration responsibility rather than discrete component sourcing, consolidating contract awards toward vertically capable manufacturers. Tier-1 suppliers in Toyota's supply ecosystem have absorbed final pack assembly functions previously executed by vehicle plants. This concentration is most visible in Japan's Aichi Prefecture industrial corridor, where dedicated Ni-MH lines feed adjacent final assembly operations.
Nickel-Metal Hydride (Ni-MH) Battery Market Segmentation
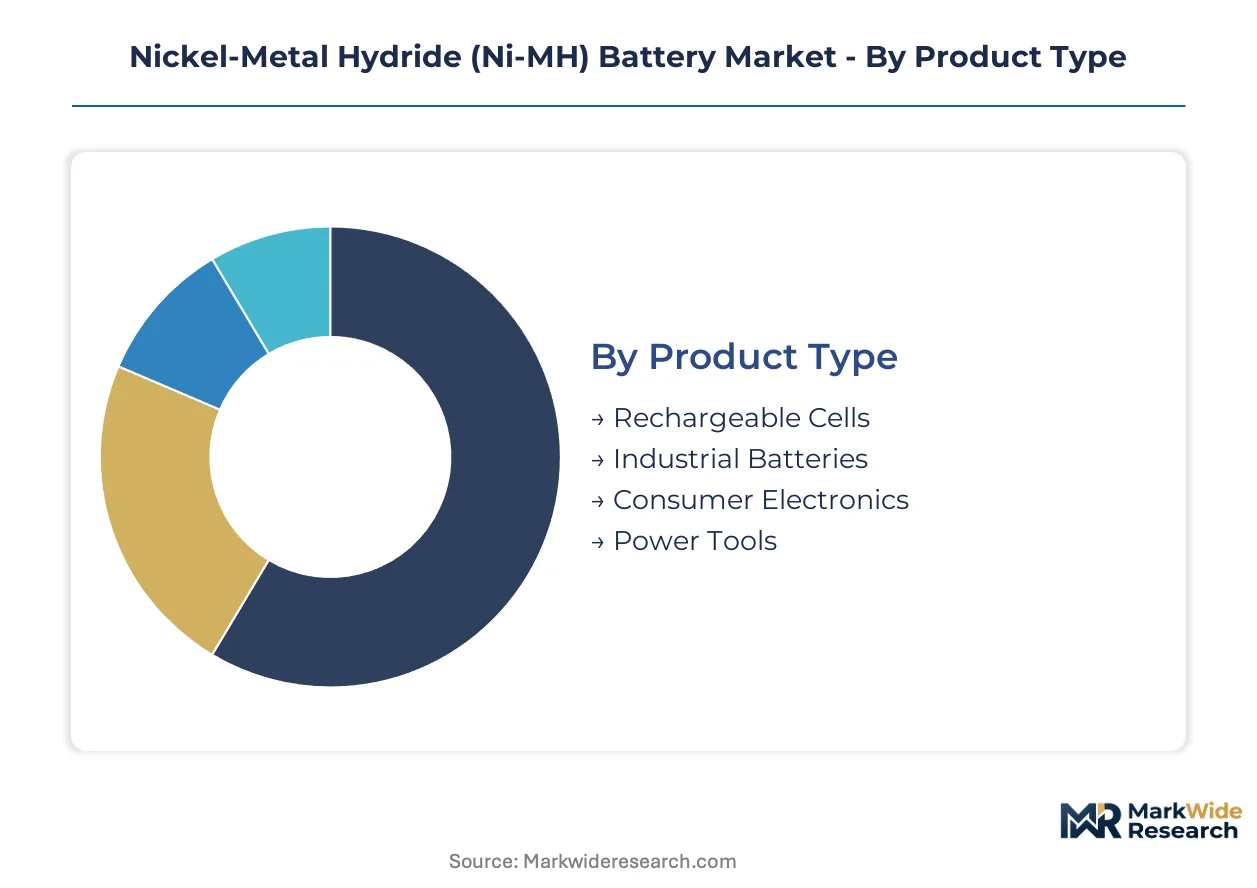
Segmentation in the Ni-MH battery market reveals how chemistry specifications, thermal requirements, and recycling economics fragment procurement decisions across automotive, industrial, and consumer channels. Buyers prioritize fundamentally different performance attributes depending on whether cells serve under-hood powertrains, telecom backup systems, or retail replacement markets.
Product Type:
Volume commitments and margin structures drive procurement negotiations, with automotive contracts demanding multi-year supply guarantees while consumer channels favor spot purchasing flexibility.
- Rechargeable Cells:Standard cylindrical and prismatic formats utilizing nickel hydroxide positive electrodes and hydrogen-absorbing negative electrodes serve cordless appliances, portable electronics, and residential power tools. Japan's consumer electronics manufacturers concentrate procurement in Osaka-based trading houses that manage inventory across retail channels in Germany and the United States.
- Industrial Batteries:Large-format cells and modular packs engineered for extended calendar life and deep discharge cycling anchor telecom backup installations and utility frequency regulation contracts. Energy providers in India and grid operators in Texas specify these configurations for 15-year service intervals where replacement accessibility is constrained.
- Consumer Electronics:Compact cell geometries optimized for device integration density power digital cameras, wireless peripherals, and portable audio equipment. Electronics producers in South Korea and Taiwan source through dedicated distributors serving Shenzhen assembly corridors.
- Power Tools:High-discharge-rate cylindrical cells withstand mechanical vibration and temperature cycling in professional construction environments. German and Japanese tool manufacturers specify these for brushless motor platforms where runtime competes with lithium-ion alternatives.
Industrial Batteries leads on scale; Low Self-Discharge technology within Rechargeable Cells leads on momentum.
Application:
Thermal environment severity and duty cycle intensity determine chemistry selection, with automotive under-hood specifications diverging sharply from climate-controlled medical installations.
- Electric Vehicles:Traction battery packs for full hybrid powertrains leverage Ni-MH's thermal stability and established recycling infrastructure against lithium-ion energy density advantages. Toyota-affiliated supply chains in Aichi Prefecture maintain dedicated production lines where cost sensitivity outweighs specific energy requirements for urban hybrid architectures.
- Renewable Energy Storage:Grid-connected battery systems buffer intermittency from solar and wind generation through rapid charge acceptance and extended cycle durability. Utility procurement departments in California and Gujarat specify these for frequency regulation contracts where calendar life exceeds energy density priorities.
- Telecommunication Equipment:Backup power systems for cellular base stations and data centers require 10-20 year operational lifespans with minimal maintenance access. Tower operators in Indonesia and Nigeria deploy these in remote installations where battery replacement logistics are prohibitively expensive.
- Medical Devices:Implantable and portable diagnostic equipment demands exceptional reliability and biocompatibility certification. Healthcare institutions in Switzerland and Japan specify cylindrical formats for patient-worn monitors and surgical instruments where failure tolerance is near-zero.
Electric Vehicles commands the largest committed volume; Renewable Energy Storage is climbing the fastest as grid stabilization contracts multiply.
End User:
Integration depth requirements separate buyers seeking discrete cells from those demanding complete pack assembly with thermal management and battery management systems.
- Automotive Manufacturers:Full hybrid vehicle programs specify cell-to-pack integration responsibility, consolidating awards toward vertically capable suppliers. Procurement departments at Toyota and affiliated OEMs in Japan's automotive corridor now require final pack assembly functions that vehicle plants previously executed.
- Electronics Producers:Consumer device assemblers source standard cell formats through distribution channels with minimal technical integration support. Contract manufacturers in Dongguan and Penang manage inventory across multiple chemistry specifications for seasonal product launches.
- Energy Providers:Utility and independent power producers negotiate long-term service contracts incorporating performance guarantees and end-of-life recycling obligations. State-owned grid operators in China and regulated utilities in Germany impose mass-based collection targets under METI and EU Green Deal circular economy provisions.
- Healthcare Institutions:Hospital systems and device OEMs demand batch traceability, sterilization compatibility, and regulatory documentation exceeding standard industrial specifications. Procurement teams at university medical centers in Boston and Tokyo specify these for implantable and life-support applications.
Automotive Manufacturers dominates absolute consumption; Healthcare Institutions delivers the steepest expansion trajectory as portable diagnostic platforms proliferate.
Technology:
Electrode formulation and electrolyte engineering differentiate performance tiers, with R&D expenditure redirecting toward thermal tolerance and rare-earth recovery economics rather than raw energy density.
- Nano-Structured:Advanced electrode architectures utilizing refined particle distributions enhance surface area and reaction kinetics for high-rate applications. Research programs at Japanese national laboratories and South Korean battery institutes focus on these formulations for next-generation hybrid powertrains.
- High-Temperature:Modified electrolyte compositions and separator materials sustain performance in automotive engine compartments exceeding 60°C ambient. These formulations penetrate under-hood applications in India's two-wheeler electrification programs and Middle Eastern automotive assembly where thermal management hardware adds unacceptable cost.
- Low Self-Discharge:Hydrogen-absorbing alloy modifications and separator treatments reduce standby capacity loss below 15 percent annually. Retail channels in Germany and Japan stock these for emergency lighting, cordless appliances, and professional tools where shelf life determines replacement economics.
- High Capacity:Optimized active material loading and cell construction maximize volumetric energy density for space-constrained applications. Consumer electronics producers specify these for digital cameras and wireless audio where runtime extension justifies premium positioning.
Low Self-Discharge leads on commercialized volume; High-Temperature is gaining share fastest as automotive thermal specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered commercial Ni-MH battery manufacturing during the 1990s hybrid vehicle revolution, establishing production corridors that now supply Toyota's global hybrid powertrain programs. This historical foundation created specialized rare-earth alloy processing capabilities and closed-loop recycling infrastructure that subsequent manufacturing regions have struggled to replicate.
Japan
Full hybrid vehicle production at Toyota Motor Corporation's Takaoka and Tsutsumi plants sustains dedicated Ni-MH procurement from Aichi Prefecture suppliers. METI enforces battery recycling quotas and carbon footprint disclosure rules that elevate compliance costs for imported cells. Domestic smelters in Akita Prefecture operate hydrometallurgical lines for rare-earth recovery from end-of-life automotive packs.
China
Inner Mongolia's rare-earth refining corridor concentrates lanthanum and cerium processing capacity for negative electrode alloys. SAMR implements national GB standards for cell safety testing that govern market access for domestic and foreign producers alike. BYD and domestic hybrid manufacturers in Shenzhen source Ni-MH cells for cost-sensitive two-wheeler electrification programs.
Germany
Automotive suppliers in Baden-Württemberg specify Ni-MH backup systems for industrial equipment where thermal stability outweighs energy density requirements. ECHA nickel compound registration under REACH inflates compliance documentation costs for European assemblers. VARTA's manufacturing presence in Ellwangen anchors domestic production for medical device and power tool applications.
United States
Grid operators in Texas and California specify Ni-MH configurations for utility-scale frequency regulation contracts where calendar life exceeds energy density priorities. EPA hazardous waste regulations govern spent battery collection and smelter emissions from recycling operations. Industrial battery distributors in Chicago and Dallas manage inventory for telecom backup installations across the Midwest and Southwest.
India
Two-wheeler electrification programs in Maharashtra and Tamil Nadu create procurement demand for cost-sensitive powertrain configurations. The PLI scheme for advanced chemistry cells could localize Ni-MH production if domestic manufacturers qualify for manufacturing incentives. State-owned grid operators impose performance guarantees on battery suppliers for rural telecom backup installations.
Nickel-Metal Hydride (Ni-MH) Battery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integration depth, with cell-to-pack capability commanding contract preference from automotive OEMs. The supplier base stratifies into three tiers: vertically integrated Japanese manufacturers with captive rare-earth supply, European specialists in cylindrical formats for industrial niches, and Asian trading houses managing spot-market consumer cell distribution. Consolidation pressure intensifies as procurement departments consolidate awards toward suppliers with in-house electrode production and pack assembly functions. Two dominant competitive moves define current positioning: backward integration into rare-earth alloy processing and geographic expansion through joint ventures in India's emerging manufacturing corridor.
Within the integrated-manufacturer tier, Panasonic Holdings Corporation and Primearth EV Energy Co., Ltd. exemplify the Japanese model of captive supply chains serving dedicated automotive programs. FDK Corporation occupies a position among specialists in cylindrical cell formats, representing the industrial-application archetype outside automotive mainstream procurement. These three companies anchor the competitive structure through their respective archetypes: full integration for hybrid powertrains, Toyota-affiliated ecosystem concentration, and format-specific industrial positioning.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| Primearth EV Energy Co., Ltd. |
| FDK Corporation |
| GS Yuasa Corporation |
| Energizer Holdings, Inc. |
| Duracell Inc. |
| VARTA AG |
| GP Batteries International Limited |
| Saft Groupe S.A. |
| Others |
Pricing and Supply Chain Analysis
Performance-grade bifurcation between automotive cell-to-pack contracts and consumer spot-market cells manifests in divergent margin structures and procurement cadences across the Ni-MH value chain. METI recycling quotas and REACH nickel compound registration requirements inflate compliance costs for European and Japanese automotive buyers, while distribution channels in Germany and the United States absorb spot-price volatility for standard cylindrical formats.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors contract negotiations, with automotive cell-to-pack integration commanding premium positioning against commodity cylindrical cells. Price differentiation rests on thermal tolerance certification and rare-earth alloy purity grades, with high-temperature formulations for under-hood applications sustaining margin premiums. Cost compression in consumer rechargeable cells is intensifying because LFP substitution erodes energy-density-compromised segments. Electronics producers in Shenzhen assembly corridors exhibit highest price sensitivity, while Toyota-affiliated procurement departments prioritize supply security over unit cost.
Supply Chain Analysis
Freight cost escalation from Inner Mongolia's rare-earth refining corridor to Aichi Prefecture cell plants compresses margins for non-integrated alloy suppliers. Supply concentrates in Japan, China, and Germany, with lanthanum nickel hydride alloys, potassium hydroxide electrolyte, and separator membranes forming critical input dependencies. Single-source vulnerability in cerium processing capacity creates exposure to China's environmental enforcement actions. Distribution runs through dedicated automotive supply corridors in Aichi Prefecture and spot-market electronics distributors in Osaka and Chicago.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in thermal-tolerance premium tiers and closed-loop rare-earth recovery systems, with EU Green Deal circular economy provisions accelerating value capture from end-of-life pack processing.
For Market Incumbents: Anticipate lithium iron phosphate encroachment by deepening backward integration into rare-earth alloy processing and securing long-term offtake agreements with Akita Prefecture hydrometallurgical facilities. Absorb final pack assembly functions previously executed by vehicle plants to defend contract preference from Toyota-affiliated procurement departments. For New Entrants and Emerging Players: Begin with India's two-wheeler electrification corridor under PLI scheme manufacturing incentives, where cost-sensitive powertrain configurations favor Ni-MH thermal stability over lithium-ion energy density. Target medical device backup power applications in Switzerland and Japan, where cylindrical format specialization and biocompatibility certification create defensible positioning against integrated automotive suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where cell-to-pack capability gaps exclude non-integrated suppliers from automotive contract awards. Five-to-ten-year viability hinges on rare-earth recovery economics rather than raw cell production scale. Monitor ECHA nickel compound registration compliance cost trajectories as inflection indicator for European assembler margin compression and acquisition target availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Alloys | Captive lanthanum nickel hydride supply secures automotive contract preference against spot-market dependent competitors. |
| Cell-to-Pack Manufacturing Scale-Up | Vertically capable suppliers absorb final assembly functions previously executed at Toyota vehicle plants in Aichi Prefecture. |
| Closed-Loop Recycling Infrastructure | Akita Prefecture hydrometallurgical lines recover rare-earth content from end-of-life hybrid packs under METI quotas. |
| High-Temperature Formulation R&D | Modified electrolyte compositions penetrate Indian two-wheeler and Middle Eastern automotive under-hood specifications. |
| Medical Device Certification Pathway | Biocompatibility documentation opens implantable equipment and portable diagnostic platforms in Swiss and Japanese healthcare institutions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with automotive procurement directors, rare-earth alloy plant managers, telecom backup system engineers, and medical device regulatory affairs specialists with secondary validation. Customs records, METI battery production statistics, ECHA registration databases, and SEC filings from listed battery manufacturers anchored supply-side estimates. Bottom-up cell production tallies and top-down hybrid vehicle deployment projections were cross-referenced for triangulation.
Comparable-period anchoring utilized historical production data across the analysis window to calibrate projection models. Segmentation dimensions included product format, application thermal environment, end-user integration depth, and electrode technology tier. CAGRs were derived from slope analysis of normalized production trajectories, incorporating rare-earth price index movements and automotive platform electrification roadmaps as industry-specific inputs.
Caveats apply where lithium iron phosphate cost curves, China's environmental enforcement actions in Inner Mongolia, or EU Green Deal carbon footprint disclosure timeline acceleration could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Thin Film and Printed Battery Market
Batteries
Hybrid Flow Battery Market
Batteries
Global Bio Compatible Battery Market
Batteries
Primary Battery Market
Batteries
South and Central America Battery Market
Batteries
West Africa Battery Market
Batteries
Europe Consumer Battery Market
Batteries
Solid-State Battery Mechanical and Safety Test Equipment Market
Batteries
Automotive Start-Stop Battery Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Industrial Backup Battery Market
Batteries
Potassium-Ion Battery Market
Batteries
Romania Rechargeable Battery Market
Batteries
Home Inverter Battery Market
Batteries
North America Industrial Battery Market
Batteries
Europe Lead-Acid Battery Market