
 US Solar Battery Market | 2026-2036
US Solar Battery Market Size, Share, and Industry Trends Forecast 2026-2036
US Solar Battery Market Insights
Subscription-based energy management software is broadening what solar battery vendors monetize beyond hardware sales. Tesla leverages its virtual power plant software to aggregate residential storage into grid services. Sunrun sustains market presence through leased battery offerings that reduce upfront homeowner capital. Enphase Energy differentiates with microinverter-integrated storage systems that simplify installation workflows.
A solar battery stores electrical energy generated by photovoltaic systems for later discharge, typically employing lithium iron phosphate or nickel manganese cobalt cathodes with capacities ranging from 5 kWh residential units to multi-megawatt containerized arrays. Its primary commercial purpose is to shift solar generation to evening peak demand periods and provide grid stabilization services. Lithium-ion chemistry dominates installed capacity due to declining cell costs and established manufacturing scale, while flow batteries occupy emerging utility-scale durations exceeding eight hours. The residential use case leads unit shipments, though utility-scale deployments capture the largest revenue pools per project.
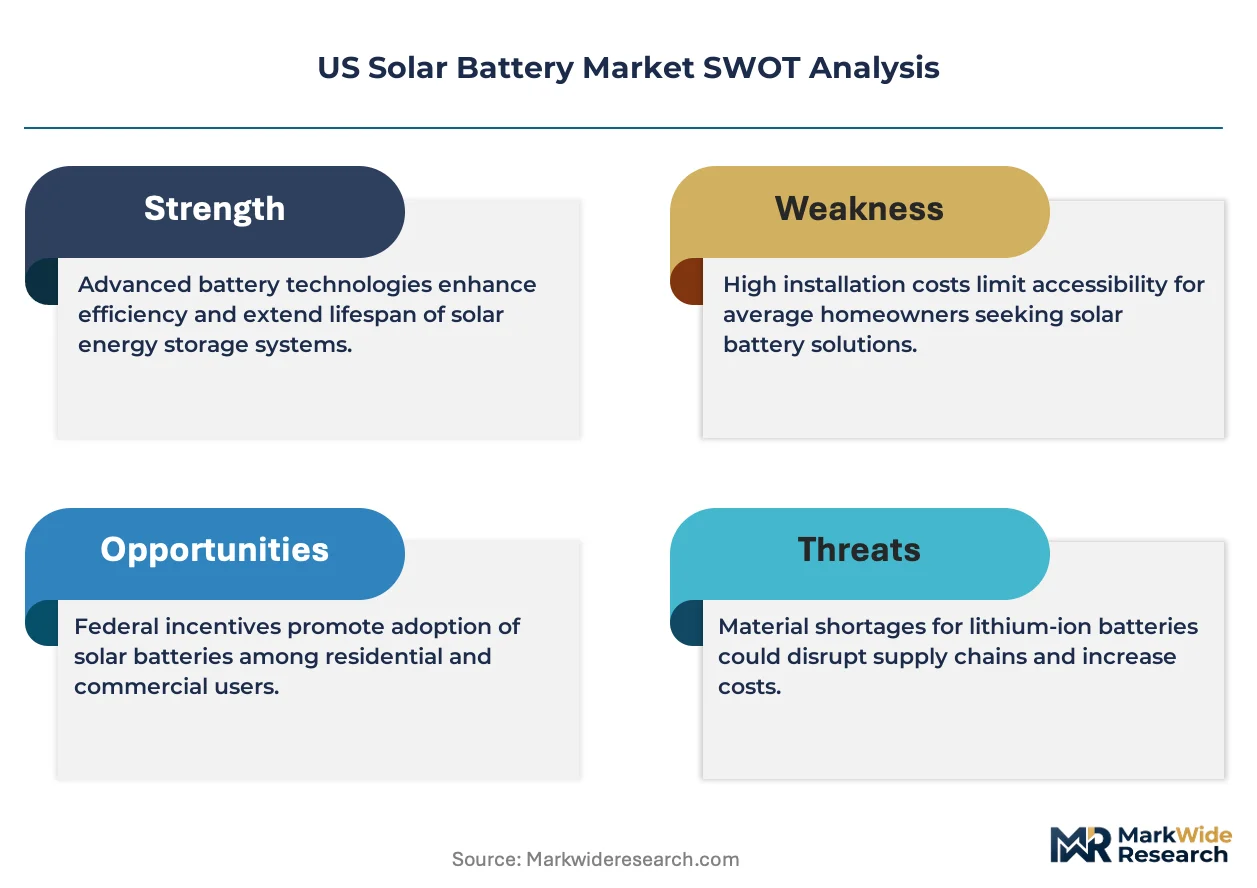
The Federal Energy Regulatory Commission Order 2222 enables distributed storage participation in wholesale markets, while the Inflation Reduction Act investment tax credits directly reduce battery system costs for residential and commercial buyers. California's Self-Generation Incentive Program and Texas ERCOT market rules further shape regional deployment economics by compensating storage for capacity and ancillary services. Stakeholders must monitor interconnection queue reforms and state-level net metering revisions that determine behind-the-meter storage payback periods.
Market Dynamics
The Inflation Reduction Act storage tax credits have fundamentally restructured residential purchase economics, shifting buyer calculus from payback-period arithmetic toward total-cost-of-ownership optimization and accelerating utility-scale hybrid deployment timelines.
Growth Catalysts
- Inflation Reduction Act Investment Tax Credits:Direct cost reductions for residential and commercial battery systems compress payback periods below seven years in high-irradiance zones.
- California Self-Generation Incentive Program:Behind-the-meter storage installations receive capacity-based rebates that stack with federal incentives, driving deployment density in the state's major metropolitan clusters.
- Lithium Iron Phosphate Chemistry:Improved thermal stability and extended cycle life relative to nickel manganese cobalt variants reduce operational risk for utility-scale operators.
Market Restraints
- Lithium Carbonate Price Volatility:Cathode material input costs fluctuate with South American brine extraction volumes and Australian spodumene concentrate spot markets.
- China-Dominated Cell Manufacturing:Over 70 percent of global lithium-ion production capacity concentrates in Chinese gigafactories, creating geopolitical exposure for US project developers.
- Eight-Hour Duration Limitation:Lithium-ion economics degrade beyond diurnal cycling, leaving multi-day seasonal storage applications to nascent flow battery alternatives with unproven scale.
Strategic Opportunities
- Texas ERCOT Ancillary Services Market:Fast-frequency response compensation mechanisms reward distributed storage participation with revenue streams independent of energy arbitrage.
- Virtual Power Plant Aggregation Software:Residential battery fleets monetize grid services through automated dispatch platforms that aggregate kilowatt-scale assets into megawatt-scale bidding blocks.
- Solar-Plus-Storage Hybrids:Co-located DC-coupled architectures reduce balance-of-system costs and interconnection queue delays for utility-scale developers in the Southwest.
Industry Challenges
- Interconnection Queue Reform Delays:Federal Energy Regulatory Commission Order 2023 reforms face implementation friction at regional transmission organizations, extending project energization timelines.
- Net Metering Revision Uncertainty:California NEM 3.0 tariff restructuring reduces export compensation rates, forcing storage vendors to recalculate value-stacking strategies for new installations.
- Certification Timeline Compression:UL 9540A fire safety testing protocols require 12-18 month validation cycles that lag behind product iteration speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Solar Battery Market |
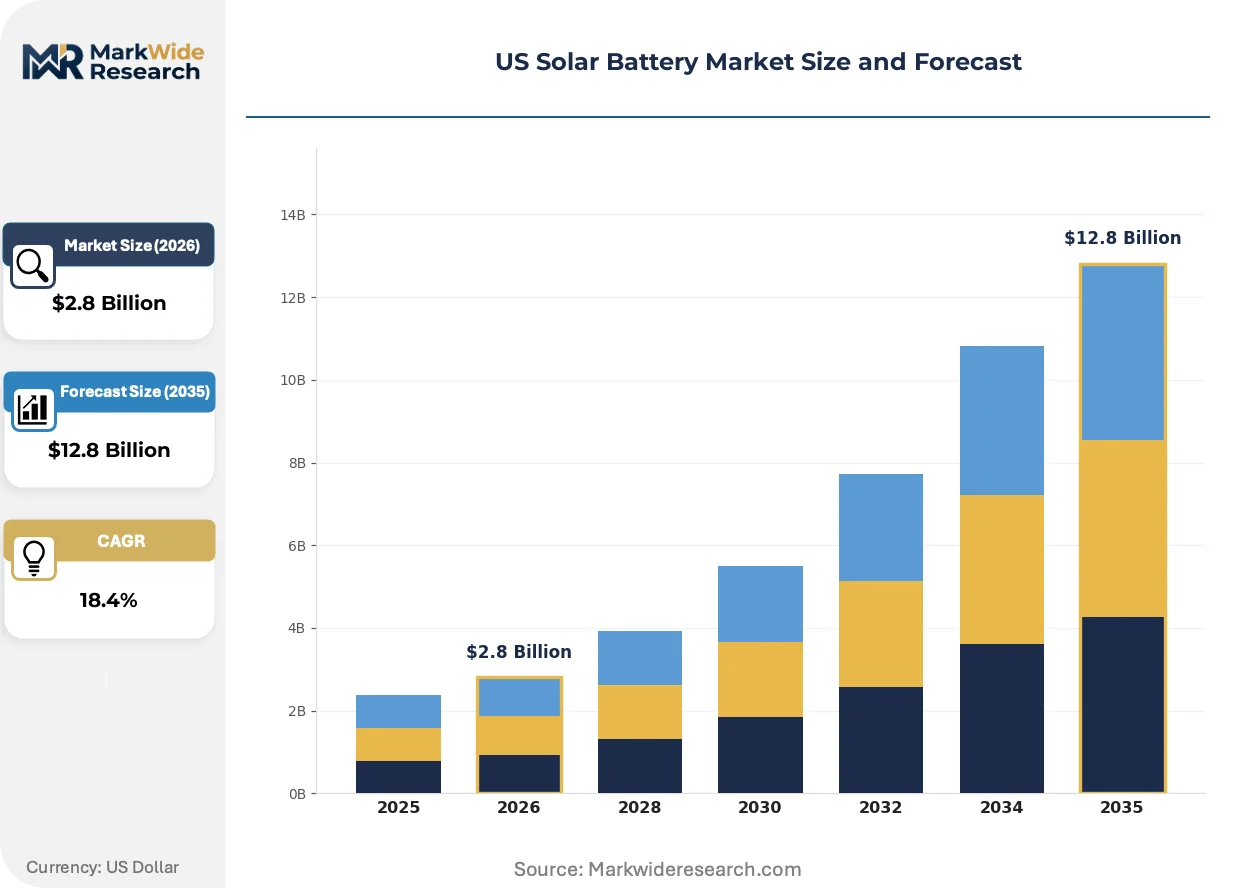
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Flow Batteries, Nickel-based Use Case: Residential, Commercial, Industrial, Utility-scale Installation: On-grid, Off-grid, Hybrid, Portable End User: Homeowners, Businesses, Energy Providers, Installers |
| Companies Covered | Tesla, Sunrun, Enphase Energy, LG Energy Solution, SunPower, ESS Inc., Powin Energy, GSL Energy, Form Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Solar Battery Market Trends and Innovations
Software-defined energy architectures are displacing hardware-centric business models, with vendors competing on dispatch algorithms and grid-integration capabilities rather than cell chemistry specifications alone.
Containerized battery storage systems with integrated power conversion and thermal management are decentralizing project development by enabling modular deployment at substations and industrial load centers. Rural electric cooperatives in the Mountain West adopt these skid-mounted units to defer transmission upgrades. Standardized 20-foot and 40-foot form factors compress engineering procurement construction timelines from 24 months to under 12.
FERC Order 2222 implementation across ISO New England and PJM Interconnection is forcing distribution utilities to develop technical standards for distributed energy resource aggregation. Wholesale market participation rules now recognize storage as a distinct asset class eligible for capacity and ancillary service payments. Commercial and industrial facility managers in the Mid-Atlantic redesign on-site solar configurations to capture these revenue streams.
Subscription-based service models are displacing outright equipment ownership among credit-constrained residential segments. Third-party ownership structures bundle hardware, installation, and maintenance into fixed monthly payments that improve household budget predictability. Arizona and Nevada markets show the strongest uptake where high cooling loads coincide with time-of-use rate structures that reward evening discharge.
US Solar Battery Market Segmentation
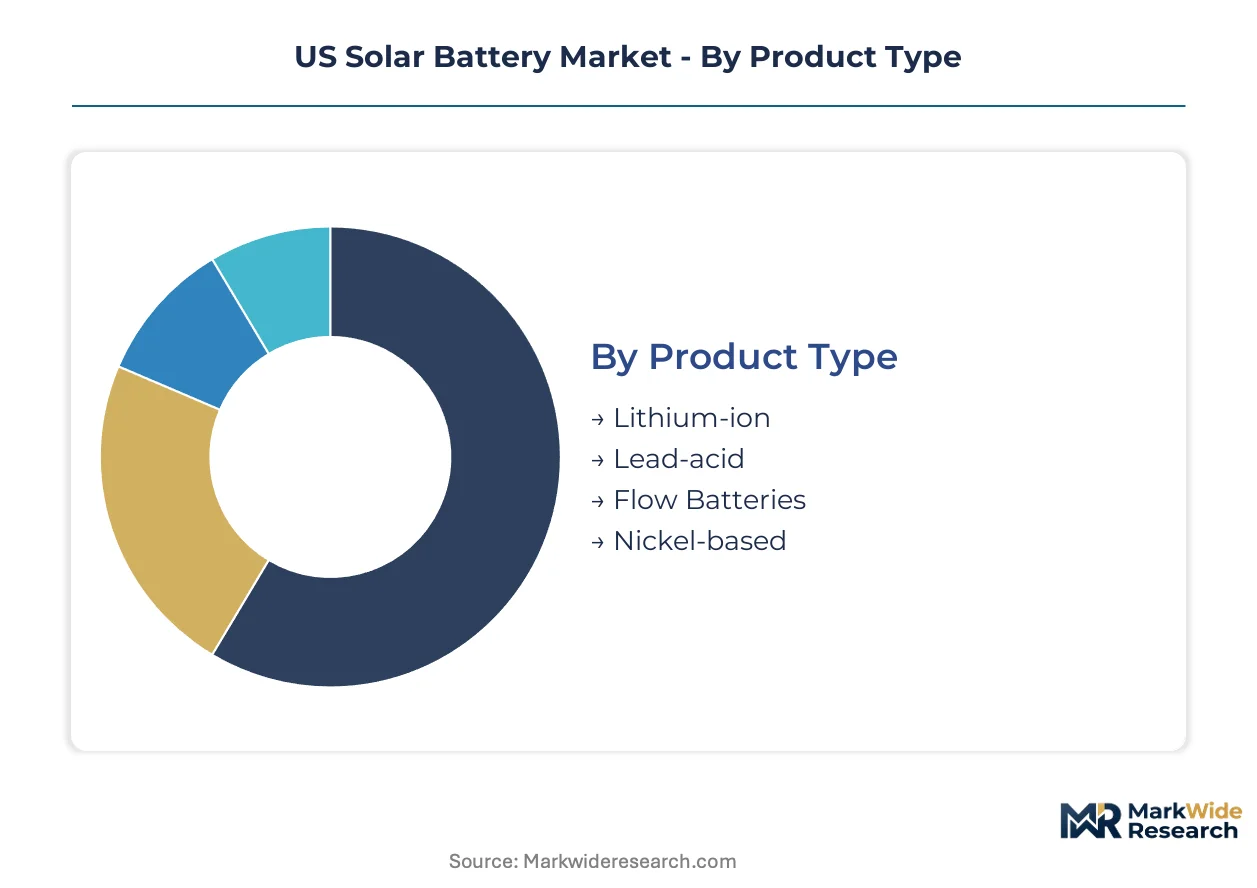
US Solar Battery Market segmentation reveals distinct buyer priorities across chemistry types, deployment scales, and grid-integration strategies. Each dimension shapes procurement criteria, installation workflows, and long-term value capture for vendors and purchasers alike.
Product Type:
Chemistry selection hinges on cycle life requirements, thermal safety thresholds, and supply chain proximity to domestic cell manufacturing.
- Lithium-ion:Lithium iron phosphate and nickel manganese cobalt cathodes deliver 4,000-8,000 cycle lifespans with 90% round-trip efficiency. Demand clusters in California and Texas utility-scale hybrids where FERC Order 2222 enables wholesale market participation and IRA tax credits compress project economics.
- Flow Batteries:Vanadium redox and zinc-bromine systems achieve 8-12 hour discharge durations without capacity degradation. Southwest utility developers evaluate these for seasonal shifting applications where lithium-ion economics degrade beyond diurnal cycling, though manufacturing scale remains limited.
- Lead-acid:Mature recycling infrastructure and low upfront capital sustain niche off-grid rural electrification in Mountain West states with limited interconnection access.
- Nickel-based:Nickel-cadmium and nickel-metal hydride chemistries occupy legacy industrial backup power installations with extreme temperature tolerance requirements.
Lithium-ion leads volumes today; flow batteries are gaining share fastest in utility-scale durations exceeding eight hours.
Use Case:
Scale of deployment determines balance-of-system complexity, software integration depth, and available revenue stacking opportunities.
- Residential:5-20 kWh wall-mounted or ground-mounted units paired with rooftop solar dominate unit shipments. California NEM 3.0 tariff restructuring forces vendors toward self-consumption optimization and virtual power plant aggregation to maintain payback periods below ten years.
- Utility-scale:Containerized multi-megawatt arrays co-located with solar farms capture the largest revenue pools per project. ERCOT fast-frequency response markets and Southwest irradiance profiles accelerate deployment timelines for solar-plus-storage hybrids seeking IRA investment tax credits.
- Commercial:100 kWh-2 MWh behind-the-meter systems target demand charge reduction and resilience for retail, healthcare, and data center loads in Texas and Arizona time-of-use markets.
- Industrial:Heavy manufacturing and cold storage facilities deploy 2-10 MWh systems for process continuity and wholesale market arbitrage participation.
Utility-scale captures dominant revenue per installation; residential unit shipments expand most rapidly with third-party ownership structures.
Installation:
Grid connection status defines regulatory jurisdiction, interconnection queue position, and available compensation mechanisms for stored energy.
- On-grid:Net-metered or time-of-use rate structures in California, Arizona, and Nevada reward evening discharge and grid services participation. FERC Order 2222 implementation across ISO territories enables aggregated distributed storage bidding into capacity and ancillary service markets.
- Hybrid:DC-coupled solar-plus-storage architectures reduce inverter costs and interconnection complexity for utility-scale Southwest developers facing 24-month queue delays.
- Off-grid:Rural electric cooperatives in Montana and Wyoming deploy skid-mounted systems to defer transmission infrastructure upgrades in low-load-density territories.
- Portable:Mobile battery trailers serve construction, emergency response, and temporary event power in Texas oilfield and disaster recovery applications.
On-grid installations dominate installed capacity; hybrid configurations are climbing the fastest as developers prioritize interconnection efficiency.
End User:
Decision-making authority and capital availability fragment across direct purchasers, intermediaries, and ratepayer-funded procurement.
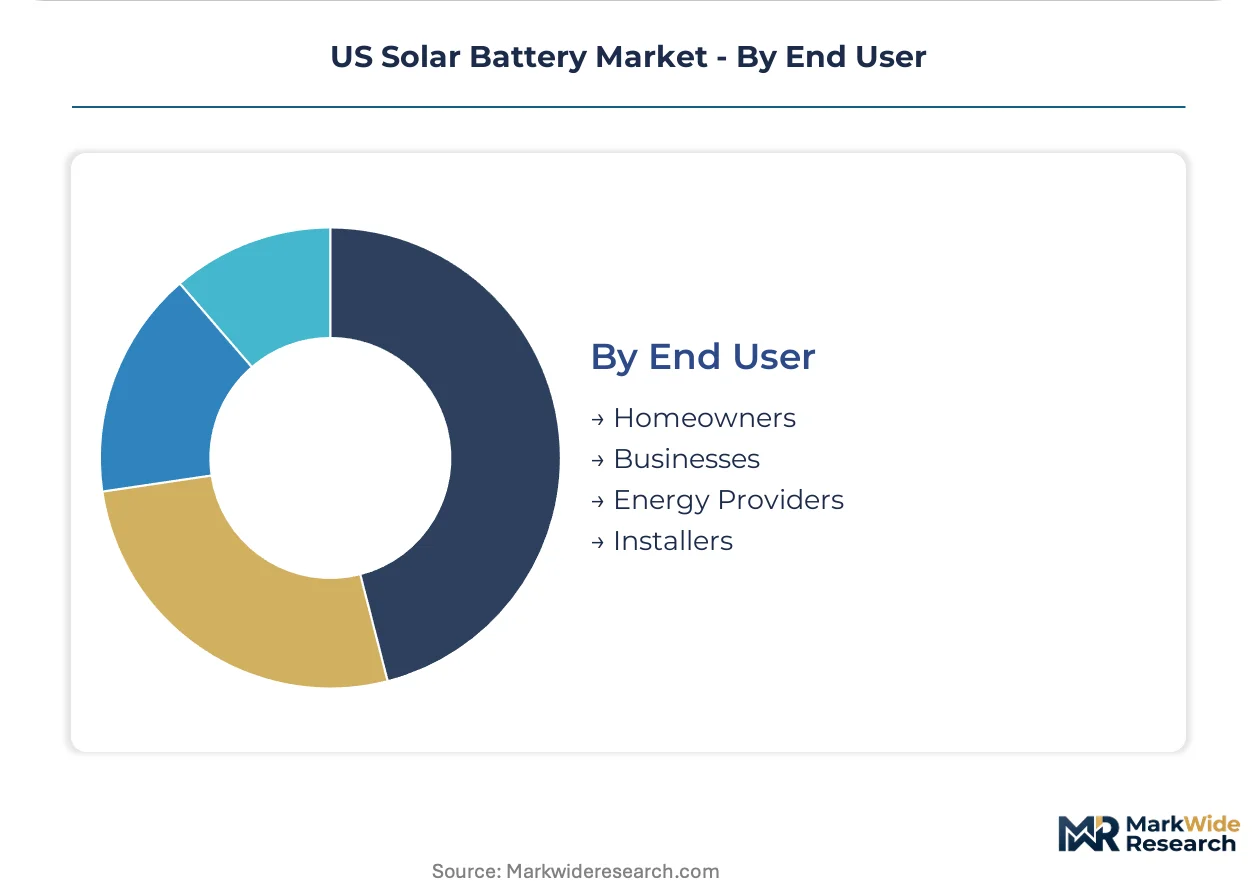
- Homeowners:Credit-constrained households in Arizona and Nevada favor leased battery offerings with fixed monthly payments over outright ownership. Subscription-based energy management software bundles hardware, installation, and maintenance into predictable budget lines.
- Energy Providers:Investor-owned utilities and rural electric cooperatives procure containerized systems for resource adequacy, transmission deferral, and renewable integration mandates under state renewable portfolio standards.
- Businesses:Commercial facility managers redesign on-site solar configurations to capture FERC Order 2222 wholesale market revenue streams in PJM Interconnection and ISO New England territories.
- Installers:Regional electrical contractors and national solar integrators specify microinverter-integrated storage systems to compress labor hours and reduce commissioning complexity.
Energy providers lead procurement volumes today; homeowners are expanding most quickly with third-party ownership and virtual power plant enrollment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage across state jurisdictions is redistributing solar battery deployment toward regions with stacked incentive structures and streamlined interconnection procedures. Production economics favor states where federal IRA credits layer atop state-level rebates and wholesale market participation rules.
California
Residential self-consumption mandates and NEM 3.0 tariff restructuring accelerate behind-the-meter storage adoption in the Los Angeles Basin and Central Valley. The California Self-Generation Incentive Program provides capacity-based rebates that stack with federal investment tax credits. Bay Area technology firms and San Diego solar installers dominate virtual power plant aggregation enrollment.
Texas
ERCOT's fast-frequency response markets compensate distributed storage for grid stabilization services independent of energy arbitrage. The absence of statewide net metering rules shifts competitive focus toward wholesale market participation and resilience value propositions. Houston and Dallas-Fort Worth metro areas concentrate commercial and industrial deployments targeting demand charge reduction.
Arizona
Time-of-use rate structures with steep evening peaks drive residential battery economics in Phoenix and Tucson metropolitan clusters. Arizona Public Service and Tucson Electric Power interconnection standards favor solar-plus-storage hybrid configurations. Third-party ownership models show strongest uptake among credit-constrained households facing high summer cooling loads.
Nevada
Nevada Energy's revised net metering tariffs and battery incentive programs reshape deployment patterns in Las Vegas and Reno corridors. Desert Southwest irradiance profiles compress solar-plus-storage payback periods below competing markets. Industrial cold storage and data center loads in Clark County drive megawatt-scale behind-the-meter procurement.
Florida
Hurricane resilience requirements and storm outage frequency accelerate residential storage adoption in Miami-Dade and Tampa Bay metropolitan areas. Florida Power and Light interconnection queue reforms lag national standards, favoring third-party aggregators over direct homeowner installations. Orlando and Jacksonville commercial facilities target backup power and demand response revenue streams.
US Solar Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated hardware-software platforms commanding premium positioning in residential markets while project developers source containerized systems from Asian cell suppliers. Market structure concentrates around three strategic archetypes: integrated energy platform operators, dedicated storage technology vendors, and utility-scale engineering procurement construction contractors. Dominant competitive moves include strategic partnerships between software aggregators and hardware OEMs, plus capacity expansion into domestic cell manufacturing to mitigate supply chain exposure.
Within the integrated platform tier, Tesla and Sunrun exemplify divergent approaches to residential market capture, with the former leveraging virtual power plant software aggregation and the latter sustaining presence through leased ownership structures. Enphase Energy occupies a position among microinverter-integrated storage specialists that compress installation labor requirements. These three anchors illustrate how vendor strategies bifurcate between hardware-centric scale plays and service-oriented recurring revenue models.
| Leading Market Players |
|---|
| Tesla |
| Sunrun |
| Enphase Energy |
| LG Energy Solution |
| SunPower |
| ESS Inc. |
| Powin Energy |
| GSL Energy |
| Form Energy |
| Others |
Pricing and Supply Chain Analysis
Utility-scale procurement preferences for containerized DC-coupled systems are compressing supplier margins while rewarding vendors with captive cell production. This demand-side specification shift forces supply chain reconfiguration toward modular manufacturing footprints and accelerates price competition in standardized product tiers.
Pricing Analysis
Distributor margins in residential channels absorb 15-25 point markups before installer layering, while direct-to-utility EPC contracts trade volume discounts against extended payment terms. Three-tier pricing structure across premium, standard, and economy levels separates Tesla-Sunrun integrated platforms from regional installer white-label offerings and commodity containerized arrays. Cost compression in lithium iron phosphate cells is intensifying because Chinese cathode material spot markets softened, though tariff exposure on finished packs limits downside. Credit-constrained homeowners in Arizona and Nevada show highest price sensitivity, while Texas commercial buyers prioritize dispatch software capabilities over per-kWh capital cost.
Supply Chain Analysis
Trans-Pacific container rates from Shanghai to Long Beach directly impact landed costs for Korean and Chinese cell suppliers serving Southwest utility projects. Cell manufacturing concentrates in China, South Korea, and Japan, with US pack assembly drawing from Mexican and Canadian component hubs to qualify for IRA domestic content bonuses. Lithium carbonate from Chilean brine operations and Australian spodumene concentrate feed cathode production, while copper busbar and power electronics hinge on Taiwanese semiconductor foundries. Single-source vulnerability in Chinese graphite anode supply creates geopolitical exposure for project developers. Distribution runs through national EPC contractors for utility-scale deployments and regional solar integrators for residential channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on IRA tax credit monetization efficiency and the shift toward software-recurring revenue models that decouple vendor economics from hardware-only transactions.
For Market Incumbents: Lock in long-term offtake agreements with Southwest utility developers before FERC Order 2023 interconnection reforms accelerate project timelines. Secure captive lithium supply through offtake contracts with Australian spodumene miners to insulate against Chinese cell manufacturer pricing power. Prioritize UL 9540A certification investment to compress product validation cycles below 12 months.
For New Entrants and Emerging Players: Launch via virtual power plant software platforms that aggregate residential fleets into ERCOT ancillary service bidding blocks. Target Arizona and Nevada third-party ownership segments where high cooling loads and time-of-use rates create immediate value stacking opportunities. Pursue white-label partnerships with regional installers lacking in-house storage engineering capabilities.
For Investors and Strategic Acquirers: Asymmetric upside sits with software-defined energy platform operators possessing dispatch algorithm IP and utility interconnection relationships. Long-term viability favors vendors with demonstrated FERC Order 2222 market participation revenue streams rather than hardware-only transaction models. Watch for California NEM 4.0 proposal filings as the signal for residential value-stacking strategy inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Cell Manufacturing Buildout | IRA domestic content bonuses reduce project cost basis for Southwest utility developers. |
| Virtual Power Plant Software Licensing | FERC Order 2222 enables aggregated residential storage bidding into ISO capacity markets. |
| Long-term Cathode Material Offtake | Australian spodumene contracts insulate against Chinese lithium carbonate price volatility. |
| DC-coupled Hybrid System Integration | Shared inverter architectures cut balance-of-system costs for solar-plus-storage projects. |
| UL 9540A Fire Safety Certification | Accelerated validation timelines compress product launch cycles below 12 months. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation against EIA generation data, FERC interconnection filings, IEA technology cost reports, and state-level incentive program databases. Bottom-up project pipeline aggregation and top-down capacity deployment estimates were triangulated against manufacturer shipment disclosures.
Historical deployment patterns across the analysis window anchored forward projections, with segmentation modeled across chemistry type, deployment scale, grid connection status, and end-user category. CAGRs were derived from installed capacity growth trajectories and revenue-per-project economics. Forecast inputs incorporated IRA tax credit phase-down schedules, lithium carbonate price curves, and interconnection queue reform implementation timelines.
Several conditions sit outside the modeled scope, including potential tariff restructuring on Chinese cell imports, state-level net metering revisions beyond NEM 3.0, and breakthrough commercialization timelines for iron-air or solid-state battery chemistries. Forecasts reflect assumptions about FERC Order 2222 implementation pace and IRA domestic content bonus qualification thresholds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Watch Battery Market
Batteries
DMC for Battery Market
Batteries
AAA Battery Market
Batteries
Europe Battery Cell Market
Batteries
Behind-The-Meter (BTM) Battery Market
Batteries
Global Solar Battery Charger Market
Batteries
High Voltage Battery Market
Batteries
Floor Scrubber Battery Market
Batteries
Japan Battery Market
Batteries
Middle East Rechargeable Battery Market
Batteries
Middle-East and Africa Consumer Battery Market
Batteries
Asia-Pacific Dual Carbon Battery Market
Batteries
Disposable Batteries Market
Batteries
Lead Carbon Battery Market
Batteries
Grid-Scale Battery Market
Batteries
Indonesia Battery Market