
 Stationary Lead-Acid Battery Market | 2026-2036
Stationary Lead-Acid Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Stationary Lead-Acid Battery Market Outlook
Advanced AGM specifications with extended cycle life and lower self-discharge rates is reorganizing procurement criteria for critical infrastructure operators. EnerSys leverages its North American manufacturing footprint to sustain long-term supply agreements with utility-scale renewable integrators. GS Yuasa anchors Asian demand through specialized production of high-reliability cells for submarine cable landing stations. East Penn Manufacturing competes on domestic vertical integration, controlling lead smelting and oxide production within its Pennsylvania operations.
Stationary lead-acid batteries are electrochemical storage devices employing lead dioxide positive plates, sponge lead negative plates, and sulfuric acid electrolyte, engineered for float-service applications requiring 10–20 year operational lifespans in standby power roles. Flooded cells retain cost dominance in bulk utility installations where maintenance access is routine, though absorbent glass mat variants capture expanding share in space-constrained telecom shelters and rack-mounted UPS configurations. Containerized installations represent the fastest-growing deployment format, driven by modular data center construction and remote renewable energy storage sites where rapid commissioning outweighs capital cost premiums.
EPA hazardous waste regulations under RCRA govern spent battery collection and recycling infrastructure in the United States, while REACH compliance in Europe restricts lead compound emissions during manufacturing and mandates end-of-life producer responsibility. China's MEE enforces wastewater discharge limits at lead smelters, directly constraining raw material supply availability for cell producers. India's BIS certification requirements for stationary batteries create market access barriers that favor established producers with in-country testing capabilities. Stakeholders must monitor regulatory divergence between jurisdictions as carbon border adjustments and circular economy mandates reshape competitive cost structures for lead-acid versus lithium-ion alternatives.
Market Dynamics
China's MEE wastewater discharge limits at lead smelters are constricting raw material flows, forcing cell producers to requalify supply chains and accelerating the shift toward AGM architectures that reduce lead intensity per kilowatt-hour.
Growth Catalysts
- India's Grid Instability:Unreliable power infrastructure across rural and semi-urban zones drives telecom tower operators to procure backup systems with 8–12 hour autonomy ratings.
- REACH Circular Economy Mandates:European producer responsibility requirements for end-of-life collection create closed-loop material flows that lower effective input costs for compliant manufacturers.
- Containerized Deployment Formats:Modular data center construction and remote renewable integration sites favor rapid-commission battery enclosures over traditional civil works.
Market Restraints
- Lead Price Volatility:Concentration of primary lead smelting in Chinese provinces subject to environmental enforcement creates input cost unpredictability for cell producers.
- Lithium-Ion Substitution:Declining lithium iron phosphate pack costs erode lead-acid competitiveness in cycling-intensive applications beyond pure float-service standby roles.
- REACH Manufacturing Compliance:Restrictions on lead compound emissions during paste mixing and formation charging add capital expenditure burdens for European production facilities.
Strategic Opportunities
- Submarine Cable Landing Stations:Asian coastal infrastructure expansion creates demand for ultra-high-reliability cells with 20-year design life and seismic-rated containment systems.
- India BIS Certification Barriers:In-country testing requirements favor established producers with domestic laboratory capabilities, creating defensive moats against low-cost imports.
- AGM-Lithium Hybrid Architectures:Convergence of lead-acid front-end buffering with lithium-ion deep cycling enables optimized cost-performance configurations for renewable storage.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Specialized expertise in lead-acid paste formulation and formation cycling protocols is concentrating among aging technical workforces in Germany and Japan.
- Multi-Jurisdiction Certification Timelines:Simultaneous pursuit of UL 1973, IEC 60896, and India BIS approvals extends product launch cycles by 14–18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stationary Lead-Acid Battery Market |
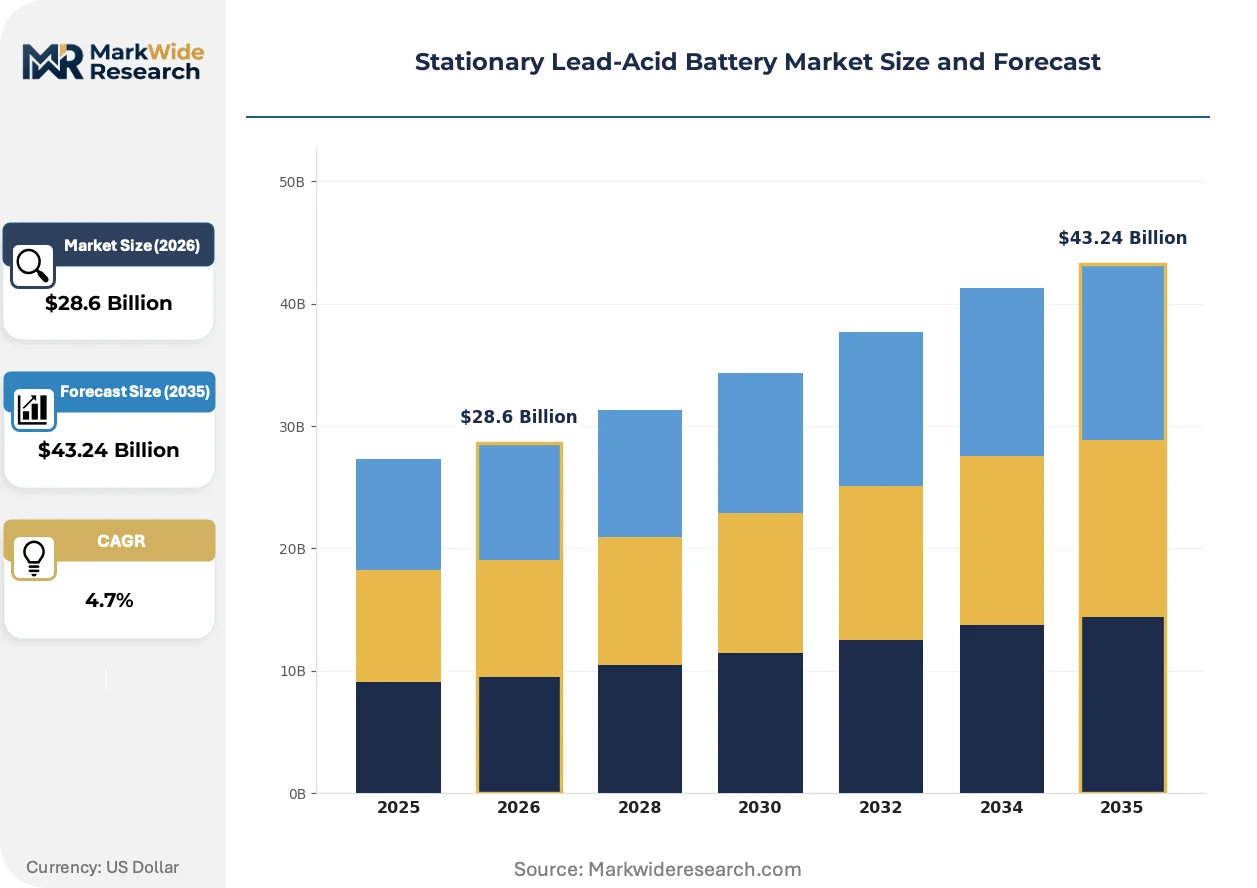
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flooded, Absorbent Glass Mat, Gel, SLI End User: Telecommunications, UPS Systems, Renewable Energy, Industrial Applications Installation Type: Stand-Alone, Rack-Mounted, Containerized, Integrated Systems Manufacturing Stage: Raw Material Sourcing, Cell Production, Assembly, Quality Control |
| Companies Covered | Exide Industries, EnerSys, Johnson Controls, GS Yuasa, East Penn Manufacturing, Narada Power Source, Panasonic, Trojan Battery Company, Crown Battery Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stationary Lead-Acid Battery Market Strategic Shifts
Carbon accounting requirements and circular economy mandates are reconfiguring material sourcing priorities, while containerized system architectures compress deployment timelines for remote infrastructure.
Advanced AGM separators with optimized fiber diameter distributions are displacing conventional flooded cells in space-constrained telecom shelters and rack-mounted UPS configurations. Hyperscale data center operators specify these variants for 15-year design life with reduced watering requirements. The technology is displacing legacy flooded architectures in applications where maintenance access is restricted or labor costs are elevated.
China's dual carbon goals and efficiency mandates issued through MIIT and MEE are tightening cell production standards for energy consumption per unit output. Smelters in Henan and Anhui provinces face production caps that constrain lead oxide availability. Domestic battery producers are responding by qualifying alternative supply from Southeast Asian smelters and investing in closed-loop recycling infrastructure.
Telecom tower operators in India and Southeast Asia are consolidating procurement through managed service providers rather than direct equipment purchase. Leasing models with guaranteed uptime SLAs transfer capital burden to system integrators who specify battery performance tiers. This pattern is most visible in India where tower companies have outsourced power infrastructure to specialized operators with captive maintenance capabilities.
Stationary Lead-Acid Battery Market Segmentation
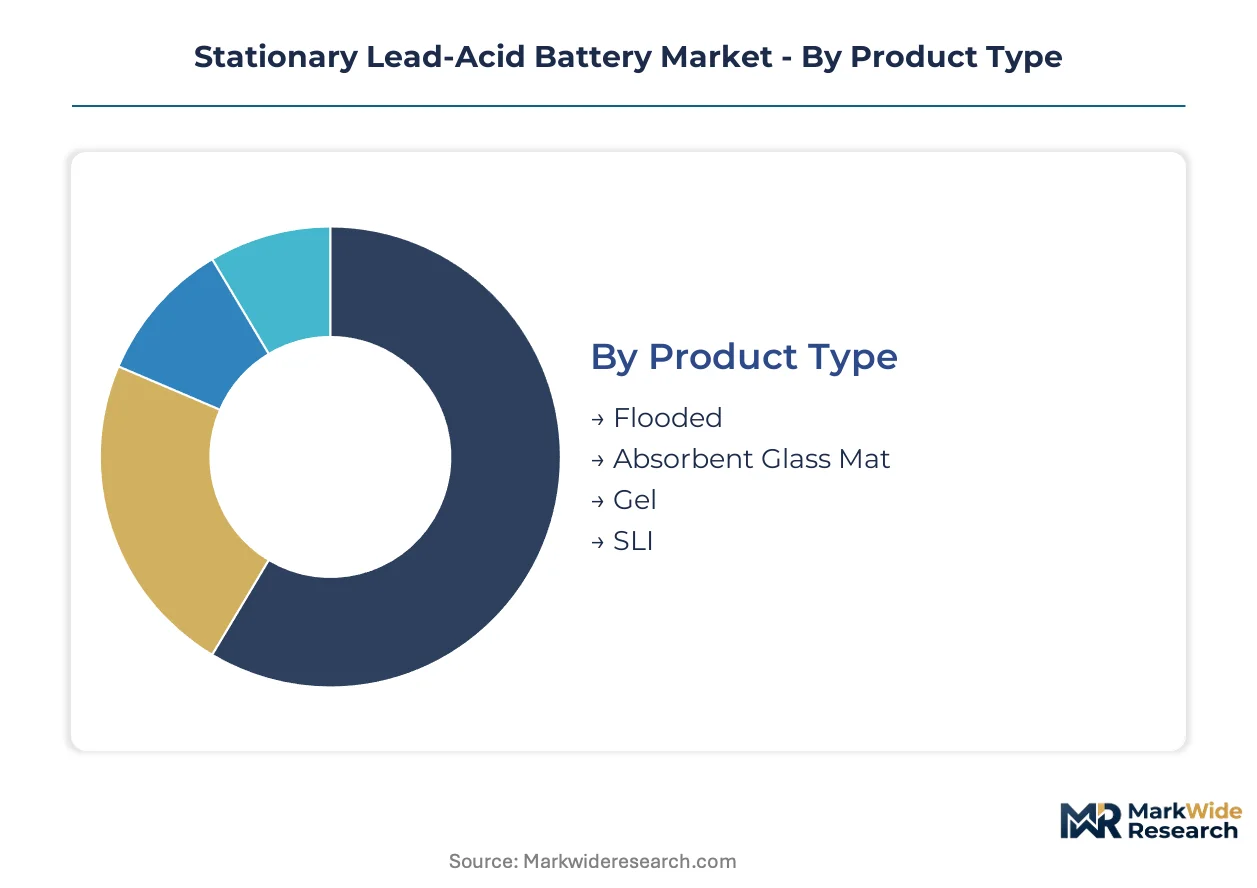
Segmentation in stationary lead-acid batteries reveals how technology choices map directly to operational constraints and total cost of ownership across infrastructure verticals. Procurement specifications diverge sharply between float-service standby roles and cycling-intensive renewable storage applications.
Product Type:
Margin pools concentrate in advanced AGM formulations where extended cycle life commands pricing premiums over commodity flooded alternatives.
- Flooded:Conventional vented cells with liquid sulfuric acid electrolyte require periodic watering but deliver lowest capital cost per kilowatt-hour. Bulk utility installations across rural India and Southeast Asian industrial zones specify flooded architectures where maintenance labor remains inexpensive and enclosure footprints are unconstrained.
- Absorbent Glass Mat:Electrolyte suspended in fiberglass mat separators eliminates spillage risk and enables sealed operation. Hyperscale data center operators in Northern Virginia and Frankfurt specify AGM variants for 15-year design life in space-constrained rack configurations where technician access is restricted.
- Gel:Silica-thickened electrolyte provides enhanced vibration resistance and deep discharge recovery. Specialized applications in seismic-rated submarine cable landing stations and offshore platforms favor gel formulations.
- SLI:Starting-lighting-ignition derivatives adapted for shallow-cycle standby service in cost-sensitive backup roles. Small commercial facilities and residential inverter systems in price-conscious markets deploy SLI-based solutions.
Flooded holds installed capacity. Absorbent Glass Mat is rotating up the share rankings.
End User:
Application-specific duty cycles determine battery chemistry selection and replacement scheduling economics.
- Telecommunications:Grid instability across India drives tower operators toward 8–12 hour autonomy systems. Managed service providers now consolidate procurement through leasing models with guaranteed uptime SLAs, transferring capital burden to integrators who specify performance tiers.
- UPS Systems:Data center deployments require instantaneous switchover capability with 15–20 year float service life. Hyperscale operators in Ashburn, Dublin, and Singapore specify AGM configurations for rack-mounted deployments where floor space commands premium valuations.
- Renewable Energy:Solar and wind integration sites favor containerized battery enclosures for rapid commissioning at remote locations. Cycling requirements here expose lead-acid limitations versus lithium-ion alternatives in daily deep-discharge regimes.
- Industrial Applications:Manufacturing facilities and process control systems demand seismic-rated containment and extended temperature tolerance. Petrochemical complexes along the US Gulf Coast specify industrial-grade cells with enhanced safety venting.
Telecommunications anchors volume throughput. Renewable Energy is expanding most quickly as solar penetration accelerates.
Installation Type:
Deployment format selection trades capital efficiency against commissioning velocity and site preparation requirements.
- Stand-Alone:Conventional battery rooms with dedicated HVAC and fire suppression systems. Established utility substations and central office facilities continue specifying stand-alone architectures where real estate constraints are absent.
- Rack-Mounted:Standardized 19-inch or 23-inch enclosures enabling vertical stacking in data center white space. Operators in Amsterdam and Tokyo metro markets prioritize rack-mounted configurations to maximize compute density per square meter.
- Containerized:Pre-engineered enclosures with integrated climate control and safety systems delivered as modular units. Remote renewable sites in Australia and Chile favor containerized formats where civil works would extend project timelines by months.
- Integrated Systems:Factory-assembled packages combining batteries, power conversion, and controls. Turnkey microgrid developers specify integrated systems to reduce field commissioning complexity and contractor coordination.
Stand-Alone retains legacy dominance. Containerized is climbing the fastest as modular construction practices spread.
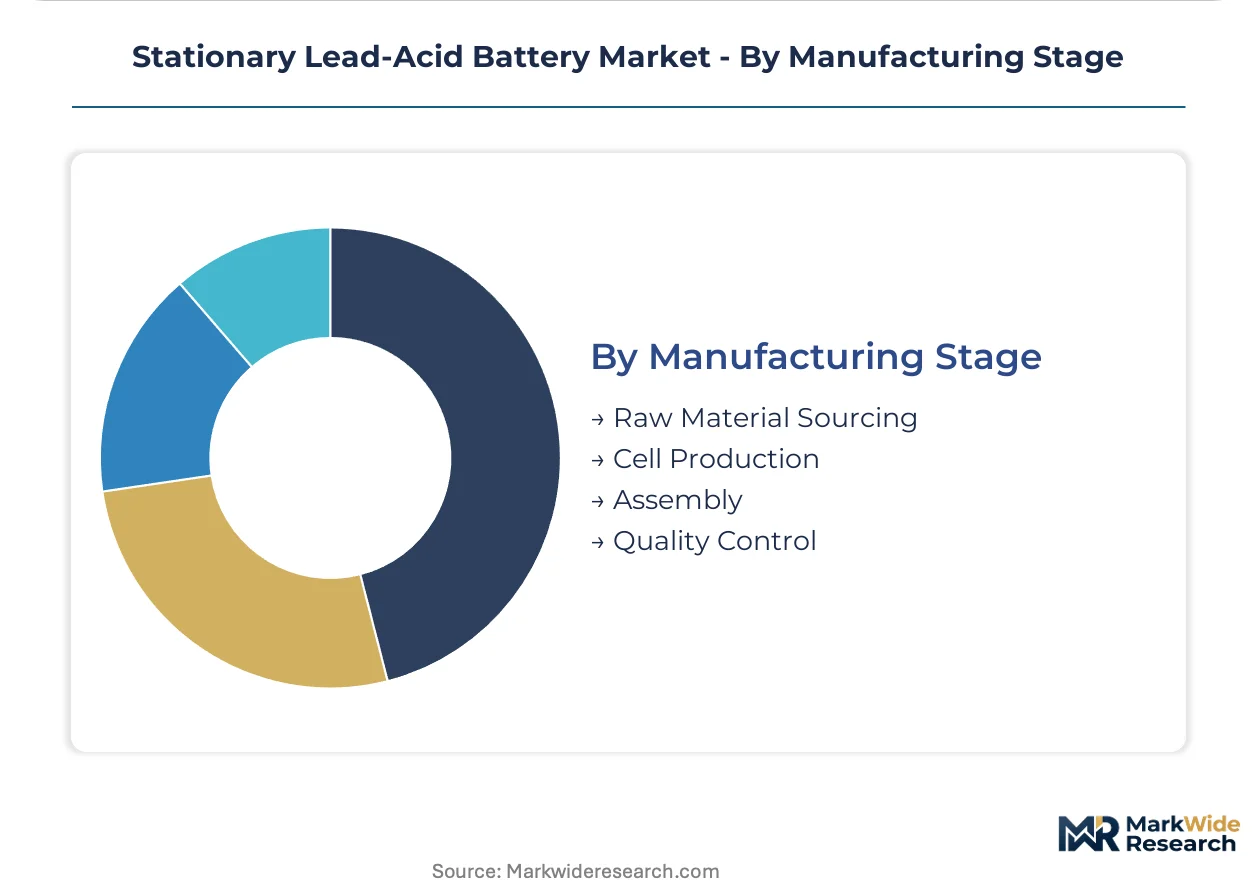
Manufacturing Stage:
Value capture concentrates downstream where quality certification and customer-specific configuration add differentiation.
- Raw Material Sourcing:Lead oxide and alloy procurement from primary smelters and recycled feedstock. China's MEE wastewater discharge limits at Henan and Anhui smelters are constraining oxide availability and forcing producers toward Southeast Asian supply alternatives.
- Cell Production:Plate casting, pasting, curing, and formation cycling operations. Proprietary paste formulations and formation protocols concentrate technical expertise among aging workforces in Germany and Japan.
- Assembly:Interconnection of cells into monoblocs and installation into enclosures. Automated welding and leak-testing investments differentiate tier-one producers from commodity assemblers.
- Quality Control:IEC 60896, UL 1973, and India BIS certification testing. Multi-jurisdiction approval timelines extend product launch cycles by 14–18 months, favoring established producers with captive laboratory capabilities.
Cell Production commands technical premiums. Quality Control is rotating up the share rankings as certification barriers intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity toward flooded cell architectures, while data center operators in Northern Virginia and Frankfurt absorb substantial premiums for AGM configurations that minimize floor space and maintenance access.
United States
Hyperscale data center construction across Loudoun County and Prince William County drives procurement of rack-mounted AGM systems with 15-year design life specifications. EPA hazardous waste regulations under RCRA govern spent battery collection and recycling infrastructure nationwide. Utility-scale renewable integrators in Texas and California favor containerized deployment formats for rapid commissioning at remote solar and wind sites.
China
Dual carbon goals issued through MIIT and efficiency mandates from MEE are tightening cell production standards for energy consumption per unit output. Wastewater discharge limits at lead smelters in Henan and Anhui provinces constrain lead oxide availability for domestic producers. Battery manufacturers in the Yangtze River Delta region are qualifying alternative supply from Southeast Asian smelters and investing in closed-loop recycling infrastructure.
Germany
Industrial manufacturing facilities and process control systems in the Ruhr region and Bavaria demand seismic-rated containment systems with extended temperature tolerance. REACH compliance restricts lead compound emissions during paste mixing and formation charging, adding capital expenditure burdens for European production facilities. Technical expertise in lead-acid paste formulation concentrates among aging workforces in established industrial clusters.
India
Grid instability across rural and semi-urban zones drives telecom tower operators toward 8–12 hour autonomy backup systems with managed service provider consolidation. BIS certification requirements for stationary batteries create market access barriers that favor established producers with in-country testing capabilities. Tower companies in Maharashtra and Gujarat have outsourced power infrastructure to specialized operators with captive maintenance capabilities.
Japan
Submarine cable landing station expansion along coastal infrastructure creates demand for ultra-high-reliability cells with 20-year design life and seismic-rated containment systems. METI standards and JIS certification protocols govern product quality and safety specifications. Specialized producers in the Kansai and Chubu regions anchor Asian demand through high-reliability cell production for critical telecommunications infrastructure.
Stationary Lead-Acid Battery Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with consolidated positions among integrated manufacturers possessing captive lead smelting capabilities and fragmented competition among regional assemblers dependent on external oxide supply. The market structure separates into three strategic archetypes: vertically integrated North American producers controlling upstream material flows, Asian specialists in high-reliability applications, and European manufacturers navigating stringent environmental compliance. Dominant competitive moves include backward integration into lead smelting and oxide production, plus qualification of alternative Southeast Asian raw material supply to circumvent Chinese environmental enforcement.
Among North American integrated manufacturers, EnerSys and East Penn Manufacturing exemplify the vertical-integration archetype through captive control over lead smelting and oxide production within domestic operations. GS Yuasa anchors the Asian specialist tier, occupying a position defined by high-reliability cell production for submarine cable landing stations and critical infrastructure applications. These three companies represent distinct strategic postures: scale-driven manufacturing footprint, domestic supply chain control, and premium-tier reliability specialization respectively.
| Leading Market Players |
|---|
| Exide Industries |
| EnerSys |
| Johnson Controls |
| GS Yuasa |
| East Penn Manufacturing |
| Narada Power Source |
| Panasonic |
| Trojan Battery Company |
| Crown Battery Manufacturing |
| Others |
Value Chain & Pricing Dynamics
Alternative Southeast Asian smelter qualification by Chinese cell producers simultaneously redraws raw material procurement geography and compresses oxide input cost premiums against domestic supply. This substitution dynamic intensifies as MEE wastewater enforcement tightens lead availability from Henan and Anhui provinces, forcing battery manufacturers to absorb logistics premiums or reformulate paste recipes toward lower lead intensity.
Pricing Analysis
Service revenue from extended maintenance contracts and guaranteed uptime SLAs drives lifetime value capture beyond initial equipment sales. Three-tier pricing structure across premium AGM, standard flooded, and economy SLI configurations segments buyers by reliability requirements and autonomy ratings. Cost compression in flooded architectures intensifies as Indian tower operators consolidate procurement through managed service providers with captive maintenance capabilities. Telecom operators in rural India exhibit acute price sensitivity toward commodity flooded cells, while hyperscale data center operators in Northern Virginia and Frankfurt absorb substantial premiums for certified AGM configurations minimizing floor space and technician access.
Supply Chain Analysis
Strategic stockpiling of lead oxide and alloy feedstock dominates inventory strategy given Chinese environmental enforcement volatility and long qualification timelines for alternative smelters. Raw material supply concentrates in China, Australia, and emerging Southeast Asian sources including Vietnam and Indonesia. Cell production draws from lead oxide, fiberglass mat separators, and sulfuric acid electrolyte as core inputs. Single-source vulnerability from concentrated Chinese primary smelting creates structural risk as MEE production caps constrain oxide availability without warning. Distribution runs through direct long-term supply agreements with utility-scale renewable integrators and tower company managed service providers, bypassing traditional distributor channels for volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stationary lead-acid battery market sits in a cyclical recovery phase driven by data center UPS deployment acceleration following hyperscale construction lulls. Capital discipline among integrated manufacturers and raw material supply constraints position compliant producers to capture margin expansion as demand inflects.
For Market Incumbents: Consolidate captive recycling infrastructure and Southeast Asian oxide supply qualification to defend against Chinese environmental enforcement volatility. Deepen backward integration into lead smelting where domestic permits allow, while accelerating AGM formulation R&D to offset lithium-ion substitution pressure in cycling-intensive renewable storage applications. Prioritize India BIS certification investment to maintain defensive moats against low-cost import competition. For New Entrants and Emerging Players: Differentiate on containerized system integration and rapid-commission deployment capabilities for remote renewable sites in Australia and Chile where civil works timelines deter established competitors. Target submarine cable landing station specifications in Japan and Southeast Asia requiring 20-year design life and seismic-rated containment, where technical barriers limit commodity competition. Pursue qualification partnerships with EPC contractors serving turnkey microgrid developers to bypass direct OEM channel conflicts. For Investors and Strategic Acquirers: The market sits at a supply-constrained recovery phase that favors vertically integrated manufacturers with captive oxide production and multi-jurisdiction certification capabilities. Long-term viability hinges on circular economy compliance and closed-loop recycling infrastructure positioning against carbon border adjustments. Acquisition target archetypes include regional assemblers with India BIS laboratory capabilities and Southeast Asian smelter supply relationships. Watch lithium iron phosphate pack cost curves as the critical inflection signal for lead-acid displacement timelines in cycling applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lead Smelting | Captive oxide supply from Pennsylvania and Southeast Asian sources insulates against Chinese MEE enforcement volatility. |
| AGM Formulation R&D Investment | Extended cycle life specifications defend data center UPS share against lithium-ion encroachment in premium segments. |
| India BIS Certification Acceleration | In-country testing capabilities create procurement barriers favoring established producers over low-cost imports. |
| Closed-Loop Recycling Infrastructure | REACH-compliant material flows lower effective input costs and position producers for EU carbon border adjustments. |
| Containerized System Integration | Pre-engineered enclosures with climate control capture rapid-commission demand from remote renewable and modular data center sites. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade data, and industry association disclosures to establish grounded market sizing. Primary interviews captured perspectives from cell production engineers, utility procurement managers, telecom tower operators, EPC contractors, and lead smelter operations directors across China, India, Germany, Japan, and the United States. Secondary validation drew from EPA RCRA compliance databases, ECHA REACH substance registrations, India BIS certification records, MIIT efficiency mandate documentation, and customs trade statistics. Bottom-up unit economics and top-down sectoral demand triangulation cross-checked volume and value estimates.
Segmentation dimensions modeled include product type architecture, end-use application duty cycle, installation format deployment constraints, and manufacturing stage value capture across the projection horizon. CAGRs derive from regression analysis against historical shipment data, capacity expansion announcements, and regulatory enforcement trajectories. Forecast inputs incorporate hyperscale data center construction pipelines, Indian telecom tower electrification mandates, and Chinese dual carbon policy implementation intensity.
The analysis sits within stated boundaries; outcomes outside sustained environmental enforcement in China, lithium-ion cost parity trajectories, or India grid stability improvements would require recalibration. Forecasts reflect assumptions regarding raw material supply continuity and certification timeline stability. Revision becomes warranted when lithium iron phosphate pack pricing crosses lead-acid total cost of ownership thresholds in cycling applications or when Chinese MEE enforcement intensity exceeds modeled production cap scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Printed Batteries Market
Batteries
Europe Lead-Acid Battery Market
Batteries
Battery Swapping Market
Batteries
Japan Battery Market
Batteries
Global Automotive Lead Acid Batteries Market
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
United Kingdom Electric Vehicle Battery Electrolyte Market
Batteries
Electric Battery Market
Batteries
Thin Film and Printed Battery Market
Batteries
Second-Life Automotive Battery Module Systems Market
Batteries
North America Lead-Acid Battery Separator for SLI Applications Market
Batteries
Zinc Carbon Battery Market
Batteries
China Battery Market
Batteries
3D-Printed Battery Market
Batteries
Lithium Thionyl Chloride Battery Market
Batteries
Myanmar Battery Market