
 PVT Battery Panel Market | 2026-2036
PVT Battery Panel Market Size, Share, and Industry Trends Forecast 2026-2036
PVT Battery Panel Market Insights
Monocrystalline-grade thermal conversion efficiency is unwinding competitive dynamics across the PVT battery panel value chain. DualSun leverages its French manufacturing base to sustain vertical integration from wafer to module assembly. LG Electronics anchors premium positioning through in-house battery management systems paired with its PVT arrays. Solimpeks competes on specialized aluminum absorber geometries that optimize heat extraction rates in Mediterranean climates.
A PVT battery panel combines photovoltaic electricity generation with integrated thermal energy capture and storage in a single laminated assembly, typically achieving electrical conversion above 18% while simultaneously harvesting 40-60% of incident energy as low-grade heat for domestic hot water or space conditioning. Monocrystalline and bifacial product types command the dominant share of current installations due to superior temperature coefficients and dual-sided gain profiles that improve annual energy yields on commercial flat roofs. Hybrid systems technology leads R&D investment flows as developers seek to optimize the coupling ratio between electrical output and thermal storage capacity, while utility-scale end users represent the fastest-expanding demand pool as behind-the-meter thermal arbitrage improves project economics.
EU Green Deal performance standards and CE marking requirements under the F-Gas Regulation are tightening minimum thermal recovery specifications for building-integrated renewable systems, effectively raising barriers for thin-film entrants lacking certified heat-exchanger integration. EMA and national building codes in France, Germany, and Italy now mandate renewable heat quotas that PVT-battery configurations satisfy more compactly than separate solar thermal plus PV installations. Stakeholders must monitor evolving battery safety certifications under IEC 62619 as thermal cycling protocols intensify with larger residential storage capacities.
Market Dynamics
Hybrid thermal-electric coupling ratios are compressing payback periods for commercial installations, forcing manufacturers to optimize the trade-off between photovoltaic output and thermal storage density. This technical tension is restructuring procurement criteria across Southern European building-integrated renewable portfolios.
Growth Catalysts
- EU Green Deal building-performance mandates:Tightened renewable heat quotas in France, Germany, and Italy are eliminating separate solar thermal-plus-PV configurations in favor of compact PVT-battery assemblies.
- Bifacial monocrystalline temperature coefficients:Superior thermal performance on commercial flat roofs is accelerating replacement cycles for legacy single-sided installations across Mediterranean climates.
- Utility-scale behind-the-meter thermal arbitrage:German and Spanish developers are expanding procurement of hybrid systems to capture peak electricity pricing differentials through stored thermal dispatch.
Market Restraints
- Aluminum absorber supply concentration:Specialized extrusion capacity for optimized heat-exchanger geometries clusters with Mediterranean fabricators, exposing procurement to regional logistics volatility.
- IEC 62619 thermal cycling certification:Intensified battery safety protocols for larger residential storage capacities are extending product validation timelines by 8-14 months.
- Thin-film heat-exchanger integration:F-Gas Regulation CE marking requirements for certified thermal recovery specifications have effectively barred non-monocrystalline entrants lacking laminated assembly expertise.
Strategic Opportunities
- CEE residential retrofits:Poland and Czech Republic building stock remains underpenetrated for building-integrated renewable heat, with EU cohesion funds financing first-wave PVT-battery installations.
- Heat pump convergence:Coupling PVT thermal output with inverter-driven heat pumps is creating all-electric domestic hot water systems displacing gas boiler baseload.
- Italy Superbonus 110% incentive extension:The renovated fiscal framework for energy-efficiency building upgrades is covering 65-110% of PVT-battery installation costs through transferable tax credits.
Industry Challenges
- Electro-thermal co-simulation expertise:The talent pool capable of optimizing coupled photovoltaic-thermal-battery system design remains shallow, with specialized training programs only now emerging at RWTH Aachen and Politecnico di Milano.
- Legacy HVAC integration complexity:Existing hydronic heating infrastructure in 1990s-era German multifamily housing requires costly buffer tank retrofits to accept PVT thermal input.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVT Battery Panel Market |
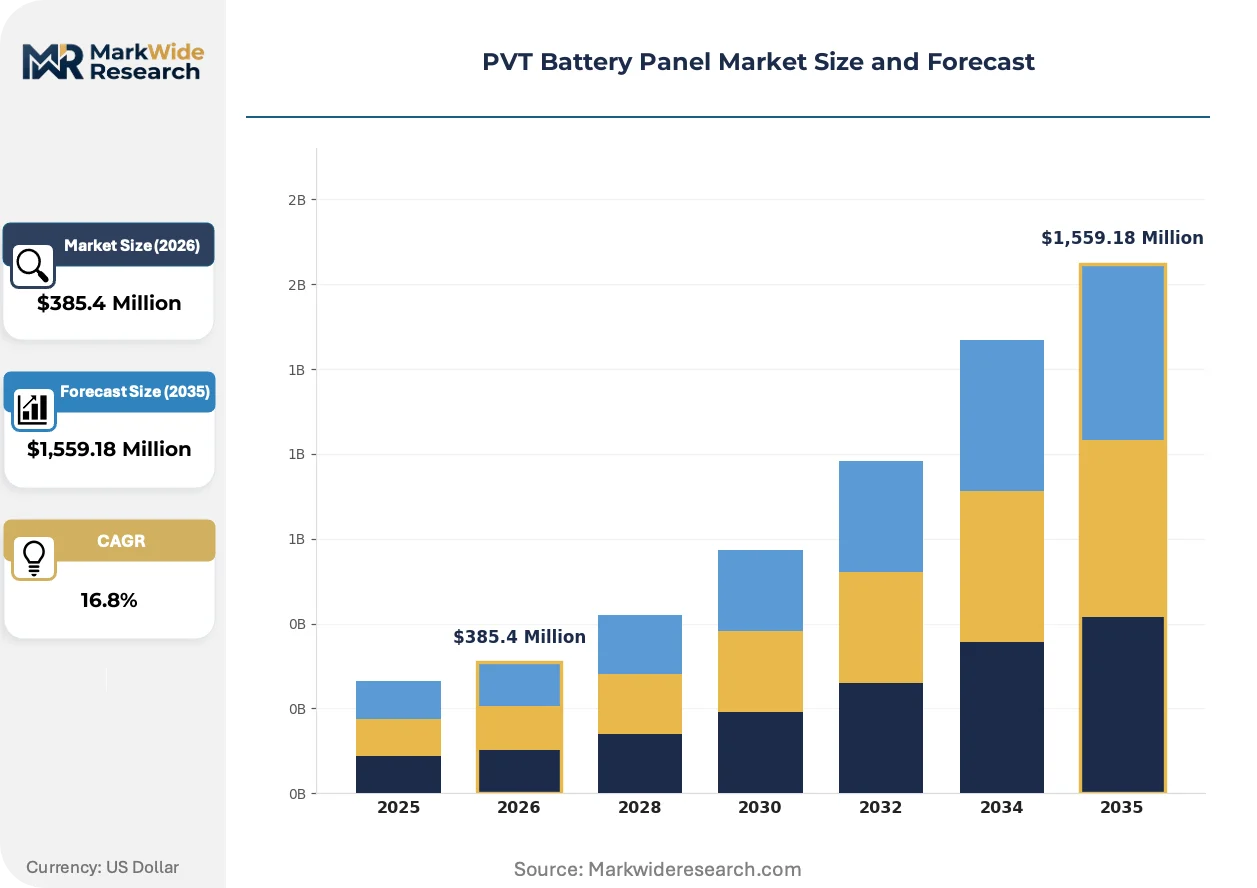
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,559.18 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin-Film, Polycrystalline, Monocrystalline, Bifacial Technology: Thermal Photovoltaics, Hybrid Systems, Concentrated Solar Power, Organic Photovoltaics End User: Residential, Commercial, Industrial, Utility Scale Distribution Channel: Direct Sales, Online Retail, Distributors, Installers |
| Companies Covered | DualSun, PiKCELL, SolarMaster, Solimpeks, Northburn Solar, NIBE Energy Systems, LG Electronics, Sunmaxx PVT, Hydro Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVT Battery Panel Market Trends and Innovations
Active materials research and regulatory calibration are compressing product development cycles while expanding the addressable building stock for hybrid thermal-electric systems. Three converging developments are restructuring competitive positioning.
Perovskite-silicon tandem junction layers are achieving laboratory thermal stability above 85°C while maintaining electrical conversion. Mediterranean commercial installers are piloting these configurations for high-temperature process heat applications. The technology is miniaturizing thermal storage volumes required per kilowatt-hour of dispatched heat, enabling rooftop installations previously constrained by structural load limits.
F-Gas Regulation phase-down schedules are accelerating refrigerant transition timelines for building-integrated heat pumps. CE marking authorities are requiring updated thermal performance declarations for coupled PVT-heat pump systems, forcing manufacturers to revalidate seasonal coefficient of performance metrics. Southern European certification bodies are responding with expedited testing protocols for R290 propane-based systems.
Aggregators are consolidating residential PVT-battery fleets into virtual power plant architectures. German distribution system operators are contracting dispatch rights for stored thermal capacity, replacing traditional feed-in tariff structures. This procurement evolution is most visible in Bavaria and Baden-Württemberg, where municipal utilities are bundling installation subsidies with 15-year thermal service agreements.
PVT Battery Panel Market Segmentation
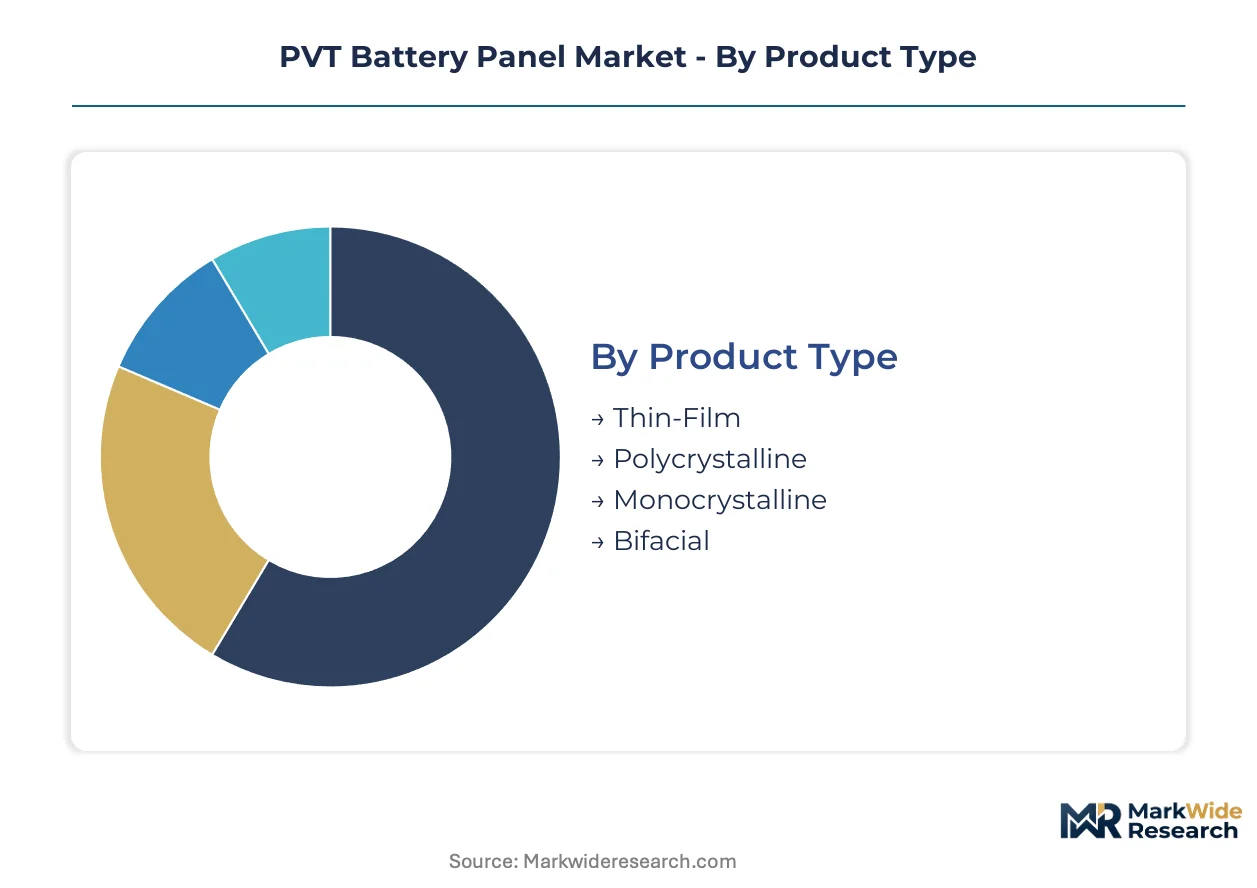
PVT battery panel procurement patterns diverge sharply across product architectures and customer scales. Technical specifications governing thermal-electric coupling ratios and storage integration density determine which configurations penetrate specific building-stock vintages and regulatory environments.
Product Type:
Monocrystalline and bifacial variants dominate export-led procurement from French and German manufacturers serving Mediterranean utility-scale developers, while thin-film configurations remain concentrated in domestic Southern European retrofits where space constraints override efficiency premiums.
- Monocrystalline:Silicon ingots sliced from single-crystal boules deliver electrical conversion above 20% with temperature coefficients below -0.35%/°C. German utility-scale developers in Bavaria prioritize these configurations for behind-the-meter thermal arbitrage where peak electricity pricing differentials justify premium procurement.
- Bifacial:Dual-sided gain profiles harvest reflected irradiance from commercial flat roofs, lifting annual energy yields 8-15% over monofacial equivalents. Spanish rooftop installers specify these for EU Green Deal building-performance compliance where bifacial monocrystalline combinations satisfy tightened renewable heat quotas.
- Thin-Film:Cadmium telluride and CIGS layers laminate onto lightweight substrates for structural load-constrained installations.
- Polycrystalline:Multi-crystal silicon cells occupy price-sensitive residential segments where thermal storage density requirements remain modest.
Monocrystalline commands the established base. The steepest expansion runs through bifacial configurations.
Technology:
Cost tier differentiation separates validated hybrid systems from developmental organic and concentrated architectures, with thermal-photovoltaic coupling ratios determining project economics across residential versus utility-scale deployments.
- Hybrid Systems:Integrated photovoltaic-thermal-battery assemblies optimize coupling ratios between electrical output and thermal storage capacity. Italian Superbonus 110% tax credit structures accelerate residential procurement of these configurations where all-electric domestic hot water systems displace gas boiler baseload.
- Thermal Photovoltaics:Standard PVT configurations without integrated battery storage serve commercial retrofit markets where existing HVAC infrastructure requires buffer tank adaptation.
- Concentrated Solar Power:Parabolic trough and Fresnel lens architectures target industrial process heat above 150°C.
- Organic Photovoltaics:Polymer-based absorber layers remain pre-commercial for building-integrated applications pending thermal stability validation.
Hybrid systems anchor current revenue concentration. Thermal photovoltaics retain retrofit penetration depth.
End User:
Volume concentration shifts toward utility-scale procurement as German distribution system operators contract dispatch rights for aggregated thermal storage, while residential segments depend on transferable tax credit liquidity.
- Utility Scale:Behind-the-meter thermal arbitrage improves project economics through peak shaving and grid services revenue streams. Spanish and German developers expand procurement as F-Gas Regulation phase-down schedules accelerate heat pump convergence.
- Commercial:Flat-roof installations across Southern European logistics centers and retail portfolios exploit bifacial gain profiles.
- Residential:Single-family and multifamily retrofits in Poland and Czech Republic tap EU cohesion funds for first-wave PVT-battery installations.
- Industrial:Process heat applications above 100°C pilot perovskite-silicon tandem configurations.
Utility scale drives capacity additions fastest. Commercial maintains installed base density.
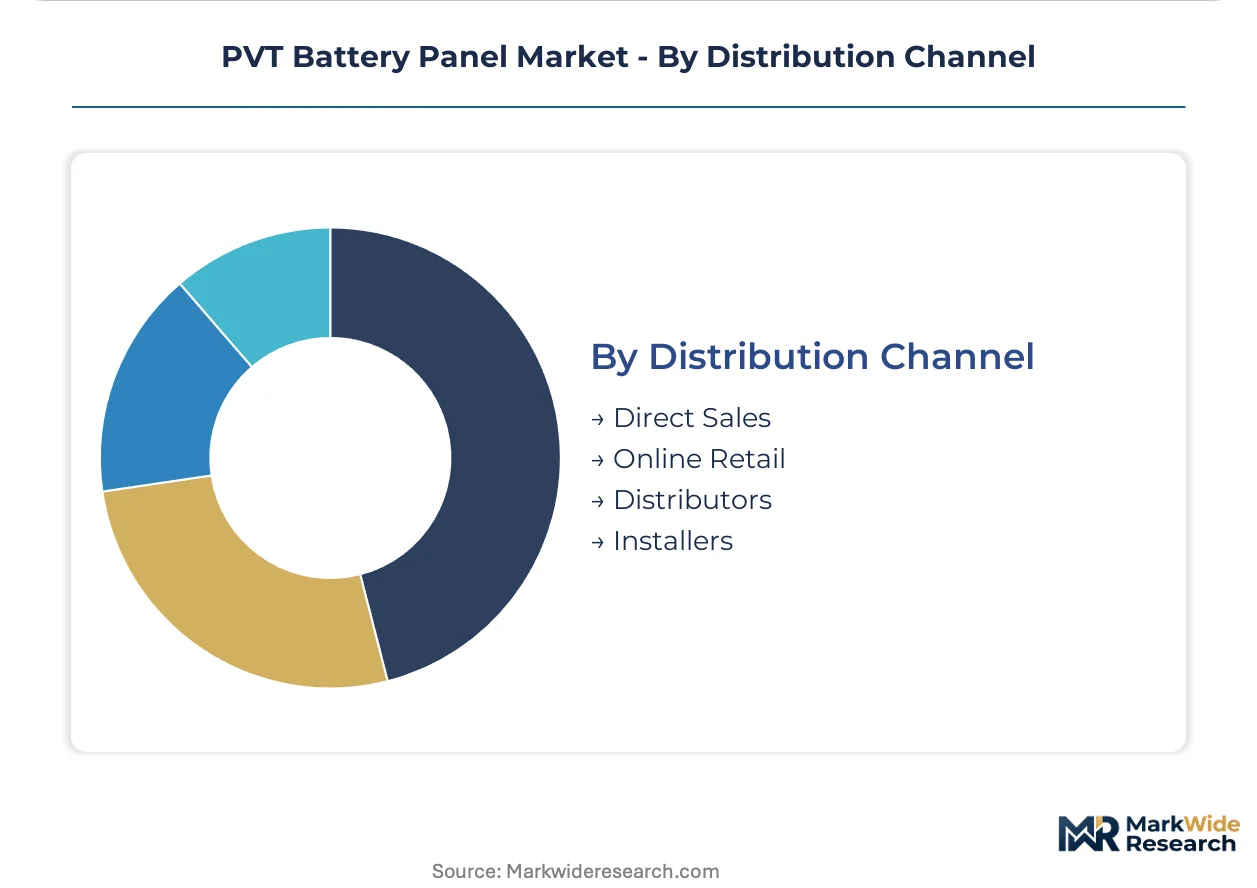
Distribution Channel:
Customer type determines channel selection, with direct sales capturing utility-scale procurement and installer networks dominating residential retrofits requiring hydronic integration expertise.
- Direct Sales:Manufacturer-to-developer relationships govern utility-scale procurement of hybrid systems where technical specification negotiation precedes volume commitments.
- Installers:Certified plumbing-electrical dual-trade contractors execute residential and commercial retrofits requiring buffer tank adaptation and heat pump coupling.
- Distributors:Regional wholesalers stock monocrystalline and bifacial modules for Mediterranean installer networks.
- Online Retail:E-commerce platforms serve price-transparent polycrystalline segments.
Direct sales capture the largest transaction values. Installer networks expand coverage fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-led procurement from French and German manufacturers dominates Mediterranean utility-scale deployment, while import dependency for specialized aluminum absorber extrusions concentrates procurement risk with Italian and Spanish fabricators. Southern European markets absorb the majority of hybrid system volumes as EU Green Deal mandates tighten building-performance standards.
Germany
Utility-scale developers in Bavaria and Baden-Württemberg expand behind-the-meter thermal arbitrage installations to capture peak electricity pricing differentials. The F-Gas Regulation accelerates R290 propane-based heat pump convergence with PVT arrays. Municipal utilities across the southern states bundle installation subsidies with 15-year thermal service agreements.
Spain
Bifacial monocrystalline configurations dominate commercial rooftop procurement across logistics centers and retail portfolios in Madrid and Catalonia. The national building code mandates renewable heat quotas that PVT-battery assemblies satisfy more compactly than separate solar thermal-plus-PV installations. Andalusian installer networks pilot perovskite-silicon tandem junction layers for high-temperature process heat applications.
France
DualSun leverages its domestic manufacturing base to sustain captive supply from wafer through module assembly for export markets. EMA and national building codes now require CE marking for certified heat-exchanger integration in building-integrated renewable systems. The Provence-Alpes-Côte d'Azur region hosts specialized aluminum absorber geometry fabricators optimizing heat extraction rates.
Italy
The Superbonus 110% fiscal framework covers 65-110% of residential PVT-battery installation costs through transferable tax credits. ANSM and national regulators enforce tightened thermal recovery specifications under EU Green Deal performance standards. Lombardy and Emilia-Romagna anchor commercial retrofit activity where existing HVAC infrastructure requires buffer tank adaptation.
Poland
EU cohesion funds finance first-wave PVT-battery installations across underpenetrated residential building stock in Warsaw and Kraków metropolitan areas. The country's national energy regulator implements renewable heat quotas aligned with EU Green Deal timelines. Silesian industrial zones emerge as early adopters for process heat pilot configurations.
PVT Battery Panel Market Competitive Landscape
Concentration sits with vertically integrated European specialists and diversified Asian electronics conglomerates competing on thermal-electric coupling optimization. The vendor base splits between premium-tier manufacturers with in-house battery management capabilities and mid-market fabricators sourcing standardized absorber geometries. Three archetypes dominate: captive-supply wafer-to-module integrators, electronics-diversified energy storage platforms, and specialized thermal engineering houses. Capacity expansion and strategic partnerships constitute the dominant competitive moves as procurement criteria restructure around hybrid system validation.
Among French integrated manufacturers, DualSun occupies a position exemplifying captive supply chain control from crystalline silicon through laminated assembly. LG Electronics anchors the electronics-diversified archetype, representing premium positioning through paired energy storage and photovoltaic-thermal arrays. Solimpeks sits within the specialized thermal engineering tier, occupying a position tied to Mediterranean climate optimization expertise. These three entities collectively represent the strategic positioning vectors—vertical integration, platform diversification, and climate-specific engineering—that define competitive differentiation in procurement markets.
| Leading Market Players |
|---|
| DualSun |
| PiKCELL |
| SolarMaster |
| Solimpeks |
| Northburn Solar |
| NIBE Energy Systems |
| LG Electronics |
| Sunmaxx PVT |
| Hydro Solar |
| Others |
Pricing and Supply Chain Analysis
Long-term thermal service agreements lock in supply access and price visibility for utility-scale developers across Bavaria and Baden-Württemberg, bundling installation subsidies with fifteen-year dispatch rights that compress procurement cost volatility.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers command spreads based on IEC 62619 certification status and in-house battery management integration, while standard configurations compete on aluminum absorber geometry optimization. Cost compression in economy tiers intensifies as polycrystalline alternatives face thin-film heat-exchanger integration barriers. Residential retrofit contractors exhibit highest price sensitivity, whereas German municipal utilities prioritize thermal-electric coupling ratios over unit economics.
Supply Chain Analysis
Inventory lead times for specialized aluminum absorber extrusions stretch procurement cycles as Mediterranean fabricators concentrate heat-exchanger geometry capacity. Crystalline silicon wafers draw from German and French ingot suppliers, while lithium-ion cells rest on South Korean and Chinese cathode material flows. Single-source vulnerability clusters with Italian and Spanish aluminum extrusion specialists. Distribution runs through direct manufacturer-to-developer relationships for utility-scale procurement, with certified installer networks handling residential retrofits requiring hydronic integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PVT battery panel market represents a high-growth disruption as EU Green Deal building-performance mandates eliminate separate solar thermal-plus-PV configurations in favor of compact hybrid assemblies.
For Market Incumbents: Secure captive supply of crystalline silicon wafers through backward integration into French and German ingot production to defend against emerging Asian electronics conglomerates. Anchor premium positioning through accelerated IEC 62619 thermal cycling certification for larger residential storage capacities, extending validation timelines that thin-film competitors cannot match. For New Entrants and Emerging Players: CE marking fast-tracks for R290 propane-based heat pump coupling systems open white-space in Southern European commercial retrofits where F-Gas Regulation phase-down schedules demand rapid revalidation. Target Poland and Czech Republic residential building stock underpenetrated for renewable heat, leveraging EU cohesion fund financing as a go-to-market wedge. For Investors and Strategic Acquirers: Specialized thermal engineering houses with Mediterranean climate optimization expertise offer the clearest acquisition target archetype for portfolio exposure to hybrid system convergence. Long-term viability hinges on electro-thermal co-simulation talent pools deepening at RWTH Aachen and Politecnico di Milano. Watch perovskite-silicon tandem junction thermal stability validation as the inflection signal for high-temperature process heat applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crystalline Silicon | Captive wafer supply secures margin control against volatile polysilicon spot markets. |
| IEC 62619 Thermal Cycling Certification | Validated battery safety protocols unlock German and Italian residential storage procurement. |
| CE Marking for R290 Heat Pump Coupling | Propane-based system approval accelerates F-Gas Regulation compliance timelines. |
| Virtual Power Plant Aggregation | German distribution system operators contract dispatch rights for stored thermal capacity. |
| Perovskite-Silicon Tandem Pilot Programs | Andalusian installers test high-temperature process heat configurations above 85°C stability. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility-scale project developers, certified plumbing-electrical contractors, aluminum absorber fabricators, and municipal utility planning officers. Secondary validation drew from EU Green Deal regulatory filings, F-Gas Regulation CE marking databases, IEC certification registries, and national building code amendments across France, Germany, Italy, and Spain. Bottom-up installation volume estimates triangulated against top-down market value reconstructions.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product architecture, thermal-electric coupling ratio, end-user scale, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns, with inputs including EU cohesion fund disbursement schedules and Superbonus 110% tax credit liquidity trajectories.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal enforcement and aluminum extrusion capacity expansion; material deviation in F-Gas Regulation phase-down timelines or battery safety protocol intensification would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Global Solar Battery Charger Market
Batteries
North America NMC Battery Pack Market
Batteries
Global Coke Oven Batteries Market
Batteries
Flow Battery Market
Batteries
Forklift Battery Rental Market
Batteries
Forklift Battery Charger Market
Batteries
Battery Pack for Marine Hybrid and Full Electric Propulsion Market
Batteries
West Africa Battery Market
Batteries
Low Temperature Battery Market
Batteries
Sodium Nickel Chloride Battery Market
Batteries
Smart Battery Market
Batteries
Europe Battery Market
Batteries
Dry Cell Battery Market
Batteries
Electric Battery Market
Batteries
Rechargeable Battery Market
Batteries
Grid-Scale Lead-Acid Battery Market