
 High-Purity Hydrogen Fluoride Market | 2026-2036
High-Purity Hydrogen Fluoride Market Size, Share, and Industry Trends Forecast 2026-2036
High-Purity Hydrogen Fluoride Market Insights
Long-term supply agreements for ultra-high-purity material is consolidating procurement strategies across leading semiconductor chemical buyers. Morita Chemical Industries leverages captive fluorite reserves and vertical acid purification to sustain cost discipline in Japanese wafer chemical supply. Do-Fluoride Chemicals anchors Chinese domestic production of electronic-grade anhydrous HF for logic and memory fabs. Stella Chemifa Corporation differentiates through sub-ppb impurity control protocols that compete for Korean and Taiwanese foundry qualification.
High-purity hydrogen fluoride denotes hydrogen fluoride refined to impurity levels below one part per billion for semiconductor etching and cleaning applications, typically manufactured through multi-stage distillation and ion-exchange purification from industrial-grade feedstock. Electronic-grade HF commands the dominant value share as 3nm and 2nm node transitions require stricter metal-ion specifications; aqueous formulations for pharmaceutical synthesis represent a mature, lower-margin pool. By delivery mode, bulk and mini-bulk systems capture growing preference as fabs consolidate chemical management through centralized distribution rather than cylinder handling.
MEE emissions standards in China, REACH registration requirements in Europe, and EPA risk management rules in the United States collectively elevate compliance costs and barrier thresholds for new acid purification entrants. Korea's MFDS and Japan's METI both maintain national chemical purity benchmarks that shape import eligibility and local qualification timelines. Stakeholders must monitor evolving node-specific purity thresholds and regional decarbonization mandates to align capacity investments with buyer qualification roadmaps.
Market Dynamics
Semiconductor node shrinkage below 5nm is compressing impurity tolerance thresholds and forcing acid purification infrastructure upgrades across East Asian electronics manufacturing corridors.
Growth Catalysts
- 3nm and 2nm Node Transitions:Logic and memory fabs in Taiwan and South Korea now require sub-ppb metal-ion specifications that only ultra-high-purity hydrogen fluoride can satisfy.
- China's Dual Carbon Goals:MEE emissions standards are mandating acid purification upgrades at domestic fluorochemical plants, expanding electronic-grade production capacity.
- REACH Registration Requirements:European chemical purity benchmarks are consolidating qualified supplier pools and elevating import eligibility thresholds for non-EU producers.
Market Restraints
- Captive Fluorite Supply Concentration:Vertical control over acid-grade fluorspar reserves limits feedstock access for independent purification specialists in Japan and China.
- Multi-Stage Distillation Capex:Ion-exchange and sublimation equipment for electronic-grade production requires substantial capital outlay with extended depreciation cycles.
- EPA Risk Management Rules:United States regulatory compliance elevates barrier thresholds for new acid purification entrants seeking domestic qualification.
Strategic Opportunities
- Indian Semiconductor Mission:Emerging fab investments in Gujarat and Tamil Nadu are creating first-mover qualification windows for electronic-grade chemical suppliers.
- Bulk Distribution Systems:Centralized chemical management through mini-bulk delivery is displacing cylinder handling at Korean and Taiwanese foundry complexes.
- F-Gas Regulation Phase-Down:European fluorinated gas restrictions are accelerating substitution toward purified inorganic fluorides for etching applications.
Industry Challenges
- Sub-ppb Metrology Expertise:ICP-MS and GF-AAS analytical capability scarcity constrains quality assurance staffing at purification facilities.
- Fab Qualification Timelines:Korean MFDS and Japan METI certification protocols extend customer onboarding to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Purity Hydrogen Fluoride Market |
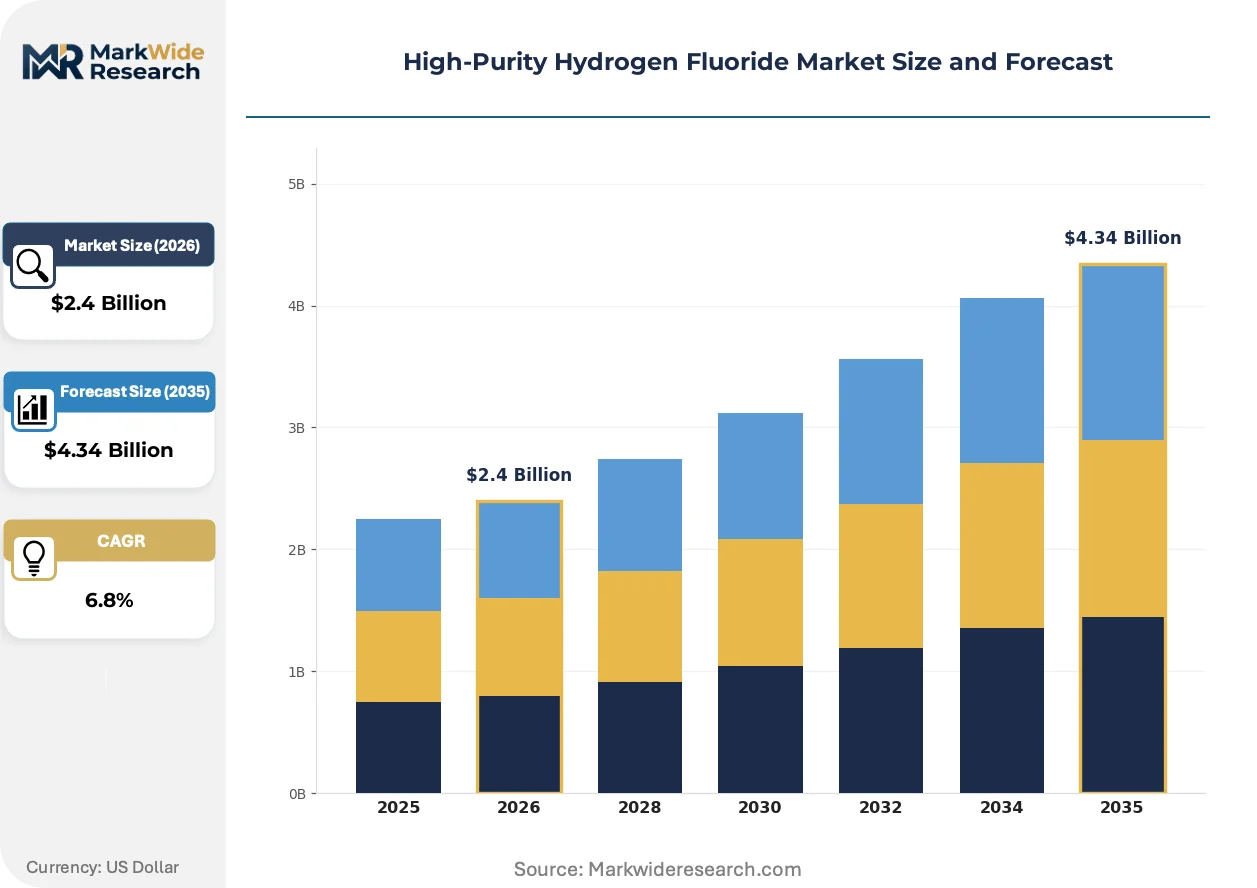
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous HF, Aqueous HF, Electronic Grade HF, Reagent Grade HF End Use Industry: Semiconductors, Pharmaceuticals, Chemical Manufacturing, Metallurgy Delivery Mode: Bulk Delivery, Cylinder Delivery, Mini-Bulk Delivery, ISO Tank Delivery Packaging Type: Steel Cylinders, Totes, Drums, Cans |
| Companies Covered | Morita Chemical Industries, Do-Fluoride Chemicals, Stella Chemifa Corporation, FDAC, Yingpeng Group, Honeywell International, Shaowu Fluoride, Zhejiang Kaiheng Electronic Materials, Solvay (Zhejiang Lansol), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Purity Hydrogen Fluoride Market Trends and Innovations
Point-of-use purification and closed-loop chemical management systems are compressing supply chain risk exposure while elevating purity assurance at the fab interface.
Multi-column ion-exchange skids for hydrogen fluoride polishing are modularizing across Taiwanese and Korean foundry chemical distribution centers. Memory and logic fabs with 3nm ramp schedules are adopting containerized purification units that integrate directly with bulk delivery infrastructure. This distributed architecture is compressing centralized acid plant capital requirements while elevating local purity control.
China's tightening MEE emissions standards are forcing fluorochemical producers to retrofit wet scrubber and thermal oxidizer systems ahead of 2025 compliance deadlines. Domestic acid purification plants face elevated operating costs from continuous emissions monitoring mandates. Electronic-grade output is concentrating at facilities with captive waste treatment infrastructure in Fujian and Zhejiang provinces.
Long-term supply agreements with fixed purity escalation clauses are displacing spot market purchasing at leading semiconductor chemical buyers. Korean and Taiwanese foundries are consolidating procurement through three-to-five-year contracts with qualified suppliers. This contractual shift is most visible at logic fabs transitioning to 2nm process development, where supply security outweighs price flexibility.
High-Purity Hydrogen Fluoride Market Segmentation
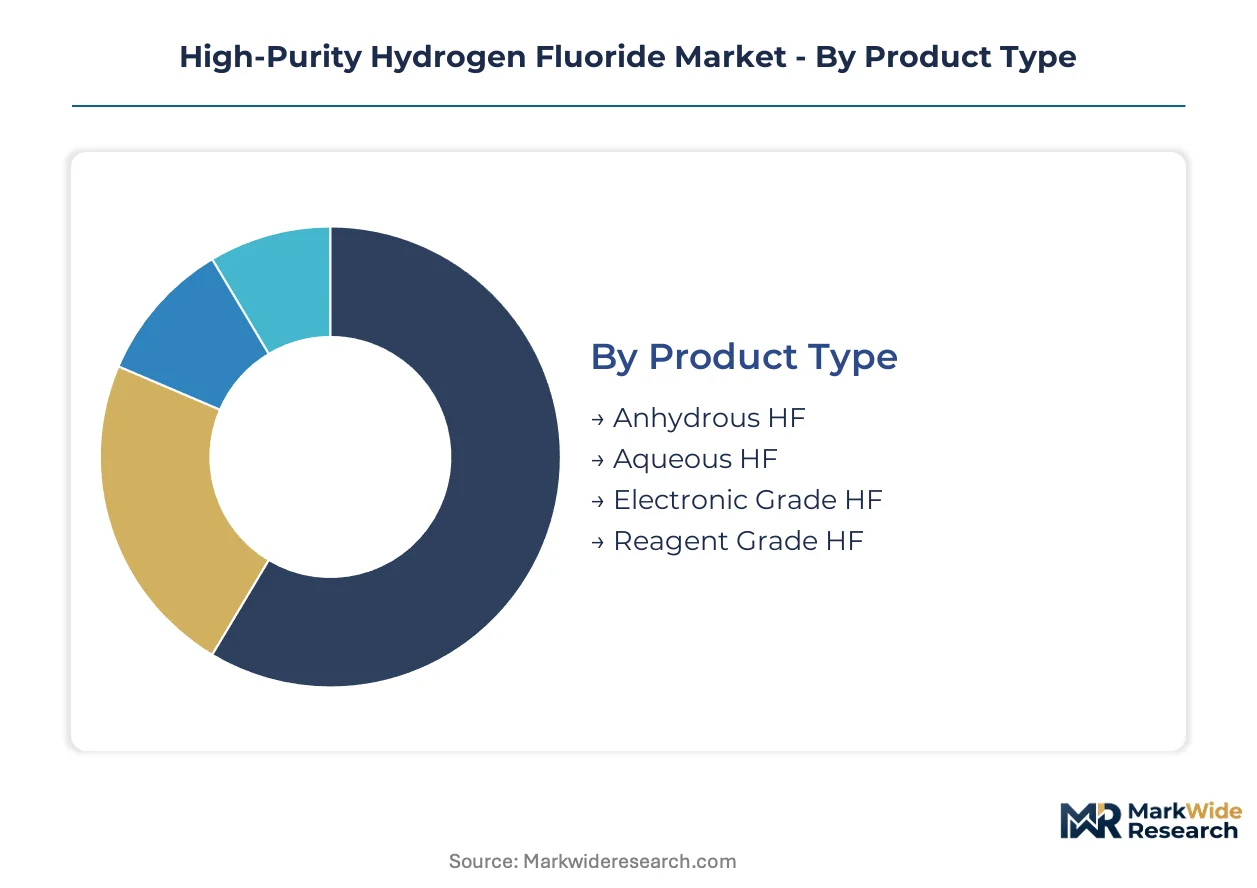
Semiconductor node transitions below 5nm are fragmenting demand across purity tiers and delivery systems. Each segment carries distinct qualification barriers and capital requirements that shape supplier positioning.
Product Type:
Upgrade cycles in acid purification infrastructure are differentiating competitive positioning across purity grades and formulation types.
- Electronic Grade HF:Refined to sub-ppb metal-ion specifications through multi-stage distillation and ion-exchange polishing. Demand concentrates at Taiwanese and Korean logic fabs transitioning to 2nm process development, where supply security outweighs price flexibility.
- Anhydrous HF:Water-free hydrogen fluoride manufactured via fractional distillation of industrial feedstock. Chinese fluorochemical producers in Fujian and Zhejiang provinces are expanding captive capacity to serve domestic memory fab ramps.
- Aqueous HF:Diluted formulations for wet etching and surface treatment applications. Pharmaceutical synthesis in India and Southeast Asia represents the primary consumption corridor.
- Reagent Grade HF:Laboratory and analytical applications requiring ppm-level purity control. Academic and industrial R&D facilities in Japan and Germany anchor demand.
Electronic Grade HF sits at the top of the volume ranking, with Anhydrous HF climbing the fastest on Chinese domestic fab investments.
End Use Industry:
Application-specific purity thresholds are creating tiered margin structures across customer segments.
- Semiconductors:Wafer etching and cleaning operations at foundries and IDMs. Korean MFDS and Japan METI certification protocols extend supplier qualification timelines to 18-24 months.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and fluorination reactions. Mature demand pool with lower purity requirements than electronics applications.
- Chemical Manufacturing:Fluoropolymer and refrigerant precursor production. Chinese MEE emissions standards are forcing acid purification upgrades at domestic fluorochemical plants.
- Metallurgy:Aluminum smelting flux and rare earth element processing. Russian and Kazakh producers represent concentrated demand centers.
Semiconductors command the steepest expansion trajectory, with Pharmaceuticals representing the most mature consumption base.
Delivery Mode:
Centralized chemical management is displacing traditional cylinder handling at high-volume consumption sites.
- Bulk Delivery:Dedicated tanker shipments to fab chemical distribution centers. Taiwanese foundry complexes are consolidating procurement through three-to-five-year supply agreements.
- Mini-Bulk Delivery:Intermediate volume systems for medium-scale semiconductor operations. Korean memory fabs are adopting containerized purification units that integrate with mini-bulk infrastructure.
- Cylinder Delivery:Traditional packaged gas model for small-volume or remote users. Declining share as fabs centralize chemical management.
- ISO Tank Delivery:Intermodal container systems for regional distribution. European REACH registration requirements are consolidating qualified supplier pools for ISO tank operators.
Bulk Delivery captures the dominant volume position, with Mini-Bulk Delivery gaining share fastest among mid-scale fabs.
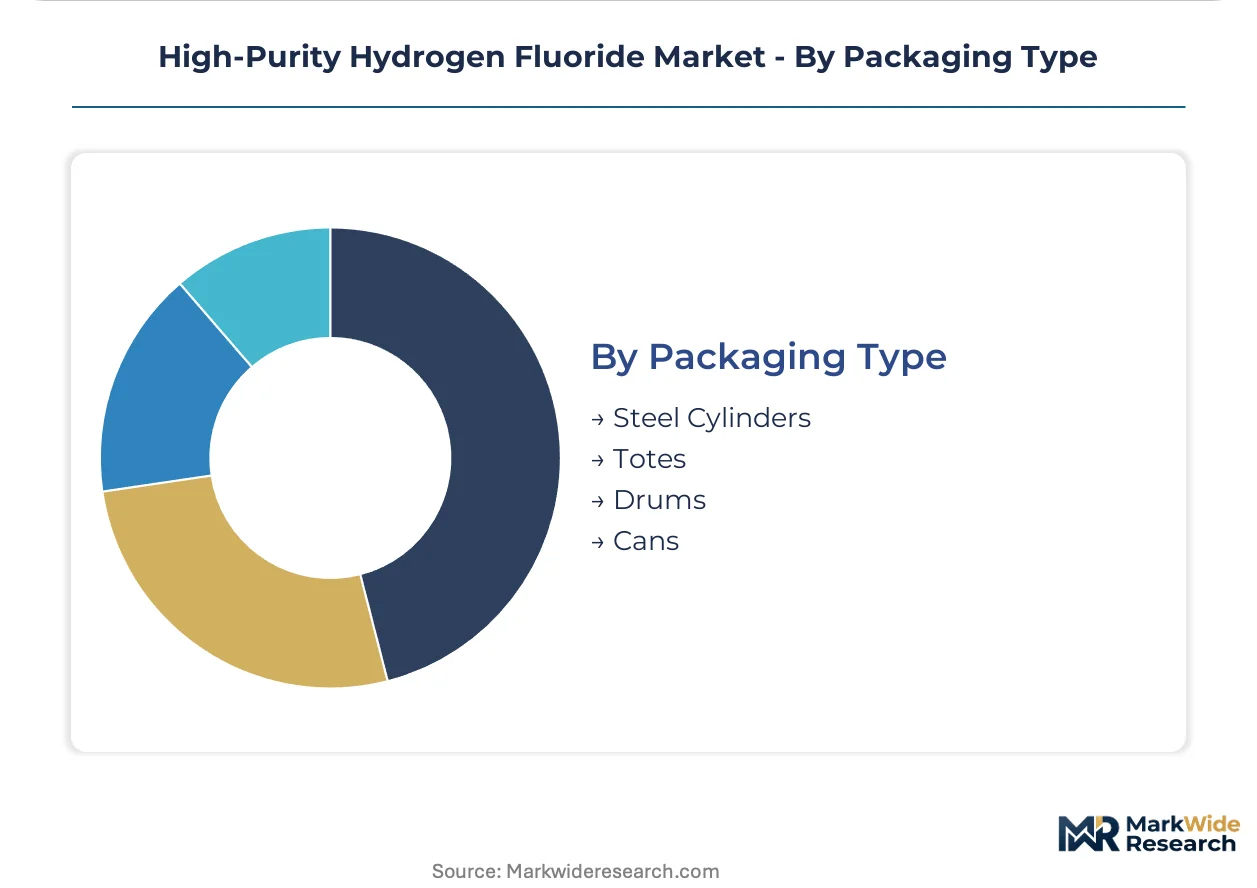
Packaging Type:
Packaging selection tracks delivery mode concentration and purity preservation requirements.
- Steel Cylinders:Standard containment for gaseous and liquid HF across cylinder delivery networks. Corrosion-resistant linings essential for electronic-grade material.
- Totes:Intermediate bulk containers for mini-bulk chemical distribution. Modular ion-exchange skids for hydrogen fluoride polishing are standardizing tote specifications at Taiwanese foundry centers.
- Drums:Aqueous formulations for pharmaceutical and chemical manufacturing. Lower unit value limits investment in specialized handling systems.
- Cans:Small-volume reagent packaging for laboratory and R&D applications. Limited growth exposure relative to fab-scale delivery systems.
Steel Cylinders retain the largest installed base, with Totes expanding most quickly on mini-bulk adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest installed base of acid purification capacity, while South Korea and Taiwan concentrate the most demanding semiconductor-grade consumption. Japan maintains vertical integration advantages through captive fluorite reserves. India's emerging fab investments are creating new qualification corridors for electronic-grade suppliers.
China
Domestic memory and logic fab ramps in Fujian and Zhejiang provinces are absorbing expanding volumes of electronic-grade anhydrous hydrogen fluoride. MEE emissions standards are forcing acid purification upgrades ahead of 2025 compliance deadlines, consolidating output at facilities with captive waste treatment infrastructure. The Yangtze River Delta cluster anchors national production gravity for fluorochemical refining.
South Korea
Samsung and SK Hynix memory operations plus foundry expansions are compressing impurity tolerance thresholds below one part per billion. MFDS certification protocols extend supplier qualification timelines to 18-24 months, elevating barriers for new market entrants. The Seoul Capital Area and Busan-Ulsan corridor concentrate demand for ultra-high-purity material.
Taiwan
TSMC and UMC foundry complexes are transitioning to 2nm process development, requiring sub-ppb metal-ion specifications that only specialized suppliers satisfy. Three-to-five-year supply agreements with fixed purity escalation clauses are displacing spot market purchasing. The Hsinchu Science Park anchors the island's chemical distribution infrastructure.
Japan
Morita Chemical Industries and Stella Chemifa Corporation leverage captive fluorite reserves and vertical acid purification to sustain cost discipline in wafer chemical supply. METI maintains national chemical purity benchmarks that shape import eligibility and local qualification timelines. The Kanto and Kansai industrial belts concentrate domestic refining expertise.
United States
Intel and GlobalFoundries operations in Arizona and New York are driving qualification demand for electronic-grade material. EPA risk management rules elevate compliance costs and barrier thresholds for new acid purification entrants seeking domestic qualification. The Southwest and Northeast corridors represent concentrated consumption nodes.
High-Purity Hydrogen Fluoride Market Competitive Landscape
Top-tier vendors anchor electronic-grade supply to leading foundries, while mid-scale fluorochemical producers compete on cost for industrial applications. Japanese specialists concentrate sub-ppb impurity control capabilities. Chinese state-linked entities dominate captive feedstock access. Strategic moves center on backward integration into acid-grade fluorspar and long-term supply contract lock-ins with memory and logic fabs.
Within the Japanese specialist tier, Morita Chemical Industries and Stella Chemifa Corporation exemplify vertical integration models that combine captive fluorite reserves with multi-stage distillation expertise. Do-Fluoride Chemicals anchors Chinese domestic production capacity for electronic-grade anhydrous material. These three entities represent distinct archetypes: Morita occupies a position defined by upstream resource control, Stella Chemifa exemplifies precision purification protocols, and Do-Fluoride represents state-supported scale expansion.
| Leading Market Players |
|---|
| Morita Chemical Industries |
| Do-Fluoride Chemicals |
| Stella Chemifa Corporation |
| FDAC |
| Yingpeng Group |
| Honeywell International |
| Shaowu Fluoride |
| Zhejiang Kaiheng Electronic Materials |
| Solvay (Zhejiang Lansol) |
| Others |
Pricing and Supply Chain Analysis
Multi-stage distillation retrofits at Chinese fluorochemical plants are simultaneously elevating production costs and concentrating electronic-grade output among facilities with captive waste treatment infrastructure. This technical transition tightens supply-side discipline while compressing margin structures for purification specialists lacking vertical feedstock control.
Pricing Analysis
Capacity additions in Fujian and Zhejiang provinces are reshaping price floors for electronic-grade material. Three-tier pricing structure across premium, standard, and economy levels separates sub-ppb foundry-qualified supply from industrial-grade volumes. Cost compression in standard-tier anhydrous material is intensifying because Chinese state-linked producers are absorbing margin pressure to secure domestic fab contracts. Memory fabs in South Korea exhibit the lowest price sensitivity, while pharmaceutical synthesizers in India represent the most cost-conscious buyer segment.
Supply Chain Analysis
Single-source vulnerability sits with acid-grade fluorspar mining concentration in Mexico, China, and Mongolia. Electronic-grade hydrogen fluoride production draws from fluorite concentrate, sulfuric acid, and ion-exchange resin inputs. Supply chain risk centers on regulatory restriction as China's MEE emissions standards force unplanned scrubber retrofits at purification facilities. Distribution runs through bulk tanker networks to fab chemical distribution centers, with mini-bulk systems gaining share at mid-scale semiconductor operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic-grade hydrogen fluoride offers margin expansion through sub-ppb qualification premiums that widen as 2nm node transitions tighten metal-ion specifications.
For Market Incumbents: Acquire captive acid-grade fluorspar reserves to secure feedstock cost discipline against Chinese state-linked competitors. Lock in three-to-five-year supply agreements with Taiwanese foundries transitioning to 2nm development, leveraging existing MFDS and METI certification credentials to extend qualification timelines for challengers. For New Entrants and Emerging Players: Enter via the Indian Semiconductor Mission corridor, where Gujarat and Tamil Nadu fab investments have created first-mover qualification windows without incumbent supply lock-ins. Target mini-bulk delivery infrastructure partnerships with mid-scale memory operations seeking containerized purification units. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale fluorochemical producers lacking electronic-grade certification but possessing distillation assets convertible to sub-ppb output. Monitor MFDS and METI qualification pipeline announcements as the inflection signal for capacity absorption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Mining | Morita Chemical Industries leverages Mexican acid-grade reserves to sustain Japanese wafer chemical cost discipline. |
| Long-term Supply Agreement | Korean foundries consolidate procurement through fixed-purity-escalation contracts displacing spot market purchasing. |
| Green Manufacturing Transition | Chinese MEE emissions mandates force wet scrubber retrofits that consolidate output at waste-treatment-equipped facilities. |
| Joint Venture | Taiwanese chemical distribution centers partner with ion-exchange skid specialists to localize polishing capacity. |
| Capacity Expansion | Do-Fluoride Chemicals anchors domestic Chinese production for logic and memory fab ramps in Fujian province. |
Research Methodology
Direct dialogue with fluorochemical plant managers, procurement leads at Taiwanese and Korean foundries, ion-exchange equipment specialists, and technical R&D directors at Japanese purification firms grounded the qualitative foundation. Secondary validation drew from customs and trade data, chemical industry association reports, SEC 10-K filings, and national emissions compliance disclosures. Bottom-up capacity modeling and top-down consumption estimates were triangulated to cross-verify output figures.
Segment-level projections across purity grade, end-use industry, packaging format, and regional production hub were generated over the projection horizon. CAGRs were derived from node-specific consumption coefficients tied to semiconductor foundry ramp schedules and fluorochemical plant utilization assumptions. Analysis incorporated MEE compliance timeline scenarios and REACH registration pathway variations as sensitivity inputs.
Inputs from primary field contacts and published regulatory filings were available through the study window; gaps in real-time fab qualification status and proprietary ion-exchange process economics introduce uncertainty bands around capacity absorption timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
Global Epichlorohydrin (ECH) Market
High-Value Chemicals
High Purity Benzenethiol Market
High-Value Chemicals
High-Heat Melamine Foam Market
High-Value Chemicals
Hydroxylamine Market
High-Value Chemicals
Global High Purity Oxygen Market
High-Value Chemicals
Hydroxylamine Sulfate Market
High-Value Chemicals
High Temperature Plastic Market
High-Value Chemicals
High-Nickel NCM Cathode Binder Latex Market
High-Value Chemicals
L-Lysine Hydrochloride (HCL) Market
High-Value Chemicals
High-Purity Acetic Acid Market
High-Value Chemicals
Global 1-Hexanol Market
High-Value Chemicals
High Purity Magnesium Citrate Market
High-Value Chemicals
High-Purity Boehmite Market
High-Value Chemicals
High-K Dielectric Material Market
High-Value Chemicals
Potassium Hydroxide Market
High-Value Chemicals
Sodium Methyl P-Hydroxybenzoate Market