
 Asia-Pacific Hydrogen Bromide Market | 2026-2036
Asia-Pacific Hydrogen Bromide Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hydrogen Bromide Market Insights
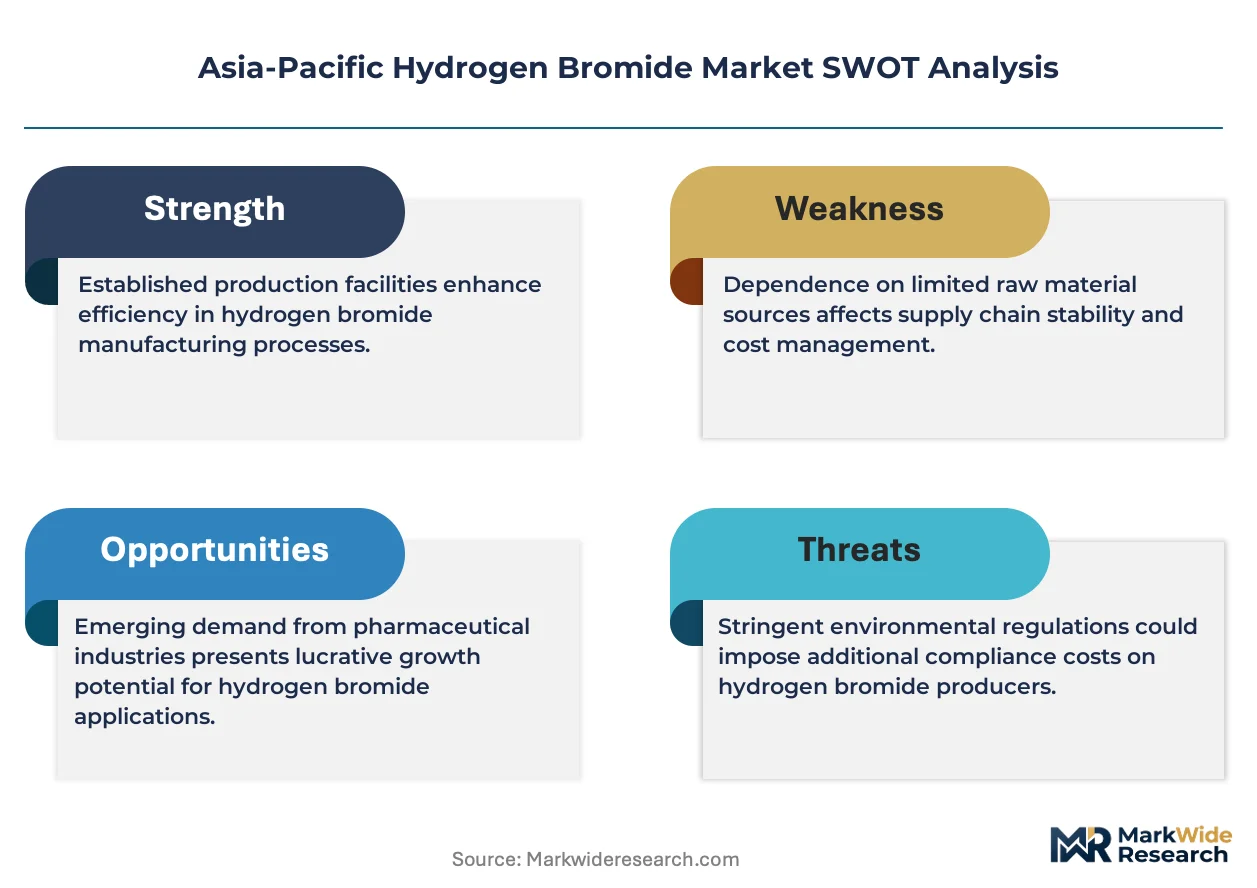
On-site production contracts are recalibrating how hydrogen bromide moves through Asia-Pacific supply chains, shifting capital risk from buyers to suppliers. Showa Denko K.K. anchors its position through captive electrolysis capacity at Japanese petrochemical complexes. Tosoh Corporation leverages advanced purification systems to serve Taiwan's semiconductor foundries. Tata Chemicals Ltd competes on bulk bromine backward integration from Indian salt flat operations.
Hydrogen bromide is a corrosive, colorless gas with molecular formula HBr, typically manufactured by direct combination of hydrogen and bromine over a platinum catalyst at elevated temperatures; it serves as a critical reagent for alkyl bromide synthesis and as an etchant in gallium arsenide wafer processing. Hydrobromic acid commands the largest volume share across the product type spectrum, reflecting its ubiquity in pharmaceutical intermediate manufacturing. Reagent-grade anhydrous hydrogen bromide captures the fastest expansion trajectory, propelled by Taiwan Semiconductor Manufacturing and Samsung Foundry demand for sub-7nm node etching chemistry. Flame retardants within the application dimension remain a mature revenue pool, with margin compression from bromine price volatility offset by long-term automotive wiring harness contracts.
Japan's METI enforces High Pressure Gas Safety Act standards that mandate 99.999% purity certification for electronics-grade hydrogen bromide, effectively filtering out non-specialized Chinese producers from Japanese fab supply chains. China's SAMR administers GB/T industrial chemical classifications that determine import licensing requirements and domestic manufacturing quotas for bromine derivatives. India's CEA regulates captive power usage for electrolytic hydrogen production, shaping where on-site HBr generation proves economically viable. Stakeholders must monitor how South Korea's K-Battery strategy redirects bromine flows from flame retardants toward next-generation solid-state electrolyte research.
Market Dynamics
On-site production contracts are redistributing capital risk across Asia-Pacific hydrogen bromide supply chains, with captive electrolysis capacity at Japanese petrochemical complexes and bulk bromine backward integration from Indian salt flat operations creating divergent competitive moats.
Growth Catalysts
- Semiconductor node shrinkage:Sub-7nm etching chemistry requirements at Taiwan Semiconductor Manufacturing and Samsung Foundry pull reagent-grade anhydrous hydrogen bromide volumes upward.
- METI High Pressure Gas Safety Act:Japan's 99.999% purity certification mandate for electronics-grade product filters out non-specialized producers and secures premium positioning for compliant suppliers.
- K-Battery strategy redirection:South Korea's solid-state electrolyte research programs siphon bromine flows from mature flame retardant applications into next-generation battery chemistry development.
Market Restraints
- Bromine feedstock volatility:Margin compression in flame retardant segments stems from elemental bromine price swings tied to Dead Sea extraction rates and Chinese environmental curtailments.
- Supply concentration risk:Eastern China's chemical manufacturing corridors dominate global merchant supply, creating single-point vulnerability for Taiwan and South Korean fab procurement.
- Technical purity ceiling:99.999% electronics-grade certification requires advanced purification systems that most Indian and Southeast Asian producers cannot economically deploy.
Strategic Opportunities
- Indian captive power arbitrage:CEA-regulated electrolytic hydrogen production incentives enable on-site HBr generation economics at Gujarat and Tamil Nadu chemical parks.
- Pharmaceutical intermediate expansion:Hydrobromic acid demand for alkyl bromide synthesis in China's Yangtze River Delta specialty chemical clusters offers volume growth outside semiconductor cyclicality.
- GB/T standard harmonization:China's SAMR industrial chemical classification reforms may streamline import licensing for qualified Japanese and Korean electronics-grade suppliers.
Industry Challenges
- Electronics-grade certification timelines:Japanese fab qualification protocols require 18-24 month validation cycles that lock out new entrants regardless of technical capability.
- Electrolysis equipment capex intensity:On-site HBr production demands platinum catalyst systems and corrosion-resistant containment infrastructure that strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hydrogen Bromide Market |
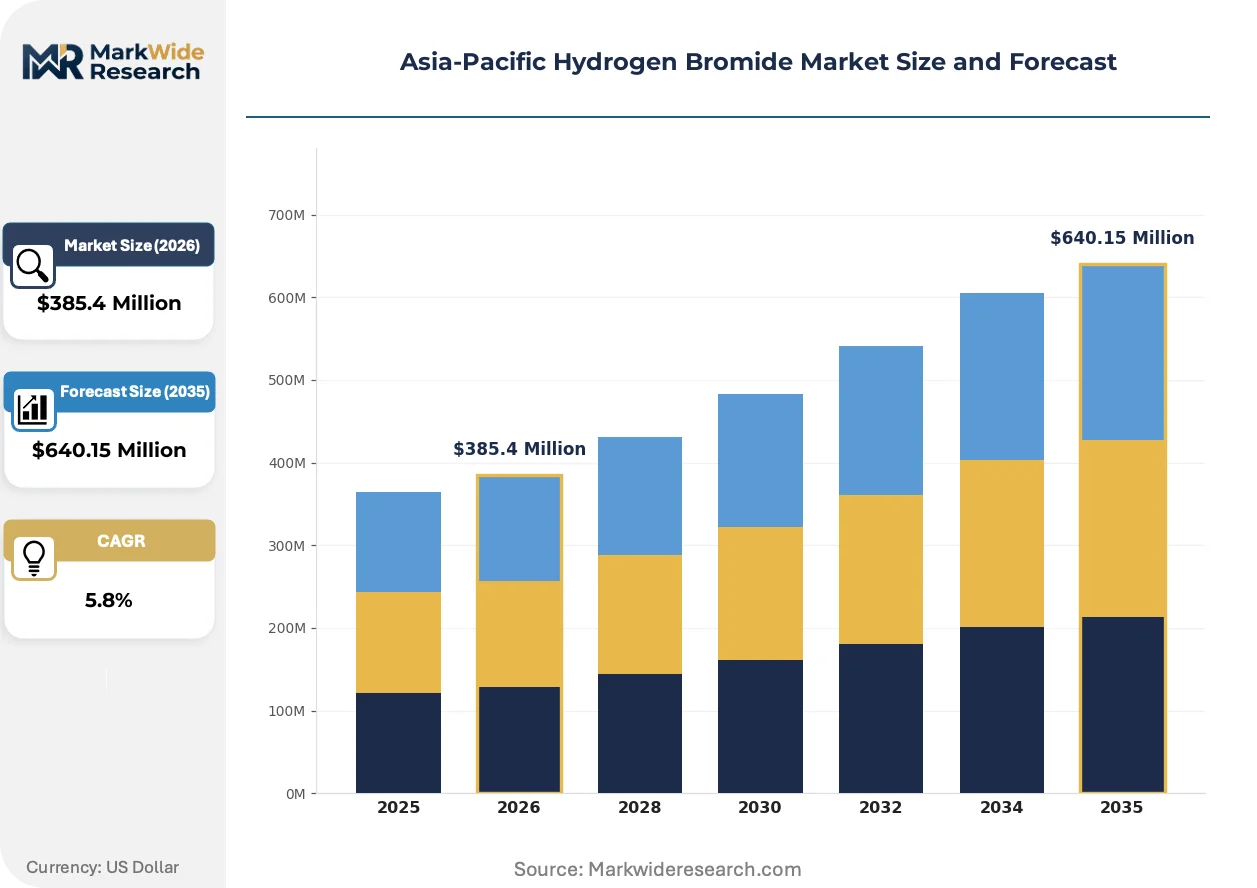
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous Hydrogen Bromide, Hydrobromic Acid, Bromide Salts, Reactants End User: Pharmaceuticals, Agriculture, Electronics, Chemical Manufacturing Application: Reagent in Organic Synthesis, Water Treatment, Flame Retardants, Battery Production Delivery Mode: Bulk Supply, Cylinder Supply, On-site Production, Specialty Packaging |
| Companies Covered | Showa Denko K.K., Tosoh Corporation, Tata Chemicals Ltd, Neogen Chemical Ltd, Triveni Interchem Private Limited, Sontara Organo Industries, Verni Gas Corporation, Air Liquide, Linde plc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hydrogen Bromide Market Trends and Innovations
Advanced purification technologies and procurement model restructuring are compressing supplier margins while elevating technical performance requirements across Asia-Pacific semiconductor and pharmaceutical end-uses.
Membrane-based gas purification is consolidating quality differentiation in electronics-grade hydrogen bromide supply. Taiwanese foundries now specify membrane-polished product for sub-5nm node etching. This technology is consolidating market share around suppliers with captive membrane fabrication capabilities.
Japan's METI is tightening High Pressure Gas Safety Act enforcement for hydrogen bromide transport and storage infrastructure. Industrial consequence includes mandatory vessel recertification cycles that favor integrated producers with in-house logistics networks. Electronics-grade product lines absorb the bulk of compliance cost pass-through.
Long-term take-or-pay contracts are displacing spot procurement at major Taiwanese and South Korean fabs. Semiconductor manufacturers seek price certainty across three-year capex cycles. This pattern concentrates procurement power among vertically integrated Japanese and Korean suppliers with demonstrated volume reliability.
Asia-Pacific Hydrogen Bromide Market Segmentation
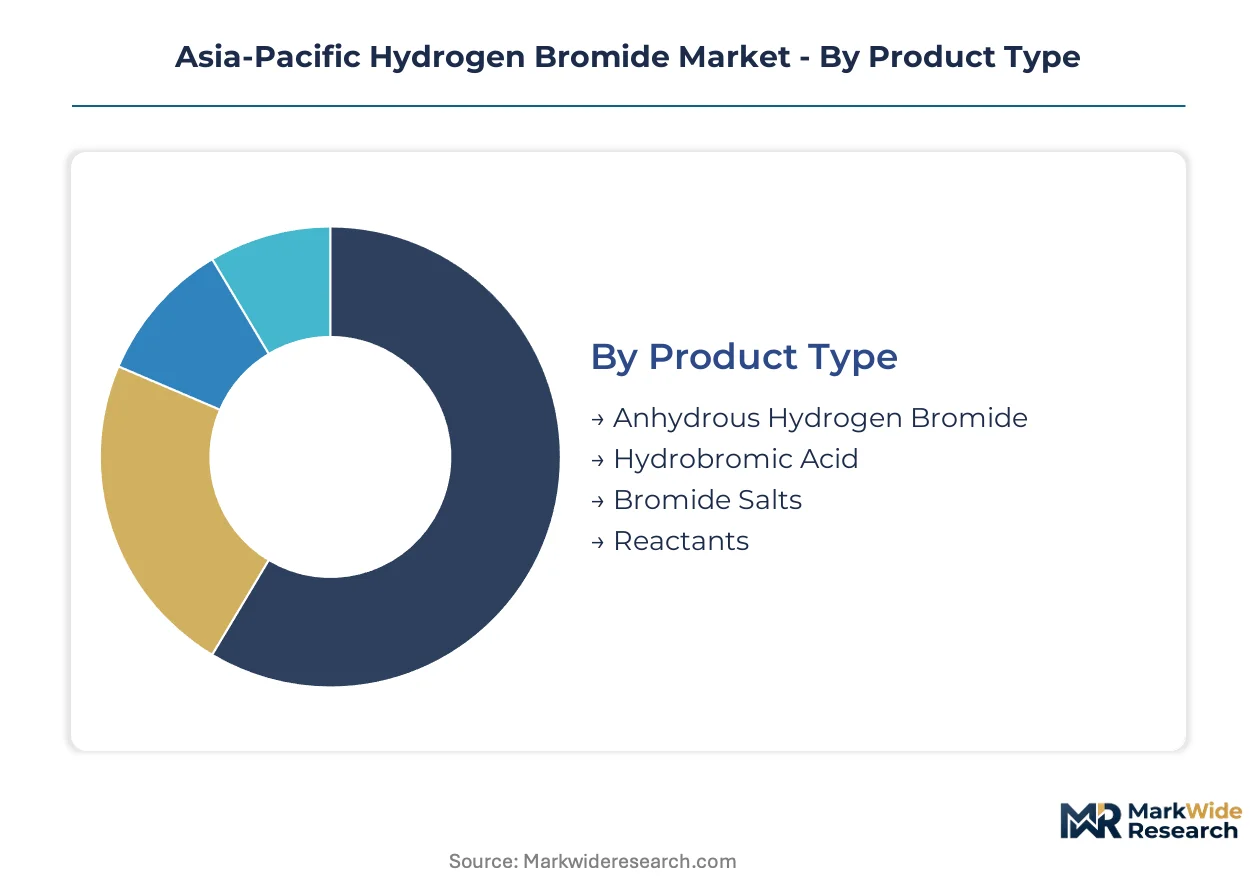
Segmentation in Asia-Pacific hydrogen bromide supply reveals how purity grades and delivery economics partition procurement power. Electronics-grade specifications at Taiwanese foundries diverge sharply from bulk acid contracts in Chinese pharmaceutical corridors.
Product Type:
Upgrade cycles in semiconductor etching chemistry and pharmaceutical intermediate synthesis are forcing specification splits across the product portfolio.
- Anhydrous Hydrogen Bromide:A corrosive, colorless gas manufactured through direct combination of hydrogen and bromine over platinum catalysts at elevated temperatures. Demand concentrates at Taiwan Semiconductor Manufacturing and Samsung Foundry for sub-7nm node gallium arsenide wafer etching, where METI-mandated 99.999% purity certification filters out non-specialized producers.
- Hydrobromic Acid:An aqueous solution of hydrogen bromide commanding the largest volume footprint across the product spectrum. Demand concentrates in eastern China's Yangtze River Delta specialty chemical clusters for alkyl bromide pharmaceutical intermediate manufacturing, with long-term automotive wiring harness contracts offsetting bromine feedstock price volatility.
- Bromide Salts:Derivative compounds serving agricultural and industrial applications with lower purity thresholds.
- Reactants:Specialty-grade formulations for custom organic synthesis operations.
Volume placements concentrate in Hydrobromic Acid; the faster expansion belongs to Anhydrous Hydrogen Bromide.
End User:
Cost tier stratification separates captive on-site production economics from merchant supply premiums across end-use categories.
- Electronics:Taiwanese foundries and South Korean memory manufacturers specify membrane-polished product for sub-5nm node etching. Long-term take-or-pay contracts displace spot procurement across three-year capex cycles, concentrating procurement power among vertically integrated Japanese and Korean suppliers.
- Pharmaceuticals:Alkyl bromide synthesis for active pharmaceutical ingredient intermediates drives hydrobromic acid consumption. China's GB/T industrial chemical classifications determine import licensing requirements and domestic manufacturing quotas that shape supplier access.
- Agriculture:Methyl bromide alternatives and soil fumigation applications with declining volume trajectories.
- Chemical Manufacturing:Bulk bromine derivative production serving flame retardant and intermediate supply chains.
Electronics commands premium pricing; pharmaceuticals offers volume stability outside semiconductor cyclicality.
Application:
Application maturity curves diverge sharply between established flame retardant chemistry and emerging solid-state electrolyte research.
- Flame Retardants:Mature revenue pool in automotive wiring harness and construction materials. Margin compression from Dead Sea bromine extraction rates and Chinese environmental curtailments strains producer economics.
- Reagent in Organic Synthesis:Pharmaceutical intermediate manufacturing in China's chemical manufacturing corridors and Indian Gujarat specialty chemical parks. India's CEA-regulated captive power incentives enable on-site HBr generation economics at selected locations.
- Water Treatment:Municipal and industrial scale applications with standardized purity requirements.
- Battery Production:South Korea's K-Battery strategy redirects bromine flows from flame retardants toward next-generation solid-state electrolyte research programs.
Flame Retardants anchor current volume; Battery Production is gaining share fastest.
Delivery Mode:
Supply concentration in eastern China's chemical corridors shapes procurement risk profiles across delivery configurations.
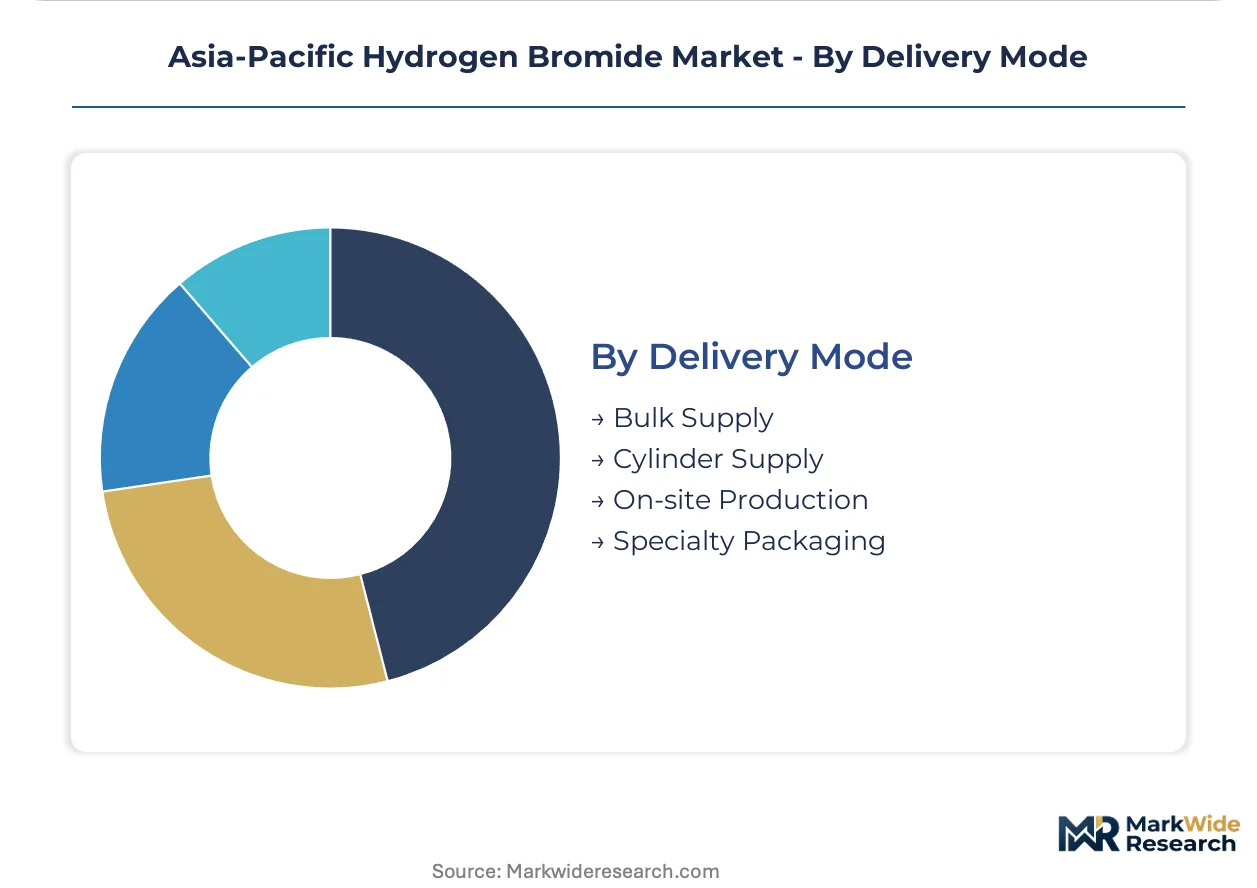
- On-site Production:Captive electrolysis capacity at Japanese petrochemical complexes and Indian salt flat operations redistributes capital risk from buyers to suppliers. Showa Denko K.K. anchors this model through integrated bromine-hydrogen infrastructure.
- Cylinder Supply:Electronics-grade product for semiconductor foundries requiring membrane-based gas purification and METI High Pressure Gas Safety Act compliance for transport vessel recertification.
- Bulk Supply:Merchant hydrobromic acid for pharmaceutical and chemical manufacturing with price exposure to elemental bromine volatility.
- Specialty Packaging:Corrosion-resistant containment for high-purity anhydrous product with stringent handling protocols.
On-site Production captures capital commitment; Cylinder Supply carries the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in eastern China while consumption concentrates at Taiwanese foundries and South Korean memory fabs, creating a geographic mismatch that shapes procurement risk profiles across the region.
China
Yangtze River Delta specialty chemical corridors generate bulk hydrobromic acid for pharmaceutical intermediate synthesis. SAMR administers GB/T industrial chemical classifications that determine import licensing requirements and domestic manufacturing quotas for bromine derivatives. Environmental curtailments in Shandong Province periodically constrain elemental bromine feedstock availability.
Japan
METI enforces High Pressure Gas Safety Act standards mandating 99.999% purity certification for electronics-grade hydrogen bromide, filtering non-specialized producers from domestic fab supply chains. Kanto region petrochemical complexes host captive electrolysis infrastructure. Showa Denko K.K. anchors integrated bromine-hydrogen production at these coastal facilities.
South Korea
Samsung Foundry and SK Hynix pull reagent-grade anhydrous product for sub-7nm node etching chemistry. The K-Battery strategy redirects bromine flows from flame retardants toward solid-state electrolyte research programs. Metropolitan Seoul semiconductor clusters negotiate long-term take-or-pay contracts to secure volume reliability.
Taiwan
Taiwan Semiconductor Manufacturing specifies membrane-polished hydrogen bromide for sub-5nm node processing, the most demanding purity threshold in regional procurement. Taichung and Tainan science parks concentrate foundry demand. Long-term contracts displace spot procurement across three-year capex cycles.
India
Gujarat and Tamil Nadu chemical parks exploit CEA-regulated captive power incentives for on-site HBr generation economics. Tata Chemicals Ltd leverages bulk bromine backward integration from Rajasthan salt flat operations. Pharmaceutical intermediate demand in Hyderabad and Ahmedabad provides volume stability outside semiconductor cyclicality.
Asia-Pacific Hydrogen Bromide Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated supply structure. Japanese and Korean integrated chemical groups control premium electronics-grade supply through captive electrolysis and advanced purification infrastructure. Indian salt-flat operators compete on bulk bromine feedstock cost. Chinese merchant producers dominate volume hydrobromic acid but face purity ceiling constraints. Strategic moves concentrate on long-term foundry qualification cycles and on-site production contract structures.
Among Japan-based chemical conglomerates, Showa Denko K.K. and Tosoh Corporation exemplify the integrated producer archetype with captive infrastructure and membrane purification capabilities. Tata Chemicals Ltd represents the backward-integrated cost competitor leveraging mineral extraction assets. These three anchors illustrate how divergent asset bases create non-overlapping competitive moats across purity grades and delivery modes.
| Leading Market Players |
|---|
| Showa Denko K.K. |
| Tosoh Corporation |
| Tata Chemicals Ltd |
| Neogen Chemical Ltd |
| Triveni Interchem Private Limited |
| Sontara Organo Industries |
| Verni Gas Corporation |
| Air Liquide |
| Linde plc |
| Others |
Pricing and Supply Chain Analysis
Membrane-based gas purification adoption at Taiwanese foundries simultaneously compresses supplier margins and concentrates procurement power among integrated producers with captive membrane fabrication capabilities. This technical transition rewards Japanese and Korean suppliers with advanced purification infrastructure while filtering out merchant producers dependent on third-party polishing services.
Pricing Analysis
Margin tightening in electronics-grade tiers reflects the capital intensity of 99.999% purity certification and METI-mandated vessel recertification cycles. Three-tier pricing structure across electronics-grade, reagent-grade, and industrial-grade levels separates membrane-polished product for sub-5nm etching from standard acid contracts. Cost-down pressure on hydrobromic acid accelerates because Chinese environmental curtailments in Shandong Province periodically constrain elemental bromine feedstock availability. Pharmaceutical intermediate manufacturers in the Yangtze River Delta demonstrate highest price sensitivity due to commodity spot exposure, while Taiwanese foundries accept premium positioning for volume reliability.
Supply Chain Analysis
Regional distribution centers in eastern China's chemical manufacturing corridors anchor hub-and-spoke patterns serving Taiwanese and South Korean fab demand. Production gravity centers on China, Japan, and India, with captive electrolysis infrastructure at Japanese petrochemical complexes and bulk bromine backward integration from Indian salt flat operations. Raw material dependencies draw from Dead Sea bromine extraction, platinum catalyst systems, and corrosion-resistant containment alloys. Single-source vulnerability concentrates in eastern China's merchant supply base for Taiwan and South Korean procurement. Distribution runs through long-term take-or-pay contracts displacing spot procurement at major semiconductor fabs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific hydrogen bromide market functions as a vertical-integration race where captive bromine-hydrogen infrastructure and membrane purification capabilities determine competitive survival. Players are pursuing upstream control over elemental bromine feedstocks and downstream qualification at Taiwanese foundries as the decisive levers.
For Market Incumbents: Cement position through captive membrane fabrication capabilities and accelerated qualification timelines at Samsung Foundry and Taiwan Semiconductor Manufacturing. METI's tightening High Pressure Gas Safety Act enforcement creates regulatory moats that non-specialized Chinese producers cannot cross. Capacity addition in Gujarat chemical parks exploiting CEA-regulated captive power incentives secures cost-competitive hydrobromic acid supply for pharmaceutical intermediate demand. For New Entrants and Emerging Players: Capture white-space in Indian on-site HBr generation contracts at Tamil Nadu chemical parks where CEA incentives enable competitive electrolysis economics. The most penetrable segment sits in reagent-grade anhydrous product for pharmaceutical intermediate synthesis outside semiconductor cyclicality. A go-to-market angle emphasizing GB/T standard harmonization with China's SAMR reforms streamlines import licensing for qualified regional suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of Indian salt-flat operators with backward-integrated bromine assets and Japanese membrane purification specialists serving sub-5nm foundry demand. Long-term viability across the analysis window hinges on demonstrated volume reliability through three-year capex cycles and METI certification maintenance. The signal to watch is qualification protocol completion at Taiwanese foundries, which locks in procurement relationships regardless of technical capability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive bromine extraction from Indian salt flats eliminates feedstock price volatility exposure. |
| Capacity Expansion | On-site HBr generation at Japanese petrochemical complexes secures METI compliance for electronics-grade supply. |
| Long-term Supply Agreement | Three-year take-or-pay contracts with Taiwanese foundries lock in volume across semiconductor capex cycles. |
| Joint Venture | Membrane fabrication partnerships consolidate quality differentiation for sub-5nm node etching chemistry. |
| Green Manufacturing Transition | CEA-regulated captive power incentives enable electrolytic hydrogen production with favorable carbon accounting. |
Research Methodology
Customs and trade data, METI regulatory filings, and semiconductor equipment capex disclosures formed the secondary backbone of this analysis. Primary interviews with plant managers at Japanese petrochemical complexes, procurement leads at Taiwanese foundries, distribution channel partners in eastern China, and technical R&D directors at Indian chemical parks validated demand assumptions. Bottom-up and top-down triangulation reconciled volume estimates from bromine feedstock flows with end-use consumption patterns at semiconductor and pharmaceutical manufacturers.
Bottom-up modeling anchored forecasts in segment-level demand drivers across grade tier, end-use industry, and regional production hub dimensions. Top-down validation cross-checked aggregate market size against elemental bromine consumption trends and hydrogen electrolysis capacity announcements. CAGRs were derived from fitted growth curves calibrated to foundry node transition timelines and pharmaceutical intermediate expansion patterns. Industry-specific inputs included MEMS capacitance data for etching chemistry intensity and K-Battery strategy funding allocations for solid-state electrolyte research.
The model holds under stable semiconductor capex cycles and continued METI enforcement intensity; deviation in Chinese environmental policy stringency or Taiwanese foundry qualification timelines would shift volume trajectories. Forecasts reflect assumptions about bromine extraction rates from Dead Sea operations and platinum catalyst system availability. Periodic stress-testing of base assumptions against actual foundry procurement contract announcements and SAMR regulatory reform implementation is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
Global High Purity AHCL Market
High-Value Chemicals
High-Temperature Epoxy Market
High-Value Chemicals
High Purity Silica Market
High-Value Chemicals
Ultra-High Purity Hydrofluoric Acid Market
High-Value Chemicals
High-Silica Zeolite Market
High-Value Chemicals
Global High Temperature Thermoplastics (Htts) Market
High-Value Chemicals
Alpha Hydroxy Acid Market
High-Value Chemicals
Potassium Hydroxide Market
High-Value Chemicals
High Purity Isobutylene (HPIB) Market
High-Value Chemicals
Global 1-Hexanol Market
High-Value Chemicals
Hydroxylamine Market
High-Value Chemicals
Phenanthroline Monohydrate Market
High-Value Chemicals
High Temperature Plastic Market
High-Value Chemicals
Hydroxocobalamin Chloride Market
High-Value Chemicals
Hydroxycarboxylic Acids Market
High-Value Chemicals
Ultra-High-Purity Anhydrous Hydrogen Chloride (Hcl) Gas Market