
 Hydroquinone Market | 2026-2036
Hydroquinone Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroquinone Market Outlook
Aftermarket technical service revenue is reshaping margin distribution across the hydroquinone value chain. Solvay leverages its integrated phenol derivative platform to sustain cost leadership in photographic-grade supply. Mitsui Chemicals anchors its position through captive hydrogen peroxide feedstock and Asian manufacturing scale.
Hydroquinone (C6H4(OH)2) is a dihydric phenol produced via oxidation of p-diisopropylbenzene or hydroperoxide rearrangement, with melting point at 172°C and critical use as a polymerization inhibitor and photographic developer. Pharmaceutical and dermatological applications command premium pricing due to USP-grade purification requirements and prescription-channel regulation. Cosmetic formulations in creams and serums face margin compression from regulatory restrictions in key Western markets, while powder and gel forms serve industrial antioxidant demand with steadier volume economics.
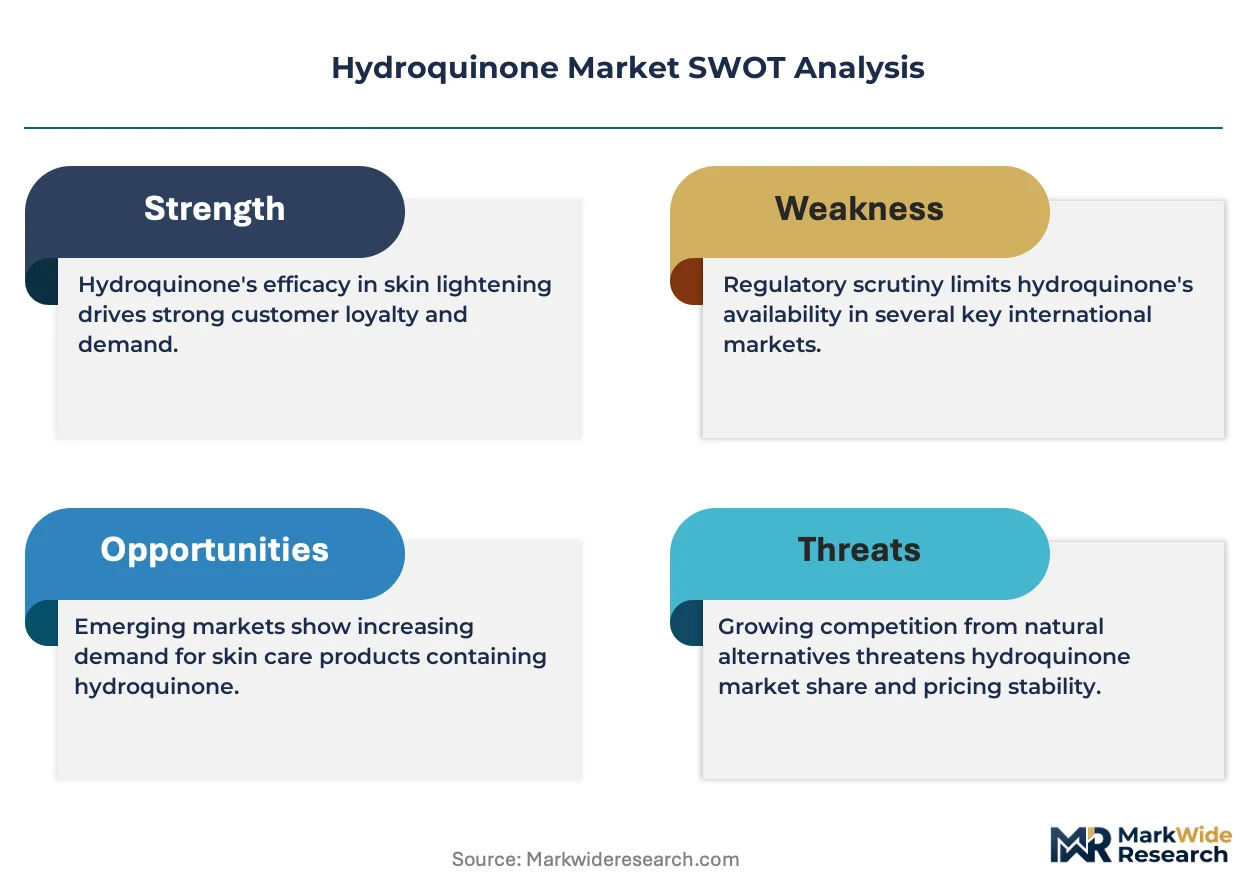
The US FDA restricts over-the-counter hydroquinone concentrations to 2% while requiring prescription status above that threshold, directly channeling demand through dermatologists and hospital pharmacies. Europe's ECHA classification of hydroquinone as a skin sensitizer under REACH and the EU's MDR framework for dermatological devices are elevating compliance costs for cosmetic-grade suppliers. Stakeholders must monitor divergence between pharmaceutical purity standards and tightening cosmetic safety thresholds when allocating R&D and capacity investments.
Market Dynamics
REACH and RoHS compliance requirements in Europe are tightening purity thresholds for cosmetic-grade material, forcing capacity reallocation toward pharmaceutical-grade streams where regulatory arbitrage still permits margin capture.
Growth Catalysts
- Photographic-grade polymerization inhibitors:Specialty chemical demand from high-performance resin manufacturers in Japan and South Korea sustains volume baselines for technical-grade producers.
- CDSCO registration pathways:India's streamlined API approval processes accelerate domestic manufacturing scale-up for dermatological actives.
- Melasma treatment protocols:Dermatology clinic expansion across Southeast Asia channels prescription-grade procurement through hospital pharmacy networks.
Market Restraints
- Phenol derivative feedstock volatility:Crude benzene price swings transmit directly to hydroquinone production economics, compressing converter margins during upstream spikes.
- EU skin sensitizer classification:ECHA's REACH designation elevates cosmetic-grade compliance costs and restricts formulation concentrations below therapeutic thresholds.
- Arbutin and kojic acid substitution:Natural-derived skin lightening actives capture over-the-counter positioning as retailers delist hydroquinone-based SKUs.
Strategic Opportunities
- USP-grade contract manufacturing:India's PLI scheme for active pharmaceutical ingredients subsidizes capital deployment for export-oriented purification facilities.
- Photographic chemical recycling loops:Spent developer recovery and re-refining technologies open closed-loop supply arrangements with commercial film processors.
- Polymerization inhibitor blends:Custom antioxidant packages for styrene and acrylic monomer producers command formulation service premiums beyond commodity hydroquinone sales.
Industry Challenges
- Pharmaceutical-grade validation timelines:USP certification cycles extend 18-24 months, freezing capacity decisions until regulatory clearance confirms.
- Cross-contamination controls:Cosmetic and pharmaceutical grade segregation demands dedicated process trains, doubling capital intensity for multi-stream producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroquinone Market |
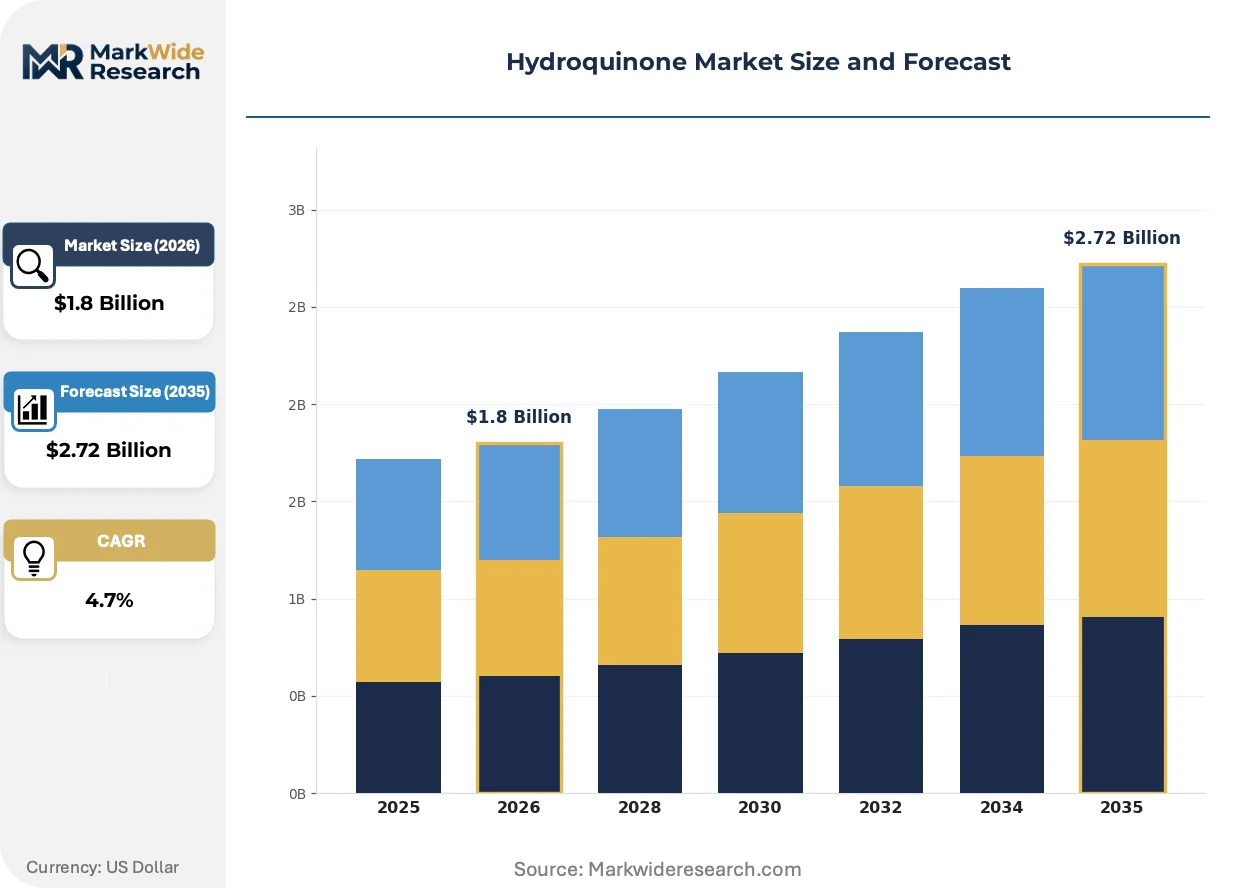
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Lightening, Creams, Gels, Serums Application: Cosmetic, Pharmaceutical, Dermatological, Medical End User: Beauty Clinics, Dermatologists, Hospitals, Home Users Form: Liquid, Cream, Powder, Gel |
| Companies Covered | Solvay, Syensqo, Eastman Chemical Company, Merck KGaA, BASF SE, Mitsui Chemicals Inc., UBE Corporation, Lanxess AG, Camlin Fine Sciences Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroquinone Market Strategic Shifts
Continuous processing technologies and regulatory divergence between pharmaceutical purity mandates and cosmetic safety restrictions are fragmenting technical pathways and supplier specialization.
Membrane-based purification systems are collapsing the cost structure for USP-grade production. Specialty chemical producers in Germany and Switzerland deploy nanofiltration cascades to replace solvent-intensive crystallization. This compression enables mid-scale entrants to challenge incumbent photographic-grade suppliers on dermatological material purity.
Europe's MDR framework for dermatological devices now captures compounded hydroquinone creams under medical device classification. EMA and notified body coordination extends approval timelines for novel delivery formats. Hospital procurement teams in France and Italy are consolidating supplier lists to pre-qualified MDR certificate holders.
Hospital pharmacy centralization is consolidating dermatological dispensing authority. Large health system formularies in the United States and Spain now mandate sole-source contracts for compounded actives, displacing independent compounding pharmacies. This concentration favors API manufacturers with validated sterile processing capabilities and 503B outsourcing facility registrations.
Hydroquinone Market Segmentation
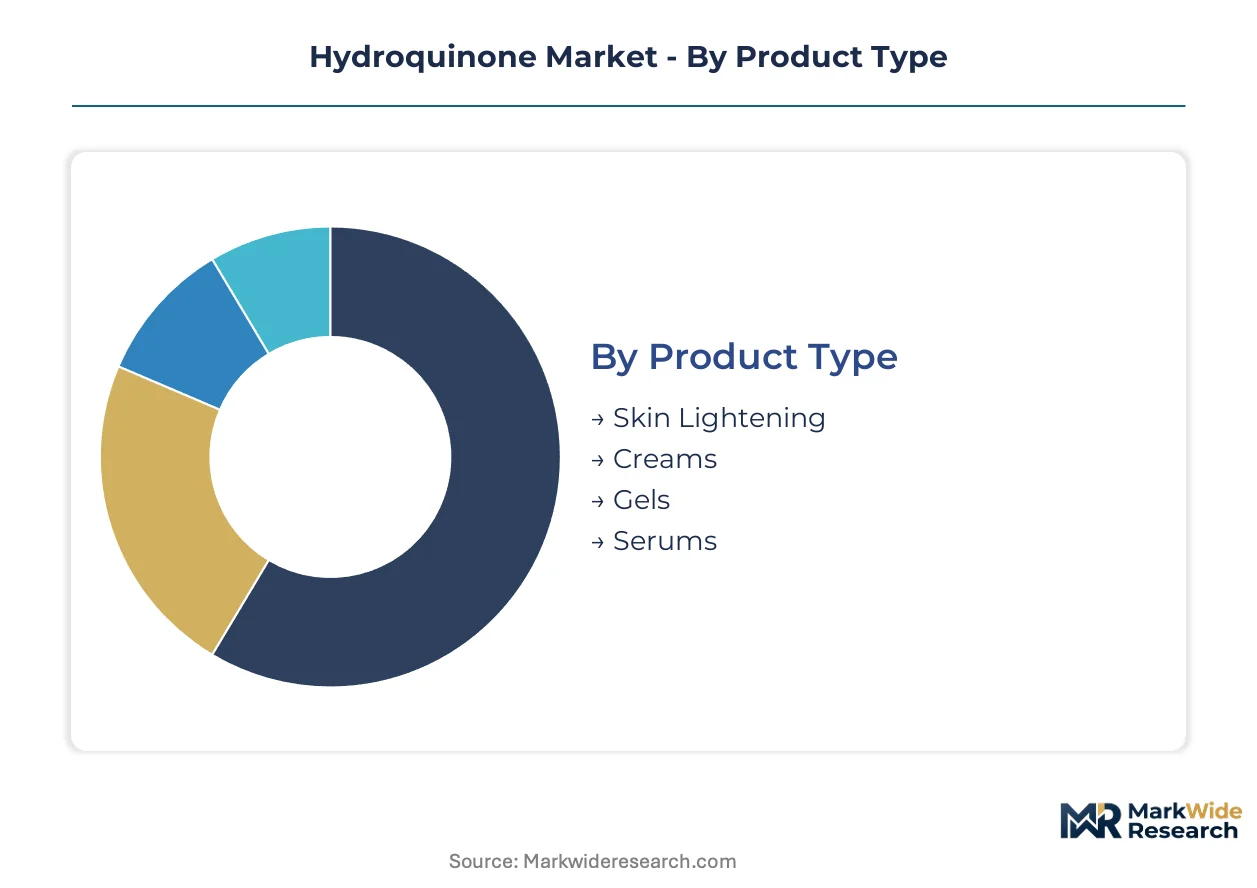
Product form and regulatory grade determine margin capture across hydroquinone applications. Pharmaceutical and cosmetic streams diverge on purity thresholds, while delivery format shapes channel access and pricing power.
Product Type:
Cost tier separates prescription-grade actives from mass-market cosmetic formulations, with regulatory compliance burden driving the wedge between segments.
- Skin Lightening:High-purity hydroquinone concentrates formulated for melasma and hyperpigmentation protocols. Dermatology networks in India channel prescription volumes through hospital pharmacies as beauty clinic chains expand compounding capacity.
- Creams:Emulsion-based delivery systems dominate over-the-counter positioning where FDA concentration limits cap at 2%. Retail delisting pressure in Western markets compresses margin pools as arbutin substitutes capture shelf space.
- Gels:Hydrogel matrices enable controlled release for professional peel applications. Aesthetic medicine practices in South Korea favor gel formats for combination therapy protocols.
- Serums:Lightweight aqueous solutions targeting at-home users through e-commerce dermatology platforms. Concentration limitations under EU skin sensitizer classifications restrict therapeutic efficacy claims.
Skin Lightening commands the established base. The steepest expansion runs through Serums.
Application:
Regulatory jurisdiction fragments the market into prescription-controlled and consumer-accessible channels with divergent compliance architectures.
- Cosmetic:Topical brightening products subject to REACH skin sensitizer thresholds and FDA OTC concentration ceilings. ECHA classifications in Europe force reformulation cycles as retailers delist non-compliant SKUs.
- Pharmaceutical:USP-grade actives for compounded dermatological preparations requiring sterile processing validation. CDSCO registration pathways in India accelerate domestic API scale-up for export markets.
- Dermatological:Clinic-dispensed treatments under physician supervision with prescription-channel pricing premiums. MDR framework capture in France and Italy extends approval timelines for novel delivery formats.
- Medical:Hospital formulary procurement of high-purity material for institutional compounding. Centralized purchasing in US health systems consolidates supplier lists to 503B-registered facilities.
Cosmetic retains volume leadership. Medical is climbing the fastest on hospital procurement consolidation.
End User:
Customer type determines specification stringency, with institutional buyers enforcing validation standards that exclude commodity-grade suppliers.
- Beauty Clinics:Aesthetic medicine chains in Southeast Asia drive procurement of compounded hydroquinone for in-clinic peel protocols. CDSCO streamlined approvals enable Indian clinic networks to source domestic API.
- Dermatologists:Prescription authority channels USP-grade demand through specialty pharmacies. US FDA 2% OTC threshold directs therapeutic concentrations into physician-controlled dispensing.
- Hospitals:Centralized pharmacy formularies mandate sole-source contracts for sterile actives. Spanish and Italian health systems consolidate supplier lists to MDR certificate holders.
- Home Users:E-commerce platforms and mass retail access concentration-limited cosmetic formulations. EU skin sensitizer warnings suppress consumer confidence in hydroquinone-based products.
Dermatologists anchor the premium tier. Beauty Clinics are gaining share fastest on network expansion.
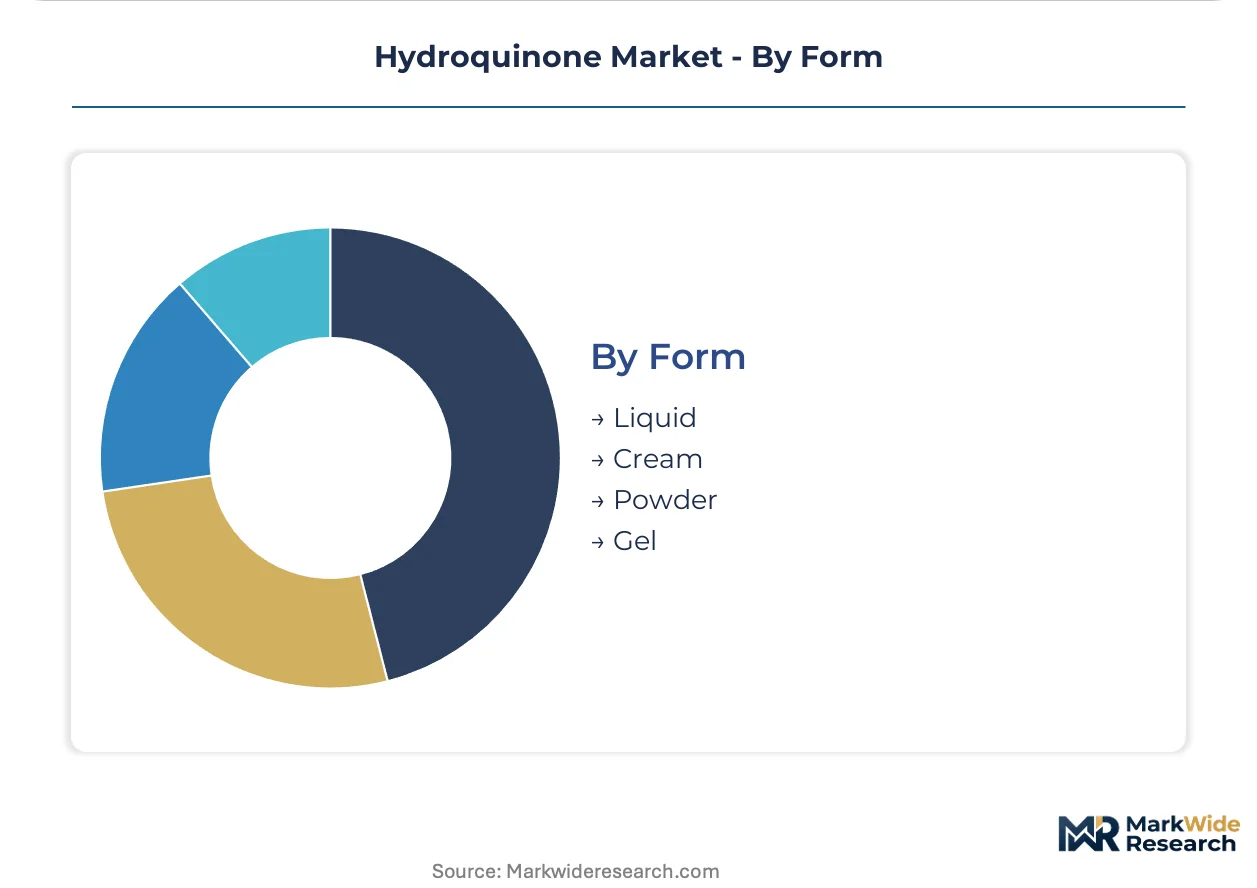
Form:
Physical state dictates processing requirements and stability profiles, with liquid and powder formats serving distinct industrial and clinical endpoints.
- Liquid:Aqueous solutions for photographic developer and polymerization inhibitor applications. Japanese and South Korean resin manufacturers sustain technical-grade baselines.
- Cream:Oil-in-water emulsions for topical dermatological delivery with shelf-stability requirements. US FDA OTC regulations constrain active loading in consumer-facing formats.
- Powder:Crystalline hydroquinone for industrial antioxidant blends and API manufacturing feedstock. Photographic chemical recycling loops in Germany recover spent developer for re-refining.
- Gel:Hydrogel matrices enabling controlled-release kinetics for professional aesthetic procedures. Swiss and German membrane purification systems collapse USP-grade production costs.
Powder dominates industrial offtake. Gel is expanding most quickly on aesthetic medicine adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Hospital procurement teams in Germany absorb USP-grade premiums without volume contraction. Indian beauty clinics negotiate aggressively on compounded API costs. Southeast Asian aesthetic chains prioritize supply security over unit economics.
Germany
Membrane purification specialists in Baden-Württemberg collapse USP-grade production costs through nanofiltration cascades. ECHA's REACH skin sensitizer classification forces cosmetic-grade reformulation cycles. Frankfurt and Ludwigshafen host pharmaceutical-grade contract manufacturing clusters serving EU hospital formularies.
United States
Hospital pharmacy centralization in Texas and Florida consolidates dermatological dispensing authority through sole-source contracts. FDA's 2% OTC concentration ceiling channels therapeutic demand through prescription channels. New Jersey and Delaware house 503B-registered outsourcing facilities capturing institutional procurement.
India
Domestic API manufacturing scales rapidly under CDSCO streamlined registration pathways for dermatological actives. The PLI scheme subsidizes capital deployment for export-oriented purification facilities. Maharashtra and Gujarat host expanding beauty clinic networks sourcing compounded hydroquinone for in-clinic peel protocols.
Japan
Photographic-grade polymerization inhibitor demand from resin manufacturers sustains technical-grade volume baselines. METI oversees chemical safety standards for industrial antioxidant applications. Osaka and Nagoya anchor specialty chemical production serving high-performance monomer producers.
South Korea
Aesthetic medicine practices in Seoul favor gel formats for combination therapy protocols. MFDS regulates cosmetic-grade concentration limits under pharmaceutical safety frameworks. Busan-Ulsan industrial clusters supply photographic chemical derivatives to Asian film processors.
Hydroquinone Market Competitive Environment
Integrated phenol derivative platforms and captive hydrogen peroxide feedstock operators split the market between cost leadership and supply security. The structure concentrates around three strategic archetypes: European chemical conglomerates with backward integration into phenol chains, Asian petrochemical groups leveraging captive peroxide supply, and Indian API specialists exploiting regulatory arbitrage on USP-grade purification. Dominant competitive moves include capacity reallocation toward pharmaceutical-grade streams and membrane technology licensing to collapse purification economics.
Among European chemical conglomerates, Solvay anchors integrated phenol derivative positioning while BASF SE occupies multinational diversified chemical archetype. Mitsui Chemicals represents Asian petrochemical scale with captive feedstock advantages. These three exemplify divergent strategic vectors: European incumbents defend through process integration, Japanese majors leverage hydrogen peroxide economics, and emerging Indian API houses exploit regulatory pathway advantages.
| Leading Market Players |
|---|
| Solvay |
| Syensqo |
| Eastman Chemical Company |
| Merck KGaA |
| BASF SE |
| Mitsui Chemicals Inc. |
| UBE Corporation |
| Lanxess AG |
| Camlin Fine Sciences Ltd |
| Others |
Value Chain & Pricing Dynamics
The Rotterdam-Antwerp chemical corridor freight differential compresses margins for cosmetic-grade imports while amplifying pricing power for Baden-Württemberg membrane purification specialists serving pharmaceutical-grade demand. This logistics wedge separates supply concentration in European phenol derivative clusters from price-sensitive procurement in Indian beauty clinic networks.
Pricing Analysis
Aftermarket technical service revenue from photographic chemical recycling and polymerization inhibitor blending drives lifetime value beyond commodity hydroquinone sales. Three-tier pricing structure across USP-grade pharmaceutical, technical-grade industrial, and cosmetic-grade material reflects purification burden and regulatory compliance intensity. Pricing pressure stems from arbutin substitution in Western retail channels, compressing cosmetic-grade margin pools. Indian beauty clinics exhibit highest price sensitivity, while German hospital formularies absorb USP-grade premiums without volume contraction.
Supply Chain Analysis
Extended payment terms from Japanese resin manufacturers and supply-chain finance facilities anchored in Singapore trading houses sustain working capital for phenol derivative converters. Production concentrates in Germany, Japan, and India, with feedstock drawn from crude benzene refining clusters and captive hydrogen peroxide operations. Single-source vulnerability runs through p-diisopropylbenzene oxidation technology licensors. Distribution runs through pharmaceutical-grade contract manufacturers for institutional buyers and direct API supply for compounding clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated sterile processing capabilities represent the critical asset gap separating qualified pharmaceutical-grade suppliers from delisted cosmetic-grade operators. This scarcity architecture concentrates procurement authority among 503B-registered facilities and MDR certificate holders.
For Market Incumbents: Entrench membrane purification cost advantages through licensing nanofiltration cascades to mid-scale challengers, converting process leadership into royalty streams. Expand Baden-Württemberg contract manufacturing clusters to capture EU hospital formulary consolidation. CDSCO registration arbitrage from Indian API specialists threatens European margin capture—accelerate sterile processing validation cycles to maintain procurement tier access. For New Entrants and Emerging Players: Establish a beachhead in Indian beauty clinic compounding networks by exploiting PLI-subsidized purification capacity and streamlined CDSCO pathways. Target gel format production for South Korean aesthetic medicine practices, where combination therapy protocols favor controlled-release delivery. Lead with photographic chemical recycling loops to secure closed-loop supply arrangements with commercial film processors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded cosmetic-grade capacity facing REACH reformulation costs. Long-term viability hinges on pharmaceutical-grade conversion economics and regulatory pathway speed. Watch EMA-ECHA coordination on dermatological device classification as the inflection signal for compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol Feedstock | Solvay's integrated derivative platform sustains cost leadership against hydrogen peroxide-based challengers. |
| Membrane Purification Technology Licensing | German nanofiltration specialists collapse USP-grade production costs for mid-scale pharmaceutical entrants. |
| Photographic Chemical Recycling Infrastructure | Spent developer recovery loops in Germany enable closed-loop supply security for film processors. |
| CDSCO Registration Pathway Exploitation | Indian PLI subsidies accelerate domestic API scale-up for export-oriented dermatological actives. |
| MDR Certificate Consolidation | French and Italian hospital systems restrict supplier lists to pre-qualified dermatological device manufacturers. |
Study Parameters
Desk research of customs trade flows, ECHA REACH registration databases, and CDSCO approval records preceded structured interviews with plant managers at phenol derivative facilities, procurement leads at Japanese resin manufacturers, distribution channel partners in pharmaceutical-grade supply, and technical R&D directors at membrane purification specialists. Primary fieldwork across German chemical clusters, Indian API manufacturing zones, and Japanese industrial chemical operations combined with secondary validation from SEC 10-K filings and Cefic industry reports. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Assumptions held fixed include REACH skin sensitizer classification persistence and FDA OTC concentration ceilings, while crude benzene price volatility and CDSCO registration timeline acceleration were modeled as scenario variables. Segmentation dimensions spanned grade tier, end-use industry, delivery format, and regional production hub. CAGRs derived from weighted average of historical volume trajectories and capacity expansion announcements. Forecast inputs incorporated photographic-grade polymerization inhibitor demand from high-performance resin manufacturers and hospital pharmacy centralization trends in US and Spanish health systems.
Sensitivities concentrate around EMA-ECHA coordination delays, PLI scheme renewal in India, and substitution acceleration from arbutin and kojic acid formulations. Forecasts reflect documented assumptions on regulatory stability and feedstock cost transmission. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High Purity Silica Market
High-Value Chemicals
Ultra-High Purity Hydrofluoric Acid Market
High-Value Chemicals
High Purity Aluminum Hydroxide Market
High-Value Chemicals
Hydroxynitrile Lyase Market
High-Value Chemicals
High-Purity Acetic Acid Market
High-Value Chemicals
Global High Temperature Thermoplastics (Htts) Market
High-Value Chemicals
High Temperature Plastic Market
High-Value Chemicals
High-Silica Zeolite Market
High-Value Chemicals
Global Hydrofluoric Acid Market
High-Value Chemicals
Hydroxylamine Sulfate Market
High-Value Chemicals
Diethylhydroxylamine (DEHA) Market
High-Value Chemicals
High Purity Lignin Market
High-Value Chemicals
High Purity Benzenethiol Market
High-Value Chemicals
Ammonium Metavanadate Market
High-Value Chemicals
Hydroxocobalamin Chloride Market
High-Value Chemicals
High-Temperature Epoxy Market