
 Hydroxocobalamin Chloride Market | 2026-2036
Hydroxocobalamin Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroxocobalamin Chloride Market Insights
Aftermarket service revenue from compounding and specialty pharmacy support is narrowing as API suppliers consolidate direct-to-formulator relationships. EUROAPI leverages its European manufacturing footprint to sustain high-purity batch consistency for injectable grades. CSPC Pharmaceutical Group anchors volume production through backward integration into fermentation-based cobalamin synthesis. Supriya Lifescience competes on cost-engineered oral supplement APIs serving Indian domestic and export markets.
Hydroxocobalamin chloride is a cobalt-corrin complex with the molecular formula C62H89CoN13O15P·Cl, synthesized via microbial fermentation followed by chromatographic purification and crystallization as the hydrochloride salt; it functions therapeutically as a vitamin B12 analog for parenteral and oral replacement therapy, with particular utility in patients with malabsorption syndromes or inherited cobalamin metabolic defects. The injection segment dominates hospital procurement due to guaranteed bioavailability in critical care settings, while oral supplements capture retail pharmacy volume through direct-to-consumer channels. Detoxification applications, notably cyanide poisoning antidote use under FDA-approved protocols, command premium pricing and specialized distribution through emergency medical services.
FDA oversees injectable sterility and stability requirements under current Good Manufacturing Practice frameworks, while EMA's REACH and MDR classifications shape European market access for medical-grade cobalamin salts. India's CDSCO mandates BIS-aligned purity testing for imported APIs, creating compliance differentiation among regional suppliers. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and IP standards to anticipate specification-driven procurement shifts.
Market Dynamics
Injectable sterility requirements under FDA current Good Manufacturing Practice frameworks are forcing API manufacturers to consolidate fermentation capacity and chromatographic purification investments, compressing the supplier base for medical-grade cobalamin salts.
Growth Catalysts
- Cyanide poisoning antidote protocols:Emergency medical services in the United States maintain stockpiles under FDA-approved detoxification guidelines, creating institutional procurement pull-through for high-purity injectable grades.
- EMA MDR classification alignment:European medical device regulation harmonization is streamlining market access for parenteral vitamin B12 replacement therapies across hospital networks.
- Malabsorption syndrome prevalence:Chronic disease management programs in Germany are expanding reimbursement coverage for parenteral cobalamin administration in pernicious anemia patients.
Market Restraints
- Fermentation feedstock volatility:Cobalt salt and corn-derived carbohydrate input costs fluctuate with commodity markets, squeezing batch economics for microbial synthesis operations.
- Supplier concentration in India:CDSCO-registered API production clusters around Maharashtra and Gujarat create geographic single-point vulnerability for international formulators.
- Oral supplement substitution:Methylcobalamin and adenosylcobalamin analogs capture retail pharmacy shelf space in direct-to-consumer channels, limiting hydroxocobalamin chloride expansion in non-prescription segments.
Strategic Opportunities
- Compounding pharmacy channel development:Specialty pharmacy direct relationships bypass traditional distributor markups for customized parenteral formulations in the United States.
- Indian domestic market penetration:Ayushman Bharat universal health coverage expansion is institutionalizing vitamin B12 deficiency screening in primary care settings.
- REACH-MDR regulatory convergence:EU chemical and medical device framework alignment creates certification efficiency for suppliers qualifying European manufacturing footprints.
Industry Challenges
- Chromatographic purification skill scarcity:High-resolution separation expertise for corrin complex isolation concentrates among legacy fermentation specialists, constraining capacity expansion.
- Pharmacopeial harmonization delays:Specification misalignment between USP, EP, and IP purity benchmarks forces redundant testing protocols for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroxocobalamin Chloride Market |
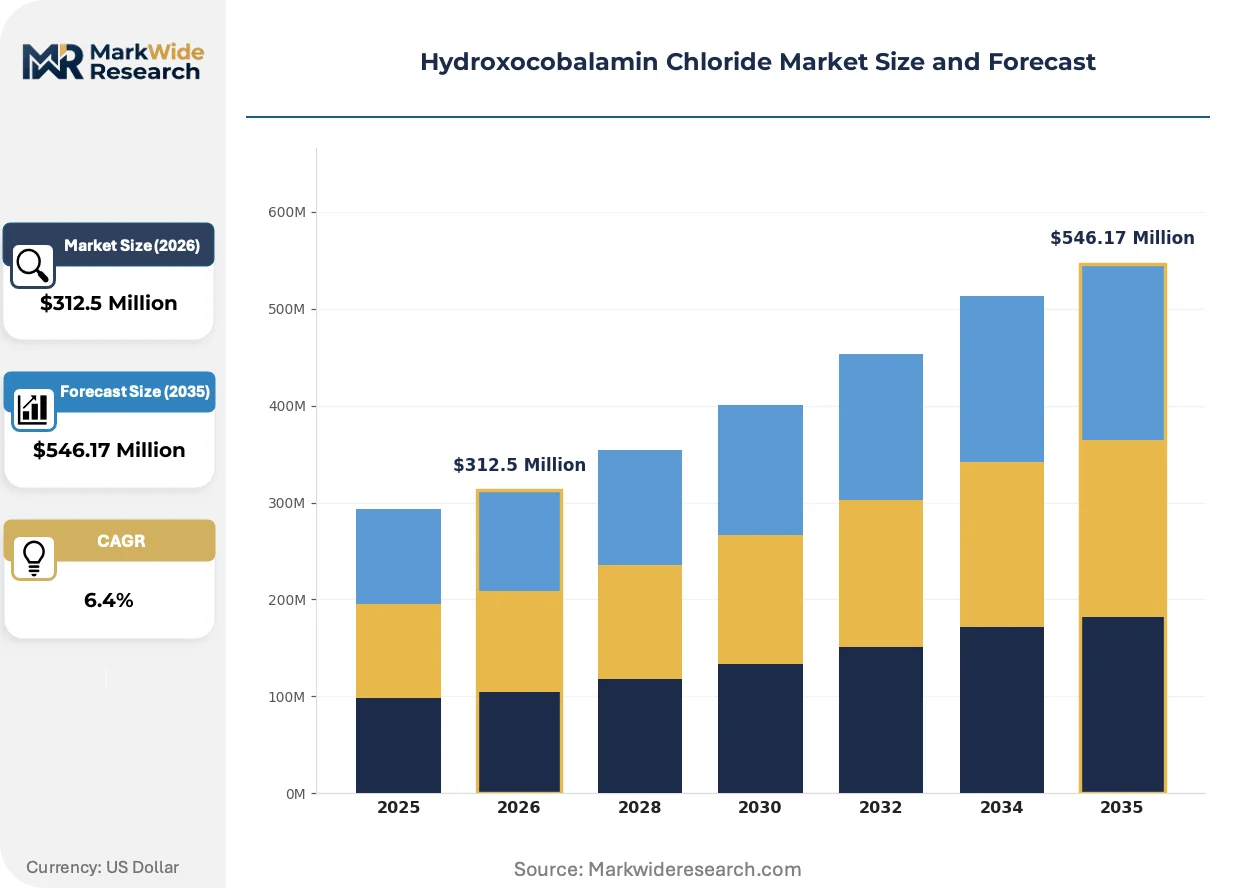
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Oral Supplement, Intranasal, Topical Application: Vitamin Deficiency, Anemia Treatment, Neurological Disorders, Detoxification End User: Hospitals, Clinics, Pharmacies, Home Care Distribution Channel: Retail, Online, Direct Sales, Wholesalers |
| Companies Covered | EUROAPI, CSPC Pharmaceutical Group, Supriya Lifescience, HealthTech BioActives, Apicore, Vital Laboratories Private Limited, Interquim Mexico, Micro Orgo Chem, North China Pharmaceutical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroxocobalamin Chloride Market Trends and Innovations
Continuous manufacturing technologies and real-time release testing are compressing batch cycle times while regulatory data integrity requirements reshape quality assurance investment priorities across the supply base.
Single-use bioreactor systems for microbial cobalamin fermentation are collapsing capital intensity barriers for mid-scale API producers. Contract manufacturers serving European hospital networks are adopting disposable stirred-tank configurations to reduce cross-contamination risk between vitamin B12 and other corrinoid campaigns. This technology shift is collapsing the minimum efficient scale for cGMP-compliant hydroxocobalamin chloride production, enabling geographic dispersal of manufacturing capacity.
EMA's updated Annex 1 sterile manufacturing guidelines are mandating barrier isolation technology and continuous environmental monitoring for parenteral API facilities. European formulators are retrofitting filling lines with restricted access barrier systems to maintain injectable product compliance. Hospital procurement departments in Germany and France are now requiring Annex 1 alignment documentation as a qualification prerequisite for supplier onboarding.
Direct contracting between API manufacturers and hospital group purchasing organizations is disintermediating traditional pharmaceutical wholesale channels. Specialty pharmacy networks in the United States are negotiating long-term supply agreements for cyanide antidote stockpiles that bypass regional distributor inventories. This channel restructuring concentrates volume commitments with vertically integrated suppliers possessing dedicated emergency medical service distribution capabilities.
Hydroxocobalamin Chloride Market Segmentation
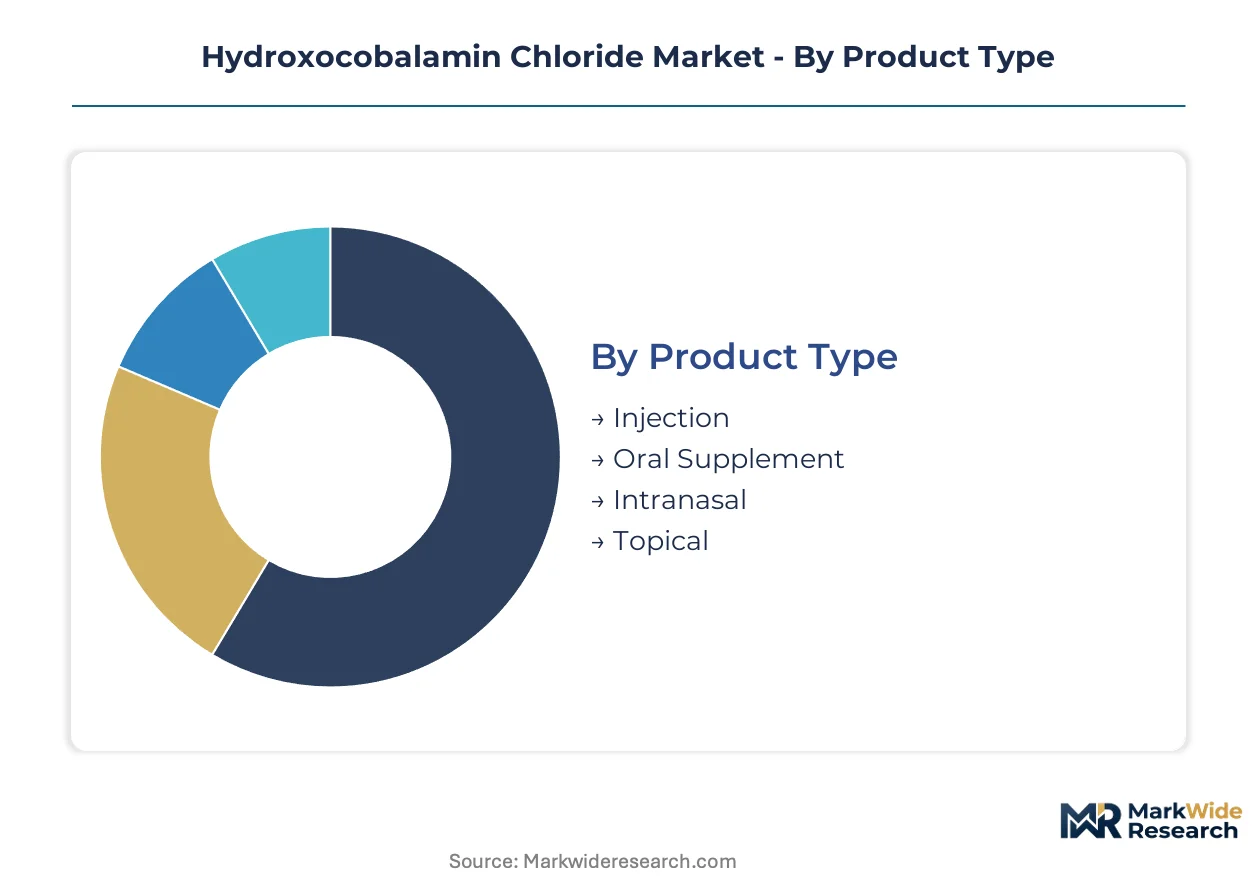
Hydroxocobalamin chloride demand fragments across administration routes, therapeutic indications, and procurement channels. Each segment carries distinct regulatory burdens, pricing power, and service intensity requirements that reshape supplier economics.
Product Type:
After-sales service intensity varies sharply by formulation complexity, with parenteral grades demanding batch-specific stability monitoring and recall management protocols that oral formats rarely require.
- Injection:Sterile aqueous solutions for intramuscular or intravenous delivery require endotoxin testing and pyrogen validation under FDA cGMP. Hospital networks in the United States concentrate procurement for pernicious anemia and emergency cyanide antidote protocols, with guaranteed bioavailability commanding premium positioning against alternative routes.
- Oral Supplement:Compressed tablets and capsules serve retail pharmacy and direct-to-consumer channels with lower regulatory thresholds. Indian domestic markets absorb substantial volume through Ayushman Bharat primary care screening programs, though bioavailability concerns limit penetration in malabsorption cases.
- Intranasal:Nasal spray formulations bypass gastrointestinal degradation for patients with compromised absorption. European hospital networks pilot limited adoption for pernicious anemia maintenance therapy.
- Topical:Transdermal gels and creams occupy niche cosmetic and wellness positioning with minimal therapeutic claim validation. Regulatory ambiguity constrains channel expansion.
Injection holds the largest share; momentum sits with oral supplements as screening programs expand in emerging markets.
Application:
Cost tier stratification separates acute intervention protocols from chronic maintenance regimens, with detoxification applications commanding 10-15x price multiples over nutritional supplementation.
- Vitamin Deficiency:Population-wide B12 insufficiency correction drives volume across oral and parenteral formats. German reimbursement frameworks institutionalize parenteral administration for documented malabsorption.
- Anemia Treatment:Pernicious anemia and megaloblastic anemia indications require sustained cobalamin replacement. Hospital-based hematology clinics anchor demand for high-purity injectable grades with documented erythropoietic response.
- Neurological Disorders:Peripheral neuropathy and subacute combined degeneration of the spinal cord represent high-value therapeutic targets. Neurology specialists in France and Switzerland prescribe parenteral loading doses followed by maintenance protocols.
- Detoxification:FDA-approved cyanide poisoning antidote use under the Cyanokit protocol creates institutional stockpiling mandates. Emergency medical services in the United States maintain rotating inventories with specialized cold-chain distribution requirements.
Anemia treatment anchors volume commitment; detoxification delivers steepest margin expansion despite limited patient incidence.
End User:
Customer type determines procurement sophistication, with hospital pharmacy and therapeutics committees imposing qualification barriers that home care channels rarely replicate.
- Hospitals:Inpatient and emergency departments administer parenteral formulations under pharmacy oversight. Group purchasing organizations in the United States consolidate volume commitments with suppliers demonstrating Annex 1 sterile manufacturing alignment.
- Clinics:Outpatient infusion centers and specialty practices manage chronic replacement therapy. German ambulatory care networks coordinate with hospital pharmacies for parenteral supply continuity.
- Pharmacies:Community and specialty dispensaries handle oral supplement retail and limited compounding. Indian retail chains expand B12 screening and supplementation counseling services.
- Home Care:Self-administered oral regimens and visiting nurse injection services support patient mobility. Reimbursement fragmentation constrains parenteral home delivery outside established markets.
Hospitals dominate value capture; home care channels are expanding most quickly as patient preference shifts toward convenience.
Distribution Channel:
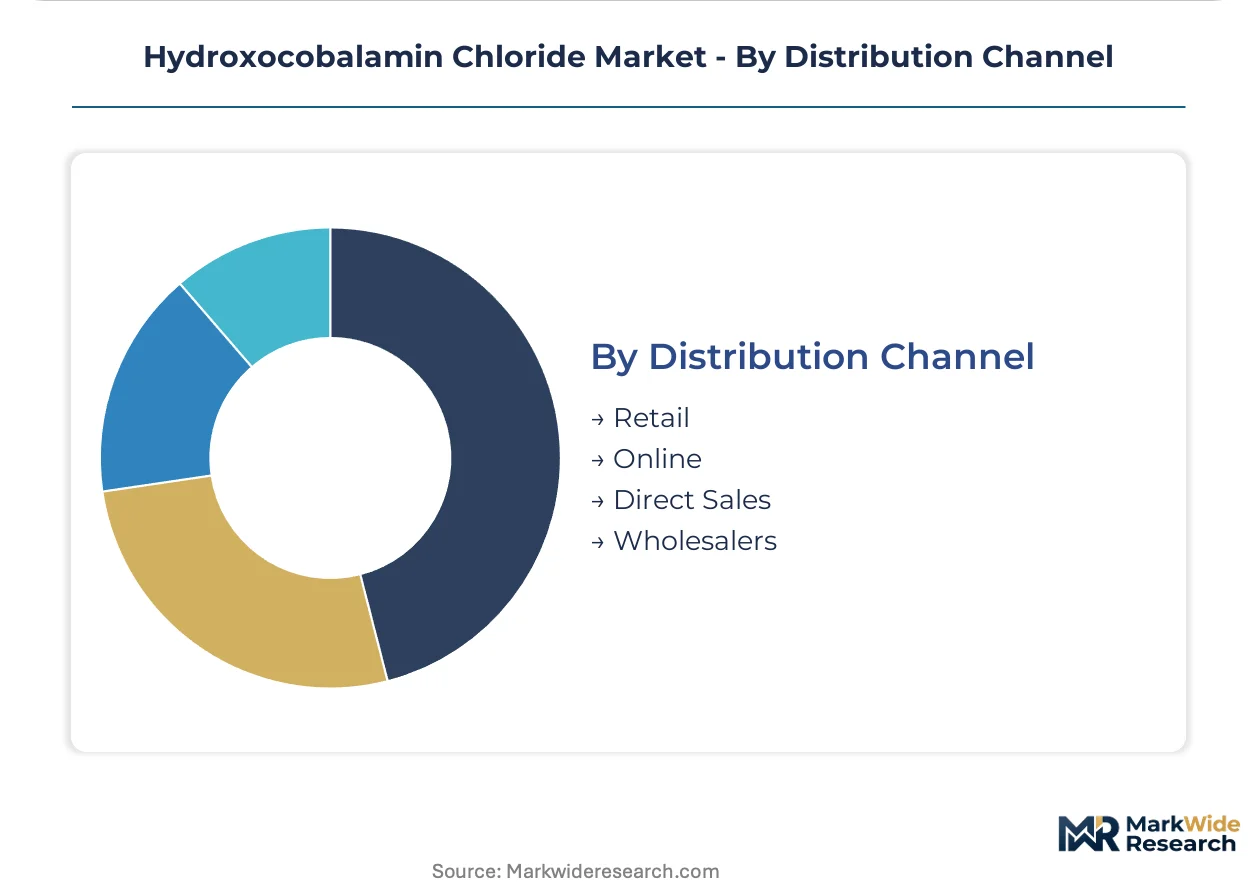
Supply concentration shapes channel economics, with direct manufacturer-to-institution contracting displacing traditional wholesale intermediaries in high-value segments.
- Retail:Brick-and-mortar pharmacies and health food stores move oral supplement volume through consumer self-selection. Shelf space competition from methylcobalamin alternatives pressures hydroxocobalamin chloride positioning.
- Online:E-commerce platforms and telehealth-integrated pharmacies capture direct-to-consumer growth. Regulatory enforcement of prescription requirements varies across jurisdictions.
- Direct Sales:API manufacturers and formulators contract directly with hospital group purchasing organizations and emergency medical service agencies. Cyanide antidote stockpiles bypass distributor inventories through long-term supply agreements.
- Wholesalers:Traditional pharmaceutical distributors serve fragmented clinic and pharmacy demand. Margin compression from direct contracting limits growth investment.
Direct sales command premium positioning; online channels gain share fastest as telehealth prescribing normalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with the United States prioritizing emergency antidote stockpiles while Germany and India concentrate on chronic disease management protocols.
United States
Emergency medical services maintain rotating cyanide antidote inventories under FDA-approved Cyanokit protocols. Hospital group purchasing organizations consolidate volume commitments with suppliers demonstrating sterile manufacturing alignment. Manufacturing and distribution clusters concentrate in the Northeast Corridor and California for cold-chain logistics efficiency.
Germany
Pernicious anemia management programs drive parenteral formulation demand through statutory health insurance reimbursement. EMA Annex 1 sterile manufacturing guidelines mandate barrier isolation technology for API facilities serving hospital networks. The Rhine-Ruhr and Bavarian pharmaceutical corridors host formulation specialists retrofitting filling lines with restricted access barrier systems.
India
Ayushman Bharat universal health coverage expansion institutionalizes vitamin B12 deficiency screening in primary care settings. CDSCO mandates BIS-aligned purity testing for imported APIs, creating compliance differentiation among domestic suppliers. API production clusters around Maharashtra and Gujarat supply international formulators with fermentation-derived cobalamin salts.
China
Hospital pharmacy procurement of injectable grades expands alongside chronic disease management program scale-up. NMPA oversight of sterile manufacturing practice frameworks shapes domestic production qualification requirements. The Yangtze River Delta anchors fermentation capacity investments for medical-grade cobalamin synthesis.
Switzerland
Neurology specialists prescribe parenteral loading doses for peripheral neuropathy and subacute combined degeneration indications. Swissmedic pharmacovigilance requirements enforce batch-specific stability documentation for hospital procurement. The Basel pharmaceutical corridor concentrates high-purity chromatographic purification expertise for corrin complex isolation.
Hydroxocobalamin Chloride Market Competitive Landscape
Capability concentration sits with European fermentation specialists possessing chromatographic purification expertise; scale advantage sits with Asian manufacturers leveraging backward integration into cobalamin synthesis. The supplier base compresses around three strategic archetypes: legacy European API houses with Annex 1 alignment, Indian cost-engineered volume producers, and Chinese integrated fermentation operators. Dominant competitive moves include direct-to-formulator contracting that disintermediates wholesale channels and single-use bioreactor adoption that collapses minimum efficient scale barriers.
Within the European high-purity tier, EUROAPI leverages its manufacturing footprint to sustain batch consistency for injectable grades. CSPC Pharmaceutical Group and North China Pharmaceutical Group anchor the scale-driven segment through integrated fermentation capacity. Supriya Lifescience occupies a position in cost-engineered oral supplement APIs serving domestic and export markets.
| Leading Market Players |
|---|
| EUROAPI |
| CSPC Pharmaceutical Group |
| Supriya Lifescience |
| HealthTech BioActives |
| Apicore |
| Vital Laboratories Private Limited |
| Interquim Mexico |
| Micro Orgo Chem |
| North China Pharmaceutical Group |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Antwerp pharmaceutical corridor anchors cold-chain logistics costs for hydroxocobalamin chloride distribution, with temperature-controlled freight rates directly shaping margin allocation between Indian API exporters and European formulators seeking Annex 1-aligned sterile grades.
Pricing Analysis
Long-term offtake agreements dominate hospital procurement, with multi-year supply contracts for cyanide antidote stockpiles commanding premium positioning against spot-market oral supplement transactions. Price differentiation rests on FDA cGMP certification tier and volume scale, with detoxification-grade injectables capturing substantial premiums over nutritional formulations. Cost compression in oral supplement tiers intensifies as methylcobalamin alternatives capture retail pharmacy shelf space. Emergency medical services demonstrate lowest price sensitivity due to regulatory stockpiling mandates, while Indian domestic retail channels absorb substantial volume at economy positioning.
Supply Chain Analysis
Export-control regimes on fermentation technology and chromatographic purification equipment constrain capacity expansion outside established manufacturing clusters. Supply concentrates in India, China, and Switzerland, with Maharashtra and Gujarat API production feeding international formulators and Basel-area specialists anchoring high-purity corrin complex isolation. Raw material dependencies center on cobalt salts, corn-derived carbohydrates, and specialized chromatography resins. Single-source vulnerability concentrates in legacy fermentation specialists possessing rare high-resolution separation expertise. Distribution runs through direct manufacturer-to-hospital contracting for injectable grades, bypassing wholesale intermediaries in high-value segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as direct-to-formulator contracting disintermediates traditional distribution, creating niche positioning for mid-scale producers with single-use bioreactor capabilities and regional regulatory alignment.
For Market Incumbents: Build regulatory certification moats through EMA Annex 1 barrier isolation investments and FDA cGMP sterile manufacturing alignment. Consolidate chromatographic purification expertise through targeted capability acquisition in Switzerland and Germany. Defend against methylcobalamin substitution threats by anchoring hospital formulary relationships for malabsorption indications. Capacity expansion in the Yangtze River Delta secures cost-competitive fermentation feedstock access. For New Entrants and Emerging Players: Compounding pharmacy networks in the United States represent the most penetrable entry point for customized parenteral formulations bypassing distributor markups. Indian Ayushman Bharat primary care screening expansion creates white-space demand for cost-engineered oral supplement APIs serving domestic volume. European hospital network Annex 1 qualification documentation requirements favor partnership-based go-to-market approaches with established sterile manufacturing specialists. For Investors and Strategic Acquirers: Carve-out targets emerge from large pharmaceutical conglomerates divesting non-core vitamin API portfolios. Long-term viability centers on backward-integrated fermentation operators with captive cobalt salt supply and chromatographic purification capabilities. Watch for FDA-EMA pharmacopeial harmonization progress as inflection indicator for specification-driven procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Annex 1 Sterile Manufacturing Alignment | EMA barrier isolation mandates reshape European hospital supplier qualification requirements. |
| Single-Use Bioreactor Adoption | Disposable stirred-tank configurations collapse minimum efficient scale for cGMP cobalamin production. |
| Direct Hospital Contracting | Manufacturer-to-GPO agreements disintermediate wholesale channels for cyanide antidote stockpiles. |
| Chromatographic Purification Capability Acquisition | High-resolution corrin complex isolation expertise concentrates among legacy fermentation specialists. |
| Indian Domestic Market Penetration | Ayushman Bharat screening expansion institutionalizes B12 deficiency detection in primary care. |
Research Methodology
Desk research of FDA cGMP guidance documents, EMA Annex 1 sterile manufacturing guidelines, and pharmacopeial standards preceded structured interviews with API manufacturing executives, hospital pharmacy directors, emergency medical service procurement leads, and regulatory affairs specialists. Secondary validation drew from CDSCO import regulations, BIS purity testing protocols, and fermentation industry trade data. Bottom-up volume modeling triangulated against top-down market sizing across administration routes and therapeutic indications.
Assumptions held fixed include current FDA-EMA regulatory alignment timelines and cobalt salt commodity price bands, while variables included single-use bioreactor adoption rates and direct contracting penetration. The analytical framework segmented by product type, application, end user, and distribution channel across the analysis window. CAGRs derived from weighted average of historical volume trends and demand elasticity estimates for hospital procurement versus retail pharmacy channels. Forecast inputs incorporated malabsorption syndrome prevalence trajectories and cyanide antidote protocol maintenance requirements.
Practitioners should monitor pharmacopeial harmonization progress between USP, EP, and IP standards for early signals of specification-driven procurement shifts. Forecasts reflect assumptions regarding sterile manufacturing compliance stability and fermentation feedstock cost bands. Material shifts in EMA MDR classification enforcement or cobalt salt export restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High-Silica Zeolite Market
High-Value Chemicals
Mono Methyl Ether of Hydroquinone (MEHQ) Market
High-Value Chemicals
Potassium Hydroxide Market
High-Value Chemicals
Global High Dispersible Silica Market
High-Value Chemicals
Diethylhydroxylamine (DEHA) Market
High-Value Chemicals
Battery Grade High Purity Lithium Fluoride Market
High-Value Chemicals
Hydroquinone Market
High-Value Chemicals
Global Hydrofluoric Acid Market
High-Value Chemicals
Global High Potency Apis /HPAPI Market
High-Value Chemicals
Hydrogen Isotope Market
High-Value Chemicals
High-Purity Boehmite Market
High-Value Chemicals
High Purity Magnesium Citrate Market
High-Value Chemicals
Global High Heat Foam Market
High-Value Chemicals
High-Purity Nitrogen Market
High-Value Chemicals
Global Epichlorohydrin (ECH) Market
High-Value Chemicals
Ultra-High Purity Materials Market